
 Asia-Pacific Professional Audio-Visual Systems Market | 2026-2036
Asia-Pacific Professional Audio-Visual Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Professional Audio-Visual Systems Market Outlook
Premium large-format LED walls and commodity LCD signage is decoupling across procurement channels in the Asia-Pacific Professional Audio-Visual Systems Market. Sony Corporation leverages its cinema-grade color calibration technology to dominate broadcast and post-production niches. Samsung Electronics anchors its position through captive semiconductor supply and in-house panel production. Panasonic Corporation competes on integrated system architectures that bundle projection, audio, and control software for enterprise clients.
Professional audio-visual systems encompass engineered assemblies of display, amplification, signal processing, and control hardware designed for commercial installations requiring sustained operation at luminance levels exceeding consumer-grade thresholds. These systems integrate 4K-to-8K resolution panels, Dante or AES67 networked audio protocols, and centralized AV-over-IP management platforms to enable real-time content distribution across multi-zone venues. Display systems lead in revenue contribution due to perpetual refresh cycles in retail and command-center environments, while video conferencing solutions represent the fastest-expanding category as enterprises standardize on hybrid collaboration infrastructure. LED technology captures margin concentration in high-brightness outdoor and fine-pitch indoor applications, whereas projection mapping carves a specialized niche in immersive entertainment and museum installations across the region.
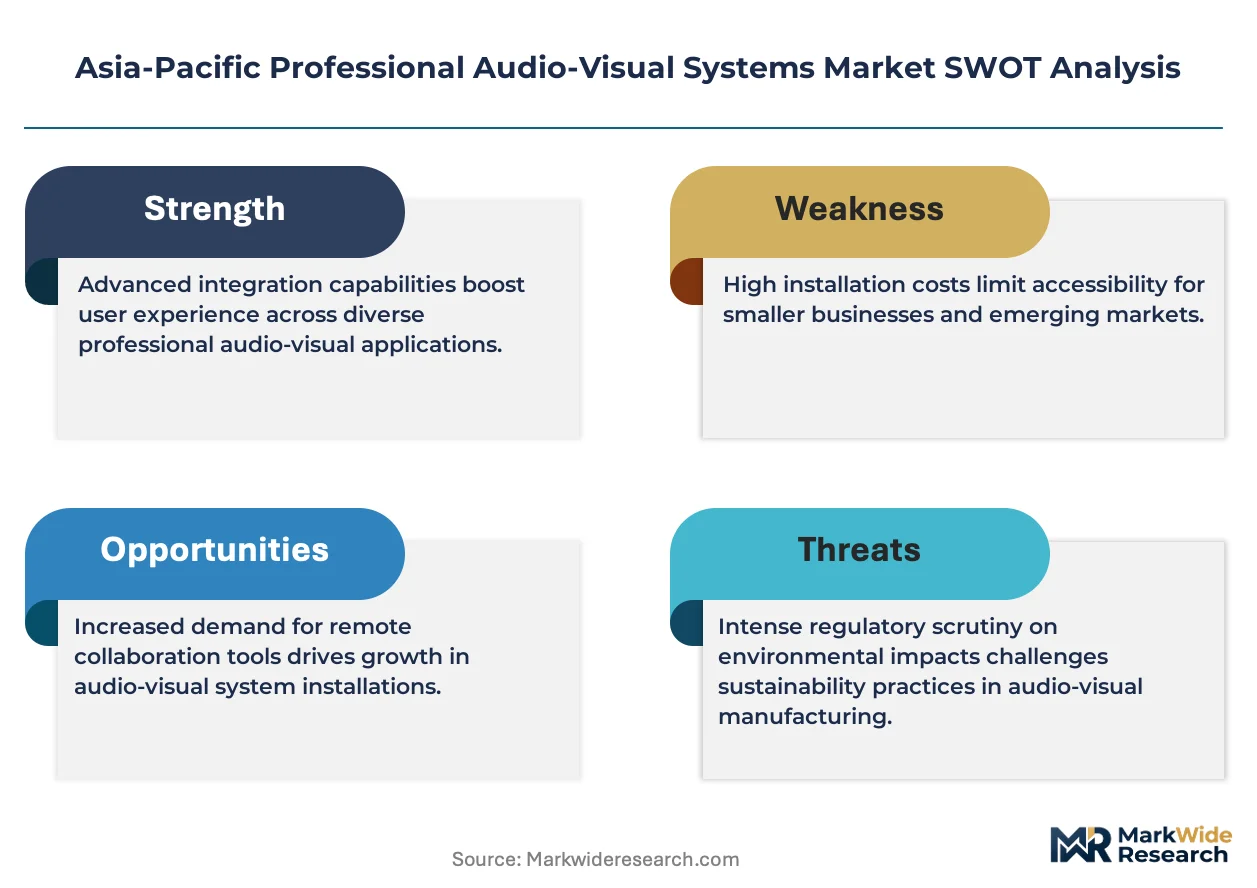
MIIT enforces GB energy efficiency standards that disqualify non-compliant display imports from Chinese public tenders, directly filtering supplier eligibility. BIS certification requirements in India mandate electromagnetic compatibility testing for audio amplification and switching equipment deployed in government auditoriums and educational institutions. TRAI's broadband infrastructure directives indirectly shape AV system specifications by mandating minimum bandwidth thresholds that IP-based video distribution must accommodate. Stakeholders must monitor how divergent national certification timelines affect product launch synchronization across multi-country deployment contracts.
Market Dynamics
Hybrid work infrastructure mandates across Asia-Pacific enterprise campuses are compressing refresh cycles for unified communication suites and forcing rapid convergence of AV-over-IP with IT network architectures.
Growth Catalysts
- Smart classroom mandates:India's National Education Policy directives are mandating interactive display installations in government schools across tier-one commercial hubs, creating sustained procurement pipelines for large-format LED and spatial audio systems.
- GB energy efficiency standards:MIIT certification requirements in China are disqualifying non-compliant display imports from public tenders, directly filtering supplier eligibility and accelerating domestic manufacturing upgrades.
- Convention center expansions:Australia's convention infrastructure pipeline in Sydney and Melbourne is driving demand for fine-pitch indoor LED and immersive projection mapping systems in hybrid event venues.
Market Restraints
- Semiconductor supply concentration:Captive foundry capacity in South Korea and Taiwan creates dependency risks for display driver ICs and signal processing chipsets used in professional AV systems.
- BIS certification friction:India's electromagnetic compatibility testing mandates for audio amplification equipment create 4-6 month approval delays that desynchronize multi-country deployment timelines.
- LCD panel oversupply volatility:Commodity pricing swings in Gen 8.5 and Gen 10.5 glass substrate production compress margins for standard-format digital signage deployments.
Strategic Opportunities
- Immersive entertainment venues:Projection mapping systems are penetrating museum and experiential retail installations across Southeast Asian tourism corridors in Thailand and Vietnam.
- TRAI bandwidth thresholds:India's broadband infrastructure directives mandating minimum IP network specifications create regulatory tailwinds for AV-over-IP distribution platform vendors.
- Spatial audio convergence:Dante and AES67 protocol integration with building automation systems is opening white space in Japanese corporate headquarters and hospitality developments.
Industry Challenges
- Dante certification scarcity:Networked audio protocol expertise remains concentrated among specialized integration firms, creating talent bottlenecks for enterprise multi-zone deployments.
- Legacy control system fragmentation:Proprietary RS-232 and HDBaseT infrastructures in existing commercial buildings complicate centralized AV-over-IP migration pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Professional Audio-Visual Systems Market |
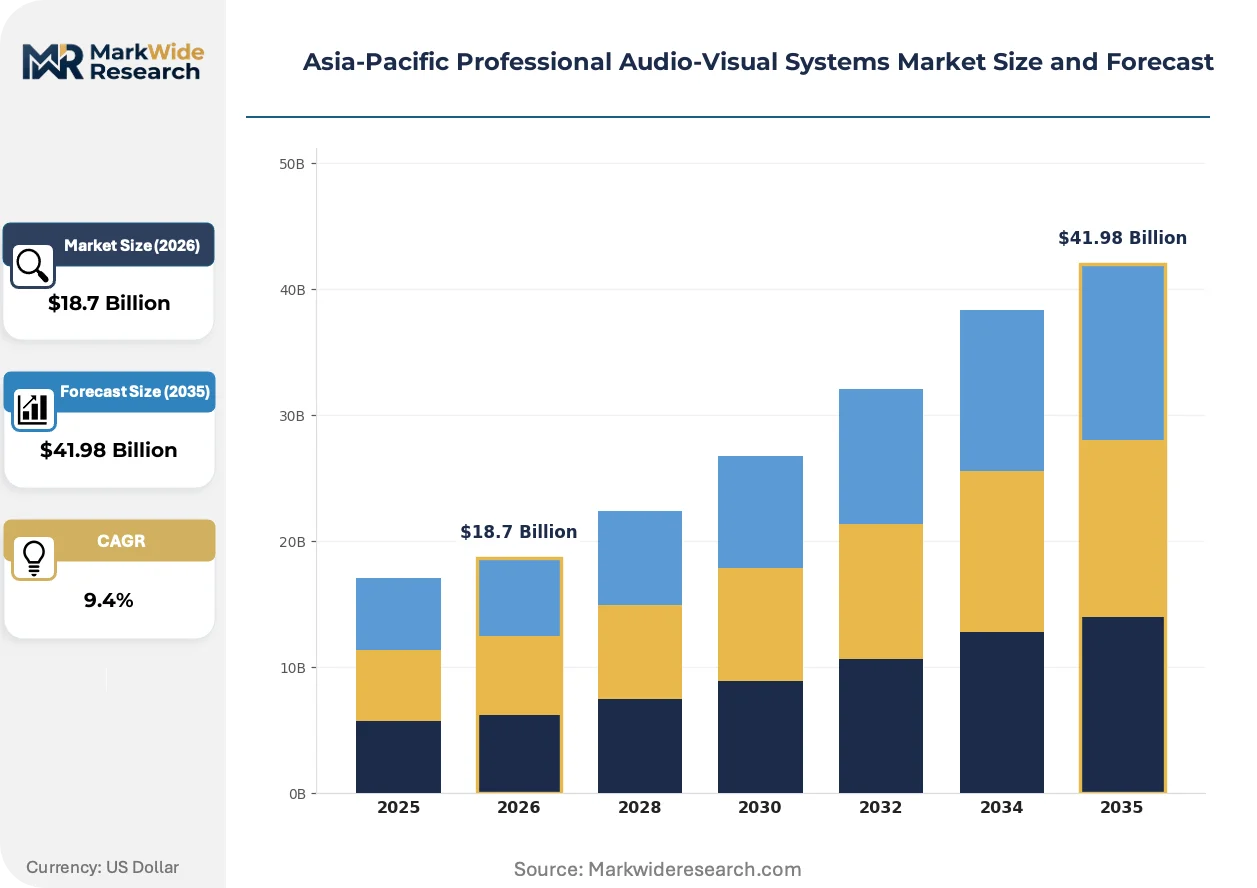
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Systems, Audio Equipment, Projectors, Video Conferencing Solutions Technology: LED, LCD, OLED, Projection Mapping End User: Corporate, Education, Entertainment, Government Installation: Fixed, Portable, Integrated, Custom Solutions |
| Companies Covered | LG Electronics, Alpine Electronics Inc., Sony Corporation, Planar Systems, Kramer Electronics, Panasonic Corporation, Epson, Guangzhou DSPPA Audio Co Ltd, Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Professional Audio-Visual Systems Market Strategic Shifts
AV-over-IP distribution architectures are displacing traditional matrix switching across Asia-Pacific commercial installations, compressing hardware footprints while expanding software-defined management capabilities.
MicroLED display technology is integrating proprietary mass-transfer processes with cinema-grade color calibration engines. Broadcast and post-production facilities in South Korea and Japan are adopting sub-0.9mm pixel pitch cabinets for critical monitoring applications. This convergence is integrating direct-view LED into reference-grade color workflows previously dominated by OLED mastering monitors.
MIIT enforcement of GB 21520 energy efficiency standards for electronic displays is tightening standby power and luminance efficacy thresholds. Non-compliant imports face automatic disqualification from Chinese government and state-owned enterprise tenders. Domestic suppliers with captive panel production are accelerating thermal management and driver circuit redesigns to maintain public sector access.
Enterprise buyers are consolidating vendor relationships around full-stack system integrators capable of unified communication, building management, and cybersecurity compliance. Single-source procurement contracts are displacing multi-vendor component sourcing in Australian financial services and Singaporean government campuses. This concentration is most visible in hybrid workspace deployments where IT-AV convergence demands single-point accountability for network security and uptime guarantees.
Asia-Pacific Professional Audio-Visual Systems Market Segmentation
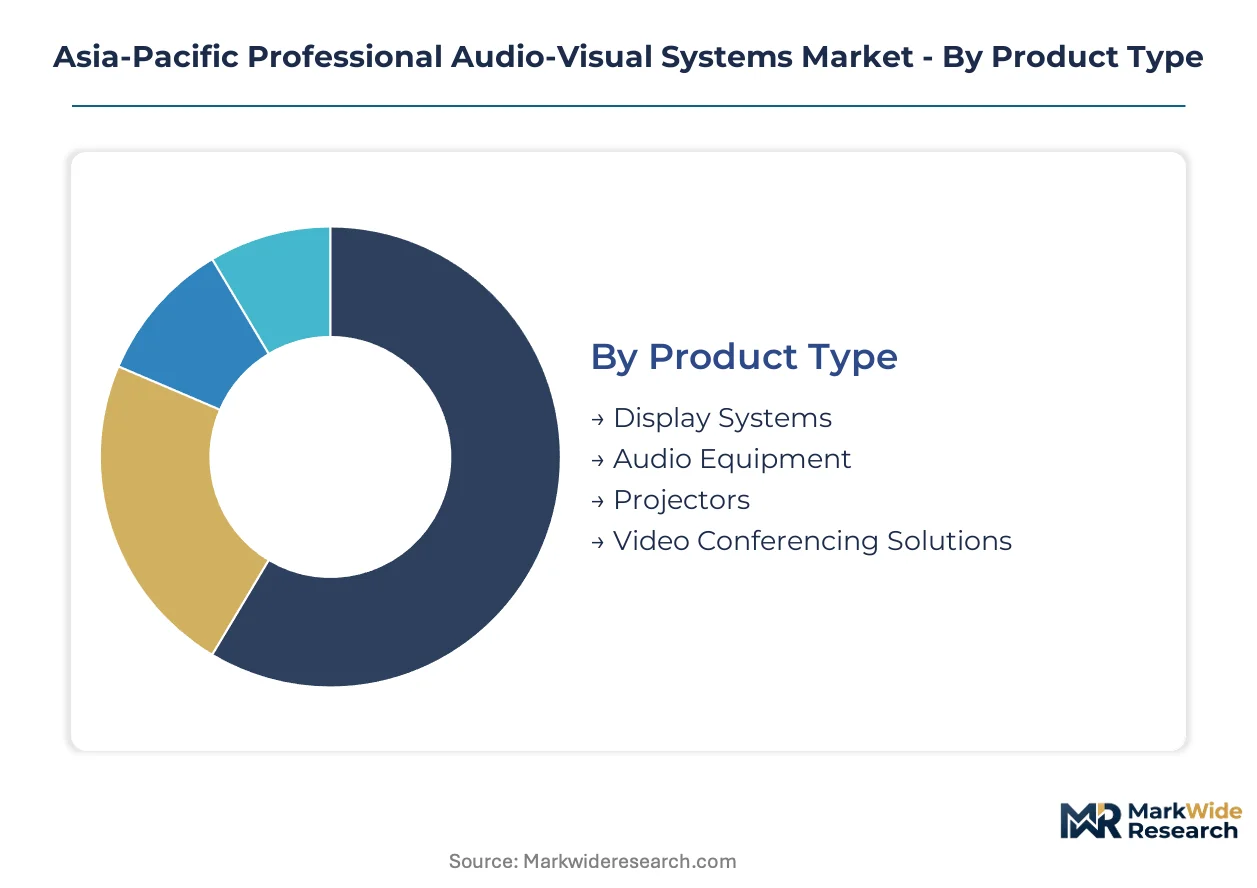
Segmentation in the Asia-Pacific Professional Audio-Visual Systems Market reveals how procurement priorities diverge across deployment contexts. Product specifications, technology choices, and installation complexity create distinct margin profiles that reshape competitive positioning.
Product Type:
Display systems anchor revenue contribution through perpetual refresh cycles, while video conferencing solutions command premium pricing as enterprises consolidate hybrid collaboration infrastructure.
- Display Systems:Engineered assemblies of 4K-to-8K resolution panels designed for sustained commercial operation at luminance levels exceeding consumer thresholds. Demand concentrates in India's tier-one retail hubs and Chinese command-center environments where perpetual refresh cycles drive procurement volume.
- Video Conferencing Solutions:Unified communication suites integrating cameras, microphones, and AV-over-IP distribution platforms for real-time multi-zone collaboration. Corporate boardrooms across Australia and Singapore are accelerating procurement as hybrid work mandates compress refresh cycles and force IT-AV convergence.
- Audio Equipment:Dante and AES67 networked amplification systems with spatial audio processing for multi-zone venue deployment.
- Projectors:High-brightness laser and lamp-based projection systems for large-venue and immersive entertainment applications.
Mature deployment sits with Display Systems. Newer deployment is concentrated in Video Conferencing Solutions.
Technology:
LED technology captures margin concentration through proprietary mass-transfer processes, while LCD commoditization creates pricing pressure in standard-format signage deployments.
- LED:Direct-view cabinets with sub-0.9mm pixel pitch integrating proprietary driver circuits and thermal management for fine-pitch indoor and high-brightness outdoor applications. South Korean broadcast facilities and Japanese post-production houses are adopting LED for reference-grade color workflows previously dominated by OLED mastering monitors.
- Projection Mapping:Edge-blended multi-projector systems with geometric correction and content synchronization for immersive entertainment and museum installations. Thailand and Vietnamese tourism corridors are driving demand as experiential retail and cultural venues expand across Southeast Asia.
- LCD:Commodity flat-panel displays leveraging Gen 8.5 and Gen 10.5 glass substrate production for cost-sensitive digital signage.
- OLED:Self-emissive panels with cinema-grade color calibration for premium broadcast monitoring and executive conferencing environments.
Volume production centers on LCD. Steepest expansion trajectory belongs to LED.
End User:
Corporate procurement dominates contract value through full-stack system integration demands, while education sector mandates create sustained pipeline visibility.
- Corporate:Enterprise campuses requiring unified communication suites with cybersecurity compliance and single-point accountability for network uptime. Australian financial services and Singaporean government campuses are consolidating vendor relationships around full-stack integrators capable of IT-AV convergence.
- Education:Government school and university deployments driven by India's National Education Policy smart classroom mandates. Tier-one commercial hubs are creating sustained procurement pipelines for interactive displays and spatial audio systems.
- Entertainment:Museum, theme park, and experiential retail venues requiring immersive projection and spatial audio for visitor engagement.
- Government:State-owned enterprise and public sector tenders subject to MIIT GB energy efficiency certification requirements in China.
Procurement standardization is most advanced in Corporate. Policy-driven expansion is concentrated in Education.
Installation:
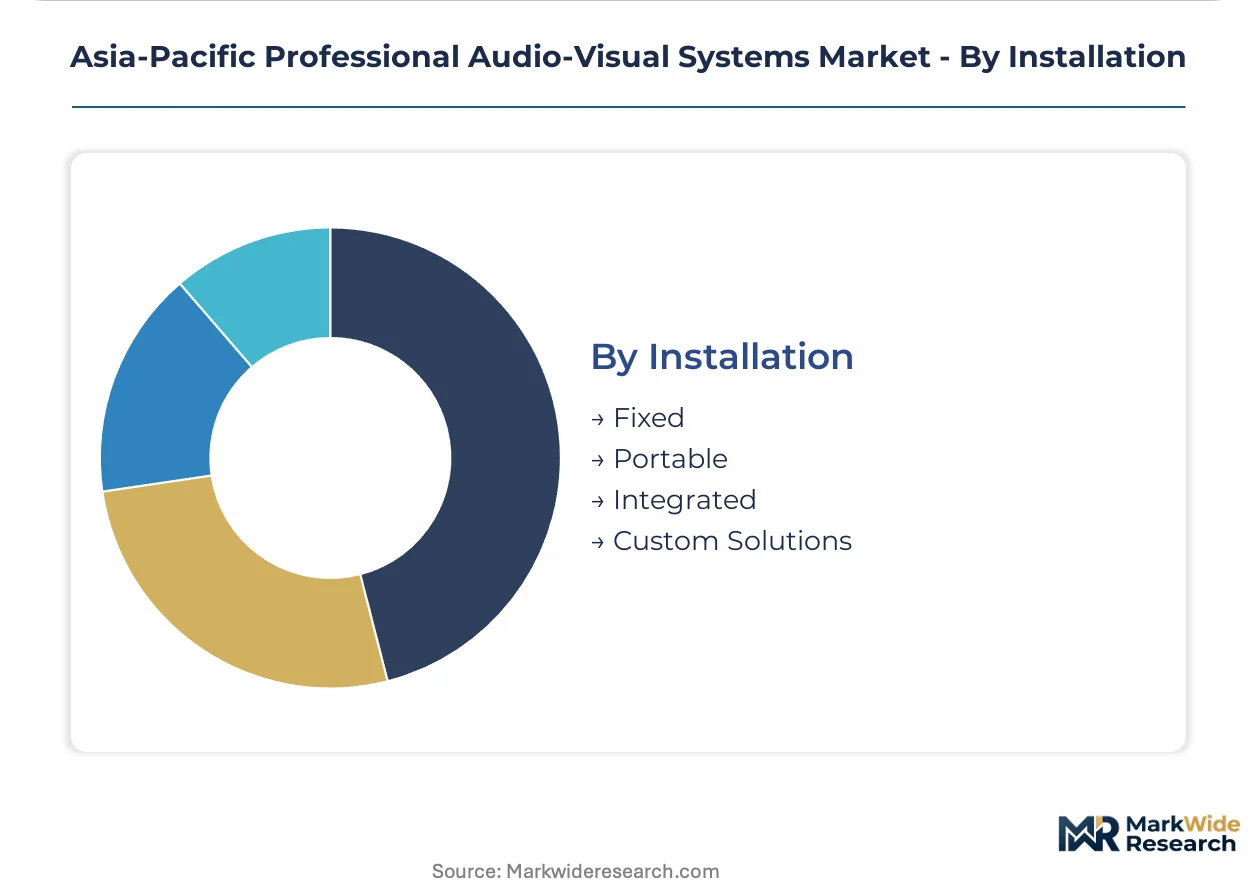
Fixed installations dominate capital expenditure, while integrated solutions command premium pricing through building automation convergence.
- Integrated:AV-over-IP architectures bundled with building management systems and centralized control software for enterprise multi-zone venues. Japanese corporate headquarters and hospitality developments are driving Dante protocol integration with HVAC and lighting automation.
- Fixed:Permanent mounted displays and audio systems in retail, command-center, and convention infrastructure. Sydney and Melbourne convention center expansions are driving fine-pitch indoor LED and immersive projection deployments.
- Portable:Mobile projection and sound reinforcement systems for temporary event and rental staging applications.
- Custom Solutions:Bespoke engineered systems for specialized museum, broadcast, and post-production facility requirements.
Revenue concentration rests with Fixed installations. Margin expansion is fastest in Integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the Asia-Pacific professional audio-visual systems landscape through its concentration of broadcast post-production facilities and command-center deployments. The Yangtze River Delta corridor generates sustained procurement for fine-pitch LED and reference-grade monitoring systems. Beijing and Shenzhen drive complementary demand through government tender pipelines and semiconductor supply integration.
China
MIIT enforcement of GB 21520 energy efficiency standards is disqualifying non-compliant display imports from state-owned enterprise tenders. Domestic suppliers with captive panel production are accelerating thermal management redesigns to maintain public sector access. Beijing-Tianjin-Hebei clusters concentrate command-center deployments driving perpetual refresh cycles for 4K-to-8K resolution panels.
India
National Education Policy smart classroom mandates are creating sustained procurement pipelines for interactive displays across tier-one commercial hubs. BIS electromagnetic compatibility testing requirements for audio amplification equipment generate 4-6 month approval delays. Mumbai and Delhi-NCR concentrate convention center expansions driving demand for spatial audio and large-format LED systems.
Japan
Broadcast and post-production facilities in Tokyo are adopting sub-0.9mm pixel pitch LED cabinets for reference-grade color workflows. METI industrial policy supports domestic manufacturing of high-brightness display components. Osaka-Kansai corridors concentrate corporate headquarters integrating Dante protocol audio with building automation systems.
South Korea
Captive foundry capacity for display driver ICs creates supply concentration risks for regional AV system manufacturers. Seoul Capital Area dominates broadcast facility upgrades integrating cinema-grade color calibration technology. Busan-Ulsan industrial zones anchor component supply chains for LED driver circuits and signal processing chipsets.
Australia
Sydney and Melbourne convention infrastructure expansions are driving procurement for immersive projection mapping and fine-pitch indoor LED systems. Enterprise campuses in Australian financial services sectors are consolidating vendor relationships around full-stack system integrators. TRAI-equivalent broadband specifications indirectly shape IP-based video distribution requirements for hybrid event venues.
Asia-Pacific Professional Audio-Visual Systems Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific professional audio-visual systems landscape. The market structure concentrates around vertically integrated electronics conglomerates with captive semiconductor supply and specialized audio-visual integrators with protocol expertise. Three archetypes dominate: diversified technology conglomerates with in-house panel production, specialized professional AV component manufacturers, and regional system integration firms with localized certification capabilities. Competitive moves center on strategic partnerships for AV-over-IP convergence and portfolio diversification into building automation integration.
Among diversified technology conglomerates, Sony Corporation and Samsung Electronics exemplify contrasting approaches to vertical integration. Sony Corporation represents the broadcast and post-production specialization archetype through its cinema-grade color calibration heritage. Samsung Electronics anchors the captive supply model with in-house semiconductor and panel production capabilities. Panasonic Corporation occupies a position emphasizing integrated system architectures that bundle multiple AV modalities for enterprise clients. Guangzhou DSPPA Audio Co Ltd exemplifies regional specialists competing through localized certification expertise and proximity to Chinese government tender pipelines.
| Leading Market Players |
|---|
| LG Electronics |
| Alpine Electronics Inc. |
| Sony Corporation |
| Planar Systems |
| Kramer Electronics |
| Panasonic Corporation |
| Epson |
| Guangzhou DSPPA Audio Co Ltd |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
India's National Education Policy smart classroom mandates are compressing procurement timelines for interactive displays and spatial audio systems, forcing suppliers to pre-qualify components against BIS electromagnetic compatibility standards and accelerating cost pass-through negotiations with tier-one commercial hub integrators.
Pricing Analysis
Value-based pricing anchored to system uptime guarantees and cybersecurity compliance certification dominates enterprise procurement in Australian financial services and Singaporean government campuses. Three-tier pricing structure across premium, standard, and economy levels separates MIIT GB 21520-certified displays from non-compliant imports and commodity LCD signage. Cost compression in standard-format digital signage is intensifying because Gen 8.5 and Gen 10.5 glass substrate oversupply swings compress margins. Government education buyers exhibit highest price sensitivity, while corporate hybrid workspace deployments prioritize single-source accountability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for display driver ICs and signal processing chipsets are mandating multi-supplier qualification across South Korean and Taiwanese foundries to mitigate single-source vulnerability. Raw material dependencies center on gallium nitride substrates for LED driver circuits, high-purity glass substrates for LCD panels, and rare earth phosphors for laser projection systems. Tariff exposure on semiconductor imports from Taiwan creates structural risk for regional AV system manufacturers. Distribution runs through authorized integration partners with localized certification expertise in China, India, and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's GB 21520 energy efficiency enforcement constructs a cost-of-compliance barrier that disqualifies non-certified imports from Chinese state-owned enterprise tenders, creating a durable moat for domestic suppliers with captive thermal management redesign capabilities.
For Market Incumbents: Anticipate accelerated consolidation around full-stack system integrators as enterprise buyers demand single-point accountability for IT-AV convergence and network security compliance. Defensive positioning requires deepening backward integration into LED driver circuit production and pre-emptive certification investment against tightening BIS electromagnetic compatibility timelines in India. For New Entrants and Emerging Players: Direct-to-integrator digital channels offer lowest-friction entry for Dante protocol expertise and AV-over-IP software platforms targeting Japanese corporate headquarters. White-space penetration concentrates on Southeast Asian museum and experiential retail projection mapping installations in Thailand and Vietnam, where localized content synchronization capabilities remain undersupplied. For Investors and Strategic Acquirers: The window for entry favors regional system integration firms with multi-country certification capabilities and established relationships with Chinese government tender pipelines. Long-term viability hinges on acquisition targets demonstrating captive supply chain relationships or proprietary mass-transfer processes for fine-pitch LED. Watch for MIIT certification timeline acceleration as inflection indicator for domestic supplier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AV-over-IP Platform Integration | Consolidates IT-AV convergence demand from Australian financial services campuses requiring cybersecurity compliance. |
| MIIT Certification Pre-Qualification | Secures access to Chinese state-owned enterprise tenders disqualifying non-compliant display imports. |
| Dante Protocol Specialization | Captures talent-scarce networked audio deployments in Japanese corporate headquarters and hospitality developments. |
| Backward Integration into LED Drivers | Reduces dependency on South Korean and Taiwanese foundry concentration for display driver IC supply. |
| Southeast Asian System Integration Partnership | Establishes localized presence for museum and experiential retail projection mapping in Thailand and Vietnam. |
Study Parameters
Multi-period observation of procurement cycle compression, certification timeline divergence, and foundry capacity allocation anchored the trend analysis, supplemented by interviews with AV system integrators, broadcast facility engineers, government procurement officers, and building automation specialists. Secondary validation drew from MIIT GB standard filings, BIS electromagnetic compatibility test records, TRAI broadband infrastructure directives, customs trade data for display panel imports, and SEC filings of diversified technology conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the Asia-Pacific region.
Segment-weighting approaches modeled display systems, video conferencing solutions, audio equipment, and projectors across technology tiers including LED, LCD, projection mapping, and OLED. End-user segmentation incorporated corporate, education, entertainment, and government procurement patterns. Installation types spanned integrated, fixed, portable, and custom solutions. CAGRs were derived from installed base refresh cycle analysis, policy mandate implementation schedules, and infrastructure investment pipelines. Industry-specific inputs included MIIT certification compliance rates and BIS approval timeline distributions.
The model holds under stable regulatory enforcement timelines and continued hybrid work infrastructure mandates; deviation in semiconductor supply chain disruption or abrupt tariff regime shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Advanced Baby Monitors Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Keycap Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Global Wireless Headphones Market