
 Global Laptop Skins Market | 2026-2036
Global Laptop Skins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laptop Skins Market Foresight
Aftermarket customization revenue is narrowing as direct-to-consumer channels capture margin pools once held by electronics retailers. dbrand leverages precision-cut vinyl templates and aggressive social media positioning to dominate premium personalization. MightySkins sustains volume leadership through licensed artwork partnerships and broad marketplace distribution. Skinit competes with institutional procurement contracts across universities and K-12 systems in North America.
Laptop skins are thin adhesive or snap-on protective layers, typically 0.1–0.5 millimeters thick, manufactured from cast vinyl, thermoplastic polyurethane, or polycarbonate substrates with pressure-sensitive acrylic backing; they shield device surfaces from abrasion while enabling aesthetic personalization for consumer and commercial users. Vinyl formulations anchor the material type segment due to cost efficiency and print compatibility, though polycarbonate variants are gaining traction among gaming users seeking rigid impact protection. Matte and textured design styles occupy mature demand pools, while metallic finish and transparent options are capturing premium margin segments as users prioritize subtle branding over loud patterning.
EPA scrutiny of phthalate plasticizers in vinyl production and REACH restrictions on SVHC substances in imported consumer goods are elevating compliance costs for manufacturers serving Europe and North America. BIS certification requirements for imported electronics accessories in India create additional market access friction for unbranded imports. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional material reformulation or supply chain regionalization delivers superior unit economics.
Market Dynamics
Direct-to-consumer vinyl printing infrastructure is compressing traditional retail margins while REACH and EPA phthalate rules force material reformulation across supply chains.
Growth Catalysts
- Remote worker procurement normalization:Enterprise IT departments now bundle aesthetic protection with device deployment, creating institutional recurring revenue streams distinct from consumer spontaneity.
- REACH SVHC disclosure mandates:European importers demand certified low-plasticizer substrates, accelerating substitution toward TPU and polycarbonate alternatives with cleaner compliance profiles.
- NCR cluster manufacturing density:Delhi-NCR print shops achieve same-day custom turnaround through integrated design-to-diecut workflows, capturing price-sensitive volume across South Asian e-commerce channels.
Market Restraints
- Cast vinyl feedstock volatility:Crude-derived plasticizer costs fluctuate with petrochemical indices, compressing gross margins for inventory-heavy distributors.
- Guangdong supply concentration:Pressure-sensitive adhesive backing production clusters in Pearl River Delta factories, creating single-region vulnerability for global fulfillment networks.
- Polycarbonate impact resistance ceiling:Rigid substrates above 0.4mm thickness interfere with laptop hinge tolerances, limiting protection upgrades for gaming device segments.
Strategic Opportunities
- India BIS certification arbitrage:Domestic labeling compliance creates protected market access for registered manufacturers against gray-market imports.
- UV-curable ink convergence:Instant-dry printing technology eliminates solvent emissions while enabling photographic resolution on textured vinyl surfaces.
- University procurement centralization:K-12 and higher-ed bulk purchasing platforms seek pre-approved vendor lists, favoring suppliers with institutional sales infrastructure.
Industry Challenges
- Color calibration talent scarcity:Digital print operators with ICC profile management skills command premium wages, constraining quality consistency at scaling facilities.
- Multi-jurisdiction SVHC tracking:ECHA substance list updates require continuous formulation monitoring, burdening smaller manufacturers without dedicated regulatory staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laptop Skins Market |
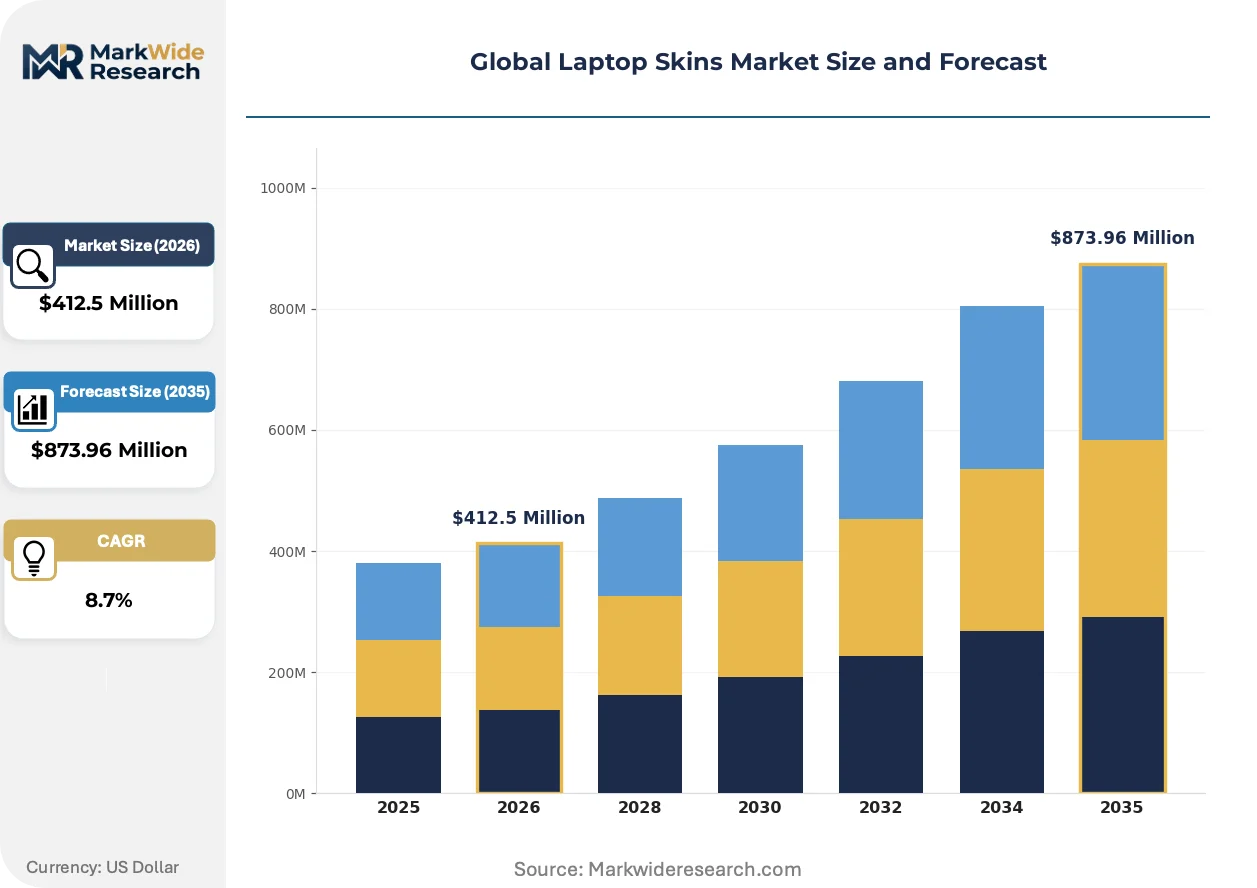
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Vinyl, Polycarbonate, Leather, Fabric, Silicone, Wood Veneer Design Style: Matte, Glossy, Textured, Printed Patterns, Metallic Finish, Transparent Application: Personal Use, Office Use, Educational Institutions, Gaming, Photography, Travel Sales Channel: Online Marketplaces, Specialty Retailers, Electronics Stores, Custom Print Shops, Subscription Services, Pop-up Events |
| Companies Covered | dbrand, MightySkins, Skinomi, Skinit, GelaSkins, DecalGirl, ZAGG, XtremeSkins, Slickwraps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laptop Skins Market Shifts & Advancements
Material science advances and channel compression are redefining how protective layers reach end users, with sustainability credentials now filtering purchasing decisions.
Cast-TPU laminate construction is hybridizing durability with flexibility, bonding elastomeric cores to printable vinyl faces. Gaming peripheral manufacturers specify these composites for tournament-grade device fleets requiring repeated re-skinning. The technology is hybridizing price tiers by collapsing the performance gap between economy vinyl and premium polycarbonate.
EPA scrutiny of vinyl chloride emissions intensified following updated toxic substance evaluations, pressuring domestic converters toward water-based adhesive systems. California Air Resources Board precedents now influence national sourcing standards. Small-batch producers in Texas and Florida face disproportionate compliance burdens relative to integrated chemical conglomerates.
Subscription-based refresh models are displacing one-time purchases among creative professionals and student cohorts. Quarterly design rotations replace permanent applications, with peel-and-replace workflows treated as consumable rather than durable goods. This pattern concentrates in North American urban markets where identity signaling through device aesthetics carries social currency.
Global Laptop Skins Market Segmentation
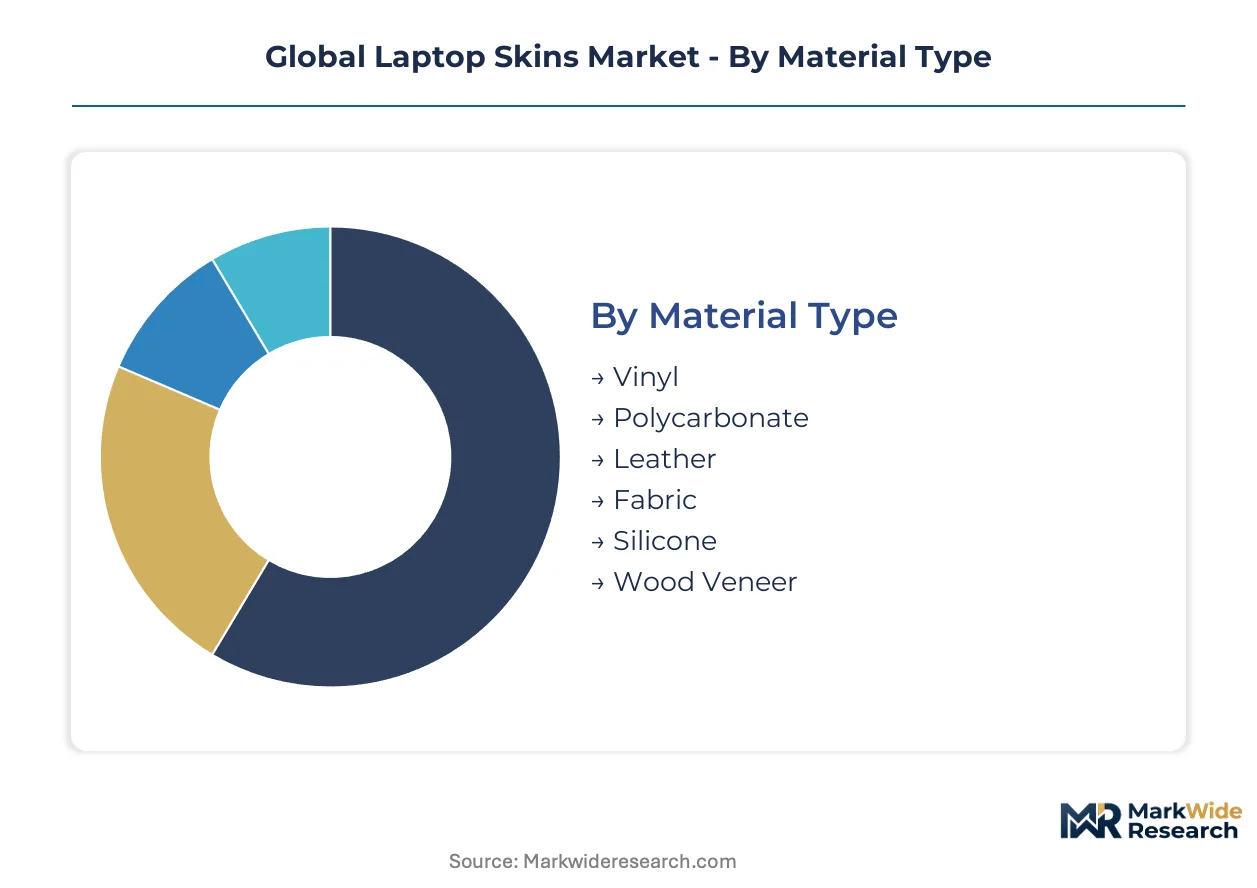
Laptop skin purchasing patterns fragment sharply across material preferences, aesthetic priorities, and procurement contexts. Manufacturers must align substrate engineering with specific end-use durability demands while calibrating design portfolios to channel-specific margin structures.
Material Type:
Mature vinyl formulations dominate installed base volumes while emerging alternatives capture premium repositioning opportunities.
- Vinyl:Cast and calendered polyvinyl chloride formulations with pressure-sensitive acrylic backing dominate production economics. REACH SVHC disclosure mandates in Europe and EPA phthalate scrutiny in the United States force continuous reformulation toward low-plasticizer compounds. Delhi-NCR manufacturing clusters exploit same-day custom turnaround capabilities to capture South Asian e-commerce volume.
- Polycarbonate:Rigid thermoplastic substrates ranging 0.3–0.5 millimeters thick deliver impact resistance for gaming device fleets requiring repeated re-skinning. Tournament-grade peripheral manufacturers specify these composites despite hinge tolerance interference above 0.4 millimeter thickness thresholds.
- Leather:Genuine and synthetic hide laminates target executive procurement segments with tactile premium positioning.
- Fabric:Woven textile faces bonded to flexible substrates serve creative professional cohorts seeking distinctive surface texture.
- Silicone:Elastomeric molded shells provide grip enhancement for travel and field-use scenarios.
- Wood Veneer:Thin timber laminates with adhesive backing occupy sustainability-signaling niche demand.
Vinyl handles the majority of throughput; polycarbonate is expanding most quickly on share.
Design Style:
Cost tier stratification separates economy matte coverage from premium metallic and transparent finishes commanding 3-4x unit pricing multiples.
- Matte:Non-reflective PVC or TPU faces with fine texture suppress fingerprint visibility and glare in office environments. Institutional procurement contracts across German universities and North American K-12 systems specify matte finishes for durability and subdued aesthetics.
- Glossy:High-sheen clearcoat surfaces maximize color saturation for photographic reproductions.
- Textured:Embossed patterns mimicking carbon fiber, brushed metal, or fabric weaves provide tactile differentiation.
- Printed Patterns:UV-curable and solvent-based inkjet reproductions of licensed artwork or custom imagery serve identity-signaling demand.
- Metallic Finish:Vacuum-deposited or pigment-loaded substrates create reflective chrome, copper, or gold effects. Subscription-based refresh models among Toronto and Vancouver creative professionals treat quarterly metallic rotations as consumable identity signaling rather than durable goods.
- Transparent:Clear cast vinyl or polycarbonate preserves OEM branding visibility while adding surface protection.
Matte absorbs baseline volume across institutional channels; metallic finish climbs the fastest on margin contribution.
Application:
Customer type divergence splits spontaneous consumer personalization from structured enterprise deployment workflows.
- Personal Use:Individual aesthetic protection purchases through Amazon, Etsy, and direct-to-consumer vinyl printing platforms. Indian and Indonesian price-sensitive consumers drive volume through marketplace aggregators.
- Office Use:Enterprise IT departments bundle skins with device deployment for remote worker fleets. Recurring procurement normalization creates institutional revenue streams distinct from consumer spontaneity.
- Educational Institutions:K-12 and higher-ed bulk purchasing platforms seek pre-approved vendor lists with BIS certification for Indian imports or REACH compliance for European tenders.
- Gaming:Tournament-grade device fleets specify cast-TPU laminate construction for repeated re-skinning durability.
- Photography:Color-calibrated skin production for creative professionals requires ICC profile management skills that command premium operator wages.
- Travel:Abrasion-resistant textures and silicone grip enhancements address mobile professional field-use scenarios.
Personal use generates raw unit volume; educational institutions represent the steepest expansion trajectory for contract-based recurring revenue.
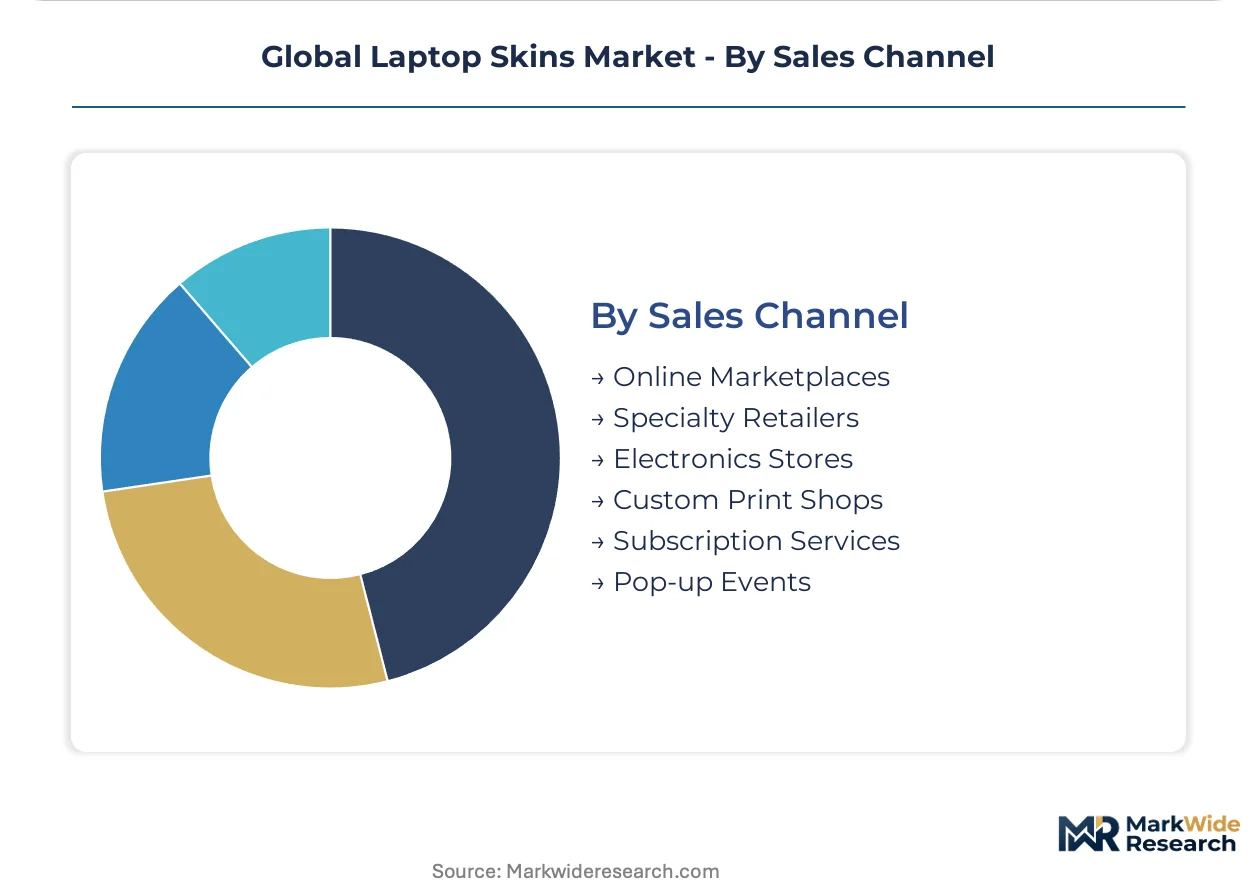
Sales Channel:
Geography of fulfillment determines margin capture, with domestic certification arbitrage protecting registered manufacturers against gray-market competition.
- Online Marketplaces:Amazon, Flipkart, and Tokopedia aggregate price-sensitive demand across Indian and Southeast Asian manufacturing clusters. dbrand and MightySkins leverage precision-cut templates and licensed artwork partnerships to dominate premium and volume positioning respectively.
- Specialty Retailers:Electronics accessory boutiques and university bookstores provide immediate fulfillment for spontaneous purchases.
- Electronics Stores:Big-box retailers and carrier outlets bundle skins with new device sales, though margin compression from direct-to-consumer channels narrows this pool.
- Custom Print Shops:Delhi-NCR and Guangdong integrated design-to-diecut workflows achieve same-day turnaround for personalized orders.
- Subscription Services:Quarterly design rotation models displace one-time purchases among North American urban creative professionals.
- Pop-up Events:Convention and campus activation channels capture impulse demand with on-site application services.
Online marketplaces command absolute volume leadership; subscription services are gaining share fastest among monetization model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Students and remote workers in India and Southeast Asia drive volume through price-sensitive e-commerce channels. Enterprise IT departments in North America and Europe bundle aesthetic protection with device deployment, creating institutional procurement workflows distinct from spontaneous consumer purchases.
United States
Enterprise IT departments normalize recurring skin procurement for remote worker fleets. EPA scrutiny of phthalate plasticizers in vinyl production pressures domestic converters toward water-based adhesive systems. Texas and Florida small-batch producers face disproportionate compliance burdens relative to integrated chemical conglomerates.
Germany
Institutional procurement contracts across universities specify matte finishes for durability and subdued aesthetics. REACH SVHC disclosure mandates accelerate substitution toward TPU and polycarbonate alternatives with cleaner compliance profiles. Berlin and Munich print shops serve European corporate clients with certified low-plasticizer substrates.
India
Price-sensitive consumers drive volume through marketplace aggregators like Flipkart. BIS certification requirements for imported electronics accessories create protected market access for registered manufacturers against gray-market imports. Delhi-NCR print shops achieve same-day custom turnaround through integrated design-to-diecut workflows.
China
Guangdong pressure-sensitive adhesive backing production clusters in Pearl River Delta factories create single-region vulnerability for global fulfillment networks. Domestic converters supply both export markets and growing local gaming peripheral demand. Shenzhen and Dongguan facilities dominate cast vinyl feedstock processing for international brands.
Indonesia
Tokopedia and regional e-commerce platforms aggregate demand across Southeast Asian manufacturing clusters. Young professionals and student cohorts prioritize aesthetic personalization for identity signaling on social media. Jakarta and Surabaya custom print shops capture volume through marketplace distribution partnerships.
Global Laptop Skins Market Competitive Landscape
Capability concentration sits with precision-cut template specialists; scale advantage sits with licensed artwork aggregators. The vendor base splits between direct-to-consumer platforms capturing margin pools once held by electronics retailers, and institutional procurement specialists serving bulk purchasing platforms. Three archetypes dominate: premium personalization engineers, volume licensing distributors, and institutional contract holders. Competitive moves center on social media positioning warfare and university procurement centralization.
Within the premium personalization tier, dbrand exemplifies precision-cut vinyl engineering and aggressive digital positioning. MightySkins occupies the volume-licensing vector through broad marketplace distribution and artwork partnerships. Skinit anchors the institutional procurement segment with pre-approved vendor status across North American K-12 and higher-education systems.
| Leading Market Players |
|---|
| dbrand |
| MightySkins |
| Skinomi |
| Skinit |
| GelaSkins |
| DecalGirl |
| ZAGG |
| XtremeSkins |
| Slickwraps |
| Others |
Supply & Pricing Matrix
Delhi-NCR manufacturing clusters anchor global vinyl skin production through same-day custom turnaround capabilities, translating geographic capacity density into pricing power across South Asian e-commerce channels. This concentration enables aggressive unit economics that compress margins for inventory-heavy distributors serving North American and European markets.
Pricing Analysis
Long-term offtake contracts with university procurement platforms and enterprise IT departments stabilize revenue for institutional specialists, while spot-market transactions through Amazon and Flipkart dominate consumer volume. Price differentiation hinges on REACH certification tier and customization turnaround speed, with certified low-plasticizer substrates commanding premium positioning. Cost compression in economy vinyl tiers is intensifying because Delhi-NCR print shops exploit integrated design-to-diecut workflows. Students and price-sensitive consumers in India and Indonesia exhibit highest price sensitivity; gaming peripheral manufacturers and creative professionals in Toronto and Vancouver show lowest sensitivity due to performance requirements.
Supply Chain Analysis
Contract manufacturing concentrates among Guangdong pressure-sensitive adhesive specialists and Delhi-NCR integrated print-to-diecut facilities, with secondary capacity emerging in Indonesian marketplace-fulfillment partnerships. Raw material dependencies center on cast vinyl feedstock, acrylic adhesive backing, and UV-curable ink formulations. Single-region vulnerability in Pearl River Delta adhesive production creates structural risk for global fulfillment networks. Distribution runs through online marketplaces aggregating price-sensitive demand, with subscription services capturing recurring revenue among North American urban creative professionals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laptop skins market operates as a defensive-moat business where regulatory entrenchment creates protected market access, with BIS certification requirements and REACH compliance acting as barriers that favor incumbent specialists over gray-market imports.
For Market Incumbents: Insulate market position by deepening backward integration into cast vinyl feedstock processing and securing pre-approved vendor status across K-12 and higher-ed procurement platforms. Threats from direct-to-consumer vinyl printing infrastructure demand channel control investments, while EPA phthalate scrutiny necessitates continuous low-plasticizer formulation R&D.
For New Entrants and Emerging Players: Build out white-space presence in subscription-based refresh models targeting North American creative professionals, where quarterly design rotations displace one-time purchases. The most penetrable segment lies in Indian BIS certification arbitrage, where domestic labeling compliance creates protected market access against unbranded imports. A direct-to-consumer platform with precision-cut template engineering offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-cut template specialists with institutional sales infrastructure over pure-play licensed artwork aggregators. Long-term viability rests on regulatory compliance capabilities and recurring revenue normalization across enterprise and educational procurement channels. The signal to watch is university procurement centralization trends, as pre-approved vendor list consolidation determines volume allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | European market access hinges on SVHC disclosure mandates from ECHA. |
| Direct-to-Consumer Platform Launch | dbrand's precision-cut template approach captures margin pools from electronics retailers. |
| Subscription Service Introduction | Quarterly design rotations monetize identity signaling among Toronto creative professionals. |
| Backward Integration into Vinyl Feedstock | Cast vinyl processing control insulates margins from petrochemical price volatility. |
| University Procurement Partnership | Pre-approved vendor status across North American K-12 systems secures recurring revenue. |
Research Methodology
A standing panel of vinyl manufacturing plant managers, e-commerce platform category leads, university procurement officers, and EPA regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from ECHA substance database updates, BIS certification registries, Amazon and Flipkart marketplace transaction data, and SEC filings from listed electronics accessory distributors. Bottom-up demand modeling across material type, design style, application, and sales channel segments was triangulated with top-down market sizing.
Scenario bracketing across conservative, baseline, and expansion cases informed projections across the analysis window. Segmentation dimensions modeled include substrate material, finish aesthetic, end-use context, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and input cost trajectory assumptions. Industry-specific forecast inputs incorporated REACH SVHC list update frequency and BIS enforcement intensity variations.
Stress conditions across crude-derived plasticizer cost spikes, Guangdong supply disruptions, and EPA enforcement escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about institutional procurement normalization and direct-to-consumer channel penetration. Quarterly review of university tender volume, Delhi-NCR print shop capacity utilization, and ECHA substance list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Wet Wipes Market