
 Desert Boots Market | 2026-2036
Desert Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Desert Boots Market Outlook
Modular product bundling with interchangeable insoles and weatherproof liners is restructuring how buyers evaluate desert boots across seasons and use cases. Clarks leverages its heritage archive to sustain premium positioning in heritage retail channels. Timberland LLC anchors its desert boot line through rugged material sourcing and outdoor credibility. Dr. Martens differentiates via its air-cushioned sole technology transferred from core footwear platforms.
Desert boots are ankle-height footwear constructed with crepe rubber soles and suede or leather uppers, traditionally featuring a minimal two-eyelet lacing system and unstructured toe box for flexibility in arid conditions. They serve both military origins and civilian fashion markets, with crepe sole composition providing distinct cushioning properties that degrade predictably in high-temperature environments. The suede and leather material segments split between heritage authenticity preferences and performance-treated variants, with treated leathers commanding margin premiums in law enforcement procurement channels. Casual boots and tactical boots represent divergent growth vectors, the former maturing in European fashion retail while the latter accelerates through paramilitary and private security contracting.
REACH in Europe restricts chromium VI in leather tanning processes, forcing reformulation of traditional suede finishing. The US EPA oversees volatile organic compound emissions from adhesive applications in domestic assembly facilities. California's Proposition 65 adds disclosure burdens for footwear containing certain chemical treatments. Stakeholders must monitor evolving material compliance thresholds while calibrating regional production footprints against regulatory enforcement intensity.
Market Dynamics
REACH compliance in Europe is forcing reformulation of traditional suede tanning processes, while heritage fashion demand in the United Kingdom pulls manufacturers toward premium positioning. This regulatory-demand tension defines current competitive maneuvering.
Growth Catalysts
- Crepe sole innovation:Advanced rubber compounding techniques improve heat degradation resistance, expanding deployment into law enforcement and private security contracting channels.
- Casual workplace normalization:Office dress code relaxation across Germany and France accelerates heritage boot adoption as acceptable professional footwear.
- REACH-driven material transparency:Chromium VI restrictions create competitive differentiation for early-compliant tanneries supplying European retail networks.
Market Restraints
- Raw material concentration:Premium crepe rubber sourcing clusters in Southeast Asian plantations, exposing supply chains to climate volatility and export licensing friction.
- Substitution threat from technical footwear:Lightweight synthetic tactical boots displace leather desert boots in paramilitary procurement where weight reduction dominates specifications.
- Regulatory fragmentation:Divergent chemical disclosure requirements between California Proposition 65 and EU REACH increase compliance overhead for multi-territory brands.
Strategic Opportunities
- Modular product architecture:Interchangeable insole and liner systems enable year-round relevance, capturing buyers who previously treated desert boots as seasonal purchases.
- Private security vertical expansion:Middle Eastern and North African contracting markets prioritize discrete professional aesthetics over overt tactical signaling.
- EU Green Deal alignment:Bio-based tanning agents and recycled rubber outsoles qualify manufacturers for public procurement preference schemes and sustainability-linked financing.
Industry Challenges
- Skilled pattern-cutting deficit:Traditional unstructured toe box construction requires artisan-level hand-finishing that vocational training programs no longer emphasize.
- Dual certification timelines:Simultaneous ISO 20347 occupational footwear and EN ISO 20345 safety boot approvals extend product launch cycles by 8-14 months.
- Legacy inventory integration:Modular boot systems demand redesigned warehousing and size-run forecasting that conflicts with established seasonal buying calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desert Boots Market |
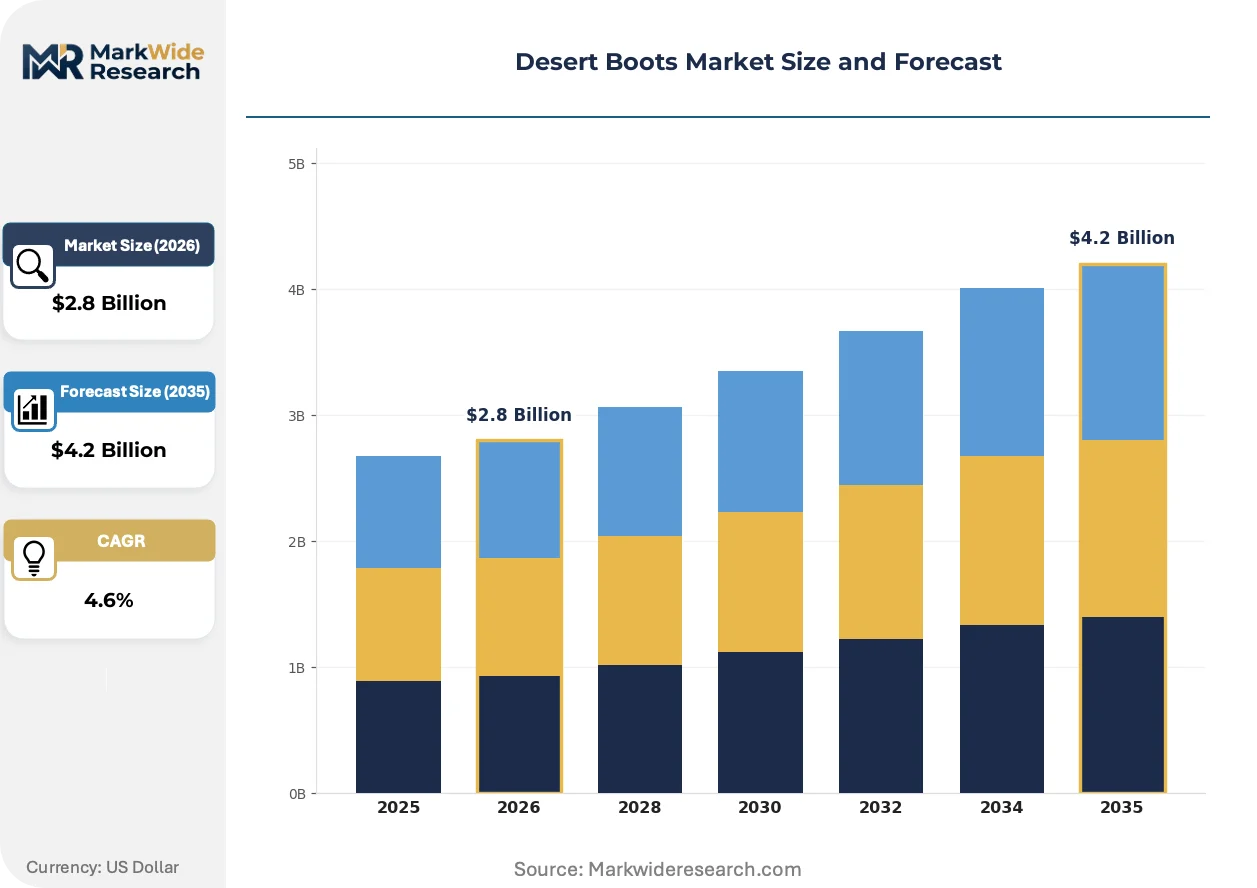
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combat Boots, Hiking Boots, Casual Boots, Tactical Boots Material: Leather, Suede, Synthetic Fabric, Rubber End User: Military Personnel, Outdoor Enthusiasts, Law Enforcement, Fashion Consumers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Clarks, Timberland LLC, Dr. Martens, Red Wing Shoes, Wolverine World Wide, Inc., L.L.Bean, Padmore & Barnes, Wolf & Shepherd, Kenneth Cole, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desert Boots Market Strategic Shifts
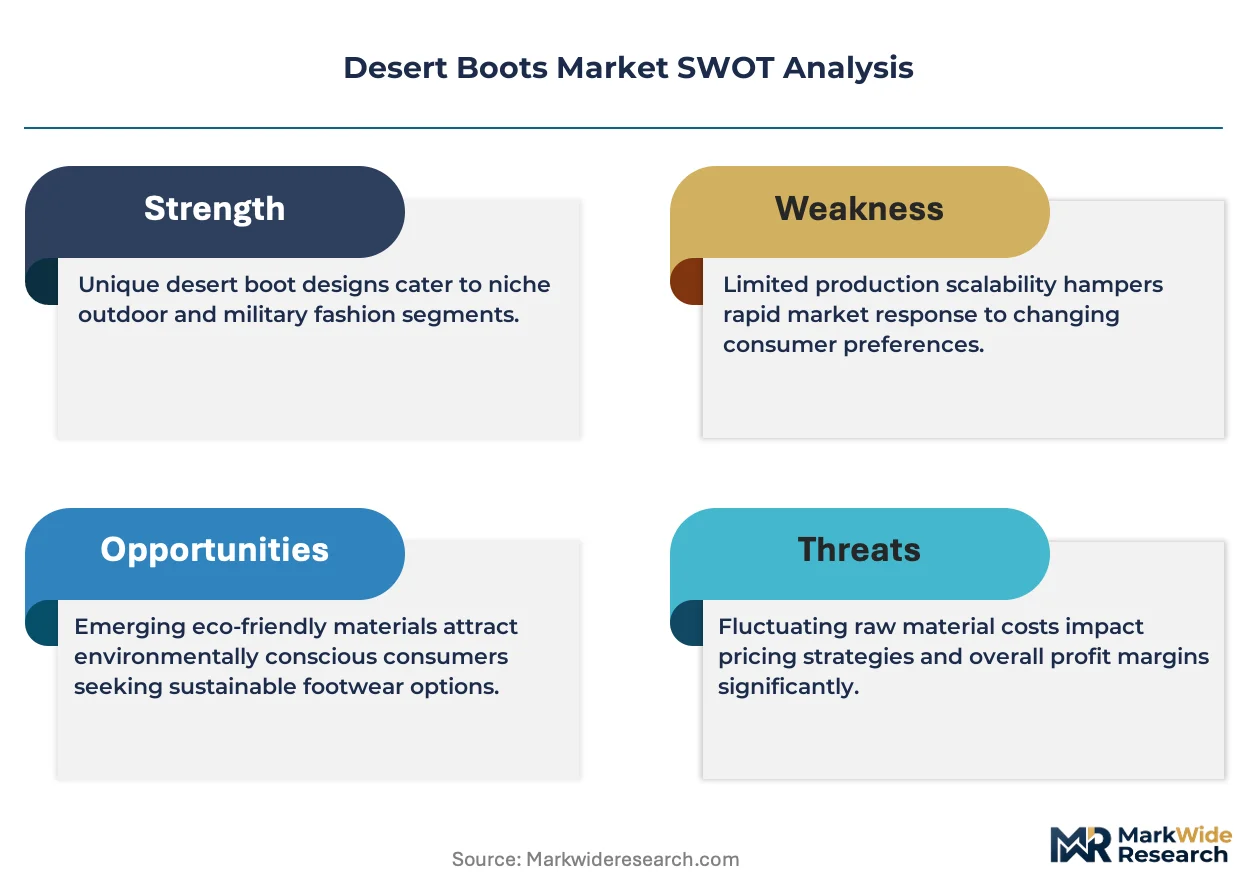
Material science convergence with heritage aesthetics is redefining how desert boots balance authenticity claims against performance expectations. Manufacturers now compete on invisible technical specifications rather than visible design alone.
Water-based polyurethane coatings is consolidating performance expectations across treated leather uppers. Outdoor retailers and urban fashion buyers now specify identical hydrophobicity standards. This technical convergence compresses differentiation space between heritage positioning and outdoor functionality.
REACH Annex XVII restrictions on chromium VI in leather tanning entered full enforcement across EU member states in 2023. Tanneries serving footwear brands face mandatory third-party testing for residual hexavalent chromium. Italian and Portuguese suppliers invested most heavily in vegetable-tanning alternatives, securing preferential supply relationships with premium brands.
Direct-to-consumer resale channel growth is fragmenting traditional wholesale relationships. Authentication services and condition-grading standards now mediate secondhand transactions. United Kingdom-based platforms command disproportionate volume given the category's British heritage associations and collector community density.
Desert Boots Market Segmentation
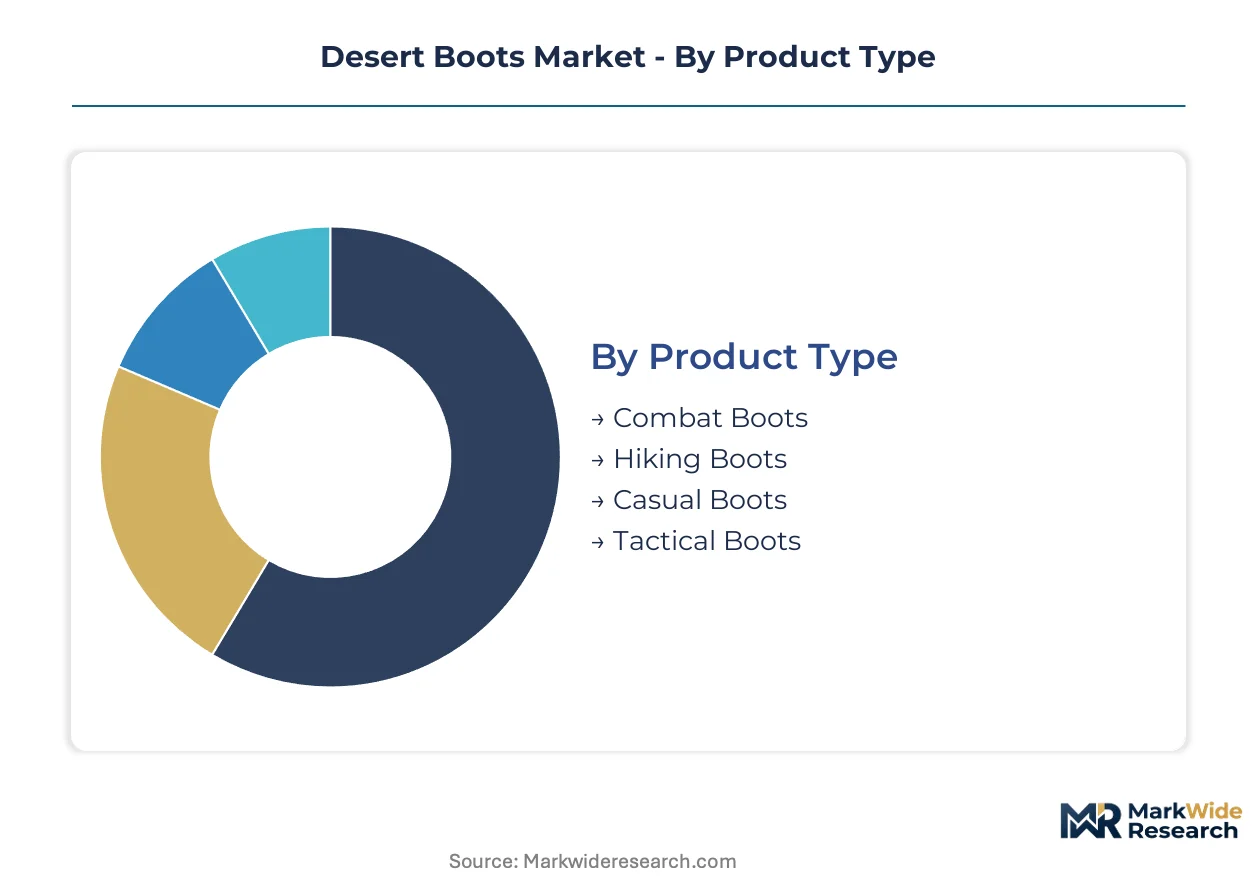
Desert boots span divergent use cases that reshape manufacturing priorities across each slice. Product architecture, material sourcing, and end-user certification requirements fragment production workflows and margin structures.
Product Type:
Volume concentrates in heritage casual formats while premium pricing accrues to specialized tactical and combat variants.
- Casual Boots:Unstructured suede uppers with crepe rubber soles dominate urban fashion retail in the United Kingdom and Germany. Office dress code relaxation across France accelerates adoption as acceptable professional footwear.
- Tactical Boots:Reinforced ankle support and oil-resistant outsole compounds serve private security contracting in the Middle East. Law enforcement procurement channels in the United States specify heat-degradation resistance standards that exceed civilian requirements.
- Combat Boots:Full-grain leather uppers with speed-lacing hardware meet military durability specifications. NATO standardization creates procurement concentration around certified suppliers.
- Hiking Boots:Aggressive lug patterns and waterproof membrane integration compete with dedicated outdoor footwear brands. Trail usage remains secondary to urban positioning for most desert boot manufacturers.
Mature deployment sits with casual boots. Newer deployment is concentrated in tactical variants.
Material:
Cost tiers separate heritage authenticity claims from performance-treated alternatives.
- Suede:Traditional napped leather finishes command authenticity premiums in United Kingdom heritage retail. REACH Annex XVII chromium VI restrictions force Portuguese and Italian tanneries toward vegetable-tanning alternatives.
- Leather:Full-grain and corrected-grain variants split between fashion positioning and uniform procurement. Treated leather with water-based polyurethane coatings consolidates hydrophobicity standards across outdoor and urban channels.
- Synthetic Fabric:Nylon and polyester blends reduce unit weight for paramilitary applications where mobility dominates specifications. Moisture-wicking linings address hot-climate deployment requirements.
- Rubber:Crepe sole compounding remains concentrated in Southeast Asian plantations. Advanced rubber formulations improve heat degradation resistance for law enforcement channels.
Heritage positioning anchors suede and leather. Synthetic fabrics are climbing the fastest among material categories.
End User:
Customer type determines certification burden and pricing architecture.
- Fashion Consumers:United Kingdom-based collectors drive secondary market volume through authentication platforms. Heritage styling preferences sustain premium pricing in London and Manchester retail corridors.
- Law Enforcement:Occupational footwear standards under ISO 20347 create compliance gates that filter supplier bases. California Proposition 65 disclosure requirements add documentation overhead for multi-territory brands.
- Military Personnel:National procurement offices specify durability testing protocols that extend product development cycles. NATO standardization creates volume concentration around approved vendor lists.
- Outdoor Enthusiasts:Trail and desert trekking applications demand outsole compounds with superior abrasion resistance. This segment competes directly with dedicated hiking boot manufacturers.
Procurement maturity sits with military channels. Fashion consumers represent the steepest expansion trajectory.
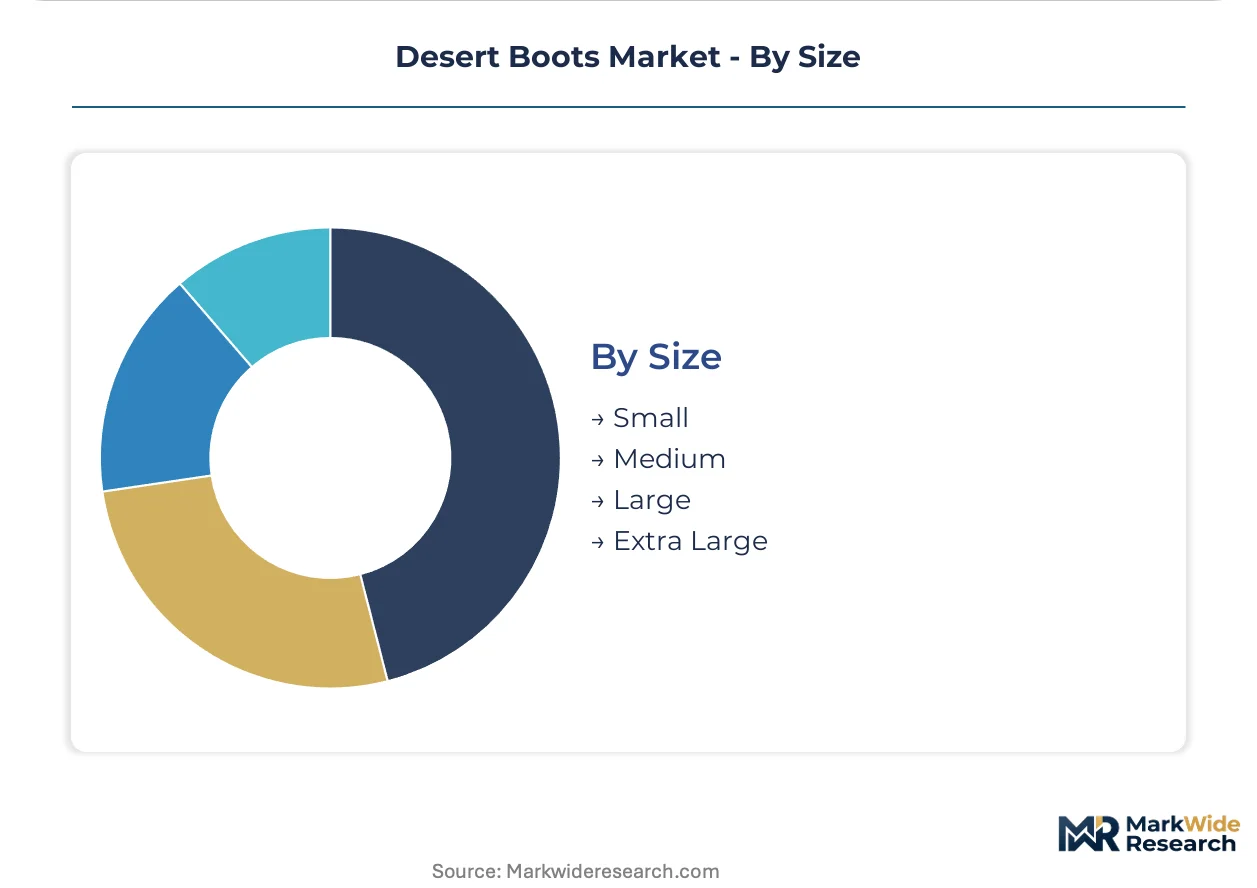
Size:
Volume distribution follows population demographics with regional fitting variations.
- Medium:Core volume concentration across European and North American markets. Size-run forecasting complexity increases with modular boot systems requiring interchangeable components.
- Large:Secondary volume peak in United States male demographics. Paramilitary procurement skews toward larger size distributions.
- Small:Women's fashion positioning and Asian market penetration drive distinct last shapes. Pattern-cutting requirements differ from men's lasts.
- Extra Large:Niche volume with limited supplier readiness. Custom production workflows disrupt standardized manufacturing lines.
Volume concentration sits with medium sizes. Extra large represents emerging demand with supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Vietnam and Bangladesh are pulling footwear assembly from traditional manufacturing bases, while heritage demand in the United Kingdom and Germany sustains premium positioning for European brands.
United Kingdom
London and Manchester retail corridors anchor heritage collector communities driving authentication platform volume. ECHA REACH Annex XVII enforcement on chromium VI in leather tanning forces Portuguese supplier relationships toward vegetable-tanning alternatives. Somerset and Northamptonshire industrial clusters concentrate traditional pattern-cutting expertise for unstructured toe box construction.
Germany
Ruhr Valley industrial buyers and Frankfurt financial sector professionals normalize desert boots within relaxed office dress codes. EU Green Deal procurement preference schemes reward bio-based tanning agents and recycled rubber outsoles in public contracting. Bavaria-based quality testing laboratories accelerate dual ISO 20347 and EN ISO 20345 certification workflows.
United States
Private security contracting in Texas and Arizona prioritizes discrete professional aesthetics over overt tactical signaling for desert boot procurement. EPA oversight of volatile organic compound emissions from adhesive applications shapes domestic assembly facility siting decisions. California Proposition 65 disclosure burdens filter multi-territory brand distribution strategies.
Italy
Tuscan and Veneto tanneries invested most heavily in REACH-compliant vegetable-tanning alternatives, securing preferential supply relationships with premium heritage brands. Milan fashion retail channels consolidate hydrophobicity standards across outdoor and urban positioning. Marche footwear industrial districts maintain artisan-level hand-finishing capabilities for unstructured construction.
France
Parisian professional services firms accelerate adoption as acceptable workplace footwear alongside Germany. ANSM chemical safety guidelines align with broader EU material transparency requirements. Lyon and Grenoble outdoor retail clusters demand identical performance specifications from heritage and technical boot manufacturers.
Desert Boots Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: heritage houses leveraging archive authenticity, outdoor brands transferring technical credibility, and artisan workshops preserving hand-finished construction. Dominant competitive moves include portfolio diversification into modular product systems and geographic expansion through direct-to-consumer resale channel integration.
Within the heritage house tier, Clarks and Dr. Martens occupy positions defined by British manufacturing lineage and transferred sole technology platforms. Timberland LLC anchors the outdoor-credibility vector through rugged material sourcing narratives. These three exemplify how brand origin stories translate into pricing architecture across United Kingdom, German, and United States retail networks.
| Leading Market Players |
|---|
| Clarks |
| Timberland LLC |
| Dr. Martens |
| Red Wing Shoes |
| Wolverine World Wide, Inc. |
| L.L.Bean |
| Padmore & Barnes |
| Wolf & Shepherd |
| Kenneth Cole |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal procurement preference schemes gate both qualified supply and premium-tier pricing access for desert boot manufacturers, rewarding Italian and Portuguese tanneries that invested in REACH-compliant vegetable-tanning alternatives while excluding non-compliant competitors from public contracting channels and sustainability-linked financing instruments.
Pricing Analysis
Margin tightening in standard-tier heritage casual boots reflects REACH-driven reformulation costs passed through Portuguese and Italian tannery networks. Three-tier pricing structure across premium, standard, and economy levels separates vegetable-tanned heritage variants from corrected-grain uniform procurement and synthetic paramilitary grades. Certification under ISO 20347 occupational footwear standards and EN ISO 20345 safety boot approvals commands substantial premiums. Fashion consumers in United Kingdom collector communities show lowest price sensitivity; private security contractors in Middle Eastern markets negotiate hardest on volume tenders.
Supply Chain Analysis
Crepe rubber compounding rests on Southeast Asian plantation networks concentrated in Thailand, Malaysia, and Indonesia, with advanced heat-resistant formulations requiring specialty latex grades. Full-grain leather feeds from Tuscan and Veneto tanneries; suede napping depends on Portuguese finishing houses. Single-source vulnerability clusters around Southeast Asian export licensing regimes subject to climate volatility. Distribution runs through heritage retail channels in United Kingdom and Germany, direct-to-consumer authentication platforms, and law enforcement procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artisan-level hand-finishing capability scarcity props pricing power for unstructured toe box construction, constraining volume expansion regardless of downstream demand signals.
For Market Incumbents: Deepen backward integration into Portuguese vegetable-tanning capacity to secure REACH-compliant suede supply against Italian competitor preferential relationships. Anchor proprietary crepe rubber formulation IP through exclusive Southeast Asian plantation partnerships. Defend against lightweight synthetic tactical boot substitution by accelerating modular product architecture deployment. For New Entrants and Emerging Players: Capture private security contracting white space in Middle Eastern and North African markets prioritizing discrete professional aesthetics over overt tactical signaling. Target United Kingdom-based direct-to-consumer resale authentication platforms where heritage collector density sustains premium velocity. Pursue EU Green Deal alignment as primary go-to-market credential for public procurement access. For Investors and Strategic Acquirers: REACH Annex XVII chromium VI testing mandate acceleration is the leading indicator that tannery compliance infrastructure will consolidate around early-mover Italian and Portuguese suppliers. Five-to-ten year viability favors vertically integrated heritage houses with captive finishing capacity rather than brand-licensing operators. Watch Italian Marche footwear district acquisition activity as inflection signal for artisan capability scarcity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Capacity | Portuguese vegetable-tanning investments secure REACH-compliant supply against Italian competitor relationships. |
| Modular Product Architecture Launch | Interchangeable insole and liner systems transform seasonal purchases into year-round revenue streams. |
| EU Green Deal Certification Program | Bio-based tanning agents and recycled rubber outsoles unlock public procurement preference schemes. |
| Direct-to-Consumer Resale Platform Partnership | United Kingdom authentication services mediate secondary market volume from heritage collector communities. |
| Dual Certification Investment | Simultaneous ISO 20347 and EN ISO 20345 approvals filter competitor access to law enforcement channels. |
Study Parameters
Independent corroboration across tannery technical directors, heritage brand product development leads, and private security procurement officers underwrites the qualitative findings. Primary fieldwork engaged footwear pattern-cutting artisans in Somerset and Northamptonshire, REACH compliance consultants advising Portuguese suppliers, and category buyers at United Kingdom heritage retail corridors. Secondary validation drew from ECHA enforcement documentation, Italian Confindustria Moda sector reports, and United States EPA adhesive emissions filings. Bottom-up volume modeling triangulated against top-down value estimates across product type, material, end user, and size segmentation dimensions.
Comparable-period anchoring referenced historical adoption curves for heritage casual boots in United Kingdom and Germany against tactical variant penetration in Middle Eastern contracting markets. The analytical framework modeled volume and value outputs across the projection horizon through segmented demand decomposition by fashion consumer, law enforcement, military personnel, and outdoor enthusiast end users. CAGRs derived from regression analysis of pricing power indicators including certification tier, material treatment grade, and channel control intensity. Forecast inputs incorporated REACH enforcement trajectory assumptions and crepe rubber supply elasticity estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Southeast Asian climate disruption, synthetic tactical boot substitution rates, and vocational training program recovery for artisan pattern-cutting skills. Assumptions underlying the analytical envelope reflect documented stakeholder input and secondary source triangulation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
UGG Boots Market
Footwear
Luxury Footwear Market
Footwear
Global Espadrille Flats Market
Footwear
Snow Boots for Women Market
Footwear
Football Shoes Market
Footwear
Kids Barefoot Shoes Market
Footwear
Global Footwear Market
Footwear
North America Athletic Footwear Market
Footwear
GCC Footwear Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Sneaker Identification Service Market
Footwear
Indian Footwear Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Global Recovery Footwear Market
Footwear
Equestrian Footwear Market
Footwear
Global Men Leather Shoes Market