
 Wrist Watch Market | 2026-2036
Wrist Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Wrist Watch Market Analysis
Professional gifting and corporate recognition programs are restructuring how mid-luxury brands engage institutional buyers. Rolex anchors its position through unmatched brand equity in the sports-luxury tier. Patek Philippe specializes in ultra-complicated movements that command sustained auction premiums. Seiko Watch Corporation leverages vertical manufacturing depth to compete across price points from entry-level to Grand Seiko.
A wrist watch is a portable timekeeping instrument worn on the wrist, comprising a movement (mechanical, quartz, or solid-state), case assembly typically of stainless steel, titanium, or ceramic, and a display mechanism with power reserve or battery life as critical functional parameters; its primary commercial purpose spans personal time management, status signaling, and wearable computing. The analog segment retains margin concentration in the luxury tier where mechanical craftsmanship justifies pricing power, while the smart watch category captures the fastest growth trajectory as health-monitoring features expand clinical-adjacent use cases. Ceramic and titanium materials within the material segment are gaining share as consumers prioritize scratch resistance and hypoallergenic contact surfaces.
The European Chemicals Agency enforces REACH substance restrictions that govern nickel content in watch cases and bracelets, directly shaping alloy selection and supplier qualification timelines. The Federal Communications Commission regulates smart watch radio-frequency emissions in the United States, creating a compliance threshold that filters entrants lacking electromagnetic testing infrastructure. ISO 1413 shock-resistance standards and ISO 22810 water-resistance ratings further define product integrity benchmarks across export markets. Stakeholders must monitor how evolving battery-safety directives and right-to-repair legislation recalibrate after-sales service economics and product lifecycle design.
Market Dynamics
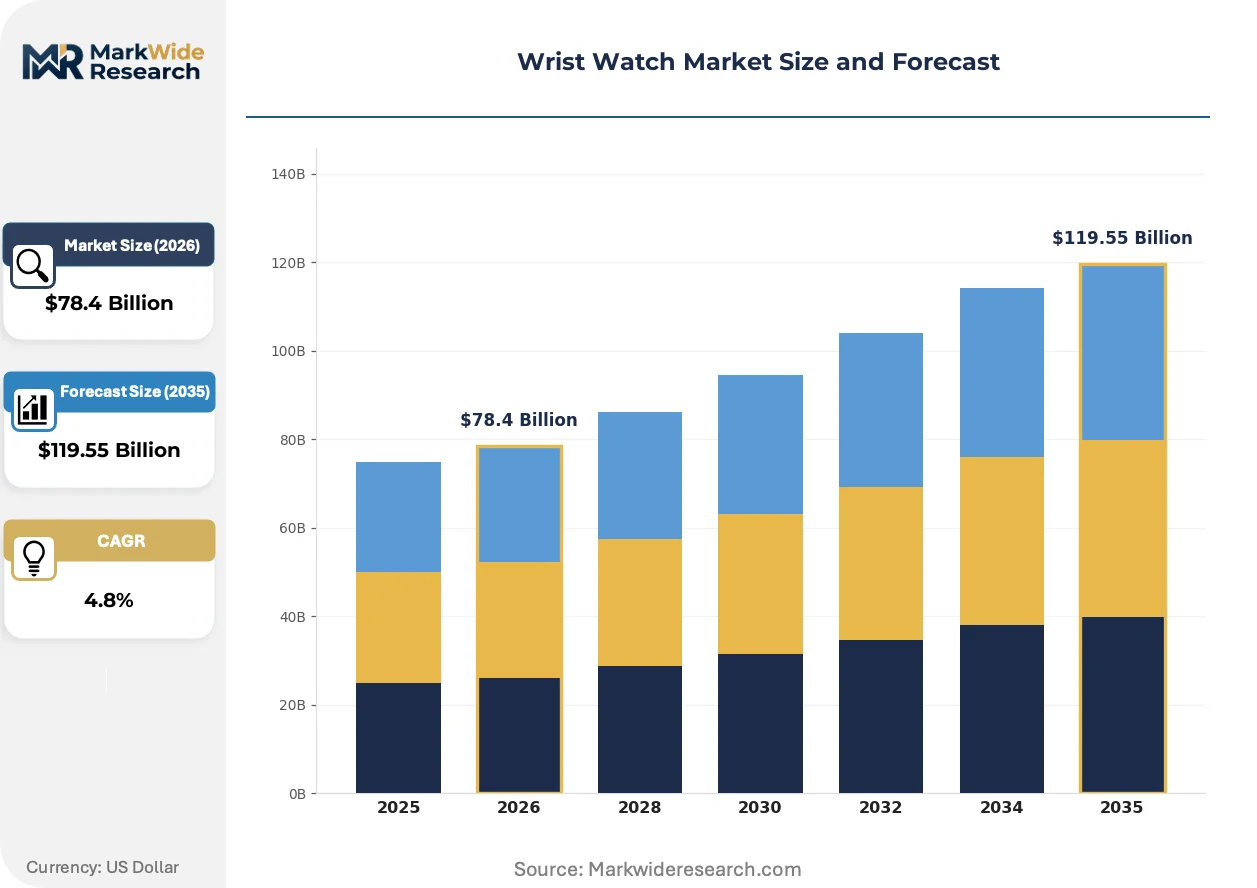
The wrist watch market is experiencing a structural bifurcation between mechanical heritage craftsmanship and solid-state health-monitoring platforms, with regulatory compliance costs now determining viable entry points across both analog and smart segments.
Growth Catalysts
- REACH nickel-release thresholds:European Chemicals Agency enforcement of stricter contact-surface standards is accelerating alloy substitution toward titanium and ceramic case materials, creating premium positioning for compliant suppliers.
- Clinical-adjacent health monitoring:FDA-cleared blood oxygen and ECG functionalities in wrist-worn devices are expanding reimbursable use cases through employer wellness programs and remote patient monitoring contracts.
- Haute horlogerie collector demand:Switzerland's concentration of artisanal movement manufacturers is sustaining auction-price premiums for complications, insulating mechanical production from quartz commoditization pressures.
Market Restraints
- Lithium-polymer cell volatility:Battery raw material cost swings and thermal-runaway shipping restrictions are compressing margins on smart watch assemblies with sub-48-hour charge cycles.
- Swiss movement supply concentration:Dependency on Valjoux, Sellita, and in-house atelier outputs for mechanical calibers creates allocation bottlenecks during demand surges.
- FCC electromagnetic testing infrastructure:Smart watch radio-frequency certification requires anechoic chamber access and SAR measurement protocols that filter entrants lacking capitalized compliance departments.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Component assembly incentives and tariff rationalization on display modules are attracting mid-tier smart watch contract manufacturers to Gujarat and Tamil Nadu clusters.
- EU right-to-repair directives:Mandated battery replaceability and spare-part availability timelines are creating aftermarket service revenue pools for independent horologists and authorized service networks.
- Silicon-carbide coating convergence:Thin-film deposition techniques from semiconductor tooling are migrating to watch case finishing, enabling scratch-resistant surfaces at reduced material thickness.
Industry Challenges
- Master watchmaker succession gaps:Swiss and German apprenticeship pipelines are failing to replace retiring specialists in hairspring adjustment and tourbillon assembly.
- ISO 22810 water-resistance certification timelines:Pressure-testing protocols for 100-meter-plus ratings require dedicated equipment queues that delay product launches by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrist Watch Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Smart, Hybrid End User: Men, Women, Kids, Unisex Material: Stainless Steel, Leather, Rubber, Ceramic Feature: Water-Resistant, GPS, Heart Rate Monitor, Sleep Tracking |
| Companies Covered | Cartier, Seiko Watch Corporation, Rolex, Longines, Tudor, Patek Philippe, Omega, Vacheron Constantin, Audemars Piguet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrist Watch Market Emerging Trajectories
Solid-state sensor miniaturization and materials science advances are compressing functional differentiation cycles, while regulatory frameworks on both sides of the Atlantic are rewriting design-for-compliance protocols.
Titanium grade 5 and ceramic matrix composites are expanding into sports-luxury and tool-watch segments as consumers prioritize mass reduction and dermal compatibility. Alpine and diving enthusiasts are adopting these materials at accelerating rates. The shift is expanding into price tiers previously dominated by stainless steel, forcing foundries to retool casting and machining lines.
ECHA's evolving REACH annex XVII restrictions on nickel migration are mandating alloy reformulation and extended leaching-test documentation for all bracelet and case exports into EU member states. Manufacturers are responding by qualifying alternative austenitic grades or migrating to entirely nickel-free titanium architectures. Swiss and German mid-luxury houses face the steepest compliance cost escalations due to legacy stainless steel dependencies.
Direct-to-consumer configuration platforms are displacing wholesale showroom dependency for entry-luxury mechanical brands, with buyers specifying dial treatments, strap materials, and engraving through browser-based interfaces. Authorized dealer networks in North America and Western Europe are consolidating as a result. The pattern is most visible among independent ateliers in Glashütte and the Jura arc seeking margin recovery from wholesale discount structures.
Wrist Watch Market Segmentation
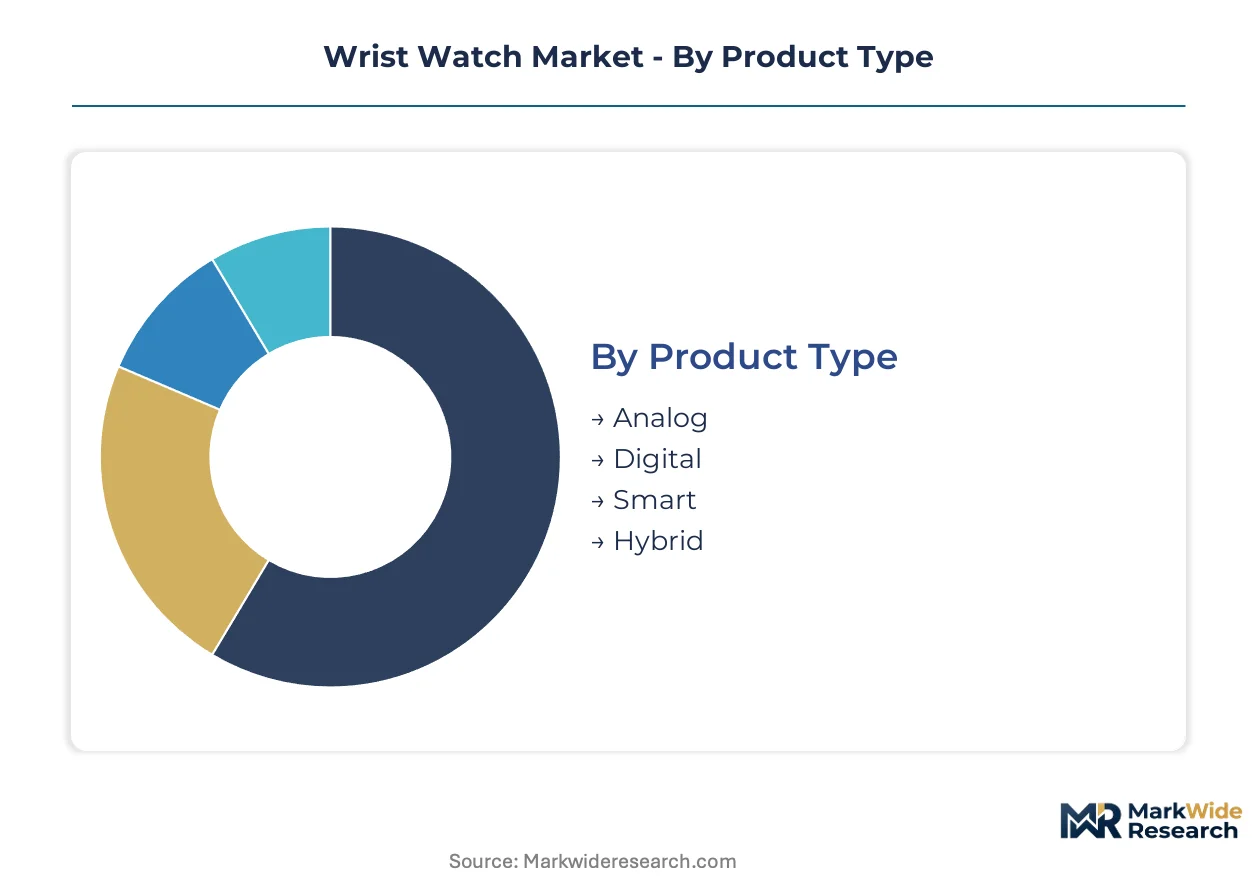
Wrist watch segmentation reveals how purchase motivations diverge sharply between heritage-driven collectors and utility-focused wearable adopters. Buyers sort first by functional archetype, then by material compatibility with lifestyle demands, creating distinct margin pools across mechanical and solid-state platforms.
Product Type:
Purchase intent splits between timekeeping tradition and biometric utility, with battery architecture and movement complexity determining price elasticity.
- Analog:Mechanical and quartz movements power traditional dial displays, with Swiss ateliers commanding sustained premiums for hand-finished calibers. Collector demand concentrates in Geneva and Biel for complications, insulated from digital commoditization by artisanal scarcity.
- Smart:Solid-state sensors and lithium-polymer cells enable continuous health monitoring, with FDA-cleared ECG and blood oxygen features expanding employer wellness program adoption. Silicon Valley and Shenzhen hardware ecosystems compete on sensor fusion and battery optimization.
- Digital:LCD and LED displays serve price-sensitive utility buyers, with Japanese manufacturers leveraging vertical component integration to maintain entry-tier positioning.
- Hybrid:Mechanical hands overlay connected notification functions, targeting professionals seeking analog aesthetics with discreet digital utility.
Volume sits with Digital; growth tilts toward Smart.
End User:
Demographic targeting reflects diverging wrist real estate competition from smartphones and fitness bands across life stages.
- Men:Tool-watch heritage and sports-luxury positioning dominate, with dive and aviation complications sustaining mechanical purchase frequency. Swiss and German houses allocate limited production to collector-heavy segments.
- Women:Jewelry-adjacent design and smaller case diameters shape assortment, with ceramic and precious metal variants capturing gifting occasions.
- Kids:GPS tracking and parental communication features define the category, with Chinese OEMs dominating contract manufacturing for safety-focused wearables.
- Unisex:Neutral case sizing and modular strap systems expand addressable market, particularly among direct-to-consumer mechanical brands.
Margin concentrates in Men; Unisex expands addressable base fastest.
Material:
Surface chemistry and dermal compatibility now filter supplier qualification under REACH nickel restrictions.
- Stainless Steel:Austenitic grades dominate mid-luxury production, though ECHA leaching-test documentation is forcing alloy reformulation or titanium migration. German and Swiss mid-tier houses face steepest compliance cost escalations.
- Ceramic:Zirconium oxide and matrix composites deliver scratch resistance and hypoallergenic contact surfaces, with adoption accelerating among diving and alpine enthusiasts prioritizing durability over mass.
- Leather:Calfskin and exotic variants serve dress-watch traditions, with Italian tanneries supplying haute horlogerie ateliers.
- Rubber:Fluoroelastomer and silicone straps dominate tool-watch and smartwatch segments, prioritizing sweat resistance and integrated fit.
Shipments cluster in Stainless Steel; Ceramic gains share steepest.
Feature:
Functional certification and sensor integration determine pricing tiers and regulatory exposure.
- Water-Resistant:ISO 22810 pressure-testing protocols gate 100-meter-plus ratings, with dedicated equipment queues delaying launches. Swiss testing houses maintain certification bottlenecks.
- Heart Rate Monitor:Photoplethysmography sensors enable clinical-adjacent monitoring, with FDA clearance pathways differentiating premium smartwatch positioning.
- GPS:Multi-band satellite reception supports navigation and pace accuracy for athletic use cases, with FCC radio-frequency certification filtering entrant capabilities.
- Sleep Tracking:Accelerometer and SpO2 fusion algorithms expand wellness platform stickiness, though battery drain tradeoffs compress charge cycles.
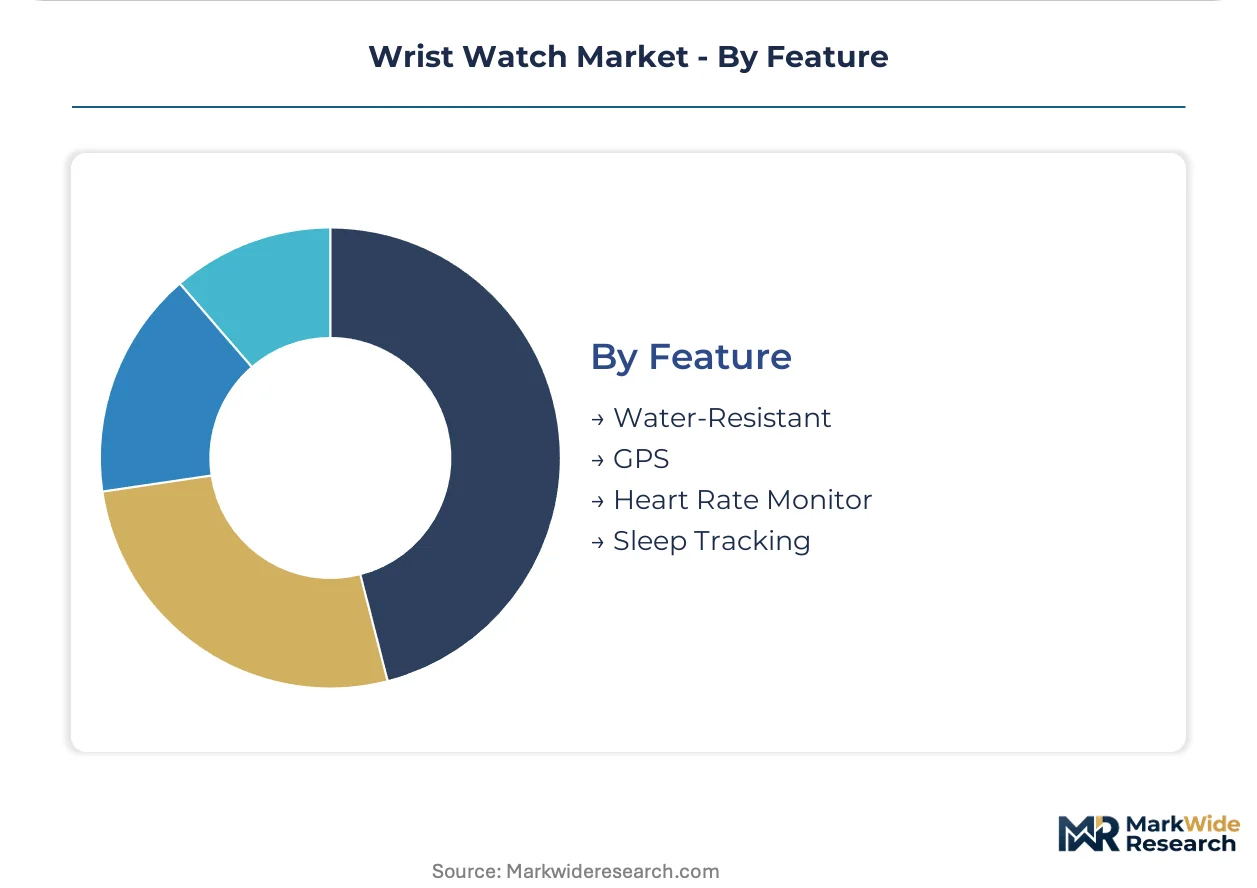
Adoption concentrates in Water-Resistant; Sleep Tracking climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss ateliers concentrate mechanical production while Chinese contract manufacturers dominate smartwatch assembly, creating a geographic split between heritage craftsmanship and solid-state volume production. Demand nodes fragment across collector markets in Geneva, mid-tier consumption in Shanghai, and clinical-adjacent wearable adoption in California medical corridors.
Switzerland
Geneva and Biel harbor the densest concentration of haute horlogerie ateliers, where artisanal movement finishing sustains auction-price premiums. Swissmedic regulates medical-device claims for emerging health-monitoring mechanical hybrids. The Jura arc from Le Locle to La Chaux-de-Fonds anchors hand-finishing apprenticeships and complications manufacturing.
China
Shenzhen hardware ecosystems supply lithium-polymer cells and display modules for global smartwatch brands. MIIT enforces GB standards for radio-frequency emissions and battery safety certifications. The Pearl River Delta cluster compresses sensor fusion prototyping cycles through vertically integrated component sourcing.
United States
Employer wellness programs and remote patient monitoring contracts expand FDA-cleared wearable adoption among clinical-adjacent users. The FCC regulates smartwatch electromagnetic emissions through SAR measurement protocols. Silicon Valley hardware startups and Minnesota-based medical device divisions compete on photoplethysmography sensor accuracy.
India
Gujarat and Tamil Nadu electronics manufacturing clusters attract mid-tier smartwatch assembly under PLI scheme incentives. BIS mandates ISI marking for lithium-ion cell imports and finished wearable safety testing. Chennai and Ahmedabad facilities specialize in GPS-enabled children's safety wearables for domestic and export markets.
Germany
Glashütte watchmakers leverage Saxon precision engineering heritage for direct-to-consumer mechanical brands. REACH enforcement through ECHA accelerates nickel-free alloy migration in bracelet and case production. The Glashütte corridor sustains independent atelier density through regional supplier networks and specialized finishing schools.
Wrist Watch Market Vendor Landscape
Top-tier vendors anchor the sports-luxury and haute horlogerie tiers, while mid-market specialists compete on manufacturing depth and direct-to-consumer configuration platforms. The vendor base stratifies across Swiss heritage houses with auction-house relationships, Japanese vertical manufacturers spanning entry to premium tiers, and Chinese contract assemblers serving Silicon Valley wellness brands. Three archetypes dominate: artisanal movement ateliers with multi-year waitlists, diversified manufacturers with in-house caliber production, and hardware-software integrators leveraging health-monitoring regulatory clearances. Competitive moves concentrate on direct-to-consumer channel buildout and titanium-ceramic material qualification under evolving nickel-release standards.
Within the heritage atelier tier, Rolex and Patek Philippe exemplify positioning through brand equity scarcity and complications craftsmanship respectively. Seiko Watch Corporation occupies a distinctive span from entry-level quartz through Grand Seiko haute horlogerie, representing vertical manufacturing depth across price architecture. These three entities illustrate how Swiss and Japanese houses defend margin pools through divergent strategies: auction-premium scarcity, artisanal movement complexity, and captive production integration.
| Leading Market Players |
|---|
| Cartier |
| Seiko Watch Corporation |
| Rolex |
| Longines |
| Tudor |
| Patek Philippe |
| Omega |
| Vacheron Constantin |
| Audemars Piguet |
| Others |
Supply Flow & Price Mechanics
Collector-heavy institutional buyers in Geneva and Shanghai concentrate demand for Swiss haute horlogerie and mid-tier smartwatch assemblies respectively, anchoring a bifurcated pricing model where artisanal scarcity premiums coexist with volume-driven component cost-down pressures.
Pricing Analysis
Margin tightening in entry-luxury mechanical tiers traces to wholesale consolidation and direct-to-consumer channel displacement. Three-tier pricing structure across haute horlogerie, sports-luxury, and entry-mechanical levels segments buyers by complications depth and brand equity. Cost compression in smartwatch assemblies accelerates because lithium-polymer cell volatility and FCC certification overhead filter capitalized entrants. Price sensitivity concentrates in digital utility buyers; collectors exhibit inelastic demand for Geneva and Biel complications.
Supply Chain Analysis
Dual-sourcing mandates from Swiss ateliers and Silicon Valley wellness brands require qualified alternative suppliers for hairsprings, escapements, and photoplethysmography sensors. Component manufacturing concentrates in Switzerland for mechanical calibers, China for display modules and battery cells, and Japan for quartz movements. Raw material dependencies span nickel-bearing austenitic steels, titanium grade 5 billets, and zirconium oxide ceramic powders. Supply chain risk centers on Valjoux and Sellita allocation bottlenecks during demand surges. Distribution runs through authorized dealer networks for heritage houses and direct-to-consumer platforms for emerging mechanical brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master watchmaker succession gaps in Swiss and German apprenticeship pipelines constrain mechanical production capacity, propping auction premiums and waitlist pricing for complications manufacturers.
For Market Incumbents: Deepen captive supply of hairsprings and escapements through in-house atelier expansion in the Jura arc, insulating against Valjoux and Sellita allocation bottlenecks. Fortify direct-to-consumer configuration platforms to recover margin from consolidating wholesale networks in North America and Western Europe. Prioritize titanium grade 5 and ceramic matrix qualification ahead of ECHA nickel-release threshold enforcement. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing in Gujarat and Tamil Nadu opens a window for mid-tier smartwatch contract assembly with tariff-rationalized display module sourcing. Target employer wellness program channels for FDA-cleared ECG and blood oxygen wearables, where clinical-adjacent positioning commands pricing power absent in consumer fitness segments. Pursue white-label partnerships with Shenzhen hardware ecosystems to compress sensor fusion prototyping cycles. For Investors and Strategic Acquirers: The window for entry favors vertically integrated Japanese manufacturers spanning entry-quartz through haute horlogerie tiers, where manufacturing depth supports margin defense across price architecture. Monitor Swiss apprenticeship graduation rates as an inflection indicator for mechanical production capacity constraints. Deviation in ECHA nickel-release enforcement timelines would shift alloy substitution economics and titanium foundry qualification priorities materially.| Strategic Initiative | Industry Significance |
|---|---|
| Titanium-Ceramic Material Qualification | ECHA REACH compliance secures EU market access for bracelet and case exports. |
| Direct-to-Consumer Platform Launch | Browser-based configuration recovers margin from consolidating wholesale networks. |
| India PLI Manufacturing Footprint | Gujarat and Tamil Nadu clusters attract tariff-rationalized smartwatch assembly. |
| FDA-Cleared Health Monitoring Integration | ECG and blood oxygen features expand reimbursable employer wellness adoption. |
| In-House Caliber Production Expansion | Jura arc atelier investment insulates against Swiss movement supply concentration. |
Methodological Framework
Independent corroboration across haute horlogerie atelier executives, smartwatch hardware engineering leads, and authorized dealer network managers underwrites the qualitative findings. Primary fieldwork encompassed complications manufacturers in Geneva and Biel, Shenzhen contract assemblers, and Glashütte independent watchmakers. Secondary validation drew from Swiss Customs Administration export statistics, ECHA substance restriction databases, FCC equipment authorization filings, and auction house complication sales records. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Comparable-period anchoring to historical Swiss export volumes and smartwatch sensor fusion adoption curves structured the projection framework. Segmentation dimensions modeled encompass product type, material architecture, end-user demographic, and functional certification tier across the analysis window. CAGRs derived from regression against disposable income elasticity and regulatory compliance cost trajectories. Forecast inputs incorporated ECHA nickel-release enforcement schedules and FDA 510(k) clearance pathways for clinical-adjacent wearables.
The model assumes a particular technology adoption path; alternative pathways for solid-state health monitoring miniaturization would alter the outlook. Forecasts reflect assumptions regarding Swiss apprenticeship pipeline replenishment and lithium-polymer cell thermal stability standards. Deviation in FCC electromagnetic testing infrastructure access or REACH annex XVII nickel migration thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Smart Speaker Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Portable Stick Market