
 Vertical Ergonomic Optical Mouse Market | 2026-2036
Vertical Ergonomic Optical Mouse Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Ergonomic Optical Mouse Market Insights
Enterprise procurement of ergonomic peripherals for hybrid office workers is realigning supplier priorities. Logitech leverages its distribution scale across corporate channels to sustain volume leadership in North American and European accounts. Evoluent specializes in adjustable-angle vertical designs that dominate the premium ergonomics segment among certified occupational therapists. Anker competes aggressively on price-point positioning, extending its consumer electronics brand into entry-level wireless vertical formats.
A vertical ergonomic optical mouse positions the hand in a neutral handshake posture, typically incorporating optical sensors with adjustable DPI resolution and sculpted contours that reduce pronation-induced wrist strain during extended computer use. Wireless variants incorporating Bluetooth and 2.4 GHz protocols are capturing the fastest growth trajectory as cable-free desk configurations become standard in modern workspaces. Office workers represent the mature volume base, while graphic designers command higher per-unit spending due to precision requirements and extended daily usage patterns that justify premium ergonomic investments.
OSHA workplace ergonomics guidelines in the United States, EU Display Screen Equipment directives under the European Agency for Safety and Health at Work, and Japan's Industrial Safety and Health Act collectively shape product certification pathways and employer procurement mandates. Compliance documentation from these frameworks increasingly appears in enterprise RFP specifications, filtering smaller uncertified suppliers from commercial tenders. Stakeholders must monitor evolving national interpretations of repetitive strain injury liability to anticipate which regulatory jurisdictions will next mandate employer-funded ergonomic peripheral programs.
Market Dynamics
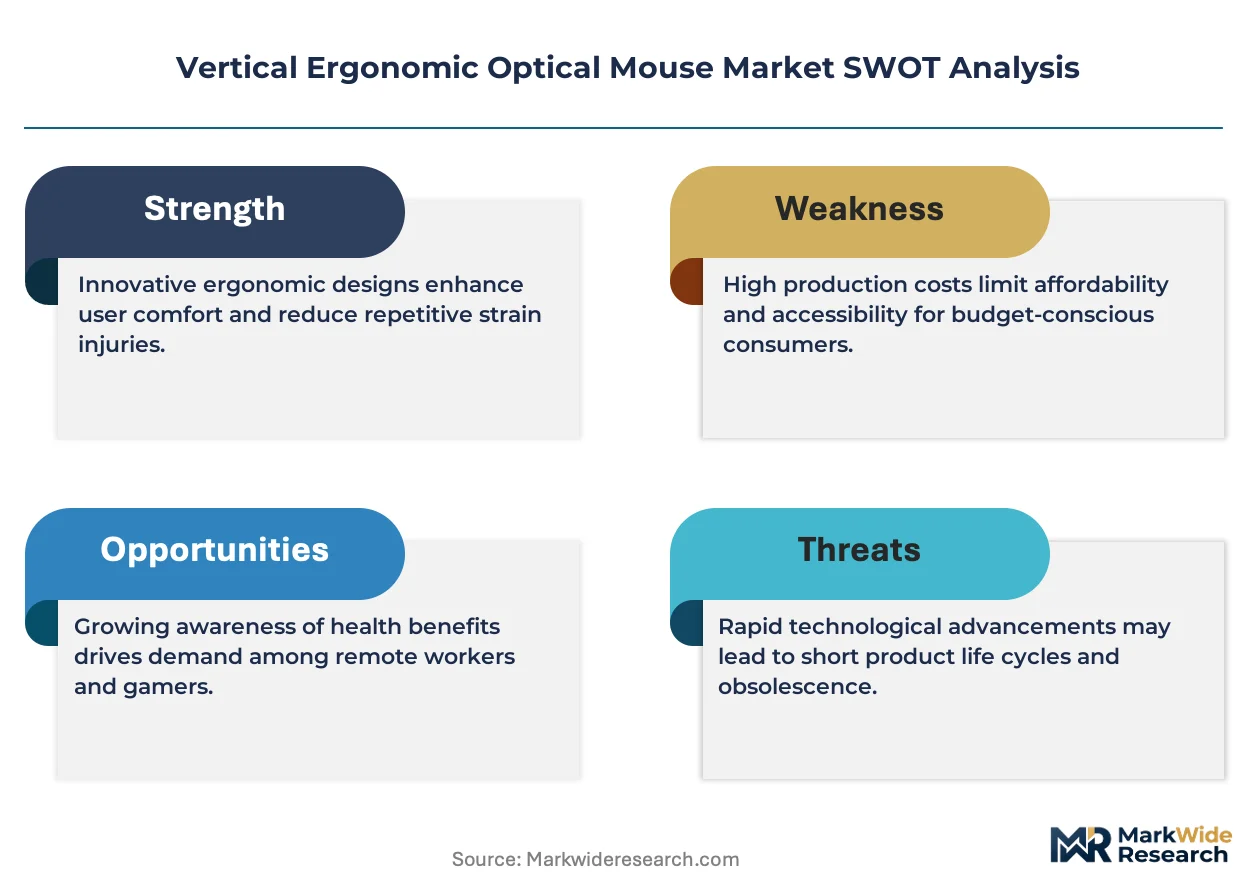
Hybrid work permanence is forcing employers to fund home-office ergonomic setups, converting what was once individual discretionary spending into corporate procurement volume with compliance documentation requirements.
Growth Catalysts
- OSHA Ergonomics Guidelines:United States employers face liability exposure for repetitive strain injuries, mandating documented ergonomic assessments that specify vertical mouse peripherals for at-risk workstations.
- Optical sensor precision gains:Adjustable DPI ranges now match gaming-grade performance, satisfying graphic designers and CAD operators who previously rejected vertical formats for accuracy limitations.
- Japan's Industrial Safety and Health Act:Mandatory employer-funded workstation assessments for white-collar staff create procurement pull through occupational health departments rather than IT purchasing.
Market Restraints
- Semiconductor input volatility:Optical sensor ICs and Bluetooth SoCs face allocation constraints from consumer electronics demand, compressing margins on wireless SKUs.
- Learning curve friction:Pronation-trained muscle memory requires 2-4 week adaptation periods, elevating return rates among non-committed buyers.
- EU Battery Directive compliance:Replaceable battery mandates and recycling documentation add certification costs that disproportionately burden entry-tier suppliers.
Strategic Opportunities
- India's white-collar expansion:IT/ITES sector growth in Bangalore and Hyderabad creates first-time ergonomic procurement demand among employers without legacy vendor relationships.
- Telehealth workstation assessments:Remote occupational therapy evaluations are expanding addressable reach to home workers outside traditional corporate programs.
- Bluetooth Low Energy convergence:Multi-device pairing protocols enable single-mouse workflows across employer-issued and personal devices, justifying premium positioning.
Industry Challenges
- Occupational therapist certification bottlenecks:Limited numbers of certified ergonomists delay enterprise rollout timelines and fragment purchasing authority across HR, IT, and facilities departments.
- Wireless coexistence testing complexity:Dense 2.4 GHz environments in open-plan offices demand extended RF validation cycles that compress product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Ergonomic Optical Mouse Market |
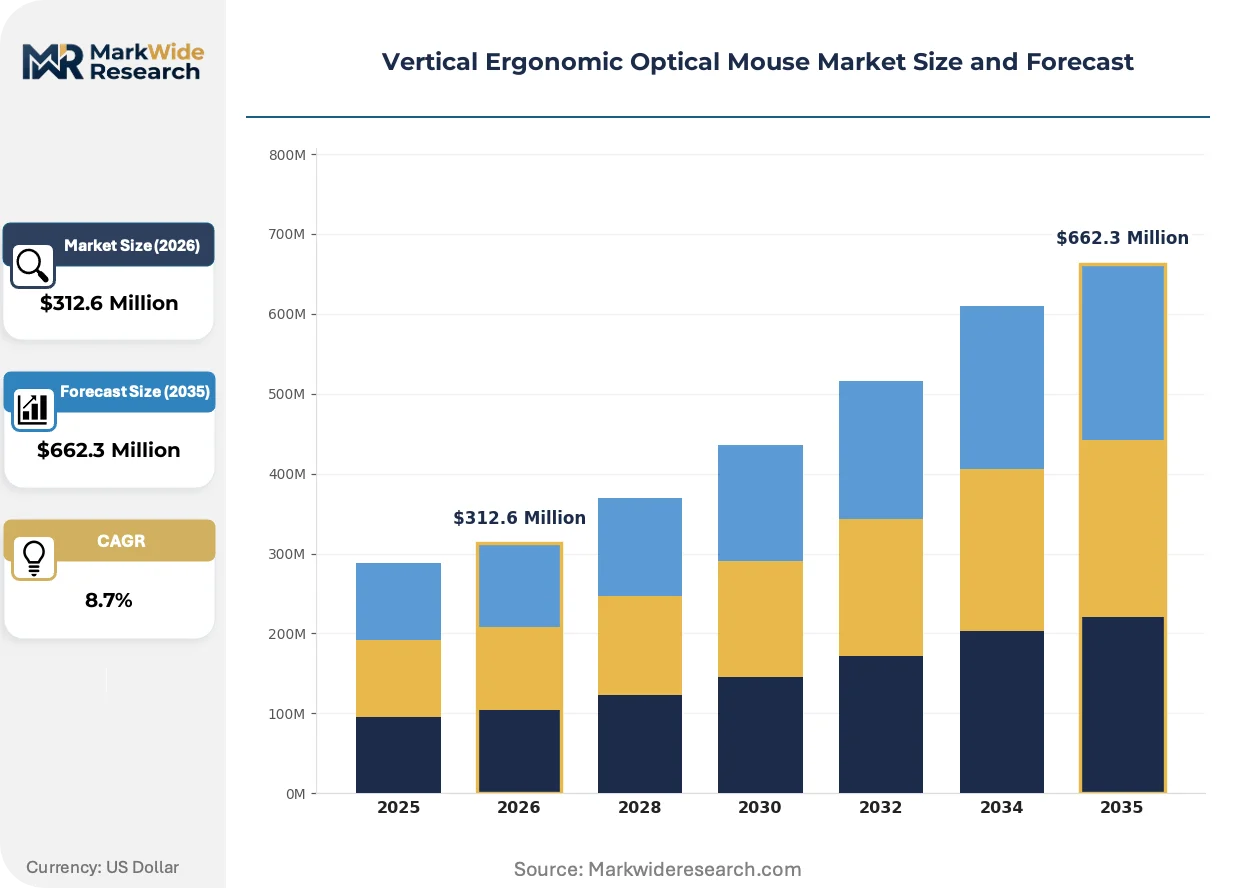
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Rechargeable, Bluetooth End User: Office Workers, Gamers, Graphic Designers, Ergonomics Enthusiasts Size: Small, Medium, Large, Extra Large Feature: Adjustable DPI, Customizable Buttons, Built-in Wrist Support, Color Variants |
| Companies Covered | Logitech, Anker, 3M, Evoluent, R-Go Tools, Microsoft, Goldtouch, Handshoe, Orthovia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Ergonomic Optical Mouse Market Trends and Innovations
Peripheral architecture is fragmenting into interchangeable subsystems, enabling rapid customization without full product redesign and compressing development cycles for specialized ergonomic variants.
Adjustable-angle hinge mechanisms are modularizing vertical mouse construction. Occupational therapists specify precise neutral-handshake angles by patient anthropometrics. Manufacturers now source standardized hinge modules from dedicated motion-component suppliers, collapsing mechanical engineering lead times from months to weeks.
EU Display Screen Equipment directives are tightening documentation requirements for employer-provided peripherals. Compliance officers now demand traceable ergonomic certification rather than marketing claims. German and French enterprise tenders increasingly specify EN ISO 9241-410 test reports as mandatory bid components, filtering uncertified Asian suppliers.
Corporate wellness budgets are absorbing ergonomic peripheral costs that employees previously self-funded. Benefits administrators negotiate volume pricing directly with distributors, bypassing traditional IT channel markups. This concentration is most advanced in United States self-insured employers seeking workers' compensation premium reductions through documented RSI prevention programs.
Vertical Ergonomic Optical Mouse Market Segmentation
Ergonomic peripheral procurement splits sharply between enterprise compliance mandates and individual discretionary purchases. Understanding these segment boundaries clarifies where certification requirements, price sensitivity, and feature prioritization diverge across buyer types.
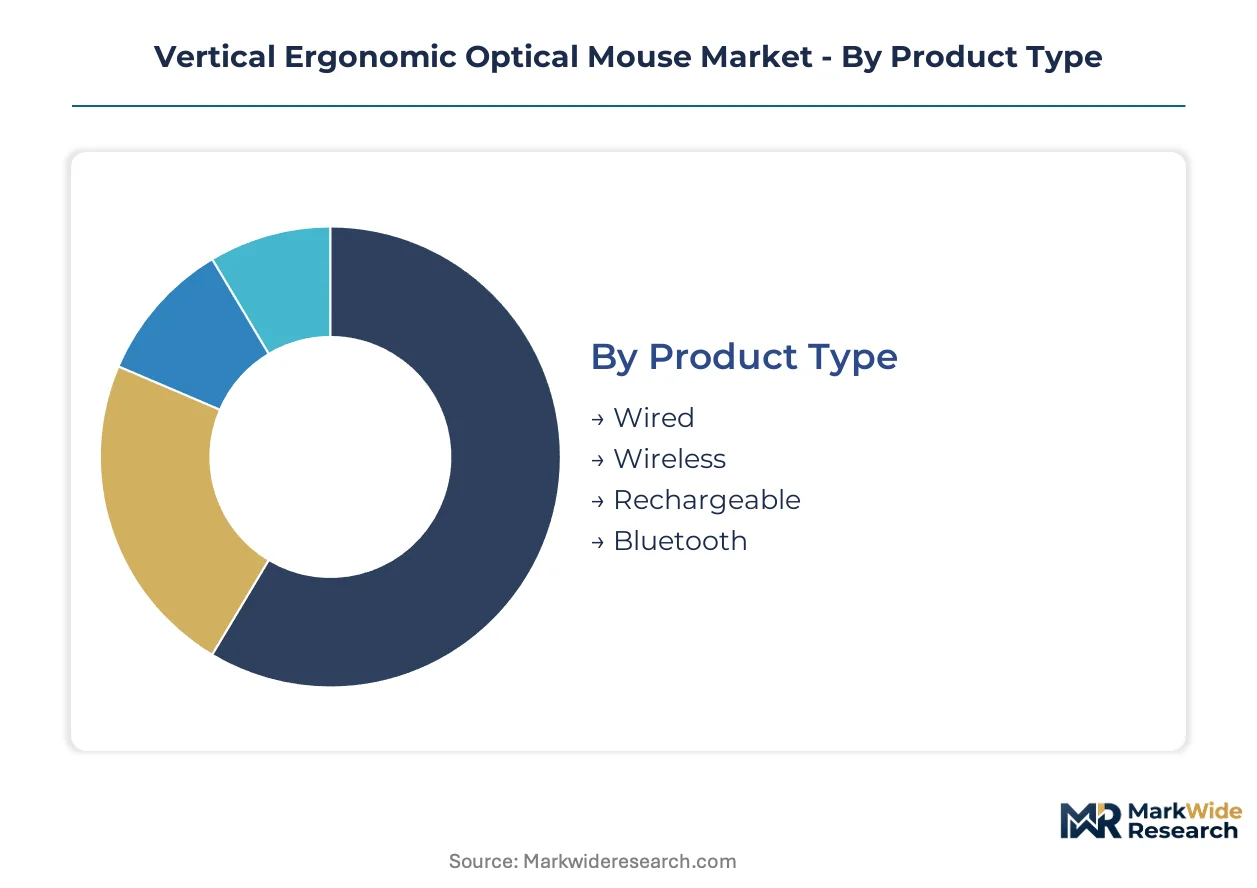
Product Type:
Enterprise IT departments weight total cost of ownership against deployment flexibility when selecting connectivity formats.
- Wired:USB-A and USB-C tethered designs eliminate battery maintenance and RF interference risks. Demand concentrates in government and financial services sectors where cybersecurity protocols restrict wireless transmitters.
- Wireless:2.4 GHz USB dongle configurations dominate hybrid office deployments. United States corporate procurement volume is accelerating as employers fund home-office ergonomic setups with cable-free desk requirements.
- Rechargeable:Lithium-ion powered units with USB-C charging ports reduce long-term operating costs. Sustainability-focused employers in Germany specify these for ESG reporting alignment.
- Bluetooth:Native protocol connectivity enables multi-device pairing without dedicated receivers. Graphic designers and consultants value seamless laptop-to-tablet switching.
Wired leads on scale; Bluetooth leads on momentum.
End User:
Occupational health liability exposure varies dramatically by workforce category, reshaping procurement authority and documentation requirements.
- Office Workers:White-collar employees in insurance, legal, and administrative functions generate baseline volume. OSHA documentation mandates in the United States convert individual purchases into corporate procurement with compliance audit trails.
- Gamers:Esports competitors and streaming content creators prioritize sensor precision and programmable macros. This segment tolerates premium pricing for adjustable DPI ranges matching gaming-grade performance.
- Graphic Designers:Extended daily usage patterns and precision requirements justify premium ergonomic investments. Adobe Creative Cloud professionals in Japan and the United States command highest per-unit spending.
- Ergonomics Enthusiasts:Self-directed consumers researching RSI prevention independently. Online communities and occupational therapist recommendations drive purchase decisions outside employer programs.
Office Workers lead on scale; Graphic Designers lead on momentum.
Size:
Anthropometric matching determines return rates and user satisfaction, particularly in direct-to-consumer channels lacking fitting consultation.
- Small:Compact footprints suit users with hand lengths under 17cm. Asian markets show concentration due to demographic anthropometrics.
- Medium:Universal-fit dimensions accommodate the broadest hand-size distribution. Volume leadership reflects default procurement specifications in enterprise tenders.
- Large:Extended palm support for hand lengths exceeding 19cm. North American and Northern European male-dominated workforces drive demand.
- Extra Large:Maximum contour dimensions for users with hand lengths above 21cm. Niche positioning limits SKU proliferation to specialized ergonomic suppliers.
Medium leads on scale; Small leads on momentum.
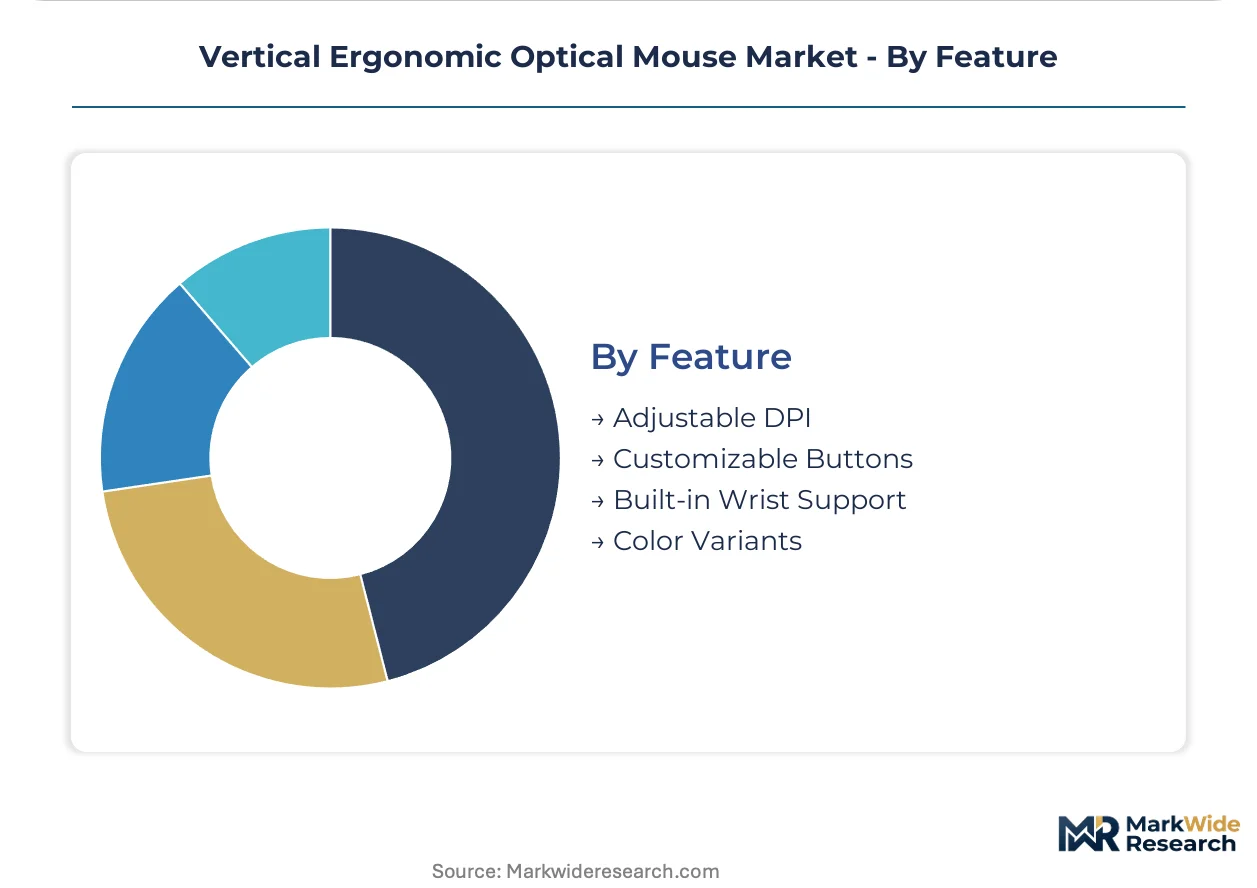
Feature:
Certification-grade functionality separates enterprise-tender winners from consumer-channel competitors.
- Adjustable DPI:Sensor resolution ranging from 800 to 4000+ dots per inch. CAD operators and precision designers require granular control absent in basic office variants.
- Customizable Buttons:Programmable inputs for macros and shortcuts. Workflow automation demands from legal and accounting professionals support premium positioning.
- Built-in Wrist Support:Integrated gel or memory foam pads eliminating separate accessory purchases. Occupational therapists specify these for documented neutral-posture compliance.
- Color Variants:Aesthetic differentiation for consumer and home-office segments. Corporate procurement largely ignores this attribute in favor of standardized fleet deployments.
Adjustable DPI leads on scale; Built-in Wrist Support leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as employers in high-liability jurisdictions fund ergonomic home-office setups while manufacturing concentrates in lower-compliance-cost regions. Compliance documentation requirements now determine market access more than price positioning.
United States
OSHA workplace ergonomics guidelines mandate documented assessments for repetitive strain injury prevention among white-collar workers. Self-insured employers negotiate volume pricing directly with distributors to secure workers' compensation premium reductions. Corporate procurement in California and New York Metro leads hybrid-office ergonomic peripheral deployment.
Germany
EU Display Screen Equipment directives under the European Agency for Safety and Health at Work tighten employer liability for workstation ergonomics. EN ISO 9241-410 test reports now appear as mandatory bid components in enterprise tenders. Industrial concentration in Baden-Württemberg and Bavaria drives premium-tier procurement for precision manufacturing offices.
Japan
The Industrial Safety and Health Act mandates employer-funded workstation assessments for white-collar staff, routing procurement through occupational health departments. Tokyo and Osaka corporate headquarters generate concentrated demand for certified ergonomic peripherals. Local distributors emphasize traceable certification documentation over marketing claims.
India
IT/ITES sector expansion in Bangalore and Hyderabad creates first-time ergonomic procurement demand among employers without legacy vendor relationships. The country's national occupational safety regulator is developing guidelines for computer workstation ergonomics. Multinational back-office operations in Hyderabad and Pune drive standardization around internationally certified peripherals.
United Kingdom
Health and Safety Executive guidance on display screen equipment reinforces employer duty-of-care for home workers. London financial services firms lead compliance-driven procurement with documented audit trails. Corporate wellness budgets in the Southeast absorb ergonomic costs previously self-funded by employees.
Vertical Ergonomic Optical Mouse Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise procurement concentrating around certification-capable suppliers while consumer channels fragment across price-positioned entrants. The vendor base organizes into three tiers: multinational peripheral brands with corporate distribution scale, dedicated ergonomic specialists with occupational therapist relationships, and consumer electronics crossovers leveraging brand recognition. Capacity expansion and strategic partnerships dominate competitive moves as suppliers secure optical sensor and wireless chipset allocations.
Among dedicated ergonomic specialists, Evoluent and R-Go Tools exemplify the certification-focused archetype that dominates occupational therapist recommendations and premium enterprise tenders. Logitech and Microsoft occupy positions at the scale-driven end, leveraging existing corporate IT channel relationships to convert individual discretionary purchases into fleet procurement contracts. Anker represents the consumer electronics crossover segment, extending brand recognition from adjacent categories into entry-level wireless formats.
| Leading Market Players |
|---|
| Logitech |
| Anker |
| 3M |
| Evoluent |
| R-Go Tools |
| Microsoft |
| Goldtouch |
| Handshoe |
| Orthovia |
| Others |
Pricing and Supply Chain Analysis
Optical sensor ICs and Bluetooth SoCs originating from Taiwan and South Korean foundries cascade through three distinct pricing tiers downstream, with enterprise procurement contracts capturing volume discounts unavailable to direct-to-consumer channels.
Pricing Analysis
Distributor margins in corporate IT channels compress pricing by 15-25 percent below retail equivalents for fleet deployments exceeding 500 units. Certification grade and volume scale drive the primary price differentiation, with EN ISO 9241-410 test documentation commanding substantial premiums over uncertified alternatives. Cost compression in the entry-tier wireless segment is intensifying because Anker and consumer electronics crossovers are absorbing margin erosion to build brand recognition. Individual discretionary buyers through Amazon and direct-to-consumer sites exhibit highest price sensitivity, while occupational health departments routing procurement through distributor partnerships show least sensitivity due to compliance mandate urgency.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based optical sensor foundries that dominate precision IC output for adjustable DPI mechanisms. Component sourcing draws from China for injection-molded housings, Vietnam for cable assemblies, and Japan for precision hinge modules. Tariff exposure on Chinese-manufactured plastic subassemblies creates margin pressure for entry-tier suppliers lacking alternative sourcing. Distribution runs through distributor-led corporate IT channels in the United States and Germany, with direct-to-consumer e-commerce capturing residual volume in unregulated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vertical Ergonomic Optical Mouse Market functions as a stable compounder anchored by regulatory mandates that convert employer liability exposure into recurring procurement volume with documented compliance requirements.
For Market Incumbents: Anticipate certification documentation becoming the primary competitive moat as EU Display Screen Equipment directives and OSHA guidelines tighten audit trail requirements. Defensive moves should concentrate on securing EN ISO 9241-410 testing partnerships with German and French laboratories, while adding in-house production of adjustable-angle hinge modules to reduce lead time vulnerability. The emerging threat of telehealth workstation assessment platforms democratizing occupational therapist access demands preemptive channel control through distributor exclusivity arrangements. For New Entrants and Emerging Players: The price-point gap between Evoluent's premium certified tier and Anker's entry-level wireless range offers white-space positioning for mid-tier suppliers bundling basic ergonomic certification with competitive pricing. India's IT/ITES sector expansion in Bangalore and Hyderabad represents the most penetrable geography given absent legacy vendor relationships and developing national ergonomic guidelines. A direct-to-employer go-to-market angle through occupational health departments bypasses crowded IT procurement channels. For Investors and Strategic Acquirers: Roll-up economics work for dedicated ergonomic specialists because occupational therapist recommendation networks create defensible customer acquisition moats resistant to price competition. The five-to-ten year viability window favors certified specialists with established EN ISO 9241-410 documentation capabilities over consumer electronics crossovers dependent on brand recognition alone. The signal to watch is national regulator adoption of employer-funded ergonomic peripheral mandates beyond current United States, Germany, and Japan coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Partnership Expansion | EN ISO 9241-410 testing agreements with German laboratories secure enterprise tender eligibility. |
| Adjustable Hinge Module Integration | Standardized motion-component sourcing collapses mechanical engineering lead times for custom variants. |
| Occupational Health Channel Development | Direct distributor relationships with Japan's occupational health departments bypass fragmented IT procurement. |
| Multi-Device Bluetooth Convergence | Bluetooth Low Energy pairing protocols justify premium positioning for hybrid laptop-tablet workflows. |
| Telehealth Assessment Platform Integration | Remote workstation evaluation partnerships expand addressable reach to unaffiliated home workers. |
Research Methodology
Bottom-up office worker and graphic designer demand modeling reconciled against top-down optical sensor and wireless chipset supply tracking forms the analytical core of this study. Primary interviews with occupational therapists, corporate procurement officers, distributor account managers, and ergonomic product managers combined with secondary validation against OSHA compliance documentation, EU Display Screen Equipment directive filings, and EN ISO 9241-410 test report databases. Customs records for optical sensor IC imports and Bluetooth SoC allocation disclosures from Taiwanese and South Korean foundries provided upstream supply-side anchors.
Input-output matrices mapped connectivity format adoption rates against end-user segment growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, end-user category, hand-size anthropometrics, and certification-grade feature bundling. CAGRs were derived through regression analysis of historical procurement volume against regulatory mandate implementation timelines, with hybrid work permanence and employer liability expansion serving as primary demand-side forecast inputs.
Caveats apply where semiconductor allocation constraints, national regulatory interpretation shifts, or occupational therapist certification bottlenecks could materially shift the outlook. Forecasts reflect documented assumptions regarding employer mandate expansion velocity and wireless protocol adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Portable Smart Speaker Market