
 Global Digital Watch Market | 2026-2036
Global Digital Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Watch Market Foresight
Fragmentation across new buyer segments is repositioning how manufacturers allocate R&D budgets. Apple Inc. leverages its ecosystem lock-in to command premium positioning among tech enthusiasts. Samsung Electronics Co. Ltd. competes through cross-device compatibility and display technology leadership. Garmin Ltd. specializes in GPS-dominant sports watches for athletes demanding ruggedized performance.
Digital watches are electronic timekeeping devices incorporating quartz or microprocessor-controlled movements, typically featuring LCD or LED displays with battery life spanning months to years depending on sensor load. Their primary commercial purpose centers on portable time display augmented by health, communication, or navigation functions. Smartwatches anchor the highest value pool through recurring software revenue and sensor density, while sports watches sustain durable margin structures in outdoor and athletic channels. Fashion watches occupy a mature segment where brand equity and design differentiation determine pricing power against functional alternatives.
The EU Green Deal and REACH framework restrict hazardous substances in watch batteries and casings, compelling manufacturers to reformulate material supply chains. The FCC in the United States and CE marking requirements in Europe govern radio-frequency emissions from Bluetooth and GPS modules, shaping product certification timelines. Japan's METI enforces energy-efficiency benchmarks that influence power-management chip selection. Stakeholders must monitor evolving battery chemistry regulations and wireless protocol standards to preserve market access across jurisdictions.
Market Dynamics
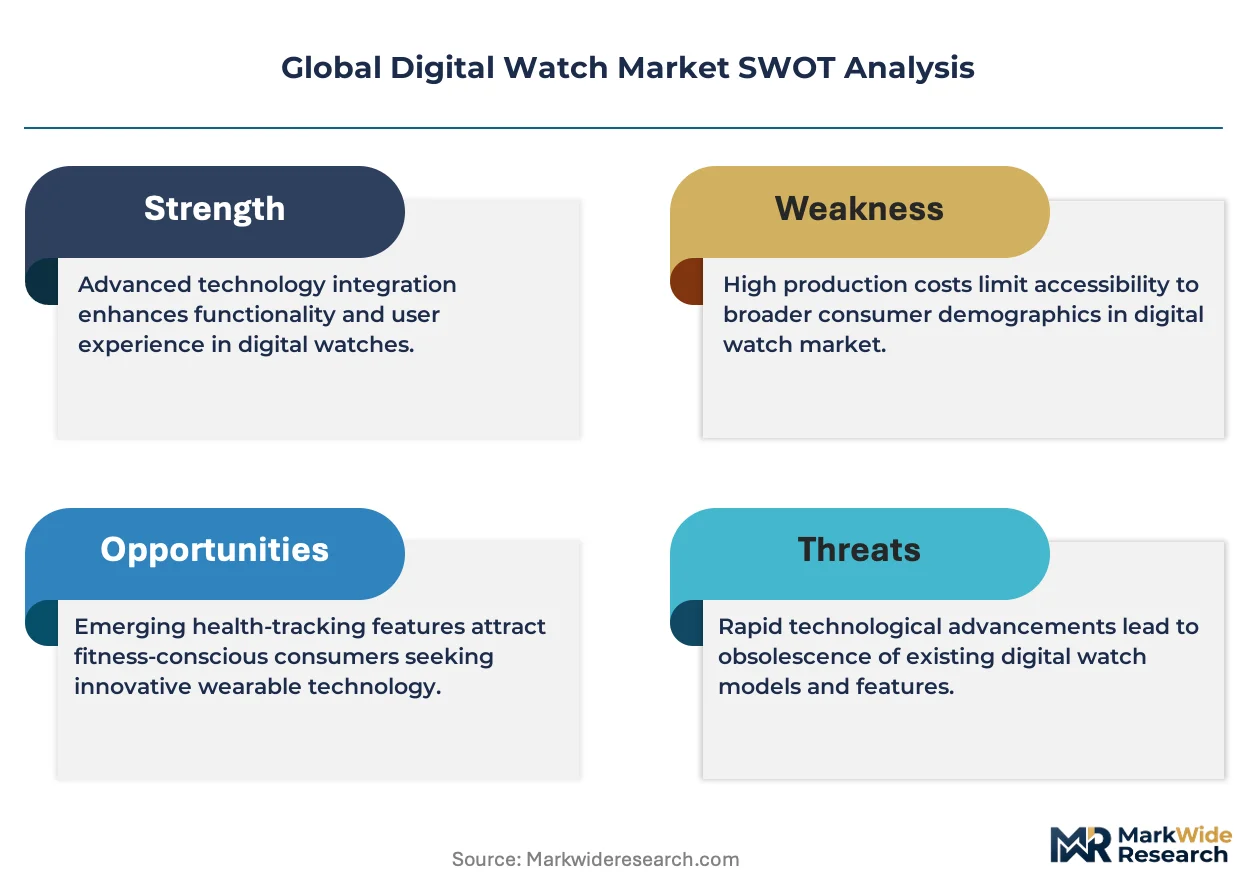
The EU Green Deal's REACH framework is forcing battery chemistry reformulation across supply chains, compressing certification timelines while manufacturers scramble for compliant material substitutes. This regulatory pressure intersects with sensor density demands from health-integrated wearables, creating simultaneous pull and push forces on R&D allocation.
Growth Catalysts
- EU REACH substance restrictions:The EU Green Deal mandates hazardous substance elimination in watch batteries and casings, compelling manufacturers to redesign material supply chains and creating first-mover advantage for compliant producers.
- Fitness tracking among athletes:Sports watches with GPS-dominant functionality command durable margins in outdoor channels, with demand concentrating among endurance athletes and military operators requiring ruggedized performance.
- Japan METI energy-efficiency benchmarks:These standards influence power-management chip selection, driving semiconductor suppliers to optimize for extended battery life in sensor-heavy devices.
Market Restraints
- Lithium supply concentration:Battery chemistry dependence on concentrated upstream mining operations in Chile and Australia creates input cost volatility and geopolitical exposure for watch manufacturers.
- CE marking and FCC certification friction:Radio-frequency emissions testing for Bluetooth and GPS modules extends product launch timelines by four to six months across European and North American markets.
- Smartphone substitution threat:Native timekeeping and basic fitness functions in mobile devices displace entry-level digital watch purchases among price-sensitive consumer segments.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract assembly and component sourcing to Indian facilities, reducing duty exposure for brands serving South Asian demand.
- Remote patient monitoring convergence:FDA-cleared biometric sensors in watches enable reimbursement pathways through US health insurers, expanding beyond consumer discretionary spend.
- Direct-to-consumer channel expansion:Bypassing traditional retail markup through owned e-commerce platforms captures margin and generates first-party data for personalization algorithms.
Industry Challenges
- RF engineering talent scarcity:Miniaturized antenna design for GPS and cellular connectivity competes with smartphone and automotive sectors for specialized electromagnetic simulation expertise.
- Legacy system integration complexity:Enterprise wellness programs require API compatibility with established electronic health record systems, extending sales cycles and technical validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Watch Market |
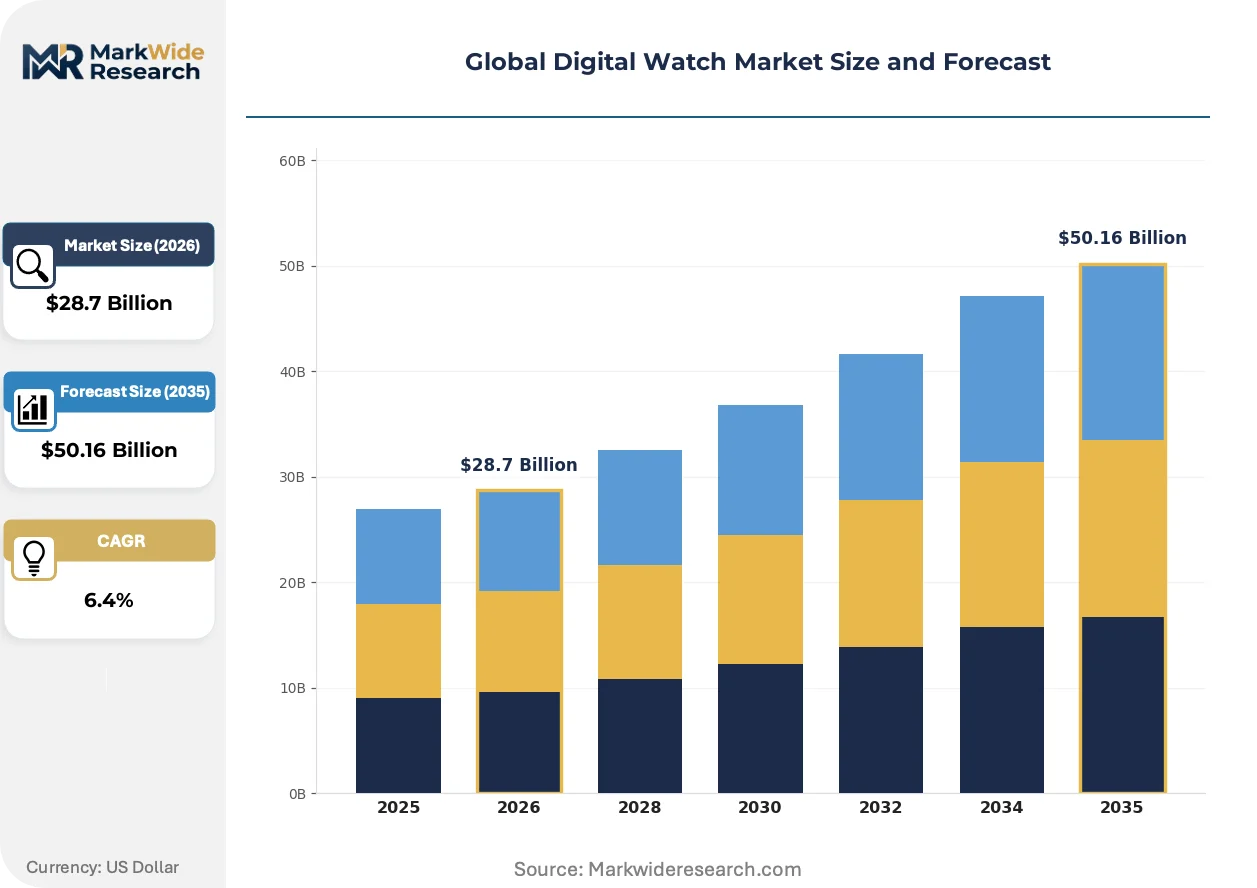
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Chronographs, Sports Watches, Fashion Watches, Casual Watches Technology: GPS, Bluetooth, Heart Rate Sensor, NFC, Accelerometer, Gyroscope Application: Fitness Tracking, Timekeeping, Sleep Monitoring, Notifications, Navigation, Health Monitoring End User: Athletes, Tech Enthusiasts, Fashionistas, Business Professionals, Students |
| Companies Covered | Casio, Fossil Group Inc., Apple Inc., Timex, Seiko, Samsung Electronics Co. Ltd., Fitbit LLC, Citizen, Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Watch Market Shifts & Advancements
Biometric sensor fusion is compressing the gap between consumer wearables and clinical-grade monitoring, while regulatory frameworks accelerate material transparency requirements. These forces are reshaping competitive differentiation from hardware specifications toward data trust and ecosystem integration.
Photoplethysmography with multi-wavelength LED arrays is converging with machine-learning arrhythmia detection, enabling atrial fibrillation screening that previously required dedicated Holter monitors. Cardiology practices in Germany and the United States are piloting prescription workflows for these devices. The structural consequence is convergence with traditional medical device revenue models and FDA 510(k) clearance pathways.
CSRD sustainability disclosure mandates in Europe now require Scope 3 emissions reporting from watch manufacturers, including upstream mining and downstream disposal impacts. This is forcing supply chain visibility investments and material passport documentation. Battery suppliers with certified recycled content are capturing preference in procurement decisions from brands headquartered in France and Switzerland.
After-sales service unbundling is fragmenting the traditional warranty bundle into subscription tiers for advanced analytics and replacement protection. Athletic retailers in Japan and Australia are piloting outcome-based coaching subscriptions tied to device purchase. This model compresses customer lifetime value realization from point-of-sale toward recurring revenue streams with lower churn than hardware replacement cycles alone.
Global Digital Watch Market Segmentation
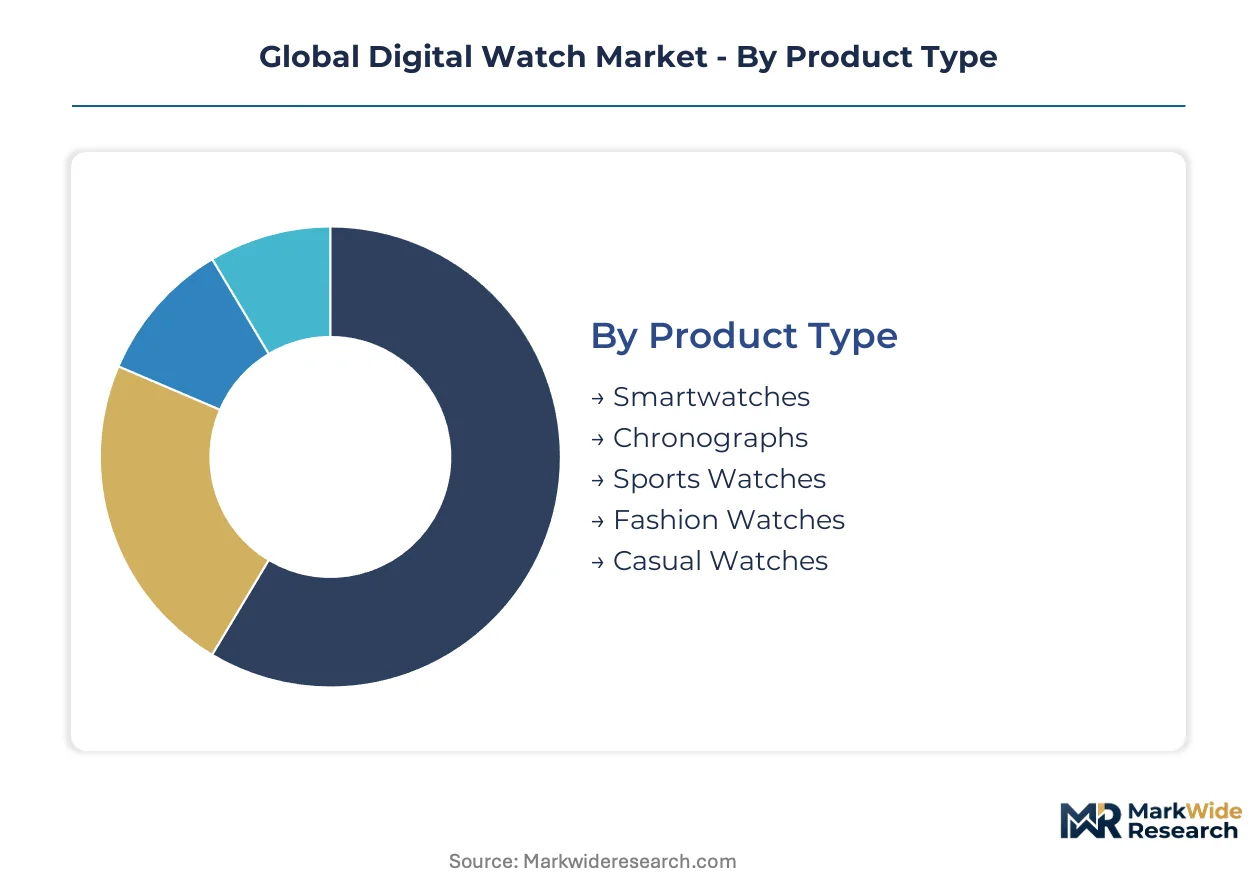
Digital watch segmentation reveals how hardware specifications, connectivity protocols, and user workflows fragment purchasing decisions across price tiers. Manufacturers optimize sensor arrays and power budgets differently for endurance athletes versus clinical monitoring applications.
Product Type:
Display resolution and processing architecture define the cost-performance frontier across wearable form factors.
- Smartwatches:Microprocessor-controlled systems with AMOLED or LTPO displays support third-party applications and cellular connectivity. Demand concentrates among tech enthusiasts in the United States and China who prioritize ecosystem integration over battery longevity.
- Sports Watches:Ruggedized polymer casings with transflective displays optimize GPS acquisition speed and barometric accuracy. Endurance athletes in Germany and Japan drive replacement cycles tied to training seasonality and sensor calibration requirements.
- Chronographs:Hybrid mechanical-digital movements preserve analog aesthetics while adding lap timing and tachymeter functions. Aviation and motorsport enthusiasts sustain niche procurement through specialty retailers.
- Fashion Watches:Minimalist digital modules prioritize slim profiles and interchangeable straps over functional density. Design-led purchasing in France and Italy responds to seasonal color palettes and brand collaborations.
- Casual Watches:Basic LCD timekeeping with alarm and backlight functions serves price-sensitive segments. Volume concentrates in India and Southeast Asia through mass-market retail and promotional bundling.
Mature deployment sits with Casual Watches. Newer deployment is concentrated in Smartwatches.
Technology:
Radio-frequency and MEMS component selection determines certification complexity and battery drain profiles.
- GPS:Multi-constellation receivers (GPS, GLONASS, Galileo, BeiDou) enable precise positioning for route tracking and geofencing. Military operators and trail runners in Switzerland and Australia demand rapid satellite acquisition in dense canopy environments.
- Bluetooth:Low-energy 5.3 protocols sustain smartphone tethering for notification mirroring and firmware updates. Smartphone ecosystem vendors in South Korea and the United States leverage this for cross-device continuity.
- Heart Rate Sensor:Photoplethysmography with green and infrared LEDs enables continuous pulse monitoring. Cardiology validation workflows in Germany and the United States are expanding reimbursement eligibility.
- NFC:Secure element integration supports contactless payment tokenization. Transit authorities in Japan and the United Kingdom have certified wearable form factors for fare gate compatibility.
- Accelerometer:Three-axis MEMS devices detect motion patterns for step counting and fall detection. Elderly care programs in the Netherlands and Singapore are piloting emergency response integration.
- Gyroscope:Angular rate sensors enable gesture recognition and swim stroke detection. Competitive swimmers in Hungary and Brazil use stroke classification for technique analysis.
Bluetooth penetration is deepest in smartphone-dependent workflows. Gyroscope adoption is climbing the fastest among aquatic sports specialists.
Application:
Software functionality stratifies around data export requirements and clinical validation thresholds.
- Fitness Tracking:Calorie estimation and workout classification algorithms process accelerometer and heart rate streams. Gym chains in the United Kingdom and Canada bundle device discounts with membership subscriptions.
- Timekeeping:Atomic clock synchronization via GPS or network time protocols ensures sub-second accuracy. Financial trading floors in London and Tokyo specify this for transaction timestamp compliance.
- Sleep Monitoring:Actigraphy combined with SpO2 and heart rate variability estimates sleep stages. Wellness programs in Sweden and the United States are incorporating this into corporate health incentives.
- Notifications:Haptic alerts for calls, messages, and calendar events reduce smartphone retrieval frequency. Knowledge workers in urban India and the Philippines prioritize this for productivity management.
- Navigation:Turn-by-turn breadcrumb trails and waypoint marking support backcountry travel. Search and rescue volunteers in Norway and New Zealand specify this for offline map reliability.
- Health Monitoring:Atrial fibrillation detection and blood oxygen trending require FDA or CE-marked algorithms. Health insurers in Germany and the United States are exploring risk-adjustment integration.
Timekeeping represents the most mature application layer. Health Monitoring is gaining share fastest as regulatory clearance expands reimbursement pathways.
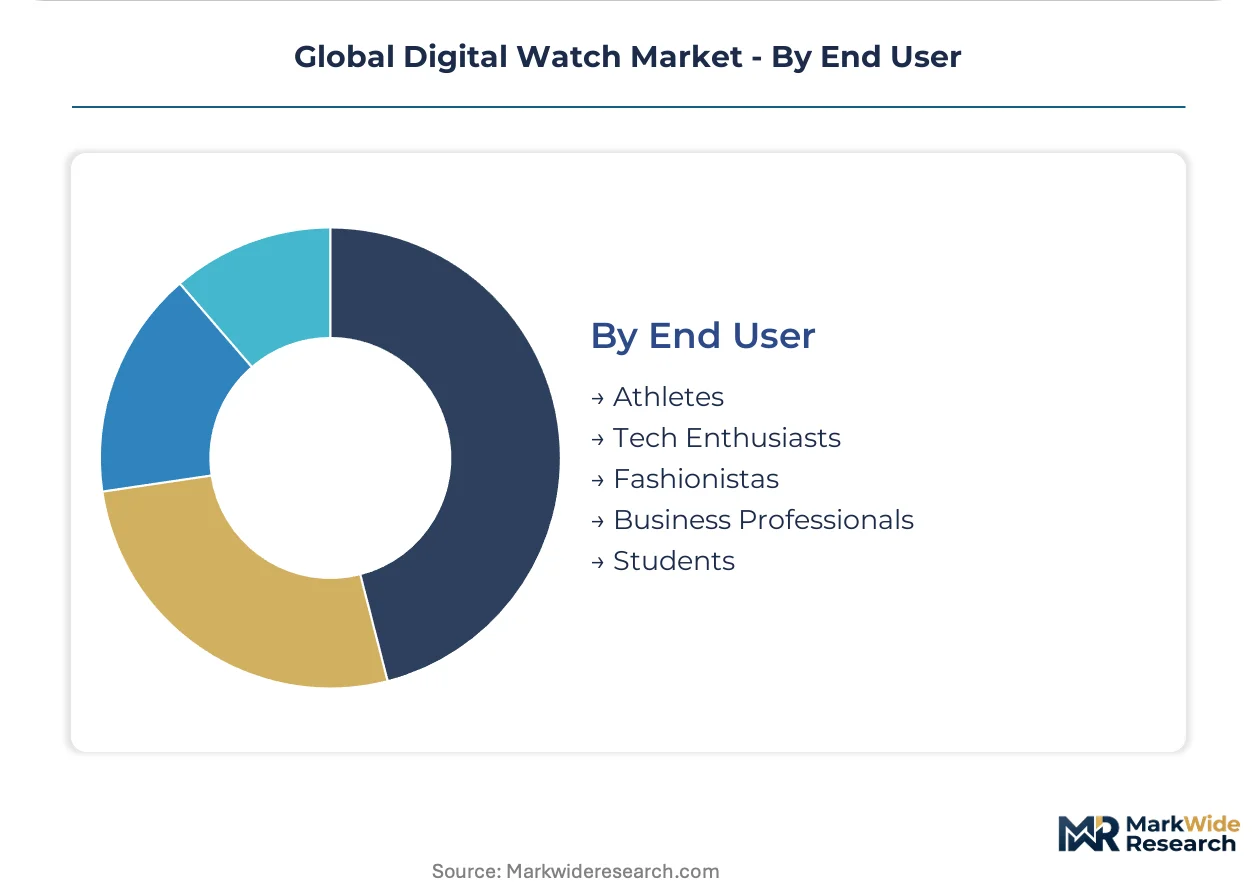
End User:
Purchasing authority and technical sophistication shape feature prioritization and channel preferences.
- Athletes:VO2 max estimation, training load balancing, and recovery metrics dominate specification sheets. Triathlon coaches in Spain and Denmark prescribe device selection based on sport-specific sensor validation.
- Tech Enthusiasts:Developer API access, beta software programs, and customization depth drive brand loyalty. Early adopter communities in California and Shenzhen influence feature roadmaps through feedback channels.
- Fashionistas:Limited edition collaborations, precious metal finishes, and heritage brand licensing command price premiums. Fashion week visibility in Milan and Paris determines seasonal collection success.
- Business Professionals:Calendar integration, silent alarms, and discreet notification filtering support meeting etiquette. Consulting firms in New York and Singapore standardize on compatible fleet deployments.
- Students:Durability, exam-mode functionality, and parental location sharing address academic environment constraints. Back-to-school retail cycles in Mexico and Poland concentrate volume in Q3.
Athletes and Business Professionals anchor replacement-driven revenue. Students represent the steepest expansion trajectory as educational technology budgets incorporate wearable monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for health-integrated wearables concentrates in China, Japan, and the United States as consumers prioritize biometric monitoring. Fitness tracking adoption among endurance athletes drives replacement cycles in Germany and Australia. Regulatory frameworks in the European Union and Japan are reshaping material sourcing and power-management requirements.
United States
Tech enthusiasts and business professionals drive premium smartwatch adoption through ecosystem integration demands. FDA clearance pathways for atrial fibrillation detection expand reimbursement eligibility through health insurers. Silicon Valley hardware startups and established consumer electronics firms cluster in California, advancing photoplethysmography algorithms for clinical-grade monitoring.
China
Domestic brands capture mass-market volume through price-competitive fitness trackers and fashion-forward designs. MIIT enforces GB standards for wireless emissions and battery safety, compressing certification timelines for Bluetooth and GPS modules. Shenzhen's electronics manufacturing corridor hosts assembly operations and MEMS sensor suppliers serving both domestic consumption and export markets.
Japan
Endurance athletes and senior care programs sustain demand for GPS-dominant sports watches and fall-detection wearables. METI energy-efficiency benchmarks influence semiconductor selection for extended battery life in sensor-dense devices. Nagoya's precision manufacturing cluster supplies gyroscope and accelerometer components to domestic watchmakers and export customers.
Germany
Triathlon coaches and cardiology practices prescribe sports watches with validated training metrics and arrhythmia screening. CSRD sustainability disclosure mandates require Scope 3 emissions reporting, forcing supply chain visibility investments. Baden-Württemberg's industrial base hosts battery suppliers with certified recycled content serving French and Swiss watch brands.
India
Students and knowledge workers in urban centers drive entry-level digital watch volume through durability and notification functionality requirements. PLI scheme incentives attract electronics assembly and component sourcing to Indian facilities, reducing duty exposure for brands serving South Asian demand. Maharashtra's manufacturing corridors expand capacity for domestic brands and contract assembly operations.
Global Digital Watch Market Competitive Landscape
United States producers anchor the premium smartwatch tier; Japanese and Swiss specialists hold durable positions in sports and precision segments. The vendor base stratifies across three layers: ecosystem-integrated technology firms, GPS-dominant athletic specialists, and design-led fashion houses. Competitive positioning depends on sensor validation depth, battery chemistry compliance, and direct-to-consumer channel control. M&A activity targets biometric algorithm startups and sustainable material suppliers; geographic expansion focuses on Indian assembly capacity and European regulatory pre-certification.
Within the technology-integrated tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify ecosystem lock-in strategies through cross-device compatibility and display technology leadership. Garmin Ltd. occupies a position among GPS-dominant specialists serving endurance athletes and military operators with ruggedized performance requirements. These three anchors represent divergent competitive archetypes: software-recurring revenue, hardware-display integration, and sensor-validation depth.
| Leading Market Players |
|---|
| Casio |
| Fossil Group Inc. |
| Apple Inc. |
| Timex |
| Seiko |
| Samsung Electronics Co. Ltd. |
| Fitbit LLC |
| Citizen |
| Garmin Ltd. |
| Others |
Supply & Pricing Matrix
Lithium carbonate from Chilean and Australian mining operations flows through three distinct pricing tiers, with battery chemistry costs compressing margins in economy segments while premium brands capture markups through sensor density and ecosystem lock-in.
Pricing Analysis
Volume concentrates in economy-tier casual watches sold through mass retail in India and Southeast Asia, while margins accrue to premium smartwatches with FDA-cleared health algorithms and subscription revenue streams. Price differentiation hinges on clinical validation depth and after-sales service bundling, with certified arrhythmia detection commanding substantial premiums over basic fitness tracking. Pricing pressure stems from smartphone substitution in entry-level segments, where native timekeeping functions displace standalone purchases. Students and price-sensitive consumers in emerging markets exhibit highest sensitivity, while endurance athletes and cardiology-integrated users in Germany and the United States demonstrate lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries fabricating power-management chips for extended battery life, compounded by Japanese suppliers dominating gyroscope and accelerometer MEMS production. Assembly draws from China, Vietnam, and India under PLI incentives, with lithium-ion cells sourced from South Korean and Chinese battery manufacturers. Tariff exposure looms for brands dependent on Chinese component flows into North American and European markets. Distribution runs through athletic specialty retailers in Japan and Australia, direct-to-consumer platforms capturing margin from owned e-commerce, and mass-market electronics chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital watch market occupies a technology-transition phase where photoplethysmography-based arrhythmia detection replaces legacy Holter monitors, forcing manufacturers to navigate FDA clearance pathways and clinical validation workflows.
For Market Incumbents: Acquire biometric algorithm startups with FDA 510(k) clearances to defend against software-defined entrants threatening hardware margins. Deepen backward integration into certified recycled battery supply chains to preempt EU Green Deal compliance costs. Prioritize API compatibility investments with Epic and Cerner electronic health record systems to capture enterprise wellness contract flows.
For New Entrants and Emerging Players: Begin with remote patient monitoring reimbursement pathways in Germany and the United States, where health insurers pilot risk-adjustment integration for FDA-cleared wearables. Target student segments in Indian urban centers through durability-focused positioning and parental location-sharing features. Deploy direct-to-consumer channel architecture to bypass established retail markups and generate first-party training data for personalization algorithms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor sustainable material suppliers with certified recycled content and Scope 3 emissions documentation serving French and Swiss headquarters. Long-term viability centers on convergence with medical device revenue models and recurring software streams rather than hardware replacement cycles. Watch for FDA clearance acceleration signals and health insurer reimbursement policy shifts as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Algorithm Acquisition | FDA-cleared arrhythmia detection enables reimbursement through US health insurers. |
| Recycled Battery Supply Integration | EU Green Deal REACH compliance creates first-mover advantage in European procurement. |
| Direct-to-Consumer Channel Buildout | Owned e-commerce captures margin and generates training data for health algorithms. |
| EHR System API Certification | Epic and Cerner compatibility extends sales cycles into enterprise wellness contracts. |
| Indian PLI Manufacturing Footprint | Production-linked incentives reduce duty exposure for South Asian demand fulfillment. |
Research Methodology
Document review covered SEC filings from wearable technology vendors, FDA 510(k) clearance databases, and EU ECHA REACH substance restriction updates, complemented by interviews with product managers at smartwatch manufacturers, procurement leads at MEMS sensor suppliers, cardiology practice administrators evaluating prescription workflows, and athletic retail category buyers in Japan and Australia. Secondary validation drew from customs trade data for lithium and rare earth imports, IEEE publications on photoplethysmography algorithm development, and METI energy-efficiency benchmark disclosures. Bottom-up unit shipment estimates triangulated against top-down consumer electronics spending data.
Cross-referencing historical replacement cycle patterns with panel input from triathlon coaches and enterprise wellness program directors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity protocol, application workflow, and end-user purchasing authority. CAGRs derived from curve-fitting historical volume trajectories against sensor density adoption curves and regulatory clearance timelines. Industry-specific inputs incorporated Bluetooth 5.3 penetration rates and GPS multi-constellation receiver cost curves.
Underlying measurement precision varies by segment; health monitoring applications with FDA clearance pathways carry tighter precision than fashion watch design-led purchasing. Forecasts reflect assumptions regarding reimbursement policy expansion, battery chemistry substitution timelines, and smartphone substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Phone Tripod Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Tablet Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Smart TV Sticks Market