
 North America Wireless Anc Headphone Market | 2026-2036
North America Wireless Anc Headphone Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireless Anc Headphone Market Insights
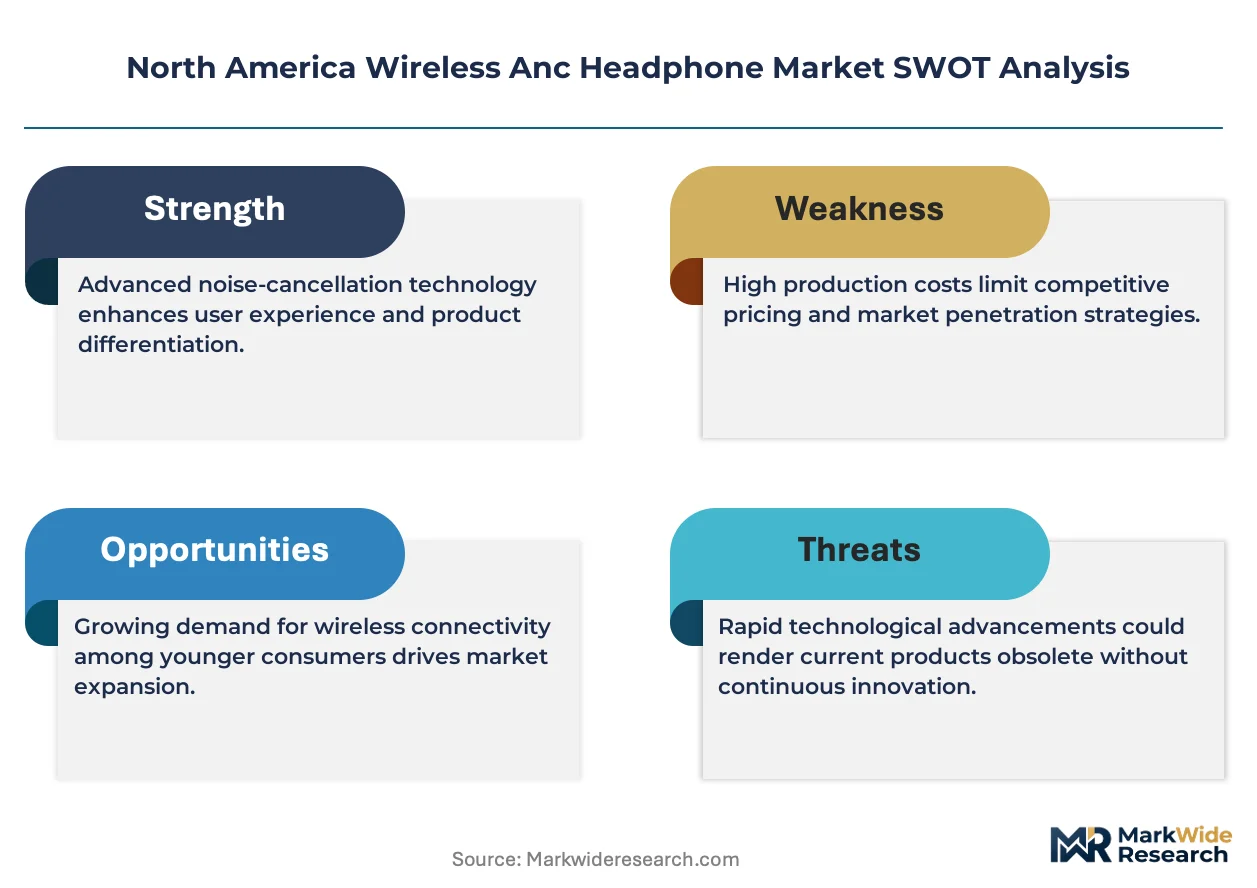
FCC Part 15 certification for unintentional radiators is bifurcating the competitive landscape between established RF engineering houses and newer entrants lacking in-house compliance labs. Apple leverages its custom silicon ecosystem to sustain tight integration between ANC algorithms and proprietary chipsets. Bose Corporation anchors its position through decades of acoustic R&D investment and direct-to-consumer channel control. Sony Corporation competes across price tiers with dual-brand positioning spanning consumer and professional audio segments.
North America wireless ANC headphones are active noise-canceling audio devices that use feedforward and feedback microphone arrays to generate inverse-phase cancellation signals, typically operating over Bluetooth 5.0 or higher protocols with codec support extending to LDAC and aptX Adaptive. The primary commercial purpose is to deliver isolated audio reproduction in high-ambient-noise environments for consumers and enterprise users. Over-ear configurations dominate margin pools due to larger driver enclosures accommodating multiple ANC microphones and extended battery cells, while in-ear formats lead unit velocity through smartphone bundling and gym-centric use cases. The gaming use case segment is expanding fastest as console and PC manufacturers integrate spatial audio APIs that depend on low-latency wireless connectivity.
FCC equipment authorization, OSHA occupational noise exposure guidelines, and California Proposition 65 chemical disclosure requirements collectively shape product design cycles, testing budgets, and packaging compliance across the United States. Health Canada and Industry Canada's radio standards specifications impose parallel but non-identical RF power limits that fragment firmware certification paths for cross-border distribution. Stakeholders must monitor evolving state-level right-to-repair legislation that threatens sealed-unit designs central to current ANC acoustic tuning and moisture protection architectures.
Market Dynamics
Enterprise procurement of ANC headphones for open-plan offices is accelerating across the United States and Canada, reshaping volume concentration away from consumer retail channels toward IT procurement frameworks and bulk corporate licensing agreements.
Growth Catalysts
- OSHA occupational noise exposure guidelines:Employers in manufacturing and logistics verticals are deploying ANC headphones as hearing conservation program components to maintain compliance with permissible exposure limits.
- Bluetooth 5.3 and LE Audio:Broadcast audio capabilities enable seamless multi-device pairing in hybrid work environments, driving refresh cycles in California and New York enterprise corridors.
- Remote-hybrid work policies:Sustained premium audio spending concentrates in metropolitan knowledge-worker clusters where home office setup stipulations include noise-canceling equipment.
Market Restraints
- FCC Part 15 certification complexity:Radio frequency equipment authorization timelines extend product development cycles by four to eight months for unintentional radiator compliance.
- Lithium-ion cell supply concentration:Battery pack sourcing depends on Asian cell manufacturers, exposing North American assemblers to shipping cost volatility and tariff exposure.
- Wired studio monitor substitution:Professional audio engineers in recording and broadcast verticals continue preferring cabled reference headphones for latency-critical monitoring applications.
Strategic Opportunities
- Canadian federal procurement:Health Canada and Industry Canada radio standards create a parallel certification path that rewards early firmware investment with preferential positioning in government telework equipment tenders.
- Gaming and spatial audio convergence:Console manufacturers integrating Microsoft Spatial Sound and Sony Tempest 3D Audio APIs create demand for low-latency wireless ANC headsets with head-tracking sensors.
- State-level right-to-repair legislation:Modular driver and battery architectures that satisfy emerging California and New York repairability mandates will differentiate compliant suppliers from sealed-unit competitors.
Industry Challenges
- Acoustic tuning talent scarcity:Feedforward and feedback microphone array calibration requires specialized DSP engineers concentrated in Boston and San Francisco audio R&D clusters.
- Cross-border firmware fragmentation:Health Canada RSS-247 power limits differ from FCC Part 15 specifications, forcing dual certification tracks for unified North American product SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireless Anc Headphone Market |
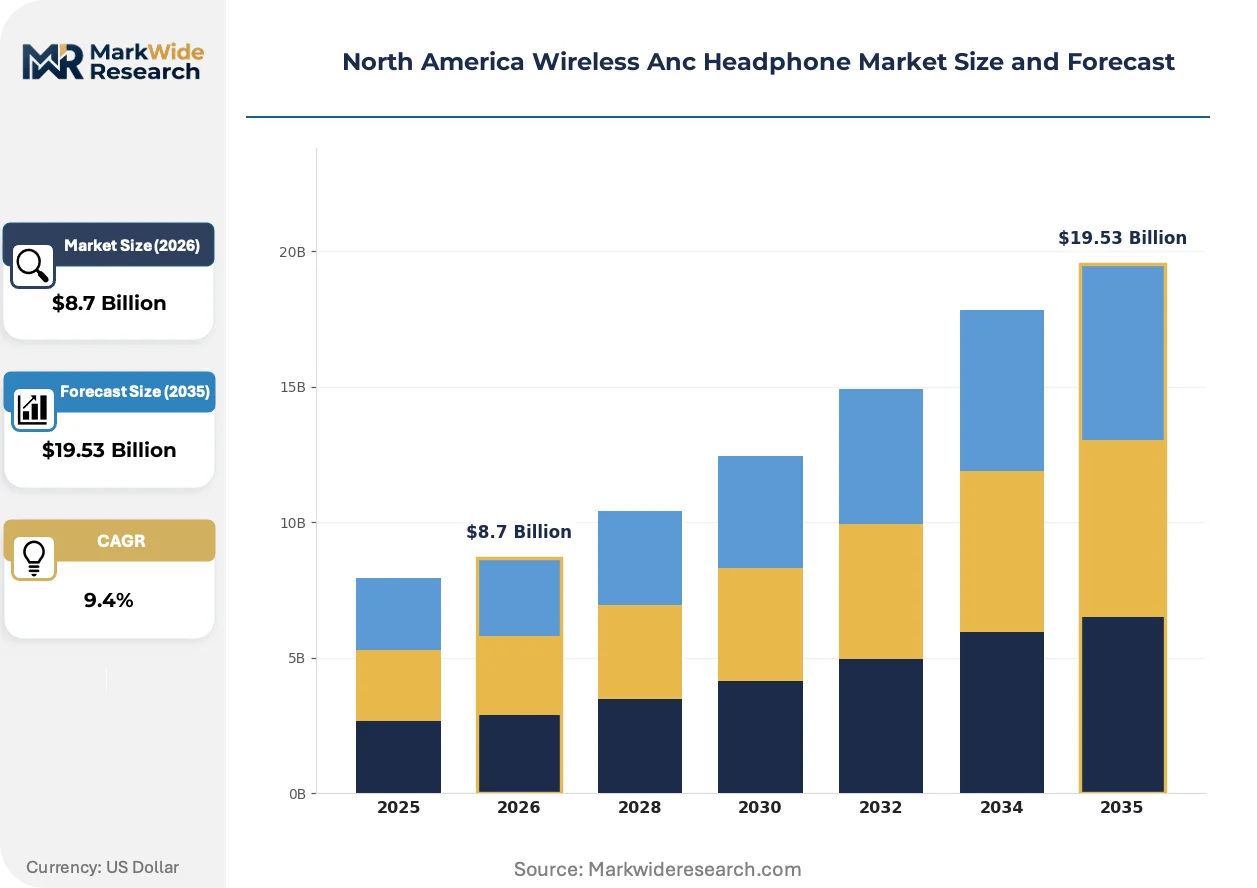
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-Ear, In-Ear, On-Ear, Neckband Use Case: Travel, Work, Sports, Gaming Connectivity: Bluetooth, NFC, Wired, Auxiliary Market Segment: Consumer Electronics, Professional Audio, Education, Corporate |
| Companies Covered | Apple, Bose Corporation, Sony Corporation, Beats, Samsung Electronics, Harman International, Sennheiser, JBL, Anker, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireless Anc Headphone Market Trends and Innovations
Adaptive ANC algorithms that respond to environmental acoustic profiles in real time are compressing the performance gap between premium and mid-tier product tiers across North American distribution channels.
On-device machine learning inference for personalized noise cancellation is displacing static filter banks that previously required manual profile selection. Enterprise IT buyers in financial services and legal verticals are specifying adaptive ANC as a standard procurement requirement. This capability compression is eroding margin premiums for legacy fixed-coefficient ANC implementations.
FCC equipment authorization requirements for radio frequency devices continue to shape product compliance timelines, with Part 15 Subpart B testing for unintentional radiators now mandatory for all Bluetooth audio peripherals. Manufacturers are front-loading RF engineering resources to prevent certification delays that compress holiday season launch windows. The gaming headset segment bears the highest compliance burden due to simultaneous 2.4 GHz and 5 GHz radio operation.
Corporate audio procurement is consolidating around IT-managed device programs that bundle ANC headphones with laptop and smartphone refresh cycles. Direct-to-consumer retail in urban flagship locations is losing volume to enterprise channel partners and carrier subsidy programs. This shift is most visible in Seattle and Toronto technology corridors where hybrid work policies have normalized equipment stipend models.
North America Wireless Anc Headphone Market Segmentation
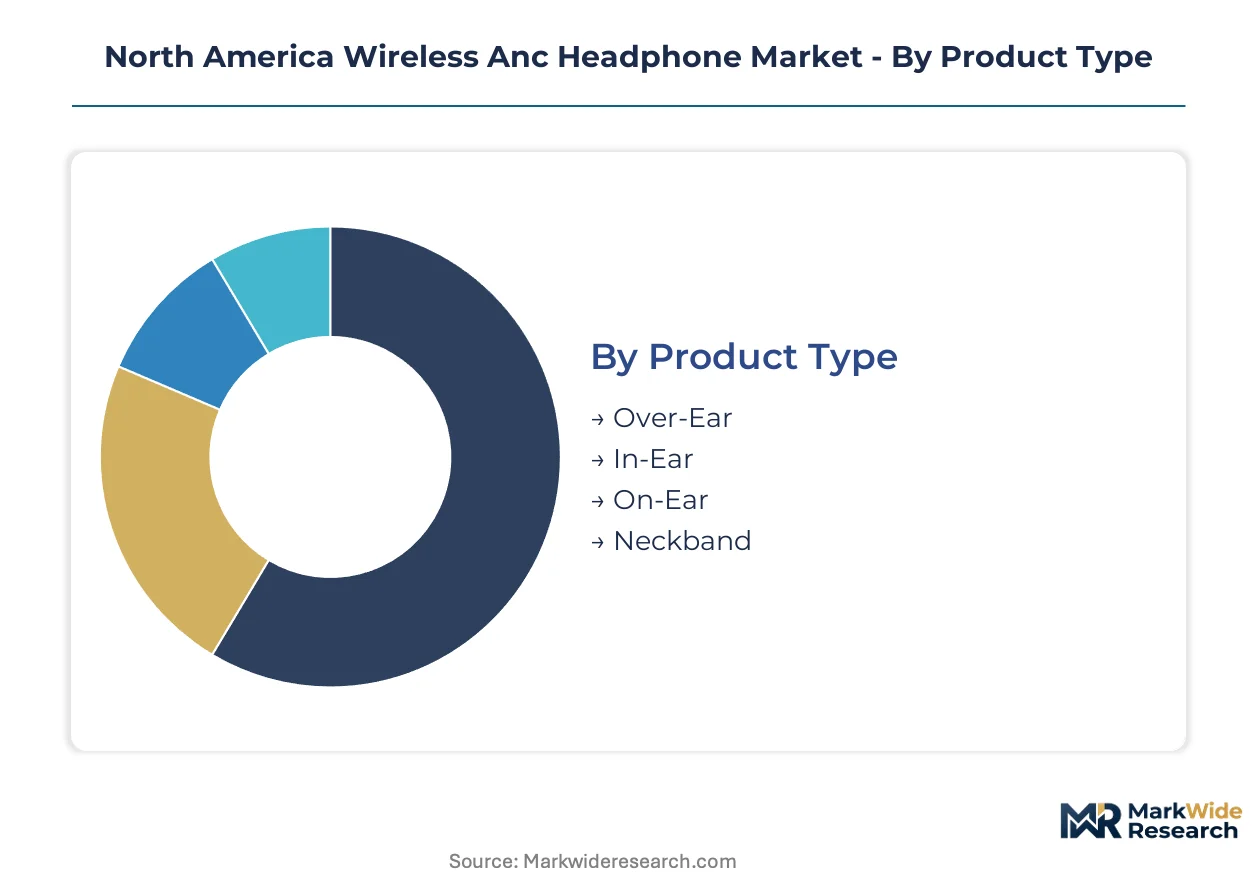
Segmentation in North American wireless ANC headphones reveals how substitution pressures from wired monitors and open-ear alternatives reshape competitive intensity across form factors. Distinct technical specifications, certification burdens, and procurement channels create divergent margin profiles that reward precise positioning.
Product Type:
Over-ear configurations face the strongest substitution threat from professional wired studio monitors in recording and broadcast verticals, while in-ear formats compete against smartphone-bundled alternatives and open-ear bone conduction devices.
- Over-Ear:Large driver enclosures accommodate multiple ANC microphones, extended battery cells, and spatial audio processing hardware. Demand concentrates in California and New York enterprise corridors where IT procurement frameworks specify premium noise-canceling equipment for open-plan offices and hybrid work stipends.
- In-Ear:Compact form factors rely on feedforward microphone arrays and smaller driver diameters, trading acoustic isolation for portability. Unit velocity leads through gym-centric use cases and smartphone bundling agreements with carriers in Seattle and Toronto technology clusters.
- On-Ear:Intermediate driver sizing appeals to commuters seeking lighter weight than over-ear designs without the insertion fatigue of in-ear models.
- Neckband:Collar-mounted electronics enable longer battery life than true wireless alternatives, retaining niche traction among warehouse and logistics workers requiring all-day wearability.
In-ear retains volume leadership; gaming-optimized over-ear configurations hold the steepest expansion curve.
Use Case:
Application-based segmentation tracks how FCC Part 15 certification complexity and latency requirements fragment procurement channels across consumer and enterprise buyers.
- Travel:Premium ANC algorithms tuned for aircraft cabin noise profiles dominate this segment, with feedforward microphone arrays optimized for repetitive low-frequency engine drone.
- Work:Enterprise IT buyers in financial services and legal verticals specify adaptive ANC and multi-device Bluetooth 5.3 pairing as standard requirements, consolidating procurement around laptop refresh cycles.
- Sports:Sweat resistance ratings and secure fit mechanisms prioritize gym and outdoor use cases, competing against open-ear alternatives that preserve situational awareness.
- Gaming:Low-latency 2.4 GHz wireless connectivity, head-tracking sensors, and spatial audio API integration drive the fastest expansion as console manufacturers deploy Microsoft Spatial Sound and Sony Tempest 3D Audio.
Work applications anchor revenue concentration; gaming exhibits the most rapid share gains.
Connectivity:
Protocol selection determines RF engineering investment, certification timeline exposure, and compatibility with enterprise device management systems.
- Bluetooth:Bluetooth 5.3 and LE Audio broadcast capabilities now dominate North American distribution, enabling seamless multi-device pairing that IT departments prioritize for hybrid work environments.
- NFC:Tap-to-pair functionality accelerates deployment in corporate settings where non-technical users require simplified onboarding workflows.
- Wired:USB-C and 3.5mm analog connections persist in latency-critical professional audio monitoring and aviation applications where RF interference is prohibited.
- Auxiliary:Analog input compatibility retains relevance for legacy aircraft entertainment systems and enterprise telephony infrastructure with proprietary jack standards.
Bluetooth commands volume leadership; LE Audio-equipped variants climb the fastest.
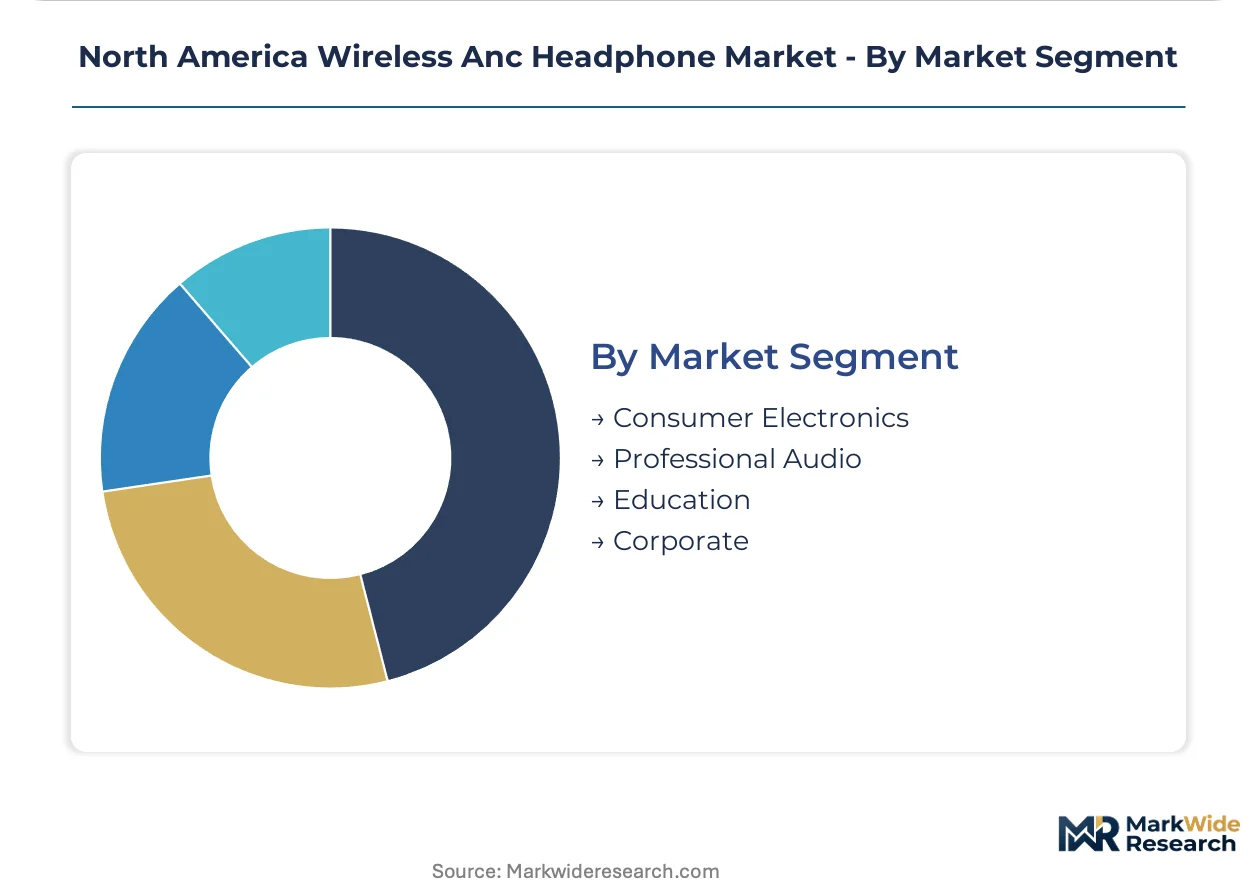
Market Segment:
Customer-type segmentation exposes how procurement authority shifts from consumer retail to IT-managed device programs and government tenders.
- Consumer Electronics:Direct-to-consumer retail in urban flagship locations is losing volume to carrier subsidy programs and bundling agreements, though premium tier spending sustains in metropolitan knowledge-worker clusters.
- Professional Audio:Recording engineers and broadcast technicians continue preferring cabled reference headphones for latency-critical monitoring, constraining wireless ANC penetration in this segment.
- Education:K-12 and university procurement frameworks are standardizing ANC headphones for standardized testing and remote learning equity programs, particularly in California and Texas districts.
- Corporate:Bulk licensing agreements and equipment stipend models now dominate volume concentration, with OSHA hearing conservation program compliance driving manufacturing and logistics vertical deployment.
Corporate procurement retains volume leadership; education exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles and Long Beach container complex anchors trans-Pacific electronics distribution, funneling ANC headphone components into North American assembly networks. Interstate rail corridors and the NAFTA-era highway grid enable rapid inland distribution to enterprise procurement hubs and consumer retail clusters.
United States
Enterprise IT procurement in California and New York metro corridors drives bulk licensing agreements for hybrid work equipment. FCC Part 15 certification timelines extend product development cycles by four to eight months for Bluetooth audio peripherals. Boston and San Francisco acoustic R&D clusters concentrate feedforward microphone array calibration talent for adaptive ANC algorithms.
Canada
Government telework equipment tenders in Ottawa and Toronto create preferential positioning for early firmware investors meeting Health Canada RSS-247 power limits. Industry Canada radio standards specifications impose parallel but non-identical RF power limits that fragment certification paths. Vancouver technology corridors sustain premium audio spending through equipment stipend models.
Mexico
Manufacturing assembly for North American distribution concentrates in Baja California and Chihuahua border zones near US logistics hubs. Mexican federal procurement frameworks for education technology are standardizing ANC headphones for remote learning equity programs. Guadalajara electronics clusters are developing component sourcing relationships with Asian battery cell suppliers.
North America Wireless Anc Headphone Market Competitive Landscape
Listed leaders compete with private specialists across acoustic R&D depth and direct-to-consumer channel control. The vendor base fragments across three tiers: integrated ecosystem operators with custom silicon, dedicated audio houses with decades of feedforward microphone investment, and smartphone OEMs leveraging bundling scale. Strategic archetypes include ecosystem-locked premium positioning, dual-brand consumer-professional spanning, and carrier-subsidized volume penetration. Competitive moves concentrate on RF engineering talent acquisition and adaptive algorithm licensing.
Within the ecosystem-locked tier, Apple exemplifies tight integration between ANC algorithms and proprietary chipsets. Bose Corporation anchors dedicated audio house positioning through acoustic R&D heritage. Sony Corporation occupies dual-brand territory spanning consumer electronics and professional monitoring segments.
| Leading Market Players |
|---|
| Apple |
| Bose Corporation |
| Sony Corporation |
| Beats |
| Samsung Electronics |
| Harman International |
| Sennheiser |
| JBL |
| Anker |
| Others |
Pricing and Supply Chain Analysis
LDAC and aptX Adaptive codec licensing displacing SBC baseline codecs is compressing margin pools for mid-tier assemblers while rewarding vertically integrated chipset houses with captive IP. This substitution dynamic simultaneously redraws component sourcing maps toward Taiwan and South Korea foundries and erodes pricing power for firmware-dependent differentiation.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement frameworks, with IT-managed device programs commanding 30-40% unit price reductions against direct-to-consumer retail. Pricing stratifies across premium adaptive ANC implementations, standard fixed-coefficient architectures, and economy Bluetooth-only configurations. Cost compression in the standard tier intensifies as adaptive algorithms migrate downward. Corporate buyers exhibit lowest price sensitivity due to OSHA compliance mandates, while education procurement shows highest elasticity.
Supply Chain Analysis
Strait of Malacca transit congestion exposes lithium-ion cell shipments from South Korea and Japan to North American assembly plants in Baja California and Chihuahua. Battery pack production draws from Chinese cathode material suppliers and Japanese electrolyte specialists. Single-source vulnerability concentrates in ANC DSP silicon from Taiwan foundries. Distribution runs through Port of Los Angeles-Long Beach container terminals into interstate rail corridors serving Seattle and Toronto technology clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedforward microphone array calibration expertise scarcity constrains product development velocity, with Boston and San Francisco R&D clusters capturing premium talent rents. This capability gap favors incumbents with embedded acoustic engineering benches.
For Market Incumbents: Shield proprietary ANC algorithm portfolios through selective licensing enforcement against smartphone OEM bundling encroachment. Deepen backward integration into custom silicon development to escape commoditized Bluetooth controller sourcing. Prioritize FCC pre-certification investment to compress holiday launch windows against Asian challenger brands. For New Entrants and Emerging Players: FCC Part 15 expedited review programs offer the fastest certification pathway for gaming-optimized over-ear configurations with simultaneous 2.4 GHz and 5 GHz radios. White-space concentrates in Canadian federal telework tenders where Health Canada RSS-247 compliance creates first-mover positioning. Channel through IT procurement frameworks rather than retail flagships to bypass incumbent shelf dominance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed acoustic engineering boutiques in Boston and San Francisco lacking enterprise channel scale. Long-term viability hinges on adaptive algorithm IP durability against on-device machine learning displacement. Monitor state-level right-to-repair legislative passage as inflection signal for modular architecture valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive ANC Algorithm Licensing | Enables mid-tier brands to close performance gaps with Bose and Sony flagship implementations. |
| Dual Certification Investment | Simultaneous FCC Part 15 and Health Canada RSS-247 approval unlocks preferential government tender positioning. |
| Gaming-Optimized SKU Development | Low-latency 2.4 GHz integration with Microsoft Spatial Sound API captures fastest-expanding use case segment. |
| Enterprise Channel Partnership | IT-managed device program inclusion secures volume concentration away from declining retail flagships. |
| Modular Architecture Transition | Repairable driver and battery designs preempt California and New York right-to-repair compliance mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with ANC engineering directors, enterprise IT procurement officers, FCC compliance consultants, and carrier device portfolio managers; and secondary validation against SEC 10-K filings, FCC equipment authorization databases, Health Canada radio standards bulletins, and enterprise procurement framework disclosures. Bottom-up unit shipment estimates triangulated against top-down consumer electronics spending allocation models.
The forecasting boundary spans the analysis window with annual granularity across product type, use case, connectivity protocol, and market segment dimensions. CAGRs derived from logistic adoption curve fitting for Bluetooth 5.3 and LE Audio penetration rates, cross-referenced against OSHA hearing conservation program deployment timelines and gaming console refresh cycles.
Decision-makers should treat outputs as directional under sustained remote-hybrid work policy assumptions; material deviation in enterprise equipment stipend prevalence would warrant model refresh. Practitioners should keep alternative scenarios live as lithium-ion cell tariff exposure and right-to-repair legislative passage evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Smart Speaker Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
North America Smartphone Accessories Market