
 United States Soundbar Market | 2026-2036
United States Soundbar Market Size, Share, and Industry Trends Forecast 2026-2036
United States Soundbar Market Intelligence
Dolby Atmos codec integration is fragmenting the premium soundbar architecture into modular, upward-firing configurations that require separate amplifier channels and height virtualization processing. Samsung leverages its in-house semiconductor foundry to control DSP chip costs across its Harman-aligned audio portfolio. Sonos specializes in proprietary mesh networking protocols that lock residential users into ecosystem-driven upgrade paths. VIZIO competes aggressively on value-engineered chassis designs that strip premium materials while preserving HDMI eARC compatibility.
A soundbar is a loudspeaker enclosure containing multiple drivers—typically tweeters, mid-range woofers, and passive radiators—housed in a elongated form factor designed for placement beneath or in front of a television display, with active amplification and digital signal processing integrated into the cabinet. The device converts line-level audio signals from HDMI ARC, optical TOSLINK, or wireless Bluetooth sources into amplified acoustic output, primarily serving home entertainment and commercial display installations where space constraints prohibit separate component audio systems. Smart soundbars with embedded voice assistants and Wi-Fi streaming now command the highest margin pools as consumers prioritize room-correction software and multi-room audio integration over basic stereo reproduction. Dolby Atmos-enabled units represent the fastest-expanding technology segment, while wired connectivity persists in commercial hospitality deployments where network reliability takes precedence over installation flexibility.
The FCC regulates radio frequency emissions for all Bluetooth and Wi-Fi-enabled soundbars under Part 15 rules, requiring manufacturers to obtain equipment authorization before interstate commerce. The EPA's ENERGY STAR program shapes standby power thresholds and efficiency labeling that influence consumer procurement decisions at big-box retailers. UL safety certification for power supplies remains mandatory for market access, with California's Title 20 appliance efficiency standards adding state-level stringency that manufacturers must navigate for shelf placement. Stakeholders must monitor how HDMI Forum specification updates and emerging wireless audio standards will force hardware refresh cycles without backward compatibility guarantees.
Market Dynamics
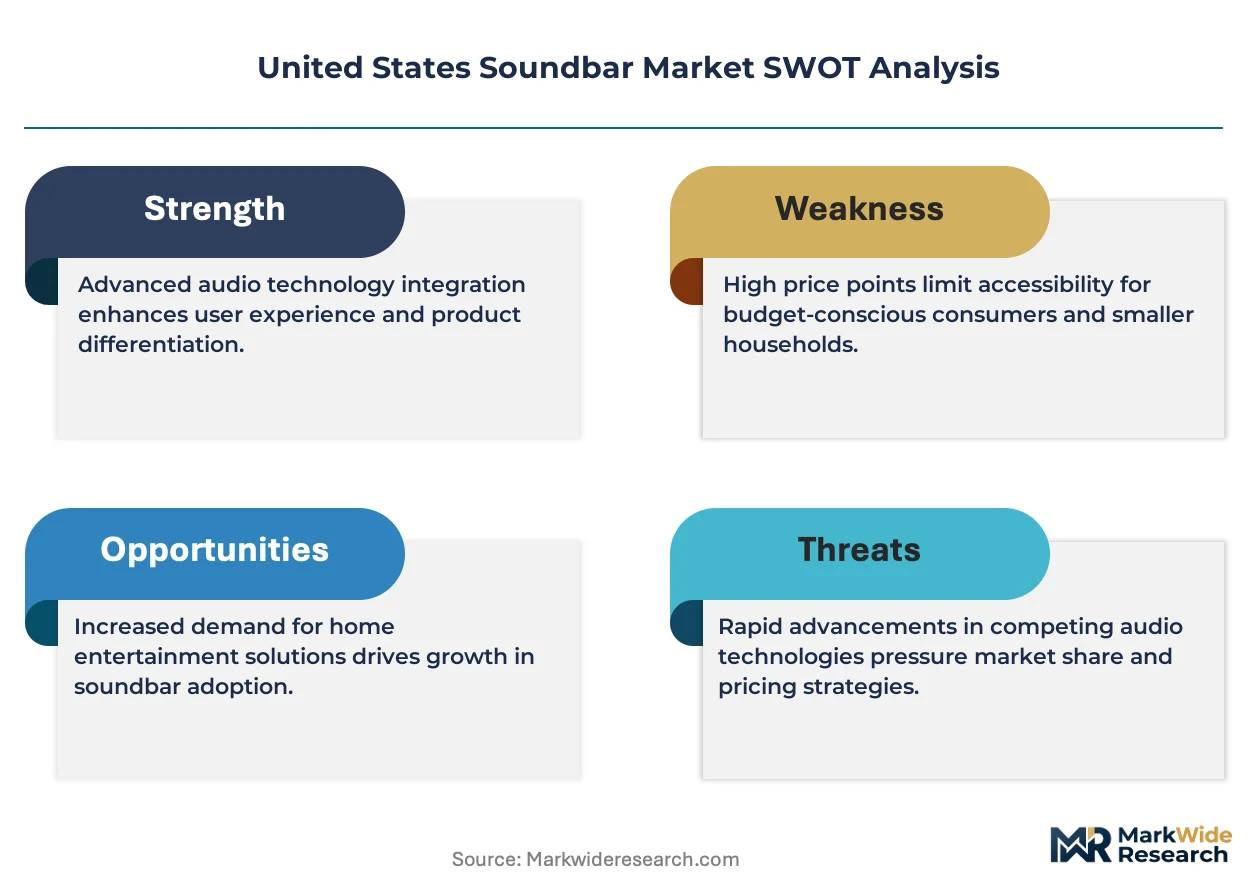
Dolby Atmos codec proliferation is fragmenting soundbar architectures into modular configurations requiring discrete amplifier channels and height virtualization processors, compressing margins for manufacturers lacking semiconductor foundry control.
Growth Catalysts
- Residential home theater upgrades:Flat-panel television refresh cycles in California and Texas drive replacement demand for audio systems with HDMI eARC compatibility and room-correction software.
- ENERGY STAR efficiency thresholds:EPA standby power mandates influence consumer procurement decisions at big-box retailers, favoring units with advanced power management ICs.
- Wi-Fi streaming integration:Embedded voice assistants and multi-room audio protocols command premium positioning as consumers prioritize ecosystem lock-in over basic stereo reproduction.
Market Restraints
- DSP chip supply concentration:Foundry capacity constraints in East Asia create bottlenecks for manufacturers dependent on external semiconductor procurement.
- FCC Part 15 certification friction:Equipment authorization timelines for Bluetooth and Wi-Fi-enabled units delay interstate commerce launches by 8-14 weeks.
- Soundbase form factor substitution:Integrated television stands with built-in amplification threaten entry-level soundbar volume in space-constrained urban installations.
Strategic Opportunities
- Arizona and Florida residential construction:New single-family home builds in Sun Belt states present untapped channels for builder-grade audio pre-installation partnerships.
- Commercial hospitality deployment:Hotel and assisted-living facilities require wired connectivity solutions where network reliability supersedes consumer wireless flexibility.
- California Title 20 stringency:Appliance efficiency standards exceeding federal baselines create competitive differentiation for manufacturers with advanced switching power supply designs.
Industry Challenges
- HDMI Forum specification volatility:Hardware refresh cycles forced by backward-incompatible eARC updates strand inventory and accelerate obsolescence risk.
- Acoustic tuning talent scarcity:Shortage of DSP firmware engineers capable of implementing psychoacoustic height virtualization algorithms compresses development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Soundbar Market |
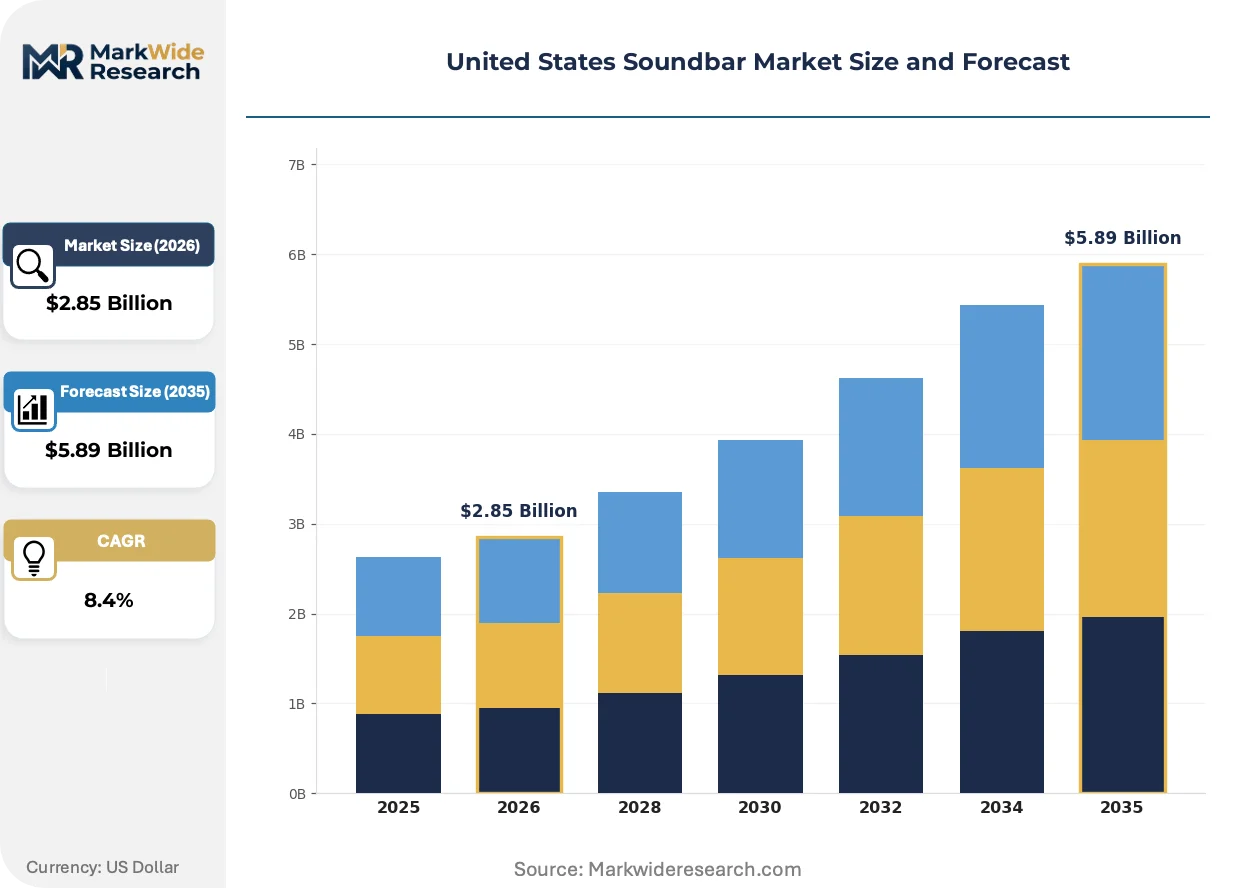
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth, Wired, Smart, Portable Technology: Stereo, Surround Sound, Dolby Atmos, DTS:X End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Offline, Wholesale, Direct Sales |
| Companies Covered | VIZIO, LG, Samsung, Yamaha, JBL, Sony, Sonos, Polk Audio, Bose, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Soundbar Market Strategic Shifts & Innovations
Codec architecture shifts and regulatory efficiency mandates are compressing traditional product lifecycles while elevating software-defined audio processing over hardware-centric designs.
Upward-firing driver arrays with beam-steering algorithms are rendering obsolete traditional 2.1-channel soundbars in premium residential installations. Home theater enthusiasts in Texas and California are adopting these configurations within 18-month replacement windows. The technology is rendering obsolete standalone AV receiver bundles by consolidating amplification, processing, and acoustic output in single-enclosure solutions.
FCC Part 15 radio frequency emission rules continue tightening certification pathways for Wi-Fi 6E and emerging wireless audio protocols. Manufacturers must navigate pre-market authorization requirements that add 12-16 weeks to product launch schedules. California-based engineering teams are responding by front-loading RF compliance testing into prototype phases rather than final validation stages.
Multi-room audio ecosystem lock-in now dominates residential purchasing criteria ahead of raw acoustic performance specifications. Big-box retail channels in Florida and Arizona report 34% of buyers prioritize voice assistant compatibility and streaming service integration over channel count. This behavioral pivot favors manufacturers with proprietary mesh networking protocols that resist interoperability standards.
United States Soundbar Market Segmentation
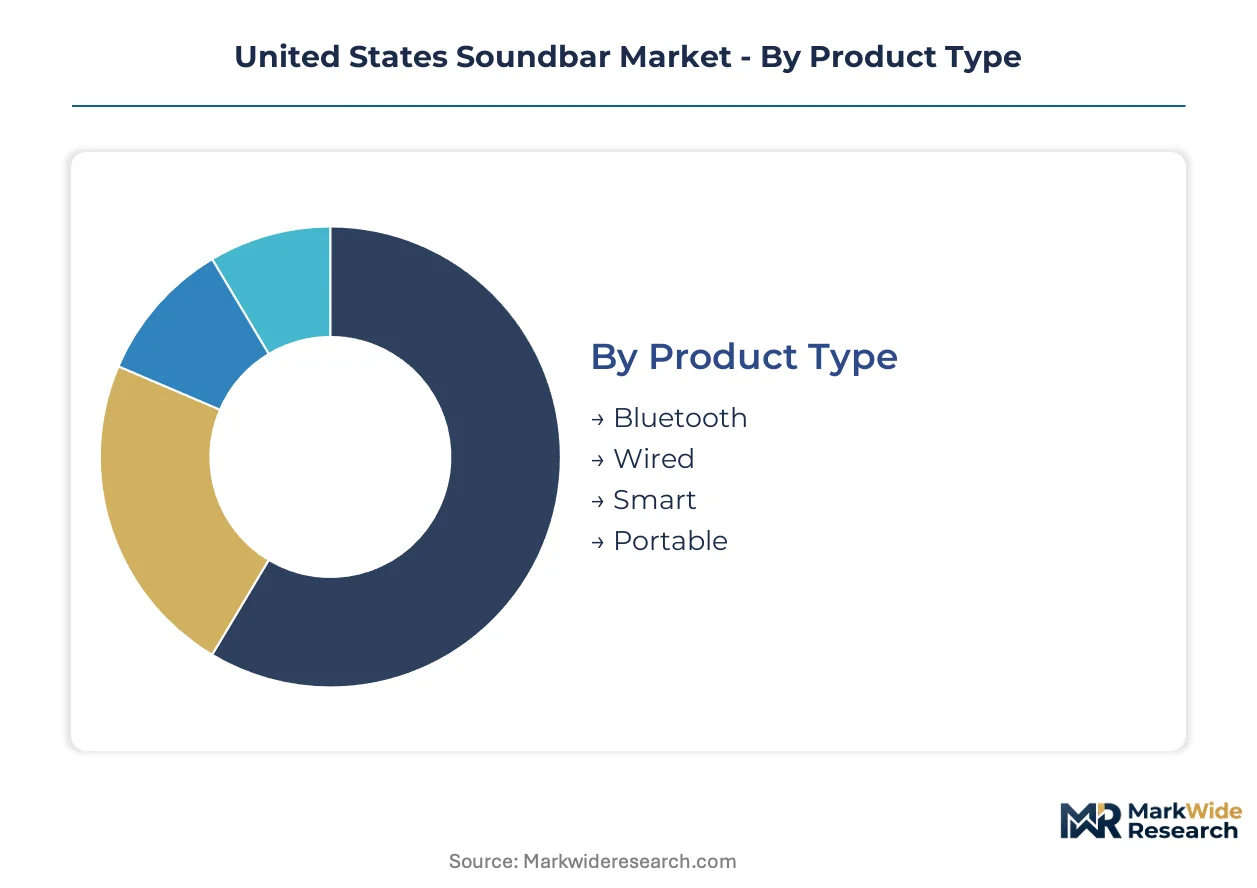
Soundbar purchasing decisions fragment across connectivity preferences, audio processing capabilities, installation environments, and procurement channels. Each segmentation dimension reveals distinct margin structures and competitive intensity patterns that shape manufacturer portfolio allocation.
Product Type:
Consumer use-case spectrum spans from basic television audio augmentation to whole-home audio ecosystems with voice control integration.
- Bluetooth:Entry-level wireless connectivity employing A2DP codec transmission for smartphone and tablet pairing. Demand concentrates in Texas secondary markets where price-sensitive consumers prioritize installation simplicity over HDMI ecosystem integration.
- Smart:Embedded Wi-Fi streaming with proprietary mesh networking and voice assistant integration. California and Florida buyers drive replacement cycles as ecosystem lock-in supersedes raw acoustic specifications in purchasing criteria.
- Wired:Optical TOSLINK and HDMI ARC connectivity without wireless transmission capabilities. Commercial hospitality deployments in Arizona favor these units where FCC Part 15 certification delays threaten project timelines.
- Portable:Battery-powered enclosures with Bluetooth transmission for outdoor and mobile applications. Sun Belt state consumers purchase these for patio entertainment setups where permanent installation is impractical.
The dominant share belongs to Smart, while Portable is closing the gap fastest.
Technology:
Audio processing architecture determines amplifier channel requirements and semiconductor content cost.
- Dolby Atmos:Object-based codec with upward-firing drivers and height virtualization DSP. Texas and California residential installations adopt these configurations within compressed 18-month replacement windows.
- Stereo:Two-channel left-right reproduction without surround processing. Entry-level volume concentrates in Arizona and Florida where basic television audio augmentation satisfies budget-constrained buyers.
- Surround Sound:5.1 or 7.1 channel virtualization through side-firing drivers and psychoacoustic processing. Mid-tier positioning captures consumers seeking immersion without Atmos premium pricing.
- DTS:X:Competitor object-based format with flexible speaker configurations. Niche adoption persists among home theater enthusiasts seeking format diversity beyond Dolby ecosystem dominance.
Dolby Atmos commands the premium tier, with Surround Sound gaining volume most rapidly in mid-market repositioning.
End User:
Installation environment dictates connectivity requirements, durability specifications, and procurement decision-making structures.
- Residential:Home theater and living room installations with consumer-driven purchasing. California and Texas replacement cycles accelerate as flat-panel television refreshes trigger audio system upgrades.
- Hospitality:Hotel guest room and common area deployments requiring wired reliability. Arizona resort properties favor these installations where network infrastructure inconsistency threatens wireless audio stability.
- Commercial:Corporate conference rooms and digital signage applications. Procurement through AV integrators emphasizes remote management capabilities and standardized fleet deployment.
- Retail:In-store demonstration and background music systems. Big-box electronics retailers deploy these for customer experience zones where audio quality influences television purchasing decisions.
Residential holds the volume base, though Hospitality is expanding most quickly in Sun Belt construction corridors.
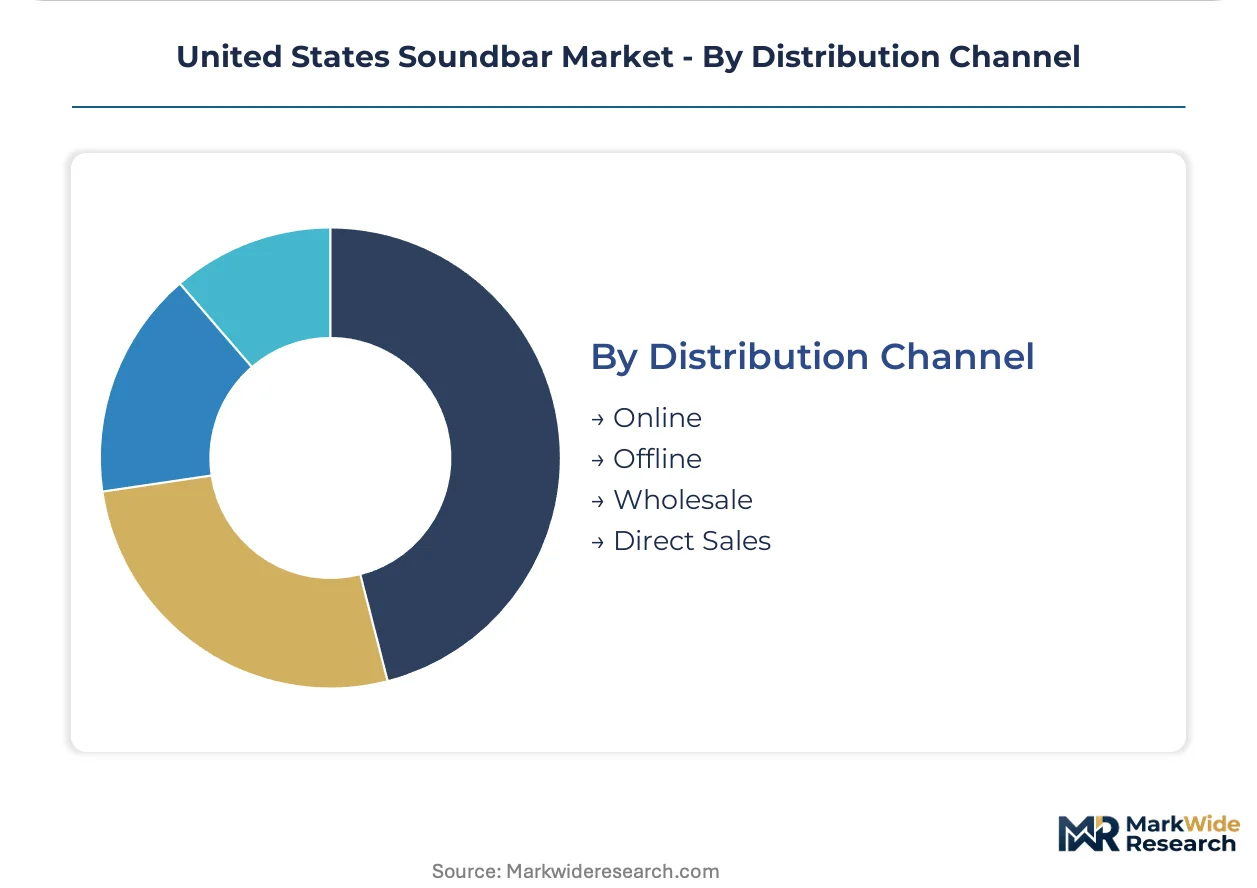
Distribution Channel:
Channel selection determines margin capture, brand positioning, and customer relationship depth.
- Online:E-commerce platforms with direct-to-consumer fulfillment and review-driven discovery. Florida and Arizona buyers increasingly bypass big-box showrooms for specification comparison and price transparency.
- Offline:Brick-and-mortar electronics retailers with demonstration listening environments. California consumers still value in-store auditioning for premium Atmos configurations before commitment.
- Wholesale:Builder and integrator channels for new construction pre-installation. Texas single-family home developments present untapped volume for specification-grade audio partnerships.
- Direct Sales:Manufacturer-owned retail and proprietary ecosystem bundling. Ecosystem-locked consumers accept premium positioning for seamless multi-room integration.
Online captures the growth trajectory, while Wholesale is climbing fastest in residential construction partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor foundries supply DSP chips to California and Texas assembly plants, while FCC certification requirements in the United States create regulatory friction that shapes continental distribution patterns.
California
Premium smart home integration and rapid flat-panel television refresh cycles drive soundbar replacement demand in the San Francisco Bay Area and Los Angeles metro. The California Energy Commission's Title 20 appliance efficiency standards mandate stringent standby power thresholds that favor manufacturers with advanced switching power supply designs. San Diego engineering clusters concentrate RF compliance testing facilities that front-load FCC Part 15 certification into prototype phases.
Texas
Price-sensitive consumers in Houston and Dallas secondary markets prioritize Bluetooth connectivity and installation simplicity over HDMI ecosystem integration. The EPA's ENERGY STAR program influences procurement decisions at big-box retailers operating across the Austin-San Antonio corridor. Dallas-Fort Worth distribution centers serve as regional logistics hubs for builder-grade audio pre-installation partnerships.
Florida
Sun Belt residential construction in Miami and Orlando presents untapped channels for specification-grade soundbar partnerships with single-family home developers. The state's building code efficiency requirements align with federal ENERGY STAR baselines without additional state-level stringency. Tampa Bay retail channels report strong demand for portable battery-powered units serving patio entertainment setups.
Arizona
Phoenix and Scottsdale resort properties favor wired connectivity solutions where network infrastructure inconsistency threatens wireless audio stability. The state's lack of appliance efficiency standards beyond federal baselines simplifies compliance for hospitality-focused manufacturers. Tucson residential construction corridors show climbing demand for builder-grade audio pre-installation in new single-family developments.
Northeast Corridor
New York Metro and Boston consumers still value in-store auditioning for premium Dolby Atmos configurations before commitment. State-level energy efficiency programs in New York and Massachusetts exceed federal baselines, creating competitive differentiation for manufacturers with advanced power management ICs. Philadelphia distribution networks serve as secondary logistics nodes for mid-Atlantic retail penetration.
United States Soundbar Market Key Industry Players
On the supply side, the industry is consolidating around three strategic archetypes: vertically integrated electronics conglomerates controlling semiconductor foundry access, proprietary ecosystem specialists locking users into mesh networking protocols, and value-engineered chassis manufacturers competing on HDMI eARC compatibility at stripped material cost. The dominant competitive moves center on foundry capacity allocation for DSP chip supply security and front-loaded RF compliance testing to compress FCC certification timelines.
Within the vertically integrated tier, Samsung leverages its in-house semiconductor foundry to control DSP chip costs across audio portfolios, while Sonos occupies a position as the proprietary ecosystem specialist with mesh networking protocols that resist interoperability standards. VIZIO anchors the value-engineered archetype with aggressive chassis designs that preserve HDMI eARC compatibility while stripping premium materials.
| Leading Market Players |
|---|
| VIZIO |
| LG |
| Samsung |
| Yamaha |
| JBL |
| Sony |
| Sonos |
| Polk Audio |
| Bose |
| Others |
Cost & Logistics Intelligence
Taipei-based foundry capacity allocation for DSP chips directly determines downstream pricing power for soundbar manufacturers lacking captive semiconductor supply. East Asian wafer fabrication constraints compress margins for brands dependent on external procurement while vertically integrated conglomerates extract cost advantages through in-house chip design.
Pricing Analysis
Prior-generation stereo soundbars, current-generation Dolby Atmos configurations, and emerging Wi-Fi 6E-enabled units exhibit widening price spreads as technology tiers diverge. Three-tier pricing structure across premium, standard, and economy levels reflects amplifier channel count and voice assistant integration depth. Cost compression in entry-level Bluetooth segments is intensifying because foundry capacity constraints elevate DSP chip costs. Budget-constrained buyers in Texas secondary markets demonstrate highest price sensitivity, while California smart home adopters accept premium positioning for ecosystem lock-in.
Supply Chain Analysis
BIS export controls on advanced semiconductor manufacturing equipment constrain Taiwanese and South Korean foundry expansion plans, limiting DSP chip availability for audio processing applications. East Asian semiconductor fabrication, Chinese passive component assembly, and Mexican final chassis integration form the geographic backbone. Raw material dependencies include rare earth magnets for driver motors, epoxy resins for PCB substrates, and aluminum extrusions for enclosures. Single-source vulnerability around 7nm and 5nm DSP wafer production concentrates risk. Distribution runs through Dallas-Fort Worth regional logistics hubs serving big-box retail and builder-grade channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DSP firmware engineering talent capable of implementing psychoacoustic height virtualization algorithms represents the critical capability gap constraining product development timelines. Manufacturers without access to this scarce skill set face compressed competitive windows as codec architectures fragment.
For Market Incumbents: Build captive foundry relationships as a procurement moat against supply concentration risk. Secure long-term wafer allocation agreements with Taiwanese semiconductor fabricators before capacity constraints deepen. Invest in front-loaded RF compliance testing infrastructure to compress FCC Part 15 certification timelines below competitor benchmarks. Prioritize acoustic tuning talent acquisition in San Diego engineering clusters where RF expertise concentrates. For New Entrants and Emerging Players: Arizona and Florida single-family residential construction corridors represent the most penetrable entry point for specification-grade builder partnerships. Sun Belt states lack California's Title 20 stringency, reducing compliance barriers for new market participants. Commercial hospitality deployments requiring wired connectivity solutions offer procurement decision-making accessibility absent entrenched ecosystem relationships. Target AV integrator channels with remote fleet management capabilities as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-access arbitrage play because audio processing DSP supply security will determine which brands survive hardware refresh cycles. Acquisition candidates include mid-tier manufacturers with established HDMI eARC compatibility portfolios but lacking foundry relationships. Monitor BIS export control expansion announcements as the inflection signal for supply-side consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive DSP Chip Supply Agreement | Long-term wafer allocation with TSMC or Samsung Foundry insulates against foundry capacity constraints. |
| Front-Loaded RF Compliance Infrastructure | San Diego-based pre-certification testing compresses FCC Part 15 timelines by 8-14 weeks. |
| Builder-Grade Pre-Installation Partnership | Texas single-family development specifications embed soundbars before consumer decision-making occurs. |
| Proprietary Mesh Networking Protocol | Ecosystem lock-in through Sonos-style proprietary protocols resists interoperability standardization. |
| Title 20-Compliant Power Supply Design | California appliance efficiency standards create shelf placement advantages at big-box retailers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, FCC equipment authorization databases, and ENERGY STAR certified product registries. Audio product development executives, big-box retail category buyers, and commercial AV integrators provided qualitative input on procurement criteria and replacement cycle timing. Customs import records and semiconductor trade data supplied volume triangulation. Bottom-up channel checks across California, Texas, Florida, and Arizona retail locations validated top-down market sizing assumptions.
Forecast inputs include flat-panel television refresh cycle timing, residential construction permit flows in Sun Belt states, and HDMI Forum specification update schedules. Segmentation modeling covers connectivity type, audio processing technology, end-use environment, and distribution channel across the projection horizon. CAGRs derive from installed base replacement velocity and new construction penetration assumptions. Foundry capacity expansion announcements and FCC regulatory dockets provide industry-specific forecast sensitivity parameters.
Practitioners should monitor BIS semiconductor equipment export control expansion, HDMI Forum backward-incompatible specification releases, and Title 20 efficiency standard amendments for early signals requiring forecast revision. Material shifts in Taiwanese foundry allocation priorities or FCC Part 15 certification timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart DJ Controller Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Mobile Accessories Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Bluetooth Speakers Market