
 US Legal Services Market | 2026-2036
US Legal Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Legal Services Market Outlook
White-glove advisory tiers is reorganizing competitive dynamics across the US legal services landscape. Paul, Weiss, Rifkind, Wharton & Garrison dominates elite M&A and securities practices through its Manhattan headquarters. Dentons US extends the largest geographic footprint among US-based firms via its polycentric partnership model. Priori Legal differentiates by embedding vetted freelance attorneys directly inside corporate legal departments.
Legal services encompass advisory representation, transactional documentation, dispute resolution, and compliance counsel delivered by licensed attorneys operating under state bar authority. The work product turns on attorney-client privilege protections, jurisdictional licensing requirements, and ethical rules governing conflicts of interest. Corporate Law within the Service Type dimension anchors the highest fee realization rates as complex cross-border transactions demand specialized partner attention. Intellectual Property under Practice Area generates outsized growth velocity as patent thickets and trade-secret litigation multiply across technology and life sciences sectors. Flat Fee arrangements within Engagement Model are gaining structural traction as general counsel demand cost predictability for routine compliance and contract work.
The American Bar Association sets model ethical standards that state supreme courts adopt with local variations, while the SEC enforces disclosure rules that directly shape securities practice demand. State bar regulators in California and New York impose continuing legal education mandates and unauthorized-practice prohibitions that constrain market entry. Stakeholders must monitor how generative AI tools intersect with state ethics opinions on competence and confidentiality obligations.
Market Dynamics
Generative AI adoption is compressing billable-hour economics while state bar regulators draft competence opinions that reshape attorney workflow requirements across the US legal services market.
Growth Catalysts
- SEC Climate Disclosure Rules:Corporate issuers face expanded ESG reporting obligations that drive demand for securities counsel with specialized disclosure expertise.
- California Privacy Rights Act:Expanding consumer data protections generate compliance mandates requiring ongoing outside counsel support for covered businesses.
- Patent thickets in biologics:Biosimilar litigation volume sustains specialized IP practice groups across life sciences verticals.
Market Restraints
- Attorney compensation inflation:First-year associate salary wars in New York and California compress partner profit margins at mid-tier firms.
- Unauthorized practice prohibitions:State bar enforcement against technology-enabled legal services limits platform scalability across jurisdictions.
- Alternative legal service providers:Managed legal service companies capture routine contract review and e-discovery volume at rate discounts.
Strategic Opportunities
- Texas regulatory arbitrage:Corporate relocations to Dallas and Austin create demand for local counsel with Delaware corporate law expertise.
- Generative AI document generation:Convergence of large language models with expert systems enables automated first-draft contract production.
- Flat-fee compliance subscriptions:General counsel procurement teams favor predictable annual arrangements for recurring regulatory filings.
Industry Challenges
- Technical competence gaps:Senior partners lack fluency in AI-assisted research tools that junior associates deploy routinely.
- Privilege preservation in cloud environments:Client data migration to SaaS platforms creates exposure under state ethical confidentiality rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Legal Services Market |
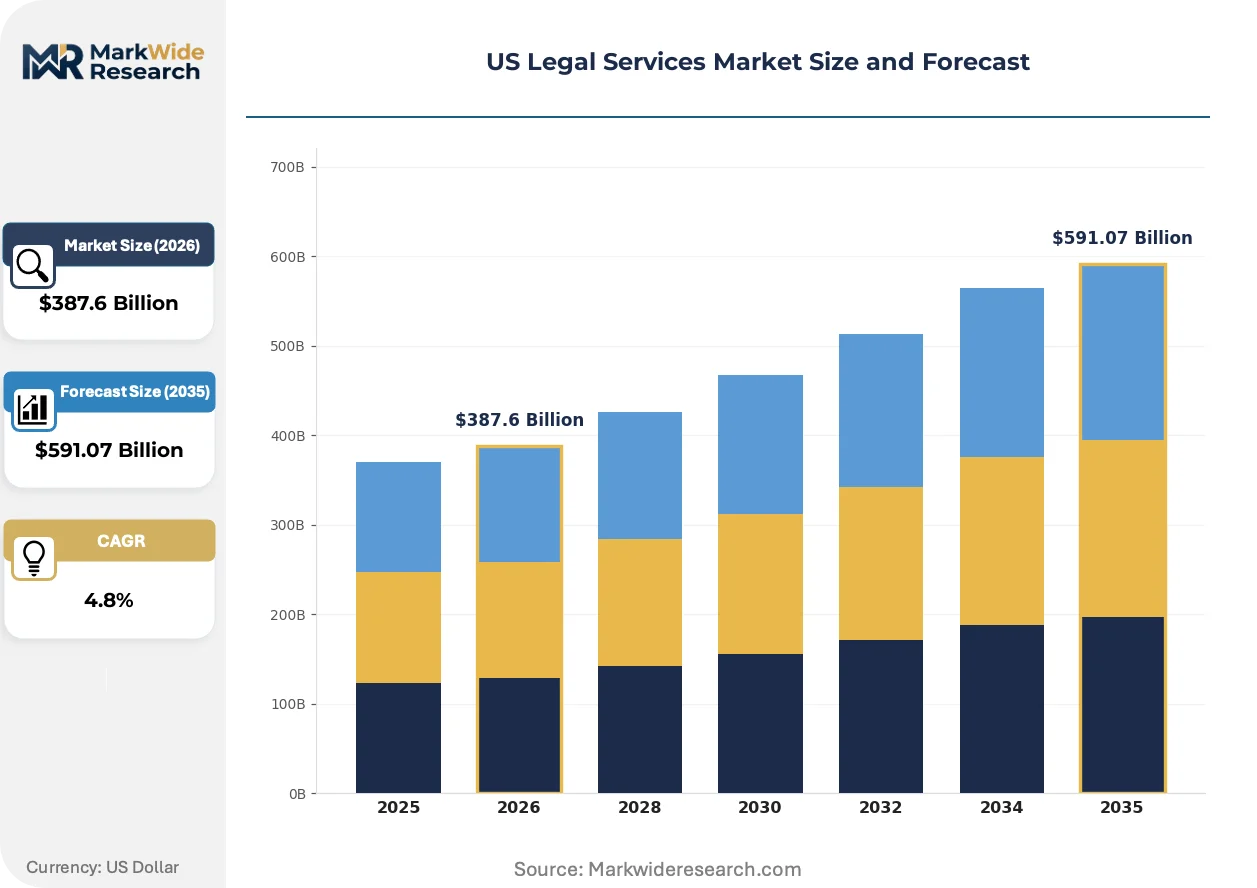
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Civil Litigation, Criminal Defense, Family Law, Corporate Law Client Type: Individual Clients, Small Businesses, Corporations, Non-Profit Organizations Engagement Model: Hourly Billing, Flat Fee, Contingency Fees, Retainer Practice Area: Intellectual Property, Employment Law, Real Estate Law, Administrative Law |
| Companies Covered | Paul, Weiss, Rifkind, Wharton & Garrison, Dentons US, Jones Walker LLP, Everlaw, Fox Rothschild, Cleary Gottlieb Steen & Hamilton, Weil, Gotshal & Manges, Priori Legal, Debevoise & Plimpton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Legal Services Market Strategic Shifts
Technology-enabled service delivery and procurement model experimentation are restructuring how legal work is priced, staffed, and consumed across corporate legal departments and law firm operations.
Natural language processing tools trained on case law and contract corpora are displacing junior associate research hours in due diligence and litigation discovery workflows. AmLaw 200 firms deploy these systems for document classification and clause extraction. Partner leverage ratios compress as technology absorbs routine analytical tasks.
The American Bar Association's Model Rules amendments on technology competence are pressuring state supreme courts to mandate CLE credits in AI ethics and data security. California and New York bar associations issued draft opinions on generative AI disclosure obligations to clients. Firms in these jurisdictions accelerate internal training investments to preempt disciplinary exposure.
Corporate legal departments unbundle matters into discrete components sourced across multiple providers. General counsel retain elite firms for bet-the-company litigation while routing compliance work to alternative legal service providers and freelance platforms. This procurement pattern concentrates in technology and financial services verticals with mature legal operations functions.
US Legal Services Market Segmentation
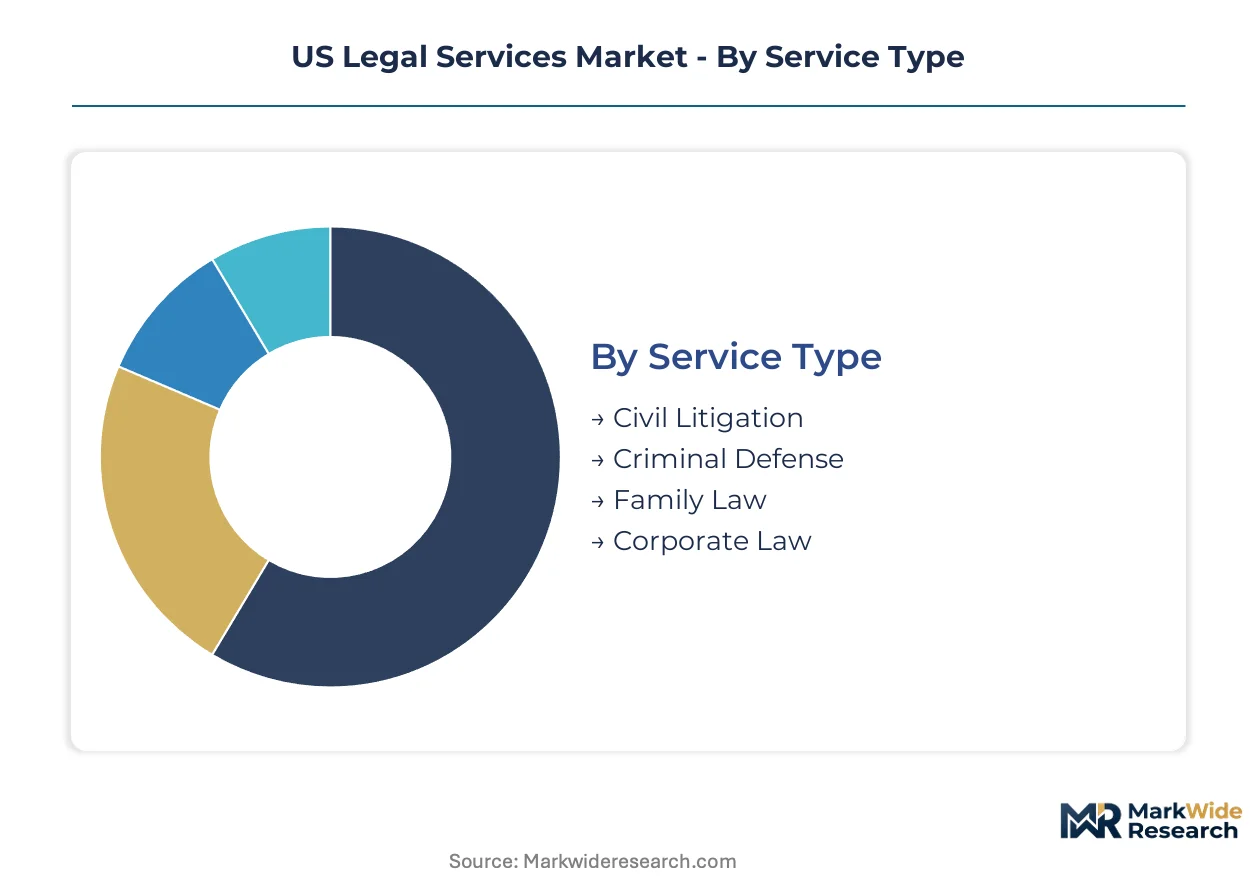
Segmentation reveals how regulatory complexity and client procurement sophistication fragment demand across distinct service tiers. Understanding these divisions exposes where fee compression accelerates and where premium pricing endures.
Service Type:
SEC disclosure mandates and state bar unauthorized-practice enforcement create divergent compliance burdens across service categories.
- Civil Litigation:Dispute resolution spanning commercial conflicts, personal injury claims, and class actions. Demand concentrates in California and New York state courts where docket congestion extends case timelines and sustains premium hourly rates for trial counsel.
- Corporate Law:Transactional advisory covering M&A, securities offerings, and governance counsel. Cross-border deal volume in Delaware-chartered entities drives the highest partner realization rates as specialized expertise commands retainer minimums.
- Criminal Defense:Representation in federal and state prosecutions spanning white-collar, violent offense, and drug-related charges. Public defender funding constraints in high-volume jurisdictions create private market opportunity.
- Family Law:Divorce, custody, and estate planning matters governed by state-specific matrimonial statutes. Mediation mandates in several jurisdictions compress traditional adversarial fee structures.
Established volume favors Civil Litigation; emerging adoption favors Corporate Law.
Client Type:
Procurement maturity varies sharply across organizational scale and legal operations investment.
- Corporations:In-house legal departments with dedicated operations functions managing outside counsel spend. Fortune 500 entities in technology and financial services verticals unbundle matters across multiple provider tiers to optimize cost-quality tradeoffs.
- Small Businesses:Owner-operated entities lacking dedicated legal staff. Subscription flat-fee models gain traction here as cost predictability outweighs scope flexibility.
- Individual Clients:Consumers navigating one-time legal events with price-sensitive engagement preferences. Limited scope representation and unbundled services expand access in family law and housing disputes.
- Non-Profit Organizations:Mission-driven entities dependent on pro bono and reduced-rate arrangements. Foundation-funded legal aid bridges representation gaps in immigration and housing matters.
Revenue concentration sits with Corporations; fastest volume expansion tracks Small Businesses adopting managed legal services.
Engagement Model:
General counsel procurement teams are forcing structural shifts away from pure hourly billing toward output-based arrangements.
- Hourly Billing:Time-based fees tied to attorney classification and recorded effort. Bet-the-company litigation and novel regulatory matters retain this structure where scope uncertainty prevents fixed pricing.
- Flat Fee:Fixed-price arrangements for defined deliverables. Contract lifecycle management and routine compliance filings migrate rapidly to this model as legal operations functions mature.
- Contingency Fees:Success-based compensation common in plaintiff-side personal injury and whistleblower actions. State-specific fee cap regulations constrain upside in several jurisdictions.
- Retainer:Prepaid access arrangements securing dedicated attorney availability. Corporate clients favor annual retainers for ongoing advisory relationships with predictable scope.
Hourly Billing retains dominance in high-stakes matters; Flat Fee arrangements are climbing the fastest across routine corporate work.
Practice Area:
Technology sector expansion and federal regulatory fragmentation generate divergent growth trajectories across specialty domains.
- Intellectual Property:Patent prosecution, trade secret litigation, and trademark portfolio management. Biosimilar disputes and AI-generated content ownership questions sustain specialized practice group investment.
- Employment Law:Workplace discrimination, wage-hour compliance, and executive compensation design. State-level paid leave mandates and non-compete restrictions multiply compliance touchpoints.
- Real Estate Law:Commercial leasing, development finance, and property dispute resolution. Corporate relocation patterns to Texas and Florida create localized demand surges.
- Administrative Law:Regulatory proceedings before federal agencies and state licensing boards. SEC climate disclosure enforcement and FDA marketing authorization challenges sustain specialized bar development.
Intellectual Property commands premium rate tiers; Administrative Law is gaining share fastest amid regulatory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US legal services market operates as a net importer of specialized cross-border counsel, with domestic firms exporting securities and M&A expertise while importing niche regulatory advisory from London and Brussels-based practices.
California
Venture capital deployment and technology sector expansion sustain demand for startup formation and intellectual property counsel. The California Privacy Rights Act imposes ongoing compliance obligations that require outside counsel support for covered businesses. Silicon Valley and San Francisco concentrate the highest density of venture-backed company legal spend, with Palo Alto and San Jose hosting specialized technology transaction practices.
New York
Capital markets activity and hedge fund formation anchor premium hourly rates for securities and investment management counsel. SEC enforcement actions and FINRA arbitration proceedings generate specialized regulatory defense demand. Manhattan hosts the headquarters of elite Wall Street practices, with Midtown and the Financial District sustaining the highest partner realization rates nationally.
Texas
Corporate relocations from California and New York create demand for Delaware corporate law expertise delivered from Dallas and Austin offices. The Texas State Bar enforces continuing legal education requirements that shape practitioner specialization patterns. Houston anchors energy sector legal demand, while Dallas-Fort Worth concentrates private equity and middle-market M&A activity.
Illinois
Commodities trading and derivatives markets sustain specialized regulatory and transactional practices. The Illinois Supreme Court maintains unauthorized practice enforcement that constrains multijurisdictional platform expansion. Chicago hosts the headquarters of derivatives exchanges and associated legal practices serving agricultural and financial futures markets.
Washington, D.C.
Federal regulatory proceedings and administrative law practice concentrate demand for agency-facing counsel. Congressional investigations and white-collar defense matters generate specialized investigative and compliance advisory work. The District and adjacent Northern Virginia suburbs host practices specializing in national security law and government contracts disputes.
US Legal Services Market Competitive Environment
Listed leaders compete with private specialists across partnership structures, with publicly held legal service platforms and privately held law firms pursuing divergent capital strategies. The market fragments across three tiers: elite Manhattan-headquartered practices commanding retainer minimums, national full-service firms with multi-office footprints, and technology-enabled platforms unbundling routine work. Three archetypes dominate: traditional partnership-model law firms, alternative legal service providers with managed service offerings, and venture-backed legal technology platforms. Competitive moves concentrate on lateral partner acquisitions for practice group expansion and proprietary technology development for document automation.
Among elite partnership-model practices, Paul, Weiss, Rifkind, Wharton & Garrison and Cleary Gottlieb Steen & Hamilton exemplify the premium-tier archetype anchored in Manhattan. Dentons US represents the polycentric global network model with distributed partnership governance. Priori Legal occupies a position within the technology-enabled platform segment, embedding vetted freelance attorneys directly inside corporate legal departments.
| Leading Market Players |
|---|
| Paul, Weiss, Rifkind, Wharton & Garrison |
| Dentons US |
| Jones Walker LLP |
| Everlaw |
| Fox Rothschild |
| Cleary Gottlieb Steen & Hamilton |
| Weil, Gotshal & Manges |
| Priori Legal |
| Debevoise & Plimpton |
| Others |
Value Chain & Pricing Dynamics
State bar unauthorized-practice enforcement gates both attorney qualification and fee tiering simultaneously, compressing supply elasticity while preserving premium realization for Manhattan and Silicon Valley practices with specialized regulatory expertise.
Pricing Analysis
Corporate legal departments anchor three-tier pricing stratification across bet-the-company, routine compliance, and commodity legal work. Hourly billing retains dominance in securities litigation and cross-border M&A where Delaware corporate law expertise commands retainer minimums, while flat-fee subscriptions capture contract lifecycle management as general counsel procurement teams prioritize cost predictability. Price compression runs through document review and e-discovery tiers as alternative legal service providers and generative AI tools displace junior associate hours. Small businesses exhibit highest price sensitivity, gravitating toward subscription models; Fortune 500 entities with mature legal operations functions demonstrate lowest sensitivity, unbundling matters across provider tiers.
Supply Chain Analysis
New York and California anchor elite partnership-model firm concentration, with Texas and Washington, D.C. emerging as secondary hubs for regulatory and energy sector practices. The talent pipeline draws from top-14 law school graduates, lateral partner acquisitions, and technology-enabled freelance platforms. Single-source vulnerability concentrates in specialized appellate and Supreme Court practices where a handful of boutiques control premium advocacy capacity. Distribution runs through direct partner-client relationships for high-stakes matters, while alternative legal service providers and managed legal service companies intermediate routine compliance and contract work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat-fee compliance subscriptions and managed legal service arrangements expand faster than traditional hourly billing, creating service-attach opportunities for technology-enabled delivery models.
For Market Incumbents: Shield partner leverage ratios by accelerating generative AI deployment for document classification and first-draft contract production. Consolidate lateral acquisitions in Texas regulatory arbitrage markets where corporate relocations from California and New York demand Delaware corporate law expertise delivered locally.
For New Entrants and Emerging Players: California and Texas bar certification fast-tracks for out-of-state attorneys create white-space entry points for technology-enabled platforms embedding vetted freelance attorneys inside corporate legal departments. Target small business subscription markets where cost predictability outweighs scope flexibility. Pursue managed legal service partnerships with alternative legal service providers to capture routine contract review volume.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across technology-enabled legal service platforms as software margins displace traditional partnership economics. Acquire targets combining proprietary document automation with established corporate legal department relationships. Watch SEC climate disclosure enforcement volume as inflection signal for securities practice demand sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Document Automation | Compresses junior associate research hours while preserving partner realization rates in bet-the-company matters. |
| Flat-Fee Compliance Subscription | Captures recurring regulatory filing volume as general counsel procurement teams demand cost predictability. |
| Texas Regulatory Arbitrage Expansion | Positions firms to serve corporate relocations from California and New York requiring Delaware corporate law expertise. |
| Alternative Legal Service Provider Partnership | Unbundles routine contract review and e-discovery to capture volume at rate discounts below traditional hourly billing. |
| Freelance Attorney Platform Integration | Embeds vetted attorneys directly inside corporate legal departments for flexible capacity without fixed overhead. |
Study Parameters
Initial hypotheses were tested against primary input from general counsel, law firm managing partners, alternative legal service provider executives, and state bar regulators and refined through secondary validation against American Bar Association ethics opinions, SEC enforcement action databases, state bar continuing legal education requirements, and corporate legal department spend surveys. Bottom-up attorney headcount and billing rate data triangulated against top-down market size estimates derived from partnership revenue disclosures and legal technology platform funding rounds.
Variance decomposition across service type, client type, engagement model, and practice area segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical billing rate inflation, attorney headcount growth, and technology adoption curves. Forecast inputs incorporated SEC regulatory expansion timelines, state privacy law proliferation patterns, and generative AI deployment penetration rates across AmLaw 200 firms.
Decision-makers should treat outputs as directional under assumptions of continued state bar enforcement against unauthorized practice and stable corporate legal department outsourcing ratios; material deviation in federal regulatory fragmentation or technology competence opinion adoption would warrant model refresh. Recalibration cycles align with material shifts in SEC enforcement priorities and state bar generative AI ethics guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cloud Broadcasting Solutions Market
Others
Global Personal Care Packaging Market
Others
Cloud-Based Streaming Services Market
Others
Tunnel Lighting Market
Others
Vegan Confectionery Market
Others
Deep Sea Mining Market
Others
North America Compressor Oil Market
Others
Channel-In-A-Box (Ciab) Market
Others
Defense Optronics Market
Others
Saudi Arabia Cat Food Market
Others
Vo5g Market
Others
Fiberglass Storage Tanks Market
Others
Europe Medical Simulation Market
Others
Rotary Dial Machine Market
Others
AI in Precision Medicine Market
Others
Badminton Apparel Market