
 Shisha Tobacco Market | 2026-2036
Shisha Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
Shisha Tobacco Market Outlook
Heat-not-burn alternatives and electronic vapor delivery is fragmenting traditional combustion-based shisha consumption patterns. Al Fakher Tobacco Trading LLC leverages its Dubai manufacturing base to sustain Gulf distribution dominance. Starbuzz Tobacco competes through California-based flavor innovation labs. Nakhla Tobacco anchors Egyptian supply chains with vertically integrated molasses sourcing.
Shisha tobacco comprises fermented molasses-soaked burley or oriental leaf, typically containing glycerin, flavoring agents, and nicotine concentrations ranging from 0.05% to 0.5% by weight, designed for slow combustion in water-cooled pipes. Flavored variants dominate volume while herbal and nicotine-free segments capture health-conscious trial. Pouch packaging leads convenience-store velocity whereas tubs command premium lounge procurement. Specialty stores concentrate margin pools through personalized blending services.
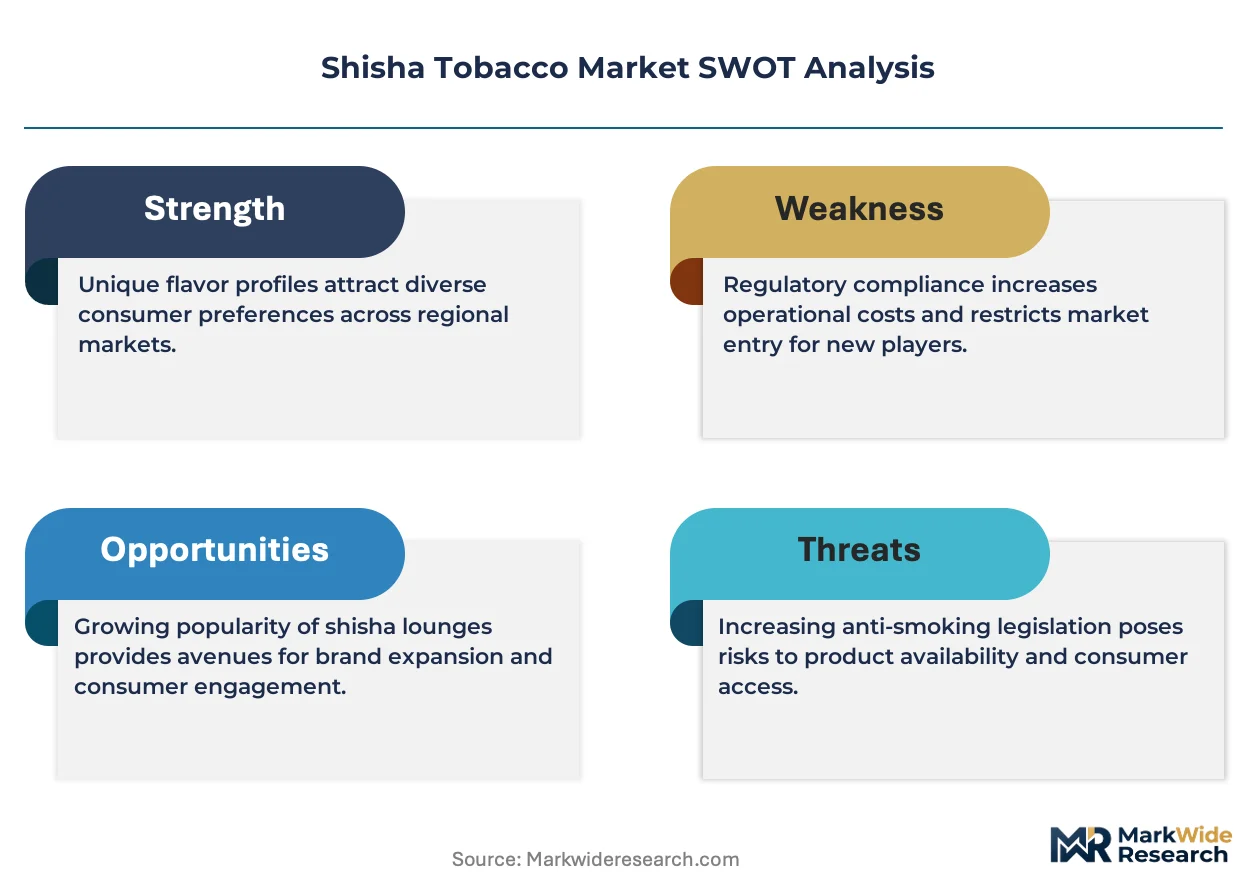
The FDA regulates imported shisha as a tobacco product under the Family Smoking Prevention and Tobacco Control Act, requiring ingredient disclosure and warning labels. The EU Tobacco Products Directive mandates maximum tar and nicotine thresholds while restricting characterizing flavors across member states. The UAE's Emirates Authority for Standardization and Metrology enforces local product registration and quality certification. Stakeholders must monitor evolving flavor bans and heat-not-burn tax parity proposals across multiple jurisdictions to anticipate portfolio restructuring requirements.
Market Dynamics
The European Union's Tobacco Products Directive flavor restrictions are fragmenting traditional product portfolios while heat-not-burn alternatives capture combustion-averse consumers across premium lounge segments.
Growth Catalysts
- Social consumption venues:Premium lounge culture in Dubai and Abu Dhabi normalizes shisha as hospitality entertainment, expanding trial among non-traditional demographics.
- REACH compliance innovation:EU manufacturers reformulate glycerin and flavoring compositions to meet chemical disclosure thresholds, opening compliant product lines.
- Molasses fermentation advances:Controlled humidity curing reduces batch variability and extends shelf stability for export markets.
Market Restraints
- Tobacco leaf input volatility:Burley and oriental leaf prices fluctuate with climate stress in Kentucky and Izmir growing belts.
- Flavor ban cascade:Characterizing flavor prohibitions in Germany, France, and Netherlands eliminate core revenue SKUs without replacement demand.
- Heat-not-burn substitution:Electronic vapor systems capture nicotine-seeking users in UAE and Saudi Arabia lounge environments.
Strategic Opportunities
- Herbal and nicotine-free white space:Non-tobacco molasses blends bypass TPD restrictions while retaining ritual consumption occasions.
- Direct-to-lounge distribution:Bypassing wholesale layers lets manufacturers capture margin and control brand presentation in Cairo and Jeddah venues.
- ISO quality certification:Voluntary standards for glycerin purity and heavy metal limits differentiate export-grade products.
Industry Challenges
- Flavor chemist scarcity:Reformulation expertise for compliant taste profiles commands premium compensation in European R&D centers.
- Dual registration burden:Separate filings with UAE's ESMA and destination-country regulators delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shisha Tobacco Market |
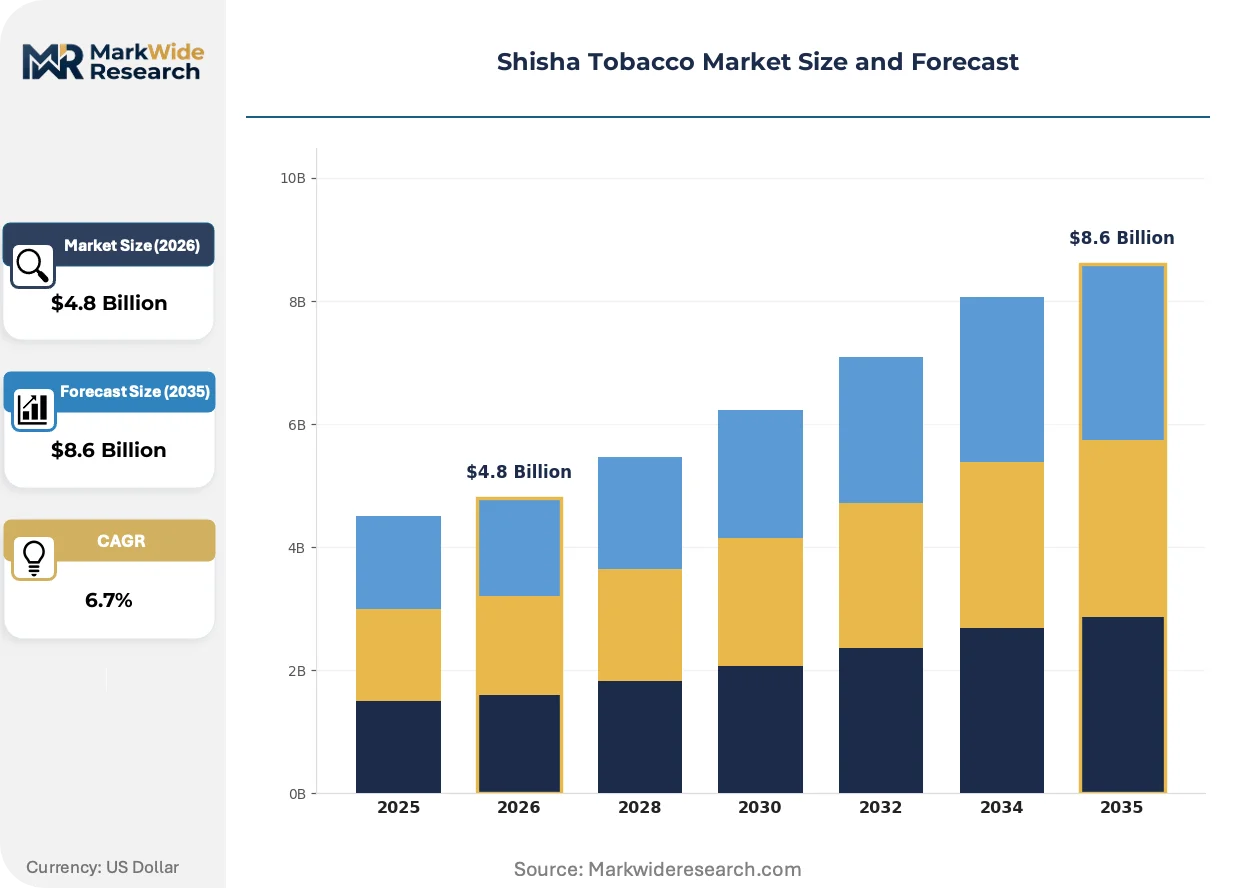
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Herbal, Nicotine-Free Packaging Type: Pouches, Cans, Bottles, Tubs Distribution Channel: Online Retail, Specialty Stores, Convenience Stores, Supermarkets Consumer Type: Young Adults, College Students, Social Smokers, Traditional Users |
| Companies Covered | Nakhla Tobacco, Social Smoke, Al Fakher Tobacco Trading LLC, Haze Tobacco, Black Burn, Starbuzz Tobacco, Mazaya (Alzawrae Company), Metco Limited, Fumari, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shisha Tobacco Market Strategic Shifts
Product architecture is splitting between combustion-loyal traditionalists and technology-curious converts, with regulatory pressure accelerating portfolio diversification across manufacturing bases.
Smart temperature-controlled heating devices is digitizing session management by embedding sensors that monitor coal proximity and airflow. Lounge operators in Dubai and Riyadh deploy these units to standardize burn rates and reduce staff intervention. The data layer is digitizing consumption analytics, letting venues optimize flavor rotation and per-table throughput.
EU F-Gas Regulation refrigerant phase-down is indirectly pressuring shisha logistics by raising cold-chain costs for glycerin storage and flavor concentrate transport. Manufacturers near Rotterdam and Hamburg ports absorb margin compression or switch to ambient-stable formulations. Mediterranean producers without direct port access face disproportionate cost escalation.
Subscription-based home-delivery models are displacing traditional bazaar and duty-free purchasing in Saudi Arabia and Egypt urban corridors. Younger consumers prioritize curated flavor assortments over single-SKU bulk buying. Cairo's delivery app penetration makes this channel transformation most visible in the Nile Delta corridor.
Shisha Tobacco Market Segmentation
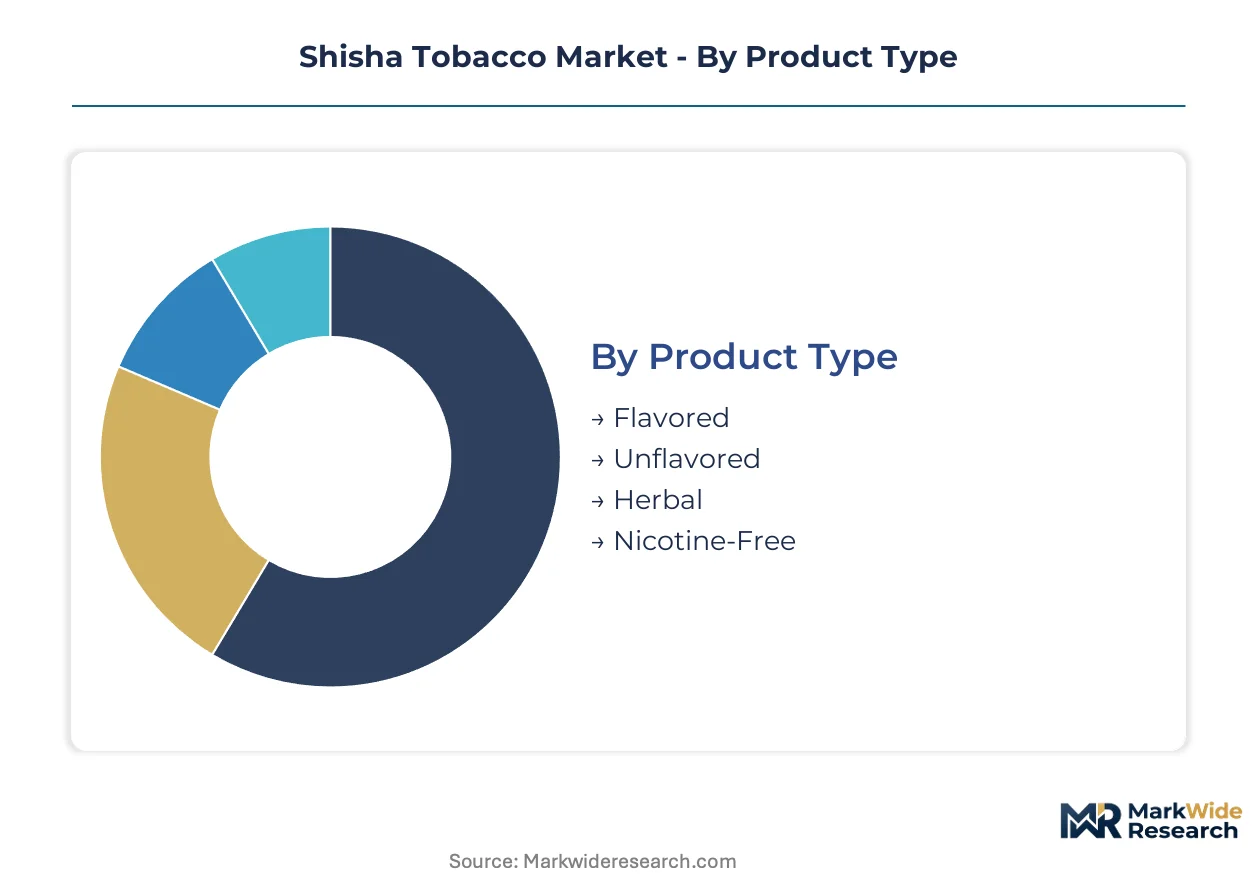
Segmentation in shisha tobacco reveals how consumption rituals, regulatory exposure, and channel economics split demand across distinct profit pools. Manufacturers configure formulation, packaging, and route-to-market strategies differently for each slice to defend margin and anticipate flavor-ban spillover effects.
Product Type:
Cost tiers separate commodity molasses from premium positioning and regulatory shelter.
- Flavored:Fermented burley or oriental leaf soaked in glycerin with synthetic or natural flavoring agents, typically containing 0.05% to 0.5% nicotine by weight. Demand concentrates in Dubai and Abu Dhabi premium lounges where social smokers drive session frequency. EU Tobacco Products Directive flavor restrictions are forcing portfolio restructuring toward compliant taste profiles.
- Herbal:Non-tobacco molasses blends using sugarcane fiber, tea leaves, or fruit pulp as substrate, bypassing tobacco excise and TPD characterizing-flavor bans in Germany and France. Cairo's traditional café sector shows rising procurement as venue operators hedge regulatory risk.
- Unflavored:Plain burley or oriental leaf with minimal processing, appealing to purist demographics in Egypt's Nile Delta corridor. Saudi Arabia's older traditional users sustain volume despite declining share.
- Nicotine-Free:Decaffeinated or never-fermented herbal bases targeting health-conscious trialists in Riyadh and Jeddah subscription channels. Younger consumers prioritize ritual participation over pharmacological effect.
Flavored variants command the established base. The steepest expansion runs through Herbal as regulatory arbitrage accelerates.
Packaging Type:
Volume economics and consumption occasion shape format selection across retail and hospitality channels.
- Tubs:Bulk polyethylene or metal containers holding 250g to 1kg, standard for Cairo and Jeddah lounge procurement where per-session throughput justifies inventory investment. Premium venues negotiate direct manufacturer pricing to bypass wholesale markups.
- Pouches:Resealable foil sachets of 50g to 100g dominating Saudi Arabia and Egypt convenience-store velocity. Urban delivery apps in the Nile Delta corridor favor pouch logistics for last-mile efficiency.
- Cans:Airtight metal cylinders with humidity seals, prevalent in UAE duty-free retail and gift segments. Emirates Authority for Standardization and Metrology registration requirements favor established suppliers with packaging compliance infrastructure.
- Bottles:Glass or PET containers for liquid molasses concentrates and flavor additives, niche in specialty store blending services. Rotterdam and Hamburg port proximity reduces glycerin cold-chain costs for EU-facing producers.
Tubs anchor hospitality procurement. Pouches are gaining share fastest through convenience and delivery channel expansion.
Distribution Channel:
Customer type and purchase urgency determine margin capture and brand control intensity.
- Specialty Stores:Curated inventory with personalized blending services and staff expertise, concentrating margin pools in Dubai's Deira district and Cairo's Khan el-Khalili cluster. ISO quality certification for glycerin purity differentiates premium stockists.
- Online Retail:Subscription-based home-delivery models displacing traditional bazaar purchasing in Saudi Arabia urban corridors. Younger consumers prioritize curated assortments over single-SKU bulk buying.
- Convenience Stores:High-velocity pouch and small-format tub placement for impulse and replenishment occasions. Shelf space competition intensifies as heat-not-burn devices capture adjacent nicotine-seeking traffic.
- Supermarkets:Mass-market flavored variants in hypermarket tobacco sections, volume-driven with compressed margins. EU flavor restrictions are eliminating core SKUs without replacement demand in German and French retail.
Specialty stores defend the premium position. Online retail climbs the fastest as app penetration restructures purchasing habits.
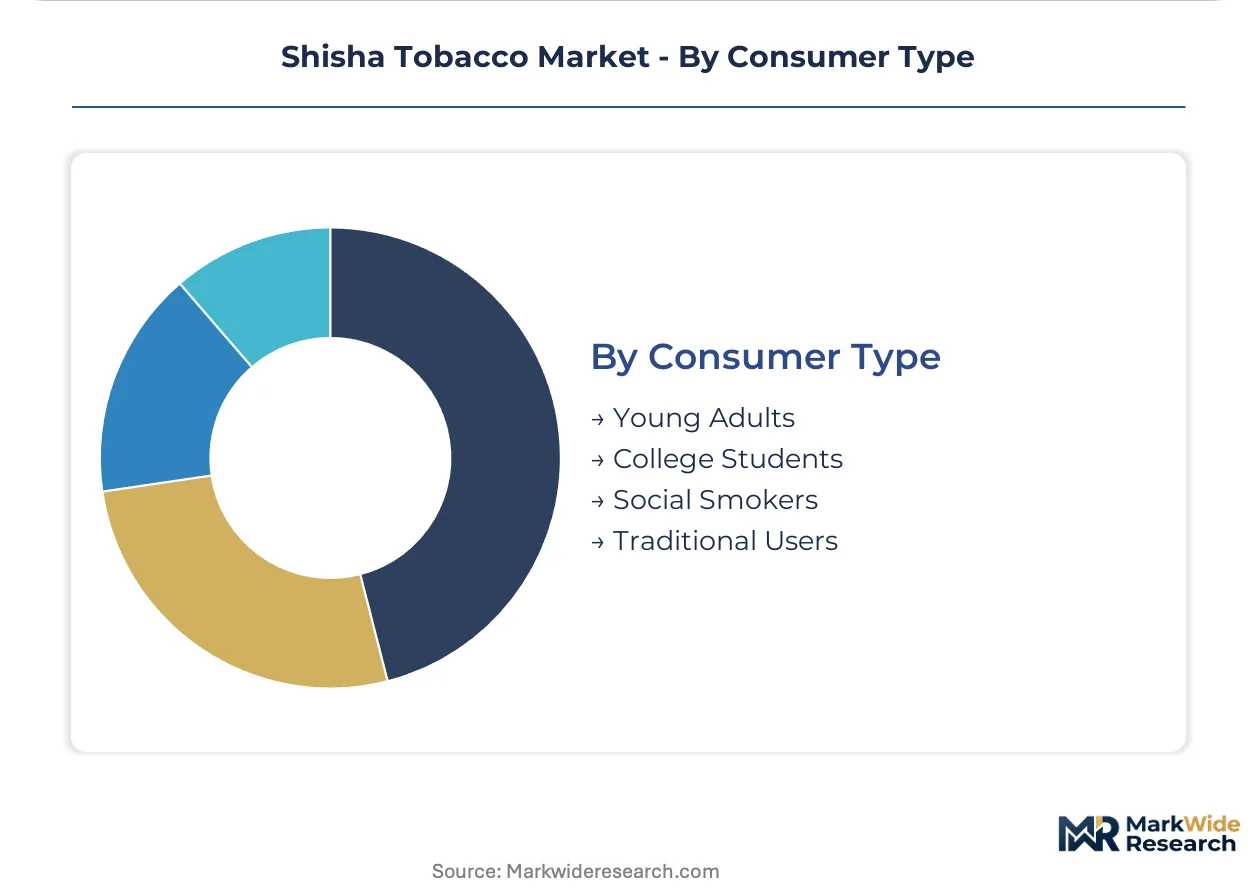
Consumer Type:
Application context and ritual frequency split demand between habitual and occasional use patterns.
- Social Smokers:Occasion-driven consumption in hospitality venues, prioritizing flavor variety and session aesthetics over nicotine delivery. Dubai lounge culture normalizes shisha as entertainment expense rather than addiction maintenance.
- Traditional Users:Daily or near-daily combustion rituals, often in home or neighborhood café settings, showing strongest loyalty to specific molasses brands and preparation methods. Egypt's older demographic sustains this segment despite youth migration to alternatives.
- Young Adults:Digital-native consumers aged 18-30, receptive to herbal and nicotine-free positioning and subscription discovery. Saudi Arabia's delivery app penetration makes this cohort most visible in Riyadh and Jeddah data.
- College Students:Price-sensitive trialists with high flavor experimentation rates and low brand loyalty, concentrated in urban Egyptian and Saudi campus corridors. Shared session economics spread cost across groups.
Traditional users anchor volume stability. Social smokers represent the fastest-growing trajectory as hospitality investment expands across Gulf cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-manufactured shisha tobacco flows primarily to Saudi Arabia and Egypt, with secondary export corridors reaching Germany and France before EU flavor restrictions tightened. Trade routes reflect both cultural consumption patterns and regulatory arbitrage opportunities.
United Arab Emirates
Dubai's premium lounge culture normalizes shisha as hospitality entertainment, expanding trial among non-traditional demographics. Emirates Authority for Standardization and Metrology enforces local product registration and quality certification requirements. Abu Dhabi and Dubai manufacturing clusters sustain Gulf distribution dominance through direct-to-venue supply relationships.
Egypt
Traditional café sector procurement anchors volume demand, with older users sustaining daily combustion rituals. The country's national tobacco regulator monitors excise collection and product safety standards. Cairo's Khan el-Khalili cluster concentrates specialty store margin pools through personalized blending services.
Saudi Arabia
Riyadh and Jeddah subscription channels show fastest herbal and nicotine-free segment growth among young adults. SFDA oversees product registration and quality compliance for imported and domestic shisha. Urban delivery app penetration restructures purchasing habits across the Nile Delta corridor influence zone.
Germany
Characterizing flavor prohibitions eliminate core revenue SKUs without replacement demand in retail channels. REACH compliance mandates chemical disclosure thresholds for glycerin and flavoring compositions. Hamburg port proximity reduces cold-chain cost escalation for EU-facing producers with ambient-stable formulations.
France
Flavor ban cascade effects compress supermarket tobacco section margins as compliant product lines struggle to offset lost volume. ANSM enforces pharmaceutical-grade standards for nicotine-containing products crossing regulatory boundaries. Paris retail clusters pivot toward herbal alternatives bypassing TPD restrictions.
Shisha Tobacco Market Competitive Environment
On the supply side, the industry is bifurcated between Gulf-based manufacturers with lounge distribution control and European reformulation specialists adapting to regulatory compression. Consolidation pressures concentrate around flavor chemistry capabilities and ESMA registration infrastructure. Three archetypes dominate: vertically integrated molasses processors, California-based flavor innovation labs, and herbal-alternative pure-plays. Competitive moves center on direct-to-lounge distribution bypassing wholesale layers and ISO quality certification differentiation for export-grade positioning.
Within the heritage manufacturer tier, Nakhla Tobacco and Al Fakher Tobacco Trading LLC exemplify vertically integrated supply chain control, with the former anchoring Egyptian molasses sourcing and the latter leveraging Dubai manufacturing bases. Starbuzz Tobacco occupies a position representing California-based flavor innovation archetypes. These three entities collectively illustrate the geographic and strategic segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Nakhla Tobacco |
| Social Smoke |
| Al Fakher Tobacco Trading LLC |
| Haze Tobacco |
| Black Burn |
| Starbuzz Tobacco |
| Mazaya (Alzawrae Company) |
| Metco Limited |
| Fumari |
| Others |
Value Chain & Pricing Dynamics
Dubai's manufacturing cluster concentrates glycerin processing and flavor compounding capacity, giving UAE-based producers leverage over Saudi Arabia and Egypt procurement negotiations. This geographic concentration lets incumbents enforce premium-mid-economy pricing differentiation while absorbing EU F-Gas Regulation cold-chain cost escalations.
Pricing Analysis
Combustion-traditional versus heat-not-burn versus herbal-alternative generation tiers create distinct price floors across the Shisha Tobacco Market. Three-tier pricing structure across premium, standard, and economy levels anchors on ISO certification status and glycerin purity grades. Pricing pressure stems from REACH compliance reformulation costs in European export corridors. College students in Egyptian urban campuses show highest price sensitivity, while Dubai lounge operators accept premium positioning for brand presentation control.
Supply Chain Analysis
Tariff exposure between Turkey and Germany dominates supply chain risk as Izmir oriental leaf faces EU Tobacco Products Directive import scrutiny. Raw material sourcing draws from Egyptian molasses belts, Kentucky burley farms, and Izmir sun-cured leaf processors. Single-source vulnerability concentrates in glycerin supply from Rotterdam and Hamburg port refineries. Distribution runs through direct-to-lounge relationships in Gulf cities and subscription-platform intermediaries in Saudi urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate heat-not-burn substitution in premium lounge segments where electronic vapor systems capture nicotine-seeking users across Dubai and Riyadh venues.
For Market Incumbents: Entrench ESMA registration infrastructure to accelerate dual-filing timelines and compress 8-14 month approval delays. Deepen backward integration into Izmir sun-cured leaf supply to buffer climate-stress volatility in Kentucky growing belts. Prioritize herbal-alternative capacity expansion ahead of EU flavor ban cascade spillover. For New Entrants and Emerging Players: Establish a beachhead in Cairo's delivery app corridor where subscription-based discovery displaces traditional bazaar purchasing. Target nicotine-free formulations for Riyadh and Jeddah young adult segments. Leverage ISO quality certification as differentiation wedge against heritage manufacturers lacking export-grade positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Egyptian molasses processors lacking direct-to-lounge distribution infrastructure. Long-term viability hinges on regulatory arbitrage capability across TPD-restricted and permissive jurisdictions. Watch SFDA registration acceleration as inflection signal for Saudi market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Herbal Product Line Expansion | Bypasses EU Tobacco Products Directive flavor bans while retaining ritual consumption occasions in German retail. |
| Direct-to-Lounge Distribution Buildout | Captures margin pools in Cairo and Jeddah venues while controlling brand presentation against wholesale competitors. |
| ISO Quality Certification Investment | Differentiates export-grade glycerin purity for Rotterdam and Hamburg port-facing producers under REACH scrutiny. |
| Smart Heating Device Integration | Digitizes session analytics for Dubai lounge operators optimizing per-table throughput and flavor rotation. |
| Molasses Fermentation Automation | Reduces batch variability for Egyptian supply chains serving Nile Delta traditional café procurement. |
Study Parameters
The analysis maps flavored, herbal, unflavored, and nicotine-free sub-sectors, each validated through lounge procurement managers, flavor chemists, regulatory affairs specialists, and molasses supply coordinators. Primary fieldwork combined with secondary triangulation across Emirates Authority for Standardization and Metrology filings, EU Tobacco Products Directive compliance databases, SFDA registration records, and customs trade flows anchored volume estimates. Bottom-up venue throughput modeling and top-down excise revenue reconciliation cross-validated demand figures.
Assumptions held EU flavor restriction enforcement intensity and Gulf hospitality investment trajectories fixed while varying heat-not-burn substitution rates and herbal segment trial conversion. Segmentation dimensions spanned product type, packaging format, distribution channel, and consumer archetype across the projection horizon. CAGRs derived from weighted average of historical lounge session frequency trends and regulatory scenario stress-testing. Molasses fermentation yield curves and glycerin cold-chain cost escalations fed industry-specific inputs.
Stress conditions across REACH disclosure thresholds, F-Gas Regulation phase-down timelines, and SFDA approval velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about lounge culture normalization and subscription channel penetration. Material shifts in EU flavor ban cascade scope or heat-not-burn tax parity proposals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Coriolis Meters Market
Others
Badminton Apparel Market
Others
Security Envelopes Market
Others
Plastic Films and Sheets Market
Others
Construction Wearables Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Video Encoder Market
Others
Balsa Wood Market
Others
Operator Training Simulator Market
Others
Prunes Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Reef Aquarium Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Smart Home Market
Others
Global Aircraft Lighting Systems Market
Others
Global Luxury High End Furniture Market