
 Pollen Allergy Market | 2026-2036
Pollen Allergy Market Size, Share, and Industry Trends Forecast 2026-2036
Pollen Allergy Market Analytics
Recombinant allergen components are shifting product economics away from crude pollen extracts toward precision biologics with improved safety profiles. ALK-Abello leverages its vertically integrated allergen manufacturing network across Europe to control raw material quality from cultivation through purification. Stallergenes Greer anchors its competitive position through sustained investment in sublingual immunotherapy tablet platforms. Sanofi dominates the symptomatic relief segment with broad antihistamine and nasal corticosteroid portfolios distributed through pharmacy and hospital channels.
Pollen allergy encompasses immune-mediated hypersensitivity reactions to airborne pollen proteins from trees, grasses, and weeds, characterized by IgE-mediated mast cell degranulation releasing histamine and leukotrienes that produce rhinitis, conjunctivitis, and asthmatic symptoms. The condition serves as a primary indication for both acute pharmacological intervention and disease-modifying immunotherapy across outpatient and specialist settings. Immunotherapy represents the fastest-growing product category as patients and payers prioritize disease modification over chronic symptomatic management. The adult end-user segment occupies the largest revenue pool, though pediatric applications are expanding fastest as early intervention protocols gain specialist endorsement. Hospital and clinic distribution channels capture premium pricing for administered therapies, while online stores extend access for maintenance prescriptions in established treatment populations.
FDA oversight of allergen extract products through the Biologics License Application pathway shapes manufacturing standards and clinical evidence requirements for US market access. EMA's MDR framework and the EU F-Gas Regulation indirectly influence diagnostic device availability and environmental exposure assessment tools. The EU AI Act will classify pollen forecasting algorithms as high-risk systems, mandating validation protocols that affect digital health entrants. Stakeholders must monitor regulatory divergence between US biologics pathways and European immunotherapy standardization initiatives to align portfolio development with divergent evidence requirements.
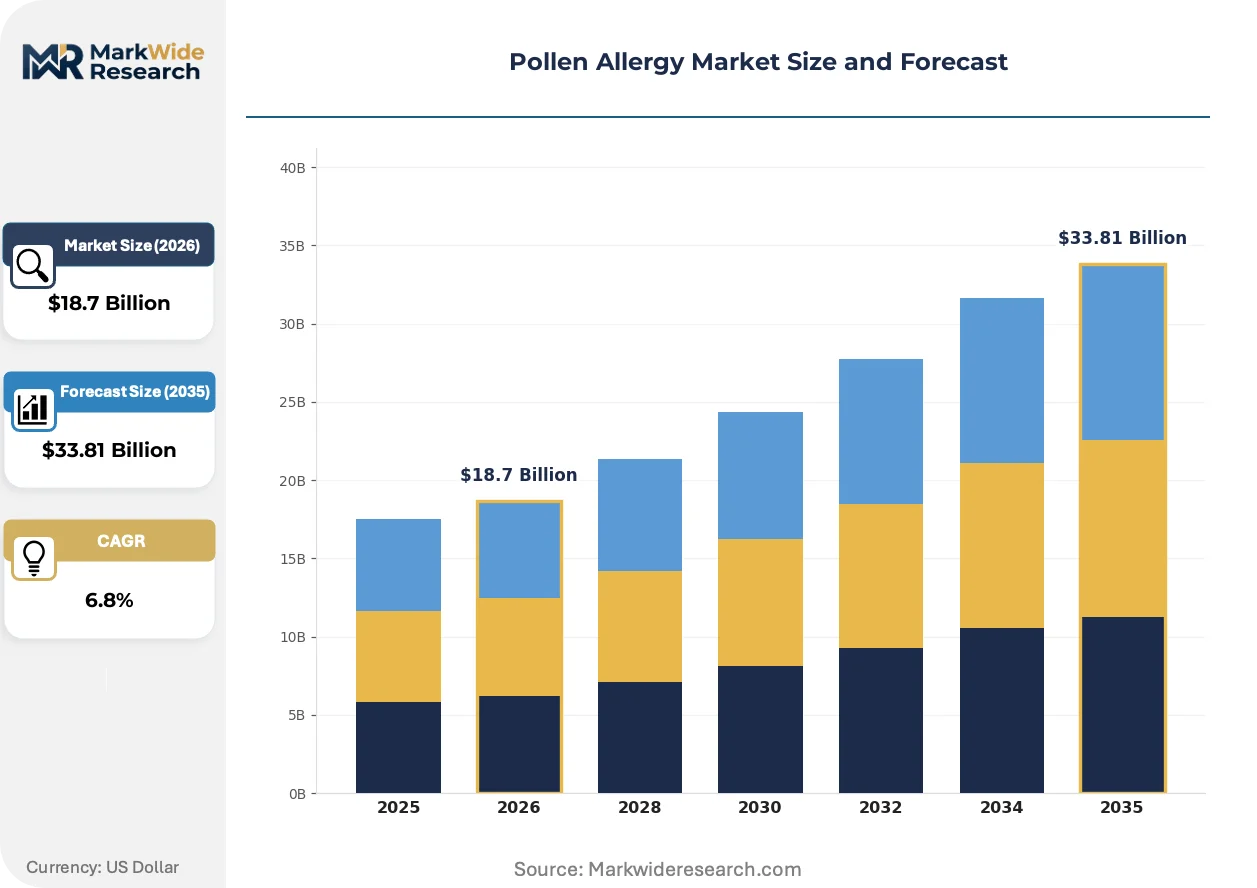
Market Dynamics
Recombinant allergen technology is compressing the therapeutic window for crude extract immunotherapy, forcing manufacturers to retool purification infrastructure and clinical trial portfolios toward precision biologics with superior safety margins.
Growth Catalysts
- EU Green Deal air quality mandates:Tighter ambient pollen monitoring standards across member states are expanding diagnostic device procurement cycles and driving real-time forecasting platform adoption.
- Pediatric allergy clinic volumes:Rising patient flows through specialist practices in Germany, France, and the United Kingdom are normalizing early-intervention immunotherapy protocols.
- Sublingual tablet platforms:Self-administered immunotherapy formats are displacing injection-based regimens in outpatient settings, improving treatment persistence rates among working-age adults.
Market Restraints
- Biologics License Application pathway complexity:FDA manufacturing standards for allergen extracts impose multi-year validation timelines that freeze smaller extract producers out of US market access.
- European raw material concentration:Controlled pollen cultivation and purification capacity clusters in Denmark and France, creating single-source vulnerability for recombinant allergen supply chains.
- Antihistamine substitution pressure:Over-the-counter symptomatic relief products capture price-sensitive patients before immunotherapy qualification, compressing addressable disease-modification demand.
Strategic Opportunities
- Digital health algorithm validation:EU AI Act high-risk system classification for pollen forecasting tools creates first-mover advantage for platforms with pre-certified clinical evidence packages.
- Maintenance prescription channel expansion:Online pharmacy fulfillment for established immunotherapy populations bypasses clinic capacity constraints in saturated urban markets.
- Sub-regional penetration in Southern Europe:Spain and Italy exhibit immunotherapy treatment rates below Northern European benchmarks, presenting volume expansion potential through subsidized access programs.
Industry Challenges
- Allergen biochemistry specialization scarcity:Purification process engineers with recombinant protein experience command premium compensation, constraining manufacturing scale-up timelines.
- MDR transition compliance backlog:European diagnostic device re-certification under the Medical Device Regulation is delaying product launches and freezing R&D resource allocation.
- Legacy extract portfolio integration:Manufacturers maintaining crude allergen production lines face dual-track capital demands while transitioning biologics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pollen Allergy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Nasal Corticosteroids, Decongestants, Immunotherapy End User: Adults, Children, Geriatrics, Pregnant Women Distribution Channel: Pharmacies, Online Stores, Hospitals, Clinics Geographical Expansion: Urban Areas, Rural Areas, Coastal Regions, Inland Areas |
| Companies Covered | ALK-Abello, Stallergenes Greer, Sanofi, GlaxoSmithKline, Johnson & Johnson, Merck & Co., Pfizer, Teva Pharmaceuticals, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pollen Allergy Market Evolving Landscape
Precision molecular diagnostics and self-administered therapeutic formats are collapsing the traditional specialist-mediated care pathway, redirecting value capture toward platform-enabled patient management ecosystems.
Recombinant allergen component testing is electrifying diagnostic specificity by quantifying IgE responses to individual protein epitopes rather than crude pollen mixtures. Specialist practices in Germany and Switzerland are adopting these multiplex assays at twice the rate of general allergy clinics. This technology is compressing the trial-and-error phase of immunotherapy formulation, enabling personalized allergen selection that reduces adverse event rates and accelerates treatment initiation.
EMA's Medical Device Regulation and the EU AI Act are converging to impose dual validation requirements on digital pollen forecasting systems. Manufacturers must now submit clinical performance data for algorithmic predictions alongside hardware safety documentation. Sub-lingual immunotherapy tablet producers with integrated patient apps face the steepest compliance burden, as their dosing reminders and symptom trackers trigger high-risk system classification.
Subscription-based immunotherapy management is displacing episodic prescription renewal in established treatment populations. Dutch and Belgian pharmacy chains are piloting annual membership models bundling medication delivery, symptom tracking, and teleconsultation access. This shift is most visible among employed adults aged 30-50, where convenience premiums outweigh co-pay sensitivity and workplace absence costs dominate total disease burden calculations.
Pollen Allergy Market Segmentation
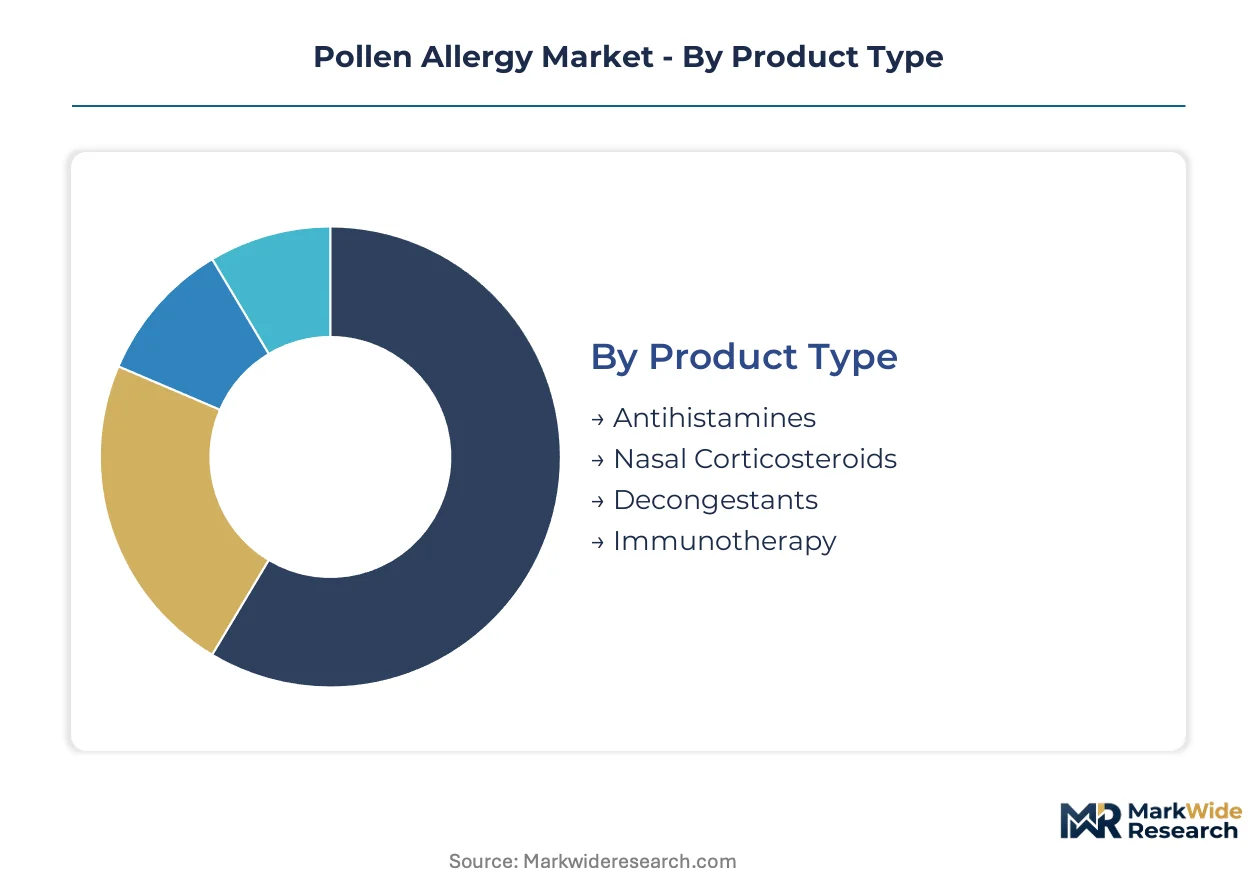
Pollen allergy treatment selection hinges on disease severity, patient age, and access to specialist care. Segment boundaries are blurring as sublingual formats and digital pharmacy channels reshape traditional category definitions.
Product Type:
Cost tier determines initial access point, with out-of-pocket thresholds filtering patients toward symptomatic relief before disease-modifying options.
- Antihistamines:First-generation and second-generation H1 receptor antagonists block histamine-mediated vasodilation and pruritus. German and French pharmacy chains move substantial volume through seasonal promotional cycles tied to national pollen calendars.
- Immunotherapy:Subcutaneous and sublingual allergen extracts induce antigen-specific immune tolerance through T-regulatory cell modulation. Denmark and France host concentrated manufacturing infrastructure for recombinant allergen purification, with sublingual tablet demand climbing fastest among working-age adults seeking self-administered regimens.
- Nasal Corticosteroids:Intranasal glucocorticoid sprays suppress local inflammatory cytokine production.
- Decongestants:Alpha-adrenergic agonists provide short-term nasal patency relief.
Antihistamines lead on scale; immunotherapy leads on momentum.
End User:
Application severity and treatment persistence requirements vary sharply across life stages, with pediatric protocols emphasizing early immune modulation.
- Adults:Working-age populations between 18 and 65 years drive the largest absolute prescription volumes, particularly for maintenance immunotherapy spanning three-to-five-year treatment courses. Workplace absence cost calculations in Germany and the Netherlands push employed patients toward disease-modifying options despite higher upfront expenditure.
- Children:Pediatric allergology practices in Munich, Paris, and London are expanding sublingual immunotherapy eligibility to patients as young as five years, capitalizing on immune system plasticity windows. Early intervention protocols are normalizing across Northern European specialist networks.
- Geriatrics:Polypharmacy considerations and comorbid cardiovascular conditions constrain antihistamine selection in patients over 65.
- Pregnant Women:FDA pregnancy category restrictions and fetal safety data gaps limit pharmacological options during gestation.
Adults dominate current revenue; children are climbing the fastest.
Distribution Channel:
Customer convenience expectations and reimbursement mechanics determine channel preference, with urban density accelerating digital adoption.
- Pharmacies:Community and hospital-affiliated dispensaries remain the primary point of contact for initial diagnosis and acute symptom management. German pharmacy chains leverage pollen forecasting integrations to trigger targeted antihistamine promotions during high-count periods.
- Online Stores:E-commerce platforms and subscription services capture established immunotherapy populations seeking refill automation. Dutch and Belgian pharmacy cooperatives pilot annual membership bundles combining medication delivery with teleconsultation access.
- Hospitals:Tertiary care centers administer subcutaneous immunotherapy and manage severe anaphylaxis cases.
- Clinics:Specialist allergy practices conduct diagnostic testing and initiate disease-modifying treatment protocols.
Pharmacies hold volume leadership; online stores show steepest expansion trajectory.
Geographical Expansion:
Supply concentration and environmental exposure patterns create divergent demand profiles across settlement types.
- Urban Areas:Dense metropolitan populations in Berlin, Madrid, and Milan concentrate diagnostic device deployment and specialist clinic capacity. Heat island effects and traffic-related pollen dispersion amplify symptom burden in city centers.
- Rural Areas:Agricultural pollen exposure and limited specialist access define treatment patterns. Telemedicine platforms bridge diagnostic gaps in French and Spanish rural departments.
- Coastal Regions:Maritime climate moderation reduces pollen season intensity in Atlantic and Mediterranean littoral zones.
- Inland Areas:Continental climate extremes extend pollen seasons in Central European basins.
Urban areas anchor commercial infrastructure; rural areas present untapped connectivity-enabled potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's vertically integrated allergen manufacturing cluster anchors European supply chains for recombinant protein purification, while regulatory divergence between FDA biologics pathways and EMA standardization initiatives shapes divergent market access strategies across the Atlantic.
Germany
Pediatric allergy clinic volumes in Munich, Hamburg, and Berlin are normalizing early-intervention immunotherapy protocols for children as young as five years. The country's statutory health insurance system subsidizes multi-year disease-modifying treatment courses, driving treatment persistence rates above European benchmarks. Bavaria's specialist practice networks concentrate diagnostic device deployment and recombinant allergen testing adoption.
United States
FDA oversight through the Biologics License Application pathway imposes multi-year manufacturing validation timelines that concentrate market access among established extract producers. The EPA's ambient air quality monitoring infrastructure supports pollen forecasting platform development, though algorithmic health tools face evolving regulatory scrutiny. Greater Boston and Research Triangle Park host concentrated biologics manufacturing and clinical trial operations.
France
ANSM and CNIL oversight converges with EMA frameworks to impose dual validation requirements on digital diagnostic systems. The Paris metropolitan area anchors specialist allergology practice expansion, while Lyon and Strasbourg host controlled pollen cultivation facilities supplying raw material to recombinant allergen purification operations. Telemedicine platforms bridge diagnostic gaps in rural departments with limited specialist access.
United Kingdom
NHS England's commissioning frameworks prioritize cost-effective symptomatic relief through pharmacy channels, though specialist referral pathways maintain immunotherapy access for severe cases. London's pediatric allergy centers are expanding sublingual tablet eligibility criteria. The MHRA's post-Brexit regulatory autonomy is diverging from EMA MDR implementation timelines, creating parallel certification requirements for diagnostic device manufacturers.
Switzerland
Swissmedic's pharmaceutical oversight maintains alignment with EMA standards while preserving national flexibility for novel biologics approval. Zurich and Geneva specialist practices are adopting multiplex recombinant allergen assays at twice the rate of general allergy clinics. The country's precision diagnostics ecosystem supports personalized immunotherapy formulation services that compress treatment initiation timelines.
Pollen Allergy Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory navigation capabilities. The market structures around three tiers: vertically integrated allergen extract producers with captive cultivation-to-purification operations; pharmaceutical conglomerates with broad symptomatic relief portfolios distributed through pharmacy and hospital channels; and emerging biologics specialists advancing recombinant protein platforms. Dominant competitive moves include backward integration into controlled pollen cultivation and strategic partnerships with digital health platforms for patient adherence monitoring.
Within the vertically integrated tier, ALK-Abello and Stallergenes Greer exemplify European manufacturing concentration through Denmark and France-based operations. Sanofi anchors the symptomatic relief segment with broad antihistamine and nasal corticosteroid distribution. These three entities represent divergent strategic archetypes: captive supply chain control, sublingual format specialization, and mass-market pharmacy channel dominance respectively.
| Leading Market Players |
|---|
| ALK-Abello |
| Stallergenes Greer |
| Sanofi |
| GlaxoSmithKline |
| Johnson & Johnson |
| Merck & Co. |
| Pfizer |
| Teva Pharmaceuticals |
| Regeneron Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
German statutory health insurance funds concentrate purchasing power for multi-year immunotherapy courses, anchoring a subscription-based pricing model that rewards treatment persistence over episodic transactions. This buyer concentration amplifies negotiating leverage on annual contract renewals while compressing margins for manufacturers lacking differentiated biologics portfolios.
Pricing Analysis
Input-cost pass-through from recombinant allergen purification runs through to sublingual tablet premiums, with Denmark and France-based manufacturing clusters commanding price premiums for certified GMP-grade extracts. Pricing stratifies across premium biologics, standard purified extracts, and economy-grade crude formulations based on molecular specificity and adverse event profile. Cost compression in the symptomatic relief tier intensifies as OTC antihistamine substitution erodes immunotherapy qualification rates. Price sensitivity concentrates among uninsured working-age adults in Southern Europe, while German and Dutch insured populations absorb higher upfront disease-modifying expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Denmark and France for controlled pollen cultivation and recombinant protein purification capacity. Raw material dependencies center on Betula verrucosa birch pollen, Phleum pratense timothy grass, and Ambrosia artemisiifolia ragweed extracts sourced from certified organic cultivation sites. Tariff exposure on diagnostic device components from Swiss and German precision manufacturing clusters threatens real-time forecasting platform deployment timelines. Distribution runs through hospital-affiliated specialty pharmacies for initial immunotherapy induction, with online fulfillment capturing maintenance prescription refills in established treatment populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pollen allergy market functions as a stable compounder underpinned by irreversible environmental pollen load increases that expand the addressable patient base regardless of economic cycles.
For Market Incumbents: Anchor competitive position through backward integration into controlled pollen cultivation networks across Northern France and Jutland Peninsula sites, securing GMP-grade raw material captive supply against extract purity standard escalation. Defend against biologics substitution by accelerating recombinant allergen component portfolio transitions ahead of EMA MDR diagnostic device re-certification deadlines. Channel control through specialist clinic partnerships in Munich and Paris preserves premium pricing access for administered induction protocols. For New Entrants and Emerging Players: The EU AI Act in European member states opens a window for digital health platforms with pre-validated pollen forecasting algorithms to capture high-risk system certification first-mover advantage. Target Southern European immunotherapy penetration gaps in Spain and Italy where subsidized access programs remain underdeveloped relative to German benchmarks. A telemedicine-integrated go-to-market angle bypasses saturated urban clinic capacity constraints while capturing rural diagnostic demand. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with respiratory portfolios are the most active acquirer in this space, seeking sublingual tablet platform capabilities to offset antihistamine patent erosion. Five-to-ten year viability hinges on recombinant biologics transition completion rather than crude extract legacy maintenance. Acquisition target archetypes include mid-scale allergen purification specialists with validated EMA manufacturing authorizations and pediatric indication expansions. Monitor EMA MDR transition compliance backlog resolution as inflection indicator for diagnostic device launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Allergen Platform Transition | ALK-Abello and Stallergenes Greer are retooling Denmark and France facilities toward precision biologics with superior safety margins. |
| Sublingual Tablet Pediatric Expansion | Munich and London specialist practices are normalizing five-year-old eligibility criteria, expanding addressable pediatric volumes. |
| EU AI Act Algorithm Pre-Certification | Dutch and Belgian pharmacy chains pilot bundled membership models integrating validated forecasting tools with medication delivery. |
| Backward Integration into Cultivation | Controlled pollen sourcing from certified organic sites in Northern France secures GMP-grade raw material quality consistency. |
| Online Pharmacy Channel Partnership | Subscription-based fulfillment bypasses clinic capacity constraints in saturated Berlin and Paris metropolitan markets. |
Research Methodology
Direct dialogue with allergy specialist physicians, pharmaceutical regulatory affairs directors, hospital pharmacy procurement managers, and digital health platform engineers grounded qualitative findings in operational reality. Secondary validation drew from EMA MDR submission databases, FDA Biologics License Application filings, national health insurance reimbursement registries, and EU Green Deal air quality monitoring disclosures. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Analytical lens alternated between granular sublingual tablet prescription tracking and aggregate immunotherapy category spend analysis across the projection horizon. Segmentation dimensions spanned product type, end-user life stage, distribution channel format, and regional regulatory cluster. CAGRs were derived from treatment initiation rate trajectories, persistence-adjusted course completion probabilities, and pricing evolution assumptions for recombinant versus extract-based formulations. Forecast inputs incorporated pollen season intensity variability, pediatric protocol adoption curves, and digital pharmacy penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA MDR transition delays, FDA biologics pathway adjudication timelines, and EU AI Act enforcement intensity scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Content Experience Platforms Market
Others
APAC Machine Vision Systems Market
Others
Singapore Retail Market
Others
Roasted Wheat Market
Others
ISO Cylinder Market
Others
Global Sportswear Market
Others
Global Cryogenic Tanks Market
Others
Global Military Apparel Market
Others
Server Market
Others
Digital Supply Chain Market
Others
High Frequency Vibrator Market
Others
Process Spectroscopy Market
Others
Liquid Density Meters Market
Others
Traditional PC Market
Others
Internet of Things Testing Market
Others
Middle East Paper Making Machine Market