
 Mono-Material Trays Market | 2026-2036
Mono-Material Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Mono-Material Trays Market Analytics
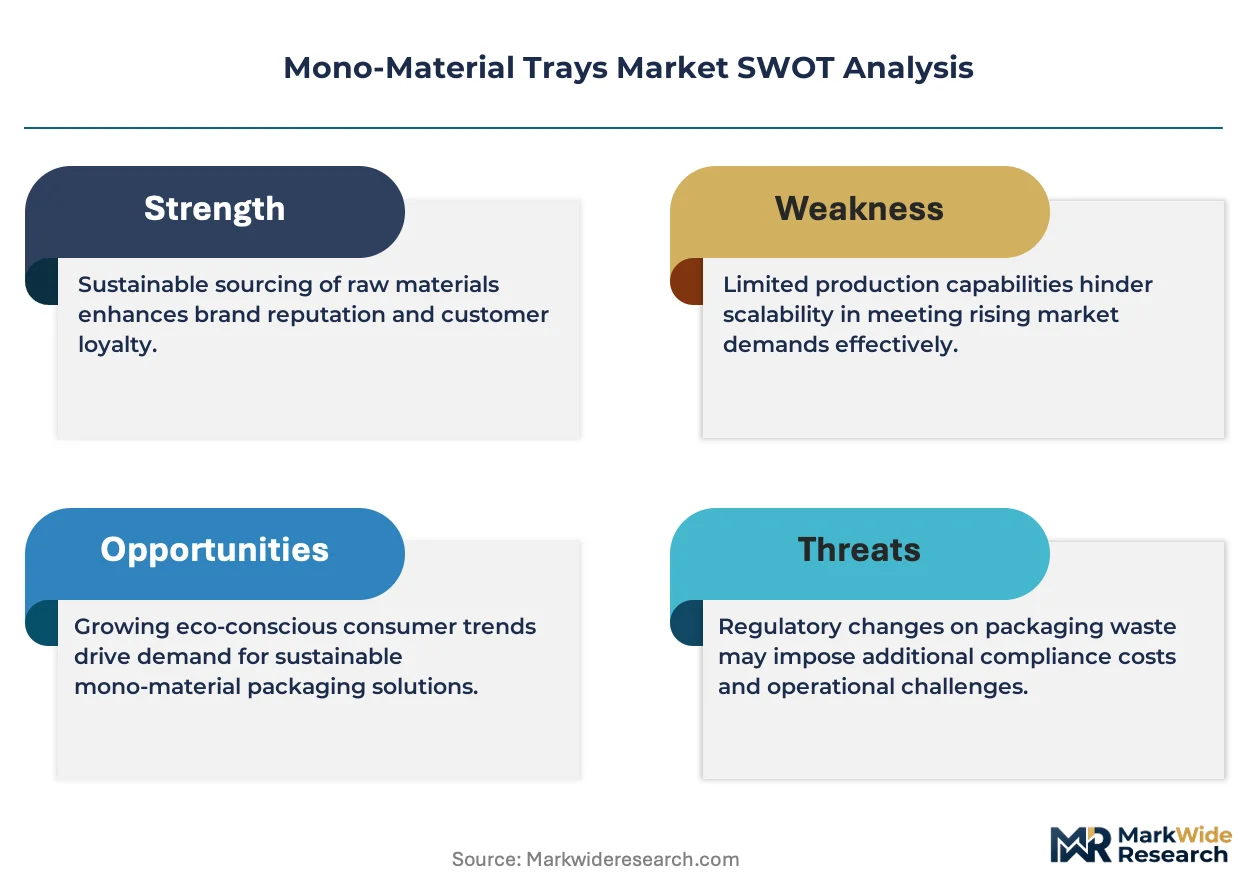
Design-for-recyclability consulting is realigning what converters sell, shifting contracts toward material-certification bundles rather than unit volumes. Faerch Plast leverages its closed-loop recycling infrastructure to secure long-term supply agreements with Nordic retailers. Huhtamaki anchors its position through thermoforming scale across Central European production hubs. Sealed Air Corporation differentiates via automation-integrated tray-sealing systems that reduce line-changeover waste.
Mono-material trays employ a single polymer substrate—typically PET, PP, or polystyrene—to eliminate multi-layer lamination barriers that complicate mechanical recycling streams. Thermoformed variants dominate current production owing to lower tooling costs and faster cycle times for shallow-draw applications. Among materials, plastic grades still lead installed capacity, though biodegradable formulations represent the fastest-expanding margin pool as brand owners seek compostable certifications. Food packaging applications absorb the majority of volume, with retail display trays maturing into a replacement-driven segment rather than a growth category.
EU REACH restrictions on per- and polyfluoroalkyl substances compel reformulation of grease-resistant tray coatings, while EFSA migration limits shape permissible additives in food-contact layers. The EU Green Deal's packaging waste directive tightens recyclability definitions, forcing converters to validate mono-material claims through third-party protocols. Stakeholders must monitor how national extended producer responsibility schemes recalibrate fee structures to penalize non-recyclable formats before committing to capacity expansion.
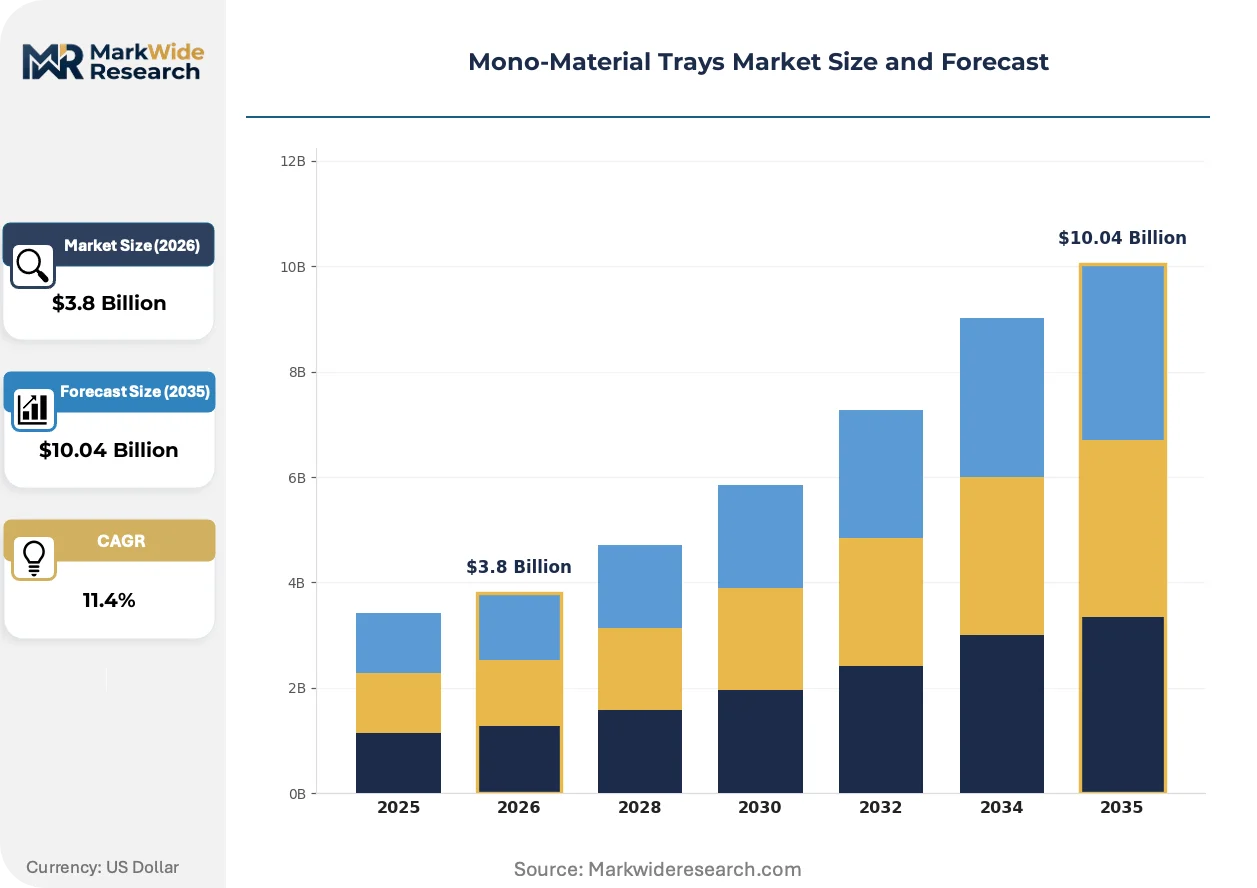
Market Dynamics
Design-for-recyclability mandates are compressing converter business models from commodity volume sales toward certified material bundles, rewiring contract structures and capital allocation priorities across thermoforming supply chains.
Growth Catalysts
- EU Green Deal Packaging Waste Directive:Binding recyclability targets force supermarket private-label programs to specify mono-material formats, pulling PET and PP tray demand upward.
- Closed-loop recycling infrastructure:Nordic retailers now require supply agreements with verified post-consumer feedstock streams, locking in converter capacity commitments.
- Supermarket consolidation:Central European retail chains are standardizing tray specifications across private-label portfolios, reducing SKU complexity and accelerating mono-material conversion.
Market Restraints
- Barrier performance gap:Mono-material substrates lack oxygen and moisture resistance of multi-layer laminates, limiting shelf-life extension for protein applications.
- Post-consumer feedstock scarcity:Food-grade rPET and rPP availability concentrates in Germany and the Netherlands, creating geographic supply bottlenecks.
- EU REACH PFAS restrictions:Grease-resistant coating reformulations face EFSA migration testing timelines that delay new product qualification by 12-18 months.
Strategic Opportunities
- Biodegradable certification pathways:Industrial compostable tray segments in France and Italy attract brand owners seeking differentiation ahead of national extended producer responsibility fee adjustments.
- Automation-integrated sealing systems:Line-changeover waste reduction technologies open retrofit markets among mid-scale ready-meal processors.
- Deposit-return scheme alignment:Germany's DRS expansion to food-contact packaging creates closed-loop collection infrastructure that converters can leverage for certified recycled content claims.
Industry Challenges
- Third-party certification backlog:Recyclability protocol validation through institutes such as Fraunhofer IVV faces 6-9 month queues, delaying contract finalization.
- Thermoforming tool reconfiguration:Shallow-draw to deep-draw transitions for protein trays require multi-cavity mold investments that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mono-Material Trays Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molded, Thermoformed, Extruded, Vacuum Formed Material: Plastic, Paper, Biodegradable, Composite Application: Food Packaging, Electronics, Medical Supplies, Retail Display End User: Food & Beverage, Pharmaceuticals, Retail, Household |
| Companies Covered | Faerch Plast, LINPAC Packaging, Amcor, Mondi Group, Sealed Air Corporation, Huhtamaki, Constantia Flexibles, Berry Global Inc., Wipak Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mono-Material Trays Market Evolving Landscape
Active developments across material science, regulatory enforcement, and buyer procurement models are compressing product development cycles and rewiring competitive differentiation in tray supply chains.
Barrier coating technology is unifying functional performance with mono-material recyclability. Solvent-free plasma deposition processes now achieve oxygen transmission rates comparable to EVOH laminates. Protein processors in Germany and Denmark are piloting these coatings for fresh meat display trays. This unifying capability is collapsing the historical trade-off between shelf-life extension and mechanical recycling compatibility.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from food-contact applications. EFSA migration limit enforcement has accelerated since 2023, compelling coating suppliers to submit novel substance dossiers. Ready-meal segments with fatty acid exposure profiles face the steepest compliance curves, driving reformulation partnerships between chemical suppliers and thermoforming converters.
Retail procurement consolidation is compressing supplier qualification timelines. Central European supermarket chains now mandate mono-material certification as a gate criterion for private-label bidding, displacing incumbent multi-layer suppliers. This pattern concentrates volume with converters holding verified closed-loop feedstock agreements, particularly visible in Nordic and German retail system specifications.
Mono-Material Trays Market Segmentation
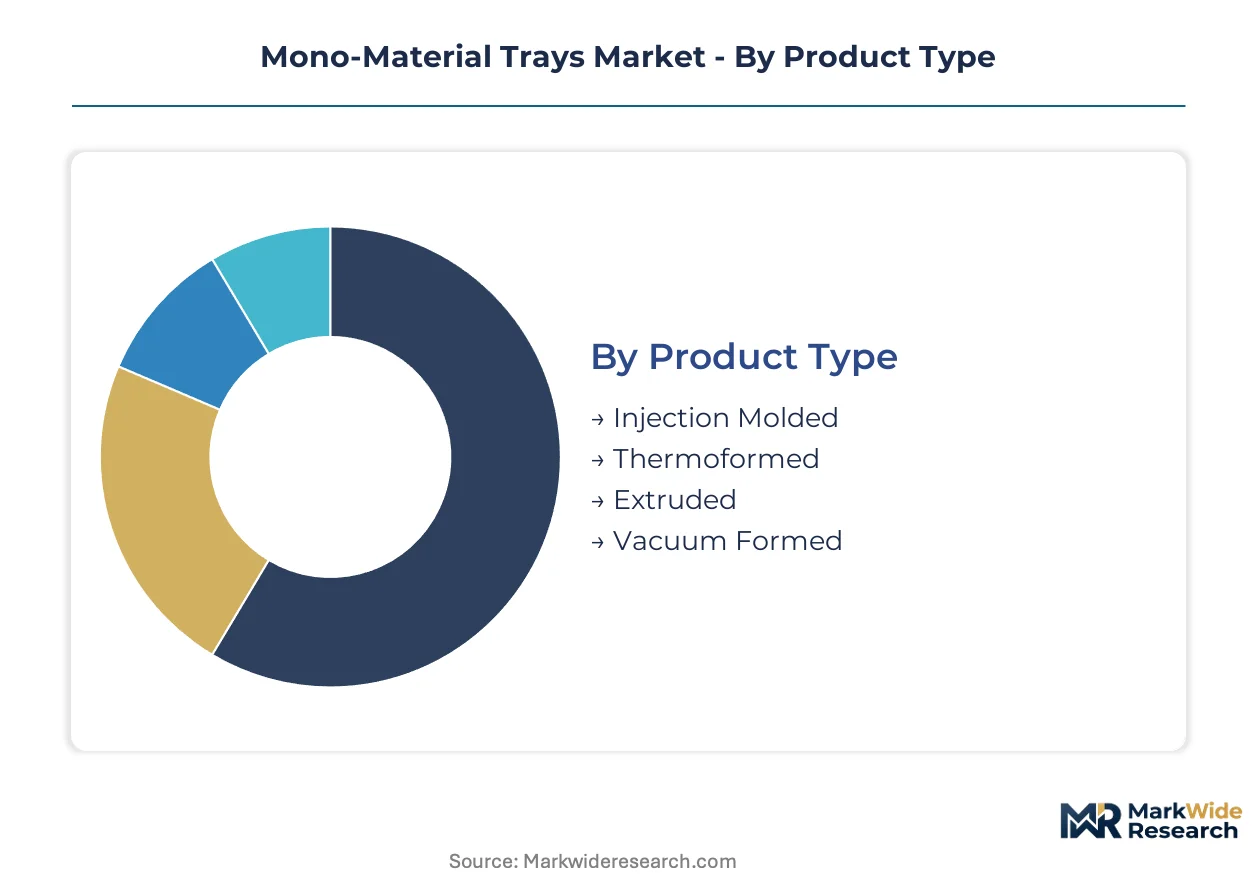
Segmentation in mono-material trays reveals how manufacturing method, substrate choice, and end-use requirements split contract value across incompatible specification tiers. Buyers face trade-offs between thermoforming speed, barrier performance, and recyclability certification that reshape supplier selection criteria.
Product Type:
Converters select forming technology based on draw depth, volume scale, and tooling amortization horizons.
- Thermoformed:Shallow-draw applications dominate current capacity owing to lower mold costs and faster cycle times. German supermarket private-label programs standardize on thermoformed PET for fresh produce display trays, pulling volume through Central European production hubs.
- Injection Molded:Deep-draw geometries and structural rigidity requirements favor this method for protein trays with integral lids. Nordic retailers specify injection molded PP for ready-meal applications requiring extended shelf-life compatibility with modified atmosphere sealing systems.
- Extruded:Continuous sheet production feeds downstream thermoforming operations with calibrated thickness control. The method concentrates in integrated converter facilities serving high-volume bakery and confectionery segments.
- Vacuum Formed:Lower-pressure forming suits thin-gauge applications with minimal draft angles. Specialty electronics packaging and medical blister trays utilize this method where dimensional tolerance requirements are less stringent.
Volume sits with Thermoformed; growth tilts toward Injection Molded.
Material:
Substrate selection hinges on mechanical recycling stream compatibility, food-contact compliance, and brand-owner sustainability commitments.
- Plastic:PET and PP grades retain installed capacity leadership due to established collection infrastructure and EFSA-approved recycling processes. Germany's packaging sector concentrates demand through supermarket conversions to mono-material formats.
- Biodegradable:Industrial compostable formulations attract brand owners in France and Italy seeking differentiation ahead of extended producer responsibility fee adjustments. PLA and starch-based blends face barrier performance constraints for protein applications.
- Paper:Fiber-based trays with polymer barrier coatings serve bakery and dry goods segments where moisture resistance requirements are moderate. Nordic retailers pilot paper alternatives for ambient shelf-stable categories.
- Composite:Hybrid structures combining fiber substrates with thin polymer skins target applications requiring structural integrity without full plastic content. Qualification timelines lag due to recyclability protocol validation requirements.
Plastic captures current volume; biodegradable alternatives are climbing the fastest.
Application:
End-use specifications diverge sharply on barrier performance, migration limits, and display requirements.
- Food Packaging:Fresh meat, produce, and ready-meal segments absorb the majority of mono-material tray volume. EU Green Deal recyclability mandates force supermarket private-label programs to specify mono-material formats, consolidating demand with certified converters.
- Retail Display:Visual presentation requirements drive shallow-draw thermoformed designs with high clarity. This segment matures into replacement-driven demand rather than expansion, with specifications standardizing across Central European chains.
- Electronics:ESD protection and dimensional stability requirements favor injection molded or vacuum formed designs. Contract manufacturers specify trays for component shipping and assembly line presentation.
- Medical Supplies:Sterilization compatibility and migration limit compliance shape material selection. EMA and national health authority requirements extend qualification timelines beyond standard commercial packaging.
Food Packaging dominates volume; Medical Supplies show steepest expansion trajectory.
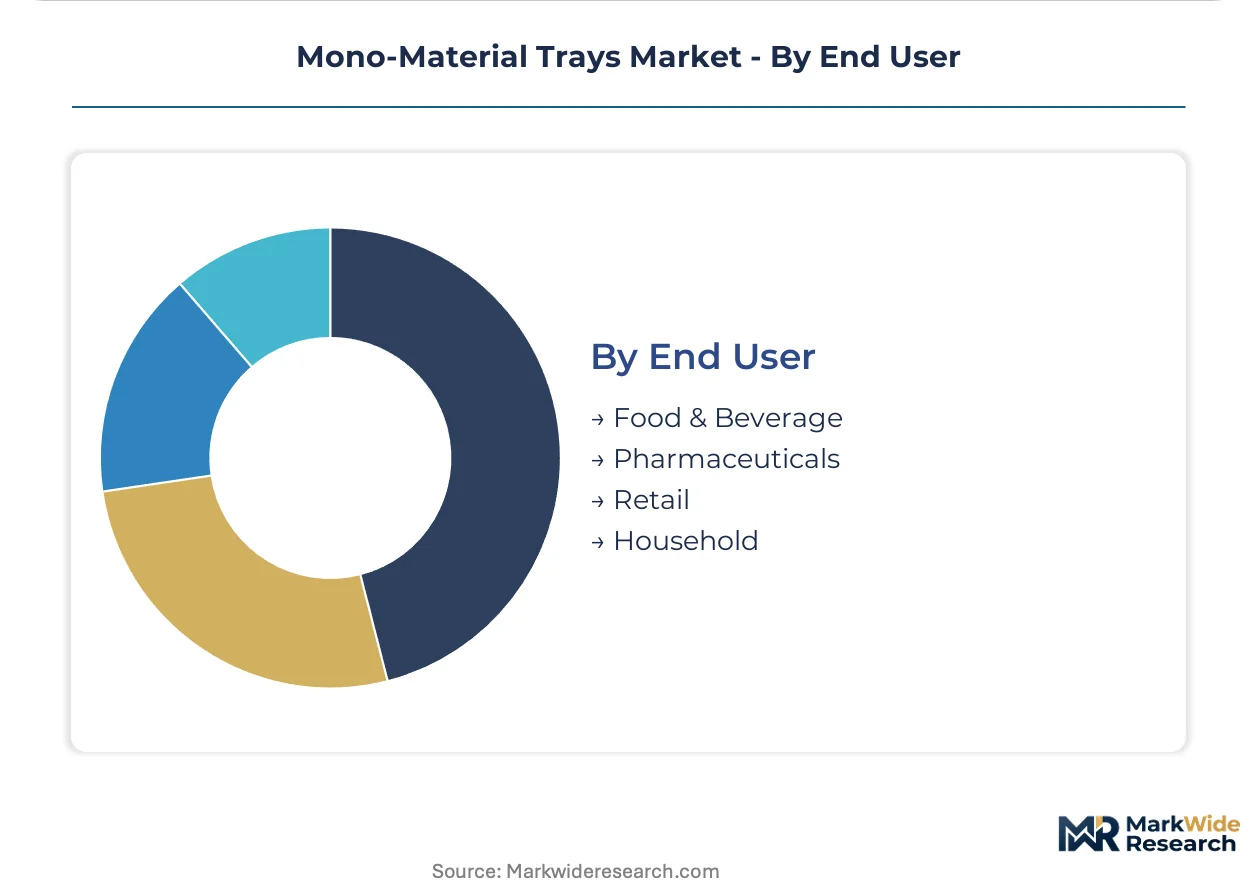
End User:
Procurement consolidation across buyer categories compresses supplier qualification and rewires contract structures toward certified material bundles.
- Food & Beverage:Protein processors, dairy operations, and ready-meal manufacturers drive specification standards. REACH PFAS restrictions on grease-resistant coatings compel reformulation partnerships with chemical suppliers.
- Retail:Supermarket private-label consolidation standardizes tray specifications across portfolios. Nordic and German retail systems now mandate mono-material certification as a gate criterion for bidding.
- Pharmaceuticals:Drug packaging and medical device presentation requirements impose EFSA and EMA migration limit compliance. Extended qualification timelines favor incumbent suppliers with established dossier libraries.
- Household:Consumer goods and cleaning product segments utilize trays for retail multipacks and promotional displays. Price sensitivity concentrates volume with high-throughput thermoforming operations.
Food & Beverage holds volume concentration; Retail procurement shifts are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Northern Europe while Southern European demand accelerates through supermarket private-label mandates. Germany and the Netherlands dominate post-consumer feedstock processing infrastructure. France and Italy pull biodegradable tray volumes through national composting certification pathways.
Germany
Supermarket private-label conversions to mono-material PET and PP formats concentrate demand through the Rhine-Ruhr packaging corridor. The EU Green Deal packaging waste directive binds national extended producer responsibility schemes to penalize non-recyclable formats by 2025. Berlin-based retail consortiums now mandate third-party recyclability certification as a bidding prerequisite, locking contracts with converters holding verified closed-loop agreements.
France
Industrial compostable tray segments attract brand owners seeking differentiation ahead of national extended producer responsibility fee adjustments. EFSA migration limit enforcement on grease-resistant coatings compels reformulation partnerships between chemical suppliers and thermoforming converters. The Lyon-Grenoble chemical cluster houses pilot facilities for solvent-free plasma deposition processes targeting fresh meat display applications.
Italy
Ready-meal processors in the Emilia-Romagna food belt drive specification standards for injection molded PP trays with modified atmosphere sealing compatibility. ANSM enforcement of REACH PFAS restrictions eliminates legacy grease-resistant chemistries from food-contact applications. Bologna-based converters are reconfiguring thermoforming tools for shallow-draw to deep-draw transitions to capture protein tray contracts.
Netherlands
Food-grade rPET and rPP availability concentrates in Rotterdam-Antwerp port corridor recycling facilities, creating geographic supply bottlenecks for converters elsewhere. The country's deposit-return scheme expansion to food-contact packaging generates closed-loop collection infrastructure that certified converters leverage for recycled content claims. Eindhoven-region equipment manufacturers supply automation-integrated sealing systems that reduce line-changeover waste for mid-scale processors.
Sweden
Nordic retailers require supply agreements with verified post-consumer feedstock streams, locking in converter capacity commitments through long-term contracts. The Stockholm-Malmö logistics corridor enables rapid distribution of thermoformed produce trays to supermarket distribution centers. Swedish converters are piloting paper alternatives with polymer barrier coatings for ambient shelf-stable bakery segments.
Mono-Material Trays Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across thermoforming supply chains. Integrated converters with captive recycling infrastructure command premium positioning in Nordic retail procurement. Three archetypes dominate: closed-loop recyclers securing long-term feedstock agreements, scale thermoformers anchoring Central European production hubs, and automation-integrated system providers reducing operational waste for processors. Competitive moves concentrate on strategic partnerships for certified material bundles and capacity expansion near post-consumer feedstock clusters.
Within the closed-loop recycler archetype, Faerch Plast exemplifies positioning through captive recycling infrastructure and long-term Nordic retail agreements. Among scale thermoformers, Huhtamaki occupies a position anchored to Central European production concentration. Sealed Air Corporation sits within the automation-integrated tier, representing system providers that bundle tray-sealing equipment with material supply contracts.
| Leading Market Players |
|---|
| Faerch Plast |
| LINPAC Packaging |
| Amcor |
| Mondi Group |
| Sealed Air Corporation |
| Huhtamaki |
| Constantia Flexibles |
| Berry Global Inc. |
| Wipak Group |
| Others |
Value Network & Pricing Analysis
Thermoforming tool engineers concentrated in the Rhine-Ruhr corridor command wage premiums that widen pricing spreads between certified and uncertified tray tiers. Labor-cost differentials between German toolrooms and Polish satellite operations compress margins on standard-grade contracts while elevating premium-tier spreads for closed-loop certified supply.
Pricing Analysis
Margin tightening in standard-grade thermoformed PET traces to supermarket procurement consolidation across Central European private-label programs. Three-tier pricing structure across premium, standard, and economy levels separates converters with verified closed-loop agreements from commodity volume sellers. Price differentiation hinges on recyclability certification grade and volume scale commitments. Protein processors show highest price sensitivity due to barrier performance requirements, while Nordic retailers demonstrate lowest sensitivity given mandated sustainability procurement gates.
Supply Chain Analysis
Regional distribution centers in Rotterdam-Antwerp and Hamburg feed hub-and-spoke patterns serving supermarket chains across Germany, the Netherlands, and Denmark. Raw material supply draws from food-grade rPET and rPP processing clusters in Germany and the Netherlands, with virgin PET feedstock anchored in Belgian and Dutch petrochemical complexes. Single-source vulnerability concentrates in post-consumer feedstock streams for certified recycled content claims. Distribution runs through retail-owned consolidation centers rather than independent wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material trays occupy a technology-transition phase as plasma-deposited barrier coatings displace legacy PFAS-based grease-resistant chemistries. This substitution wave rewires competitive positioning around coating qualification timelines and EFSA migration compliance dossiers.
For Market Incumbents: Acquire solvent-free plasma deposition coating assets to secure barrier performance parity with multi-layer laminates. Lock long-term post-consumer feedstock agreements before Germany's deposit-return scheme expansion to food-contact packaging concentrates supply. Defend against mid-cap converters with reconfigured thermoforming tools by accelerating deep-draw protein tray certification. For New Entrants and Emerging Players: The premium-to-economy price gap in industrial compostable trays invites mid-tier positioning for French and Italian brand owners ahead of extended producer responsibility fee adjustments. Target ready-meal processors in the Emilia-Romagna belt seeking modified atmosphere sealing compatibility without incumbent converter backlog. Enter through biodegradable certification partnerships with Lyon-Grenoble chemical cluster pilot facilities. For Investors and Strategic Acquirers: Re-rating potential sits with closed-loop recyclers given EU Green Deal packaging waste directive enforcement tightening recyclability definitions. Five-to-ten-year viability favors converters with captive recycling infrastructure and verified Nordic retail agreements. Watch Fraunhofer IVV certification queue lengths as inflection indicator for contract velocity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure Investment | Secures long-term feedstock agreements with Nordic retailers mandating verified post-consumer streams. |
| Solvent-Free Plasma Deposition Partnership | Collapses barrier performance gap with EVOH laminates for German protein tray applications. |
| Thermoforming Tool Reconfiguration | Enables deep-draw protein tray capture for Bologna-based converters competing on shelf-life extension. |
| Biodegradable Certification Pathway | Opens French and Italian segments ahead of national extended producer responsibility fee adjustments. |
| Automation-Integrated Sealing System Deployment | Reduces line-changeover waste for mid-scale ready-meal processors in Central European production hubs. |
Research Methodology
Document review covered EU regulatory filings, EFSA migration limit dossiers, and supermarket private-label specification sheets, complemented by interviews with thermoforming plant managers, retail procurement leads at Central European chains, coating technology R&D directors, and post-consumer recycling facility operators. Secondary validation drew from customs trade data, SEC filings of listed packaging converters, and extended producer responsibility scheme fee schedules. Bottom-up volume estimates triangulated against top-down market sizing across material-grade and application segments.
Historical shipment data cross-referenced against expert panel inputs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include manufacturing method, substrate material, end-use application, and buyer procurement consolidation tier. CAGRs were derived from slope analysis of verified contract volumes and capacity expansion announcements. Industry-specific forecast inputs incorporated EFSA migration testing timelines and third-party recyclability protocol validation queues.
Inputs from retail procurement databases and converter capacity announcements were available through the study window; gaps in confidential contract pricing introduce uncertainty bands around tier-level spreads. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and feedstock infrastructure buildout. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
APAC Rigid Plastic Packaging Market