
 GCC Gas Hobs Market | 2026-2036
GCC Gas Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Gas Hobs Market Insights
Restaurant kitchen specifications across the GCC is hardening demand for commercial-grade gas hobs with higher burner output and flame stability. Siemens leverages its European engineering heritage to anchor premium positioning in UAE fit-out projects. Haier competes aggressively on cost-optimized stainless steel platforms for Saudi residential developments. Bosch sustains technology leadership through precision flame control systems that appeal to hotel operators in Dubai and Abu Dhabi.
A gas hob is a cooking appliance comprising one or more gas burners mounted on a flat surface, typically constructed from stainless steel, tempered glass, or cast iron, with thermal outputs ranging from 3 kW to 5 kW per burner depending on configuration. The device converts pressurized natural gas or LPG into controlled flame for direct-heat food preparation in residential and commercial kitchens. Built-in hobs dominate value capture across GCC markets due to seamless countertop integration demanded by modern kitchen design, while freestanding units retain volume traction in labor-camp and budget residential segments. Stainless steel material configurations lead commercial installations for durability under intensive use, whereas glass surfaces differentiate premium residential offerings through aesthetic alignment with contemporary interiors.
The Emirates Authority for Standardization and Metrology enforces ESMA certification for gas appliance safety, directly conditioning market access for non-compliant imports into the UAE. Saudi Standards, Metrology and Quality Organization mandates SASO energy efficiency labeling that shapes product specifications for Kingdom-bound shipments. The Gulf Standardization Organization's regional technical regulations create harmonized compliance thresholds across Bahrain, Kuwait, Oman, Qatar, and Saudi Arabia, reducing fragmentation but raising baseline manufacturing costs. Stakeholders must monitor evolving efficiency tiers and safety shut-off mandates as these frameworks tighten, while positioning procurement and R&D investments to preempt rather than react to regulatory shifts.
Market Dynamics
Restaurant kitchen modernization across Saudi Arabia and the UAE is hardening demand specifications toward commercial-grade gas hobs with higher thermal output and flame stability, compressing replacement cycles and reshaping procurement criteria across the GCC.
Growth Catalysts
- ESMA Certification Mandates:The Emirates Authority for Standardization and Metrology enforces safety standards that accelerate replacement of aging units in UAE hospitality fit-outs.
- Hospitality Construction Clusters:Riyadh and Jeddah corridors in Saudi Arabia anchor active commercial kitchen deployment, hardening demand for built-in stainless steel configurations.
- Flame Control Engineering:Precision burner systems with thermal outputs exceeding 4 kW per burner are displacing conventional platforms in premium hotel operator specifications.
Market Restraints
- Stainless Steel Input Volatility:Raw material cost swings for commercial-grade 304 stainless compress margin structures for mid-tier manufacturers serving budget residential segments.
- Import Concentration Risk:Manufacturing gravity in East Asian supply bases creates lead-time exposure and currency-hedging complexity for GCC distributors.
- LPG Infrastructure Gaps:Piped natural gas penetration remains uneven across Oman and Bahrain, limiting addressable market for high-output natural gas configurations.
Strategic Opportunities
- Qatar Hospitality Pipeline:Preparations for expanded tourism capacity are generating tender activity for commercial kitchen equipment ahead of venue commissioning.
- SASO Efficiency Tiers:Saudi Standards, Metrology and Quality Organization labeling mandates create first-mover positioning for manufacturers preempting stricter energy classifications.
- Glass Surface Convergence:Aesthetic alignment with contemporary residential interiors is opening premium price-band capture beyond traditional stainless steel dominance.
Industry Challenges
- Certification Timeline Compression:Gulf Standardization Organization harmonization efforts require simultaneous multi-market testing, extending product launch schedules.
- Technical Service Networks:After-sales support infrastructure for precision flame control systems remains underdeveloped outside Dubai and Riyadh metropolitan zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Gas Hobs Market |
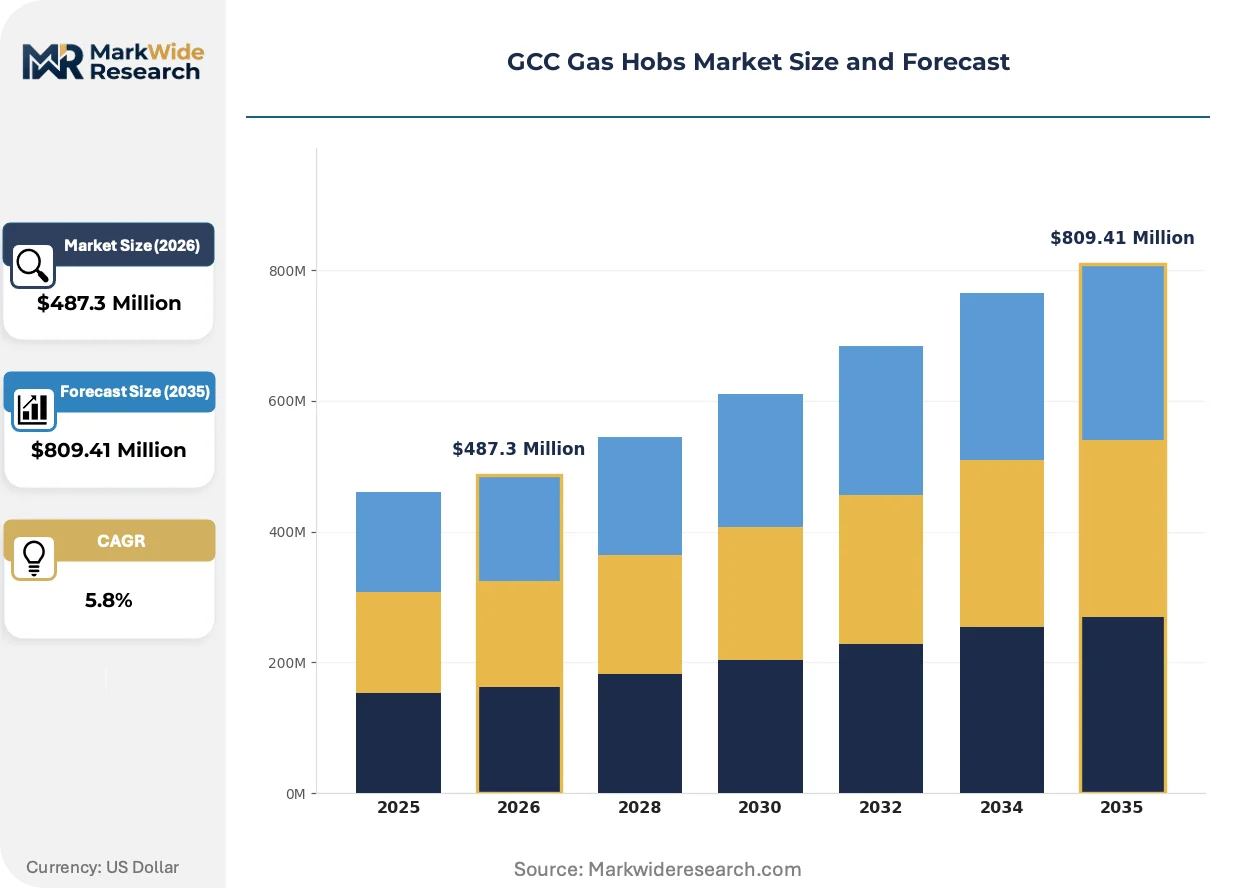
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in Hobs, Freestanding Hobs, Portable Hobs, Commercial Hobs End User: Residential, Restaurants, Hotels, Catering Services Material: Stainless Steel, Cast Iron, Glass, Aluminum Features: Automatic Ignition, Safety Shut-off, Flame Control, Multi-Cooking Zones |
| Companies Covered | Siemens, Sonashi, Electrolux, Whirlpool, Nikai, Haier, Milton, Electrolux AB, Bosch, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Gas Hobs Market Trends and Innovations
Flame stability engineering and surface material evolution are consolidating competitive positioning across the GCC, while regulatory tightening and procurement professionalization reshape how buyers evaluate lifecycle cost against upfront capital outlay.
Tempered glass cooktop surfaces are consolidating share in premium residential segments across Dubai and Abu Dhabi. High-net-worth buyers prioritize aesthetic integration with open-plan kitchen designs. This material shift is compressing traditional stainless steel dominance in the above-3,500 SAR price band.
SASO energy efficiency labeling mandates from the Saudi Standards, Metrology and Quality Organization are compressing product development timelines. Manufacturers must now validate burner performance across standardized test protocols before Kingdom entry. Hotel operators in Jeddah and Riyadh are responding by specifying certified units exclusively, filtering non-compliant imports from tender consideration.
Centralized procurement through hospitality management groups is displacing fragmented site-level purchasing across the UAE. Operators like Emaar Hospitality and Rotana are consolidating vendor relationships to secure volume pricing and standardized maintenance protocols. This concentration is most visible in Dubai's new-build hotel pipeline, where group-level frameworks override individual property discretion.
GCC Gas Hobs Market Segmentation
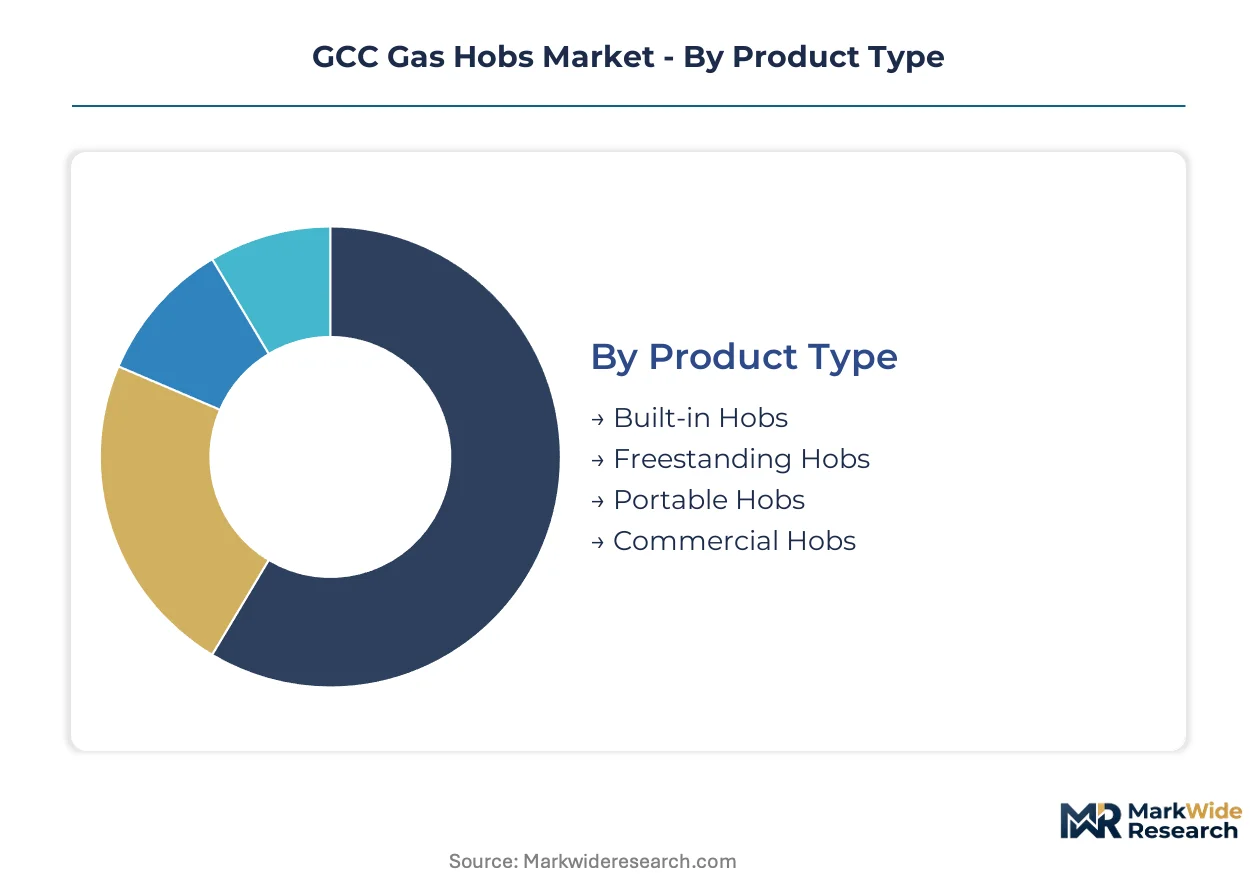
Segmentation in the GCC gas hobs market reveals how procurement criteria diverge between hospitality operators prioritizing thermal output and residential buyers emphasizing aesthetic integration. Understanding these fault lines enables manufacturers to align R&D investments with the specific compliance and performance thresholds governing each buyer category.
Product Type:
Installation permanence drives buyer decision-making, with countertop integration requirements separating premium fit-outs from budget deployments.
- Built-in Hobs:These units embed flush into kitchen countertops, requiring precise cutout specifications and seamless surface alignment. Demand concentrates in Dubai and Abu Dhabi hotel fit-outs where open-plan kitchen visibility elevates design standards. ESMA certification mandates accelerate replacement of non-compliant legacy units in UAE hospitality renovations.
- Freestanding Hobs:Self-contained units with integrated bases allow flexible positioning without permanent installation. Labor camps and budget residential compounds across Saudi Arabia's Riyadh corridor favor these configurations for deployment speed and minimal fit-out cost.
- Portable Hobs:Compact single-burner units designed for temporary or mobile food preparation. Catering operators in Qatar's expanding hospitality pipeline deploy these for off-site events and venue soft openings.
- Commercial Hobs:Heavy-duty platforms with reinforced grates and sustained high-output operation. Jeddah restaurant clusters specify these for intensive wok and tandoor-style cooking requiring flame stability above 4 kW per burner.
Built-in hobs lead on scale; commercial hobs lead on momentum.
End User:
Volume concentration varies sharply across buyer types, with procurement centralization in hospitality groups reshaping vendor relationship structures.
- Residential:Individual households and apartment developers specifying kitchen packages for new-build towers. Glass surface preferences in Abu Dhabi high-end residential towers are displacing stainless steel above the premium price threshold.
- Restaurants:Independent and chain dining establishments requiring durable daily-cycle operation. Kitchen modernization across Saudi Arabia is compressing replacement cycles from ten-year to six-year intervals.
- Hotels:Managed properties under group procurement frameworks. Emaar Hospitality and Rotana are consolidating vendor relationships to secure standardized maintenance protocols across Dubai's new-build pipeline.
- Catering Services:Event and institutional food service operators with intermittent high-volume demands. Preparations for expanded tourism capacity in Qatar are generating tender activity ahead of venue commissioning.
Residential captures volume dominance; hotels exhibit the steepest expansion trajectory.
Material:
Surface composition directly determines thermal mass, cleaning protocols, and aesthetic positioning across price bands.
- Stainless Steel:Commercial-grade 304 alloy dominates restaurant installations for durability under intensive use. Raw material cost volatility compresses margin structures for mid-tier manufacturers serving budget segments.
- Cast Iron:Heavy grates and burner housings providing thermal retention for sustained high-output cooking. Traditional establishments in Saudi Arabia's central region specify these for heavy-utensil compatibility.
- Glass:Tempered ceramic surfaces enabling contemporary aesthetic alignment. High-net-worth buyers in Dubai prioritize open-plan kitchen integration, consolidating share in the above-3,500 SAR residential band.
- Aluminum:Lightweight burner components and trim elements reducing unit weight for transport cost optimization. Budget manufacturers targeting Oman and Bahrain labor-camp segments favor this material for landed cost control.
Stainless steel anchors commercial scale; glass gains share fastest in residential premium tiers.
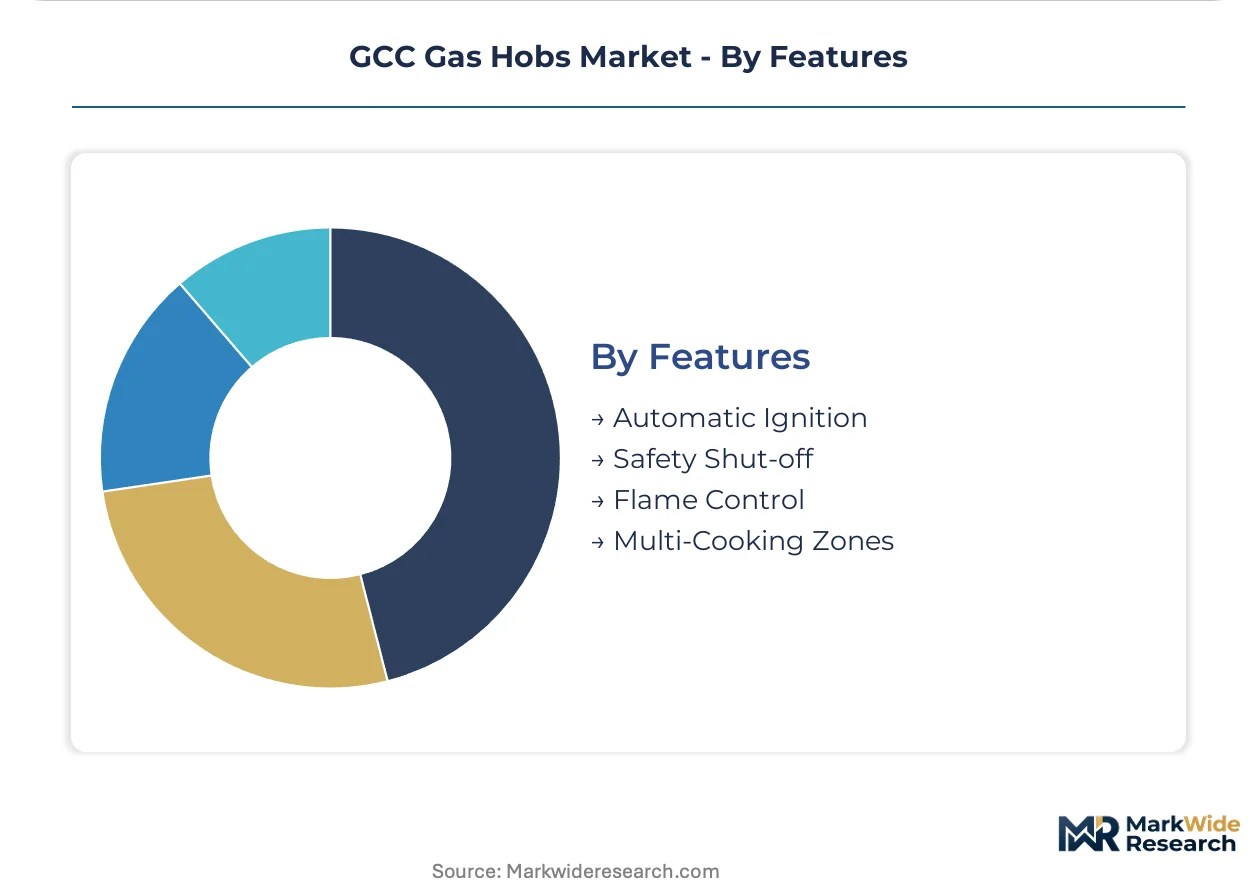
Features:
Safety and precision engineering are becoming non-negotiable in procurement specifications, with regulatory mandates filtering non-compliant imports from tender consideration.
- Automatic Ignition:Piezoelectric or battery-powered spark systems eliminating manual lighting. SASO energy efficiency labeling mandates in Saudi Arabia require validated ignition performance across standardized test protocols.
- Safety Shut-off:Flame failure devices cutting gas supply when burner extinguishes. UAE ESMA certification mandates accelerate replacement of aging units lacking this protection in hospitality fit-outs.
- Flame Control:Precision modulation systems enabling graduated thermal output. Hotel operators in Jeddah and Riyadh specify certified units exclusively, filtering non-compliant imports from tender pools.
- Multi-Cooking Zones:Varied burner sizes and outputs accommodating simultaneous preparation modes. Centralized procurement through hospitality management groups is standardizing these configurations across UAE property portfolios.
Flame control leads on specification priority; safety shut-off tightens fastest as regulatory floor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh and Jeddah corridors anchor commercial kitchen deployment across the GCC, with hospitality construction clusters hardening demand for built-in stainless steel configurations and precision flame control systems.
Saudi Arabia
Kitchen modernization across Riyadh and Jeddah restaurant clusters compresses replacement cycles from ten-year to six-year intervals. SASO energy efficiency labeling mandates from the Saudi Standards, Metrology and Quality Organization filter non-compliant imports from tender consideration. Western Region hospitality developments specify certified commercial hobs exclusively for new-build properties.
United Arab Emirates
ESMA certification mandates accelerate replacement of aging units in Dubai and Abu Dhabi hospitality fit-outs. The Emirates Authority for Standardization and Metrology enforces safety shut-off requirements that reshape procurement criteria. Centralized procurement through Emaar Hospitality and Rotana consolidates vendor relationships across Dubai's new-build hotel pipeline.
Qatar
Preparations for expanded tourism capacity generate tender activity for commercial kitchen equipment ahead of venue commissioning. The country's national standardization body aligns with Gulf Standardization Organization harmonization efforts. Doha hospitality developments specify high-output burner configurations for intensive cooking applications.
Kuwait
Residential tower construction in metropolitan zones drives demand for glass-surface built-in hobs. National quality infrastructure mandates shape import specifications for kitchen appliance categories. Urban development corridors concentrate fit-out activity for premium residential segments.
Oman
LPG infrastructure gaps limit addressable market for high-output natural gas configurations outside Muscat metropolitan zones. The country's national standards organization participates in Gulf Standardization Organization technical harmonization. Labor-camp and budget residential segments favor freestanding units for deployment speed.
GCC Gas Hobs Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers align with hospitality management groups for volume pricing and standardized maintenance protocols. The vendor base organizes around three tiers: European engineering specialists, East Asian cost-optimized platforms, and regional distribution-focused assemblers. Technology licensing and portfolio diversification represent the primary competitive vectors as flame control engineering becomes a procurement differentiator.
Within the European engineering tier, Siemens and Bosch exemplify precision flame control positioning for premium hospitality specifications. Haier occupies a position among cost-optimized stainless steel platform providers targeting Saudi residential developments. These three anchors illustrate how geographic origin and engineering heritage shape competitive archetype differentiation across the GCC procurement landscape.
| Leading Market Players |
|---|
| Siemens |
| Sonashi |
| Electrolux |
| Whirlpool |
| Nikai |
| Haier |
| Milton |
| Electrolux AB |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
Precision flame control engineering is compressing manufacturing economics while concentrating procurement power among hospitality groups capable of certifying multi-burner platforms across ESMA and SASO protocols simultaneously.
Pricing Analysis
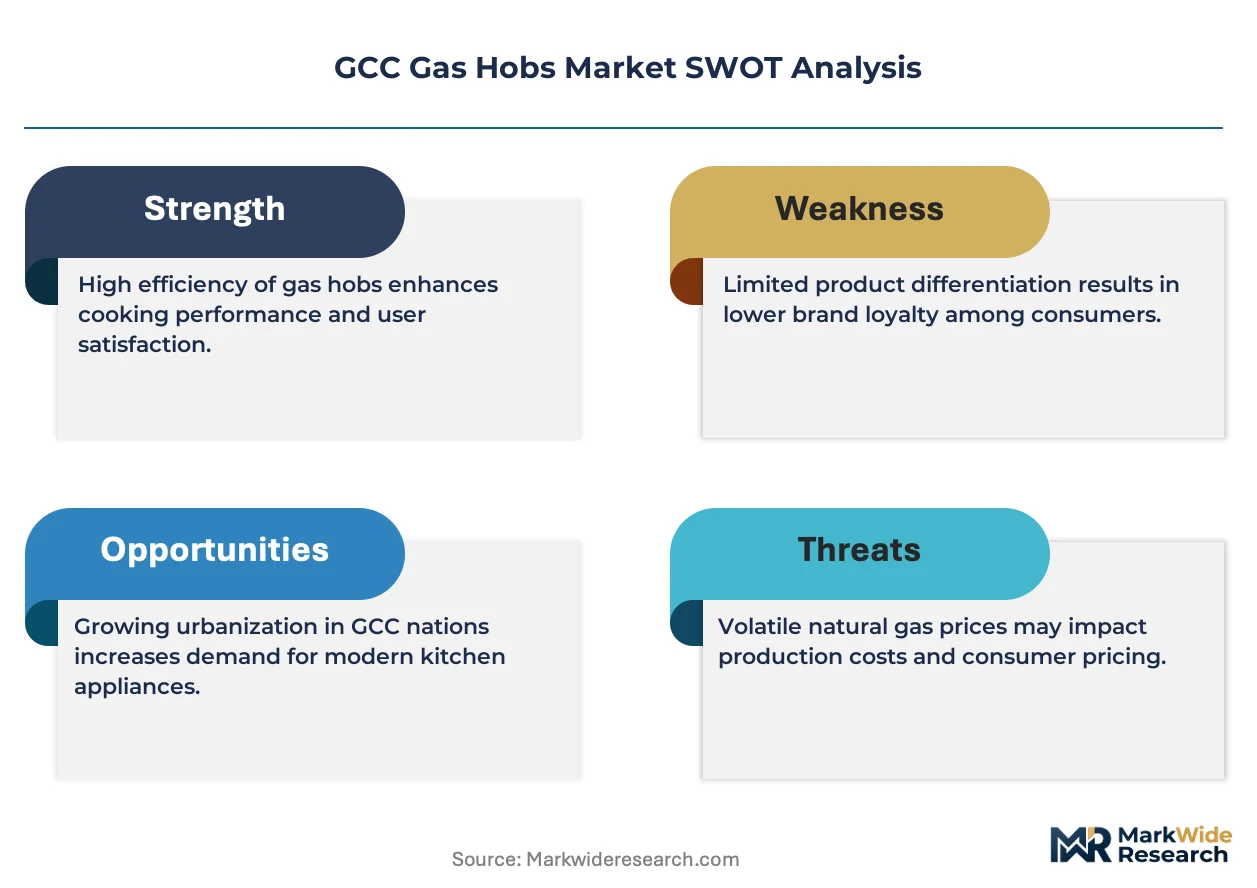
Input-cost pass-through from commercial-grade 304 stainless steel volatility is compressing margin structures for mid-tier manufacturers serving Saudi Arabia's budget residential segments. Pricing stratifies across premium, standard, and economy tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Price erosion runs through the economy tier as East Asian imports compete on landed cost. Labor-camp buyers in Oman exhibit highest price sensitivity; Dubai hotel operators under Emaar Hospitality frameworks prioritize lifecycle cost over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with East Asian manufacturing gravity for burner control systems and tempered glass cooktop substrates. Production draws from China, South Korea, and Taiwan for precision ignition modules and safety shut-off assemblies. Raw material dependencies center on 304 stainless steel, cast iron grates, and aluminum trim components. Tariff exposure on Chinese-origin components creates landed cost unpredictability for GCC distributors. Distribution runs through hospitality procurement consortia and regional appliance assemblers with in-country warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC gas hobs market functions as a stable compounder anchored by mandatory replacement cycles driven by tightening ESMA and SASO safety mandates across the region's hospitality construction pipeline.
For Market Incumbents: Anchor market position through backward integration into stainless steel component fabrication to defend against raw material volatility. Deepen certification investment across GSO harmonization pathways to preempt regulatory timeline compression. Control channel relationships with Emaar Hospitality and Rotana procurement frameworks to lock out emerging competitors.
For New Entrants and Emerging Players: Capture white-space in Qatar's pre-commissioning hospitality tender activity ahead of venue openings. Penetrate Oman's LPG-dominant labor-camp segment with freestanding configurations bypassing natural gas infrastructure gaps. Deploy direct contracting with Saudi restaurant clusters in Jeddah's modernization corridor as entry vector.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution-focused assemblers lacking in-house flame control engineering. Long-term viability over a five-to-ten year window favors targets with established ESMA certification and Dubai-based service networks. Watch SASO efficiency tier advancement as signal for accelerated replacement demand in Saudi Arabia.
| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Certification Pre-Investment | Secures UAE market access before safety shut-off mandates tighten further. |
| Backward Integration into Stainless Components | Captures margin compression from 304 alloy price volatility in commercial segments. |
| Hospitality Procurement Consortium Partnership | Locks volume pricing with Emaar Hospitality and Rotana framework agreements. |
| Glass Surface Manufacturing Capability | Opens premium residential price bands above 3,500 SAR in Dubai and Abu Dhabi. |
| Qatar Pre-Commissioning Tender Positioning | Captures commercial kitchen equipment demand ahead of expanded tourism capacity. |
Research Methodology
Coverage spans Saudi Arabia, UAE, Qatar, Kuwait, and Oman, with primary inputs from each market combining interviews with hospitality procurement directors, commercial kitchen equipment distributors, ESMA certification consultants, and restaurant operations managers. Secondary validation draws from SASO energy efficiency labeling databases, GSO technical regulation harmonization documents, UAE customs import records, and hospitality construction pipeline filings. Bottom-up demand estimation and top-down market sizing triangulate volume and value outputs.
Granularity-level modeling disaggregates the analysis window by product type, end user, material configuration, and feature set, with additional dimensioning by regulatory compliance tier and burner output specification. CAGRs derive from segment-level growth trajectory blending with macroeconomic indicators across the projection horizon. Forecast inputs incorporate hospitality construction completion schedules, SASO efficiency tier evolution, and ESMA certification timeline compression.
Regulatory enforcement variance, raw material price volatility, and hospitality construction delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about certification pathway timelines and procurement centralization trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Cat Hair Remover Market
Household Items
Portable Humidifiers Market
Household Items
Shower Heads and Systems Market
Household Items
Smart Bathroom Products Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Hand-Held Vacuum Cleaner Market
Household Items
Netherlands Cookware Market
Household Items
Neck Pillows Market
Household Items
Knife Market
Household Items
North America Glassware Market
Household Items
Europe Digital Showers Market
Household Items
Commercial Locker Market
Household Items
Smart Fridge Market
Household Items
Gel Warmers Market
Household Items
Portable Car Vacuum Market
Household Items
India Digital Showers Market