
 Portable Car Vacuum Market | 2026-2036
Portable Car Vacuum Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Car Vacuum Market Analytics
Chinese contract manufacturers is broadening output of brushless motor cores for portable car vacuums, expanding the supply base beyond traditional appliance hubs. Dyson Ltd leverages proprietary cyclone geometry to sustain premium positioning in cordless segments. Black+Decker anchors mass-market distribution through big-box automotive aisles in the United States. Fanttik specializes in compact lithium-ion form factors aimed at gig economy drivers.
A portable car vacuum is a compact suction device engineered for automotive interiors, typically operating at 12V DC or 18V-20V lithium-ion battery platforms with airflow rates between 15 and 35 cubic feet per minute to extract debris from upholstery crevices and carpet pile. Its primary commercial purpose is to maintain vehicle resale value and hygiene standards without fixed installation infrastructure. Cordless battery-powered configurations now capture the fastest expansion as lithium energy density improves and fleet operators abandon tethered units. HEPA filtration technology commands margin concentration among allergy-sensitive residential buyers, while wet-and-dry product types dominate commercial automotive detailer procurement.
The US Consumer Product Safety Commission enforces electrical safety standards for lithium-ion battery systems in handheld appliances, limiting entry of uncertified imports. The EU Ecodesign Directive and CE marking requirements mandate minimum motor efficiency thresholds and recyclable material content, reshaping supplier compliance costs. California's Title 20 appliance efficiency regulations extend these constraints to units sold through West Coast distribution channels. Stakeholders must monitor pending battery passport traceability rules and decide whether to front-run compliance through modular motor architectures or absorb retrofit costs later.
Market Dynamics
Lithium-ion energy density gains and fleet operator procurement protocols are compressing demand toward cordless platforms while EU motor efficiency mandates force component redesign across supplier tiers.
Growth Catalysts
- Ride-sharing fleet protocols:North American fleet operators are expanding in-house detailing to reduce third-party service costs, creating bulk procurement channels for commercial-grade cordless units.
- Ecodesign for Sustainable Products Regulation:The EU framework pressures manufacturers to eliminate single-use vacuum bags and improve motor efficiency, accelerating modular motor architecture adoption.
- Brushless motor core supply:Chinese contract manufacturers are broadening output of brushless motor cores, expanding the supply base beyond traditional appliance hubs and reducing component bottlenecks.
Market Restraints
- Lithium-ion input volatility:Battery-grade lithium carbonate price swings compress margin stability for cordless platform manufacturers dependent on cylindrical cell supply.
- Certification friction:US Consumer Product Safety Commission electrical safety standards for lithium-ion systems limit entry of uncertified imports, raising compliance capital requirements.
- HEPA filtration cost structure:Pleated HEPA media and sealed gasket systems add 15-25% to bill-of-materials costs, constraining penetration in price-sensitive residential segments.
Strategic Opportunities
- Battery passport traceability:Pending EU battery passport rules create first-mover advantage for manufacturers front-running compliance through modular motor architectures with embedded traceability.
- Gig economy driver segment:Compact lithium-ion form factors targeting independent ride-share and delivery drivers represent underpenetrated demand in urban mobility corridors.
- Wet-and-dry commercial procurement:Automotive detailer channels are consolidating specification standards, creating white space for OEM-authorized service networks sourcing in bulk.
Industry Challenges
- Motor efficiency certification timelines:CE marking and California Title 20 testing protocols extend product launch cycles by 8-14 months, compressing competitive response windows.
- Cyclone geometry IP complexity:Proprietary multi-cyclone separation patents held by incumbent premium manufacturers create licensing barriers for mid-tier entrants seeking HEPA-equivalent performance without bag systems.
- Supply chain reconfiguration costs:Shifting motor production from traditional appliance hubs to brushless-specialized contract manufacturers requires tooling capital and qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Car Vacuum Market |
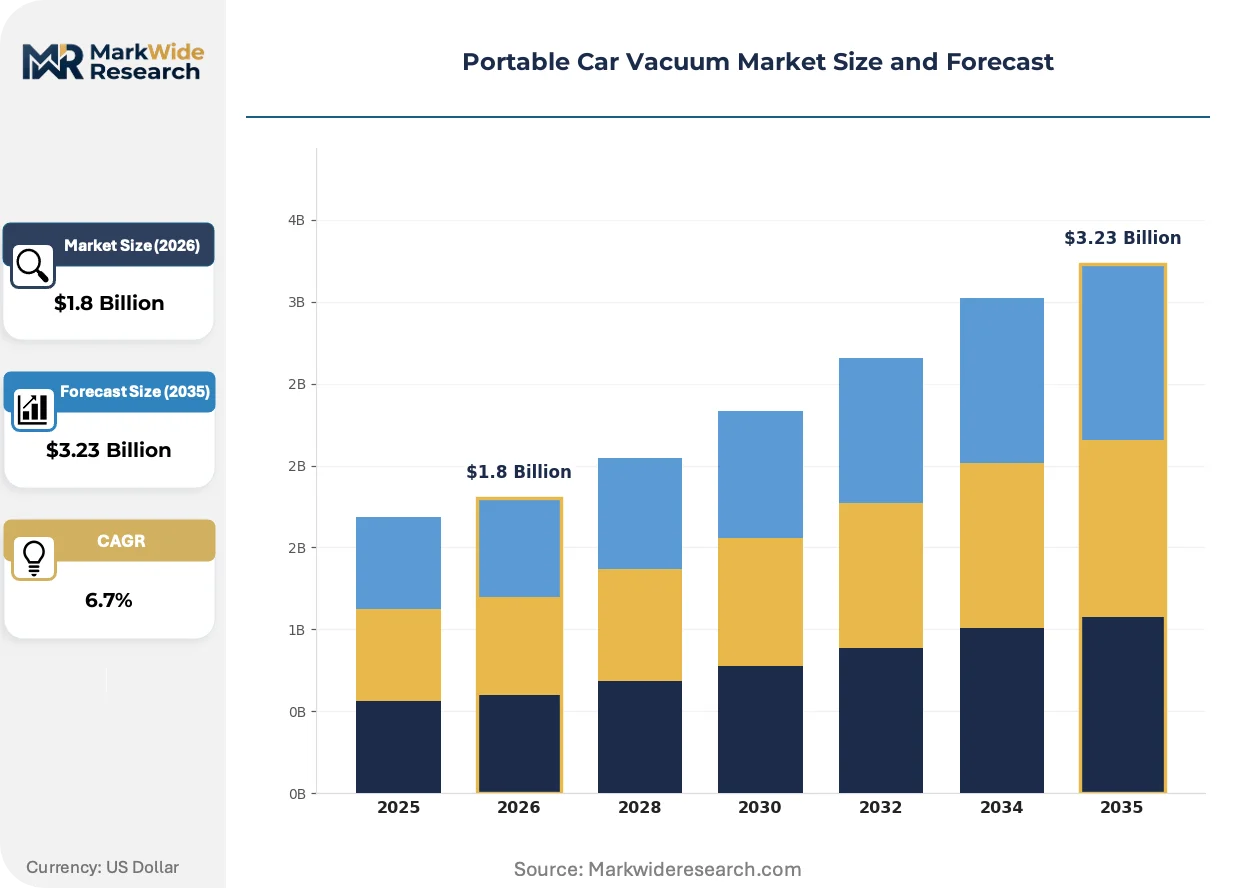
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet & Dry, Handheld, Cordless, Wall-Mounted Technology: Bagless, Cyclonic, HEPA, Brushless Power Source: Battery-Powered, Corded Electric, Solar-Powered, Hybrid End User: Residential, Commercial, Automotive Detailers, Fleet Services |
| Companies Covered | Dyson Ltd, SharkNinja Inc, Bissell Inc, Black+Decker, iRobot Corporation, Hoover Inc, Fanttik, ThisWorx, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Car Vacuum Market Evolving Landscape
Cordless powertrains, regulatory efficiency mandates, and fleet procurement centralization are restructuring competitive advantage around battery chemistry and motor control firmware rather than suction hardware alone.
Brushless DC motor control with field-oriented commutation algorithms is absorbing the performance gap between battery and corded platforms. Fleet operators in Germany's automotive aftermarket cluster are specifying these units for daily interior protocols. The technology is absorbing what had been a tethered-only performance tier, enabling full cordless conversion in commercial settings.
California's Title 20 appliance efficiency regulations extend EU Ecodesign Directive motor efficiency thresholds to West Coast distribution channels. Manufacturers must redesign stator laminations and magnet arrays to meet combined jurisdiction requirements. Cordless lithium-ion platforms face the tightest compliance burden due to battery-to-motor energy conversion losses.
Fleet procurement departments are consolidating supplier rosters around OEM-authorized detailing networks. Independent operators and gig drivers are losing access to bulk pricing tiers as volume concentrates through fleet management companies. This concentration is most visible in North American urban mobility corridors where ride-sharing density supports dedicated cleaning infrastructure.
Portable Car Vacuum Market Segmentation
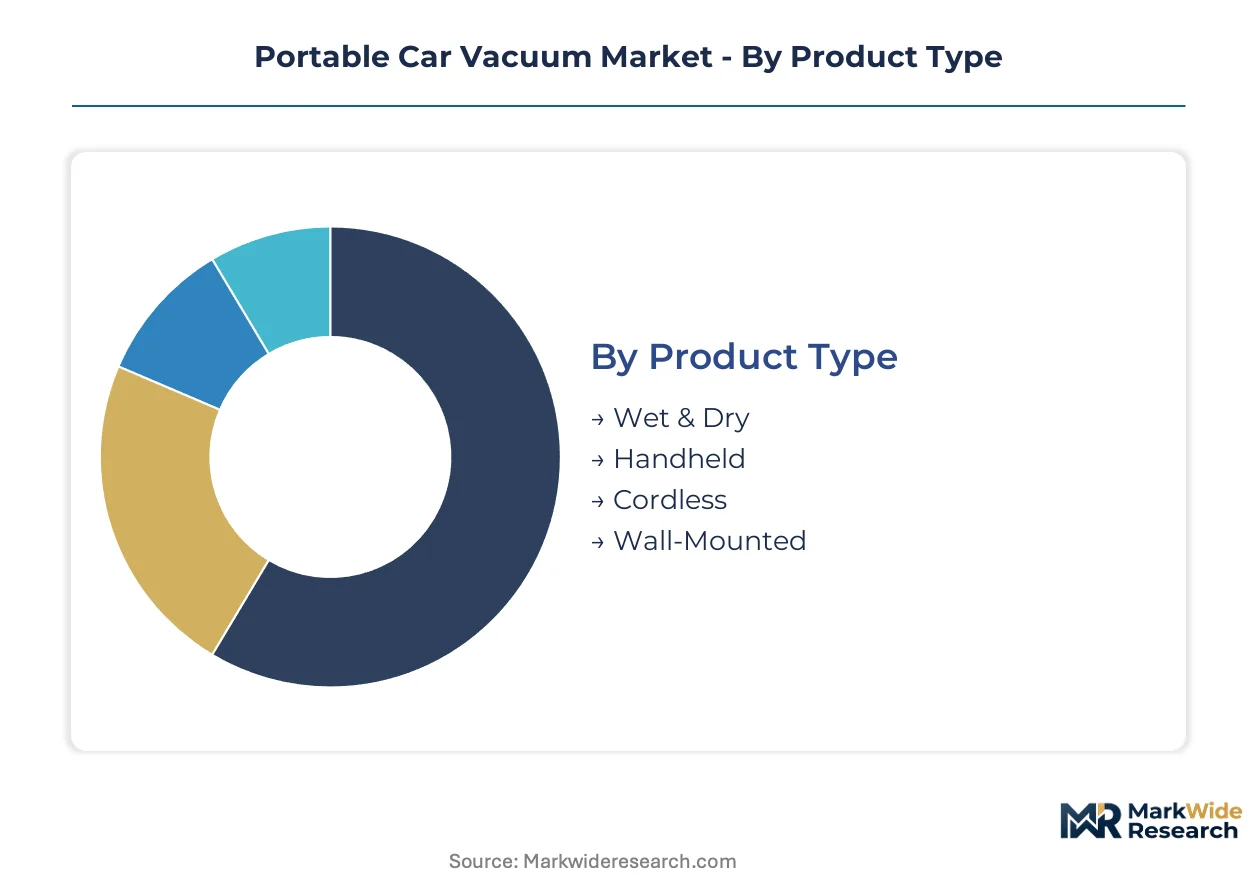
Segmentation in portable car vacuums separates procurement behavior across fleet-scale buyers, allergy-sensitive households, and gig-economy independents. Each dimension—product form, filtration technology, powertrain, and end-use—creates distinct margin tiers and compliance burdens.
Product Type:
Commercial buyers prioritize durability and debris-handling versatility over residential convenience features.
- Wet & Dry:Sealed motor housings and corrosion-resistant intake ports handle liquid spills alongside solid debris. Automotive detailers in Germany's aftermarket cluster specify these units for daily interior protocols, accepting higher unit costs for reduced service downtime.
- Cordless:Lithium-ion platforms operating at 18V-20V with brushless motor control absorb what had been tethered-only performance tiers. Fleet operators across North American urban mobility corridors are abandoning corded units entirely, compressing demand toward battery-native architectures.
- Handheld:Compact form factors target gig-economy drivers needing rapid cabin turnover between fares.
- Wall-Mounted:Fixed installation units serve permanent detailing bays in OEM-authorized service networks.
Volume sits with wet-and-dry configurations in commercial channels; growth tilts toward cordless platforms as lithium energy density improves.
Technology:
Filtration and motor architecture choices determine regulatory compliance trajectories and recurring revenue potential.
- HEPA:Pleated media and sealed gasket systems capture 99.97% of 0.3-micron particles. Allergy-sensitive residential buyers in California and EU member states absorb 15-25% bill-of-materials premiums for certified units meeting Ecodesign efficiency thresholds.
- Brushless:Field-oriented commutation algorithms optimize torque-per-watt performance. Chinese contract manufacturers are expanding brushless motor core output, reducing component bottlenecks for cordless platform assemblers.
- Bagless:Cyclone separation eliminates recurring bag purchases, constraining aftermarket revenue streams.
- Cyclonic:Multi-stage centrifugal separation demands precise geometry tolerances, creating IP licensing barriers for mid-tier entrants.
Certification complexity clusters around HEPA and brushless combinations; cyclonic architectures face the steepest IP concentration.
Power Source:
Energy platform selection locks manufacturers into distinct supply chain risk profiles and jurisdiction-specific safety testing.
- Battery-Powered:Cylindrical lithium-ion cells from specialized suppliers power cordless platforms. US Consumer Product Safety Commission electrical safety standards limit entry of uncertified imports, raising compliance capital requirements for new entrants.
- Corded Electric:12V DC vehicle outlet dependency constrains mobility but eliminates battery degradation costs. Price-sensitive residential segments in regions with weaker cordless infrastructure continue procurement.
- Solar-Powered:Photovoltaic integration targets off-grid and emergency preparedness niches with limited commercial scale.
- Hybrid:Dual battery-corded flexibility adds component cost without clear buyer willingness-to-pay premiums.
Procurement gravity centers on battery-powered architectures; corded electric retains residual share in budget residential tiers.
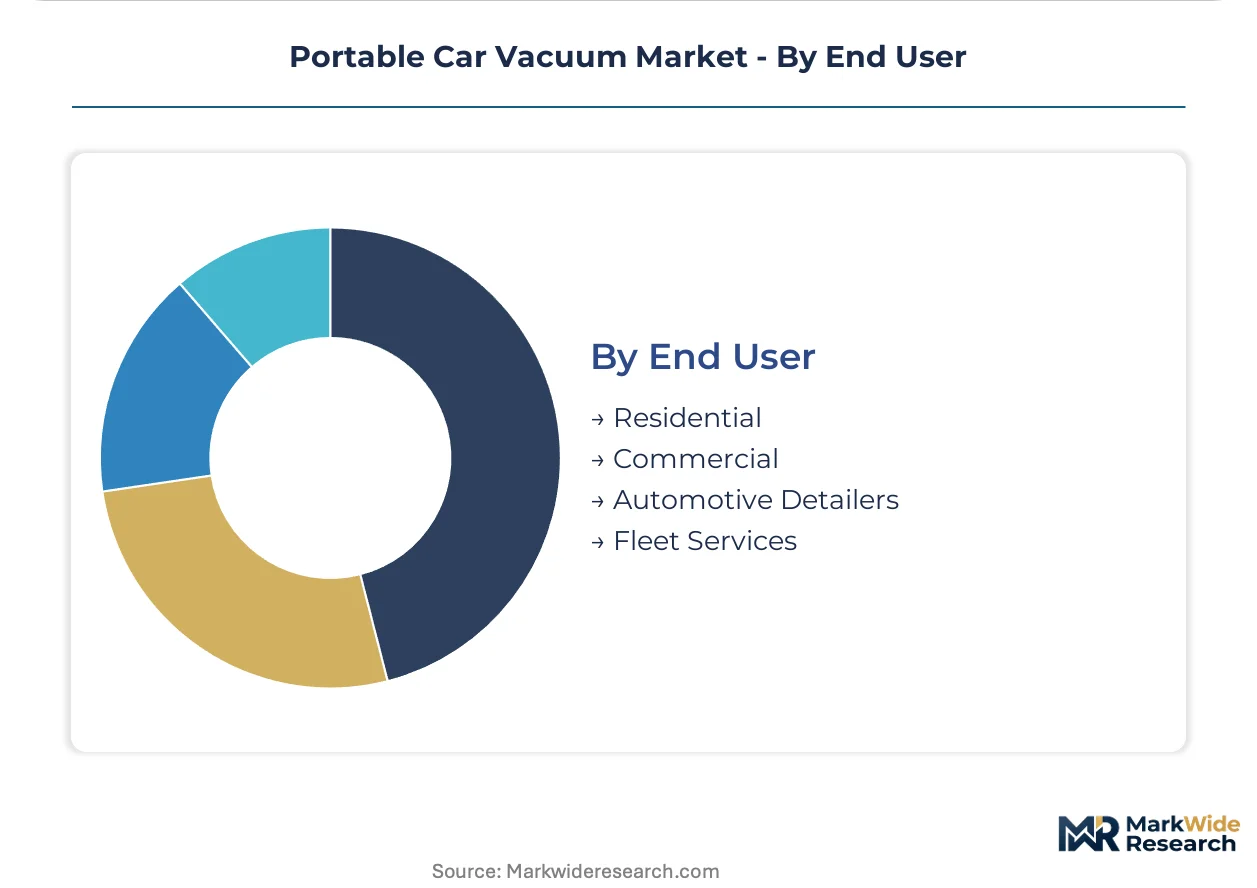
End User:
Customer scale and purchasing centralization separate pricing power and specification influence.
- Fleet Services:Ride-sharing fleet operators across North America are expanding in-house detailing protocols to reduce third-party service costs. Bulk procurement channels concentrate volume through fleet management companies, squeezing independent operators from pricing tiers.
- Automotive Detailers:OEM-authorized service networks in Germany's automotive aftermarket cluster specify commercial-grade cordless units with modular motor architectures for traceability compliance.
- Residential:Individual buyers prioritize compact storage and HEPA certification for allergy management.
- Commercial:Non-fleet commercial buyers include rental car agencies and dealership pre-delivery services with moderate volume concentration.
Margin concentration aligns with fleet services and automotive detailers; residential volume spreads across fragmented channels with weaker pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate deposits in Chile's Atacama Desert anchor battery supply chains for cordless portable car vacuum manufacturers serving North American and European assembly lines.
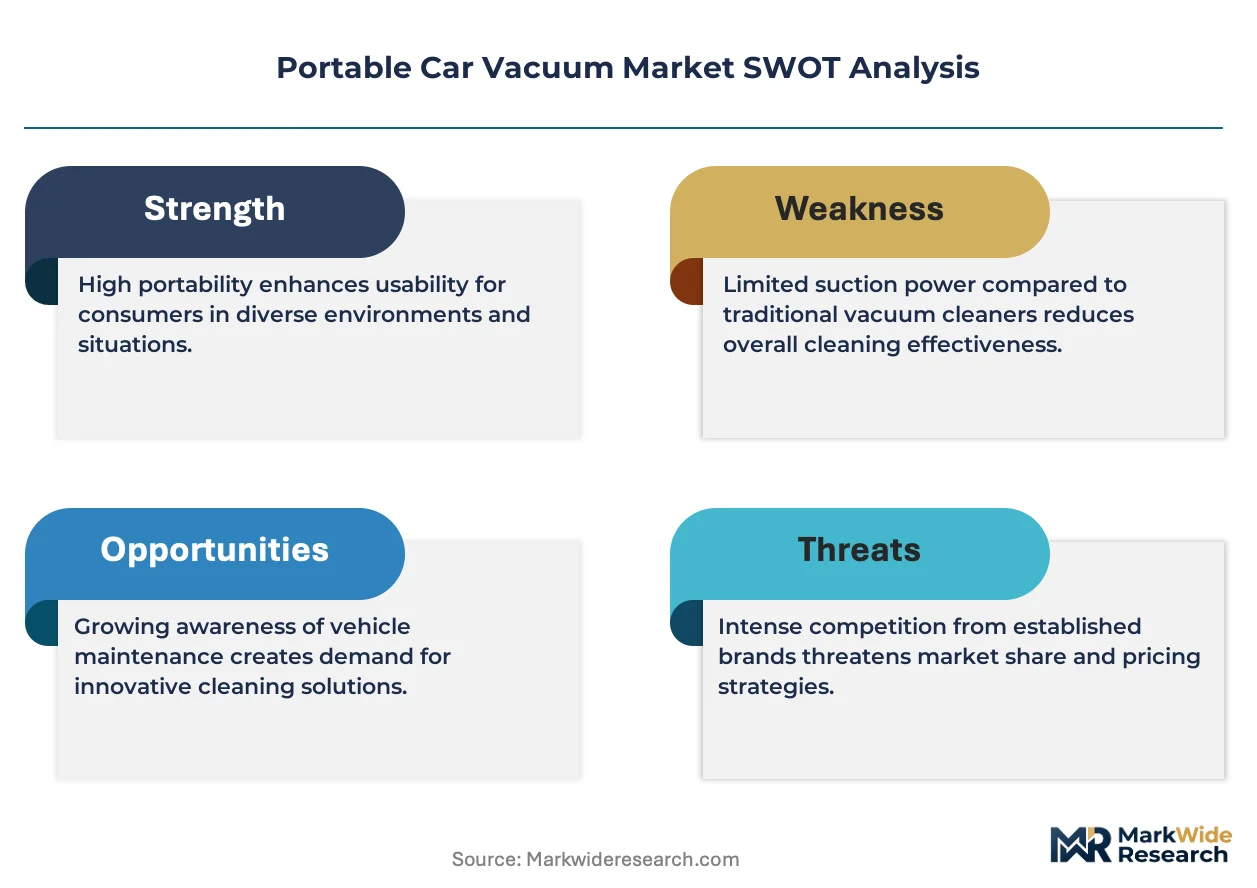
United States
Ride-sharing fleet operators in California and Texas are expanding in-house detailing protocols to reduce third-party service costs. The US Consumer Product Safety Commission enforces electrical safety standards for lithium-ion battery systems in handheld appliances. Los Angeles and Dallas-Fort Worth anchor procurement concentration for commercial-grade cordless units.
Germany
OEM-authorized detailing services in Bavaria and Baden-Württemberg source commercial-grade cordless units in bulk for daily interior protocols. The EU Ecodesign for Sustainable Products Regulation pressures manufacturers to eliminate single-use vacuum bags and improve motor efficiency. Stuttgart's automotive aftermarket cluster drives specification standards for modular motor architectures.
China
Contract manufacturers in Guangdong and Zhejiang provinces are broadening output of brushless motor cores for portable car vacuums. The country's national quality regulator enforces GB standards for lithium-ion battery safety in consumer appliances. Shenzhen and Dongguan host expanding production hubs beyond traditional appliance manufacturing centers.
Japan
Residential buyers in Tokyo and Osaka prioritize HEPA-certified compact units for allergy management in dense urban parking environments. METI efficiency guidelines shape motor performance thresholds for domestic market entry. Nagoya's industrial corridor supplies precision-machined cyclone separation components to regional assemblers.
United Kingdom
Fleet service companies in London and Birmingham are consolidating supplier rosters around standardized cordless specifications. CE marking requirements mandate minimum motor efficiency thresholds and recyclable material content. The Midlands manufacturing belt hosts assembly operations serving both domestic demand and EU export channels.
Portable Car Vacuum Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue compact lithium-ion form factors for gig economy drivers. The vendor base spans premium cyclone-geometry specialists, mass-market appliance brands, and contract-manufacturing platforms. Three archetypes dominate: technology licensors with proprietary separation patents, volume distributors with big-box retail anchoring, and component-integrated fabricators with brushless motor control. Competitive moves concentrate on geographic expansion through fleet procurement channels and portfolio diversification into wet-and-dry commercial specifications.
Within the premium technology tier, Dyson Ltd and SharkNinja Inc exemplify positioning around proprietary cyclone geometry and cordless powertrain integration. Black+Decker anchors mass-market distribution through established retail automotive aisles. Fanttik occupies a specialist position targeting compact lithium-ion configurations for independent ride-share operators. These three entities represent distinct competitive vectors: patent-protected separation systems, scale-driven channel access, and gig-economy form factor optimization.
| Leading Market Players |
|---|
| Dyson Ltd |
| SharkNinja Inc |
| Bissell Inc |
| Black+Decker |
| iRobot Corporation |
| Hoover Inc |
| Fanttik |
| ThisWorx |
| Panasonic Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price volatility from Chile's Atacama Desert flows through cylindrical cell suppliers to compress margins on cordless platforms, while fleet procurement concentration in North America and Germany funnels volume toward contract-based pricing tiers with modular motor traceability requirements.
Pricing Analysis
Warranty bundling separates premium cordless units with multi-year motor coverage from unbundled economy tiers where service costs fall on buyers. Three-tier pricing structure across premium, standard, and economy levels reflects HEPA certification grade and brushless motor architecture. Pricing pressure stems from battery-grade lithium carbonate input swings that destabilize cordless platform margins. Fleet services exhibit lowest price sensitivity due to bulk procurement scale, while gig-economy independents face acute cost compression in compact handheld segments.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Rotterdam, and Shenzhen operate hub-and-spoke patterns feeding automotive aftermarket clusters. Brushless motor cores draw from Guangdong and Zhejiang provinces, lithium cells from South Korea and Japan, and cyclone separation components from Nagoya's precision machining corridor. Single-source vulnerability concentrates in cylindrical cell supply from specialized battery manufacturers. Distribution runs through OEM-authorized service networks and big-box automotive aisles with fleet management company bypass channels gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign motor efficiency mandates and pending battery passport rules are forcing capital-constrained assemblers toward exit, consolidating procurement volume around compliant modular architectures.
For Market Incumbents: Deploy backward integration into brushless motor core production to capture margin from Chinese contract manufacturers and insulate against lithium input volatility. Lock fleet procurement channels through embedded traceability firmware that preempts battery passport compliance costs. Defend against Fanttik-type compact entrants by tightening form factor specifications in OEM-authorized detailing networks. For New Entrants and Emerging Players: Enter via gig-economy driver segments in urban mobility corridors where specification standards remain fragmented and bulk pricing tiers exclude independents. Target wet-and-dry configurations for automotive detailer white space in secondary North American markets. Pursue direct-to-driver digital channels bypassing consolidated fleet management company procurement. For Investors and Strategic Acquirers: Brushless motor control firmware acquisitions by established appliance platforms signal that cordless performance parity has become the decisive capability threshold. Position for five-to-ten year viability around component-integrated fabricators with field-oriented commutation IP and modular motor architectures. Monitor CE marking certification timelines as leading indicator of competitive response windows compressing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Motor Architecture Development | Enables battery passport traceability compliance ahead of EU mandate enforcement. |
| Fleet Procurement Channel Integration | Locks volume through ride-sharing operator in-house detailing protocol expansion. |
| Brushless Motor Core Capacity Expansion | Reduces dependency on Chinese contract manufacturer supply bottlenecks. |
| HEPA Filtration Certification Investment | Captures allergy-sensitive residential premium in California and EU markets. |
| Wet-and-Dry Commercial Specification Launch | Penetrates automotive detailer procurement consolidating around OEM-authorized networks. |
Research Methodology
Trade databases, customs records, and automotive aftermarket procurement filings formed the secondary backbone, cross-referenced with primary interviews involving fleet operations managers, automotive detailer procurement leads, contract manufacturing sourcing directors, and lithium-ion battery safety compliance officers. Bottom-up unit shipment estimates by product type and powertrain configuration were triangulated against top-down market value reconstructions from distributor revenue disclosures and retail channel audit data.
Historical trendline analysis of cordless platform adoption rates and motor efficiency certification timelines informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, filtration technology, power source architecture, and end-user procurement scale. CAGRs were derived from weighted average growth trajectories with lithium energy density improvement curves and fleet operator capital expenditure patterns as key industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery-grade lithium carbonate price spike scenarios or accelerated EU battery passport implementation. Outputs reflect documented assumptions around motor efficiency threshold compliance and fleet procurement centralization rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Toilet Brush Market
Household Items
Crash Mat Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Robot Mops Market
Household Items
France Digital Showers Market
Household Items
Nebulizing Diffuser Market
Household Items
Cookware Market
Household Items
Tablet Tissue Paper Market
Household Items
Cat Hair Remover Market
Household Items
Kuwait Gas Hobs Market
Household Items
Disposable Napkins Market
Household Items
Hand-Held Vacuum Cleaner Market
Household Items
Brazil Cookware Market
Household Items
Bagless Vacuum Cleaner Market
Household Items
Insulated Lunch Box Market
Household Items
Umbrella Market