
 India Digital Showers Market | 2026-2036
India Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
India Digital Showers Market Insights
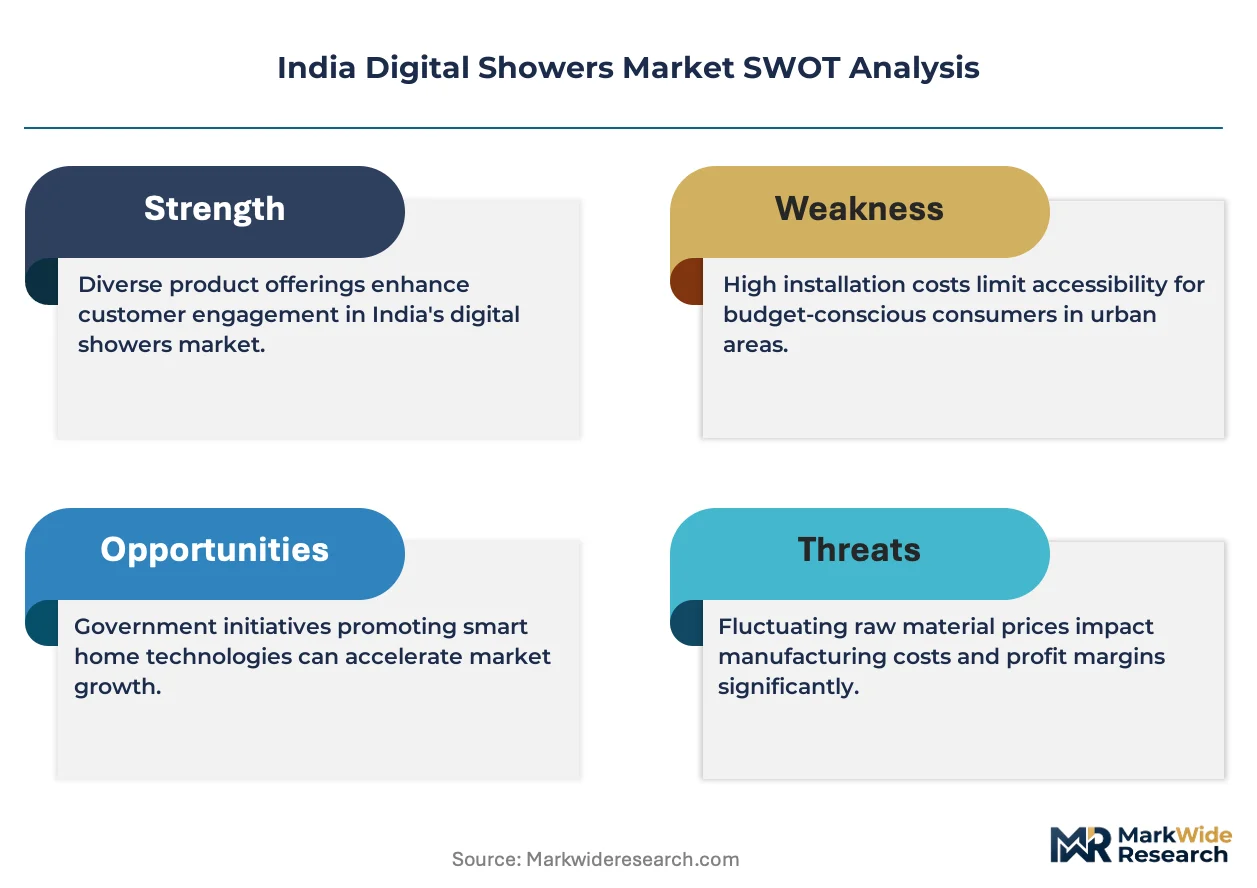
Subscription-based firmware and remote diagnostics is hardening as a recurring revenue layer atop hardware sales in India's digital shower segment. Kohler India leverages its service infrastructure to lock in premium hospitality accounts. Jaquar Group anchors its position through deep backward integration into brass forging and chrome plating. CERA Sanitaryware Ltd. competes on price-accessible digital temperature control variants for tier-two residential developers.
Digital showers integrate thermostatic mixing valves, electronic control modules, and IoT-enabled user interfaces to deliver precise temperature management and programmable water delivery for residential, commercial, and hospitality environments. Smart showers with voice activation and app-based scheduling command the highest margin pools, while thermostatic valves represent the volume foundation due to simpler installation requirements. Wall-mounted installation types dominate retrofit demand across aging urban housing stock, whereas integrated systems capture new-build premium projects where concealed plumbing permits full digital integration.
BIS mandates electrical safety certification for all electronically actuated water fixtures, compelling redesigns of control modules and power isolation systems. The Bureau of Energy Efficiency's water-heating efficiency norms indirectly shape digital shower specification by rewarding systems that integrate with heat-pump and solar thermal sources. State-level municipal corporations in Maharashtra and Karnataka are embedding smart water metering into building codes, creating compliance pull for conservation-logic digital showers. Stakeholders must weigh the capital intensity of BIS testing laboratories against the margin compression risk of competing solely on imported unbranded electronic valve assemblies.
Market Dynamics
BIS electrical safety mandates are forcing control module redesigns across India's digital shower supply base, while municipal smart water metering codes in Maharashtra and Karnataka create specification pull for conservation-logic systems.
Growth Catalysts
- State-Level Smart Metering Mandates:Municipal corporations in Maharashtra and Karnataka are embedding smart water metering into building codes, creating compliance-driven demand for digital showers with integrated flow-logic.
- Heat-Pump Integration Incentives:The Bureau of Energy Efficiency's water-heating efficiency norms reward systems compatible with solar thermal and heat-pump sources, steering specification toward digitally controlled thermostatic valves.
- Hospitality Sustainability Specs:Sustainability-focused hotel developers in Gujarat and Maharashtra are specifying water conservation functionality as a procurement criterion, concentrating volume in premium digital shower categories.
Market Restraints
- Brass Input Cost Volatility:Fluctuations in copper and zinc prices directly compress margins for domestic manufacturers reliant on brass forging for valve bodies and thermostatic cartridges.
- BIS Certification Capital Intensity:The cost and timeline of electrical safety testing at BIS-accredited laboratories creates a structural barrier for smaller valve assembly importers.
- Skilled Installation Bottleneck:Concealed plumbing requirements for integrated digital systems face a shortage of trained technicians in tier-two and tier-three urban markets.
Strategic Opportunities
- Subscription Firmware Revenue:Remote diagnostics and over-the-air updates represent a recurring revenue layer atop hardware sales, with hospitality chains in Bangalore and Mumbai as early adopters.
- Tier-Two Residential Penetration:Price-accessible thermostatic variants targeting developers in Pune, Hyderabad, and Chennai remain underpenetrated relative to Mumbai and Bangalore saturation.
- Voice-Activation Convergence:Integration of voice control with existing smart home ecosystems opens specification pathways in luxury residential projects where full-home automation is standard.
Industry Challenges
- Retrofit Installation Complexity:Aging urban housing stock in Delhi and Kolkata requires extensive concealed plumbing modification, slowing wall-mounted digital shower penetration.
- Power Isolation Engineering:BIS mandates for electrical safety in wet environments demand redesign of control module housing and grounding systems, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Digital Showers Market |
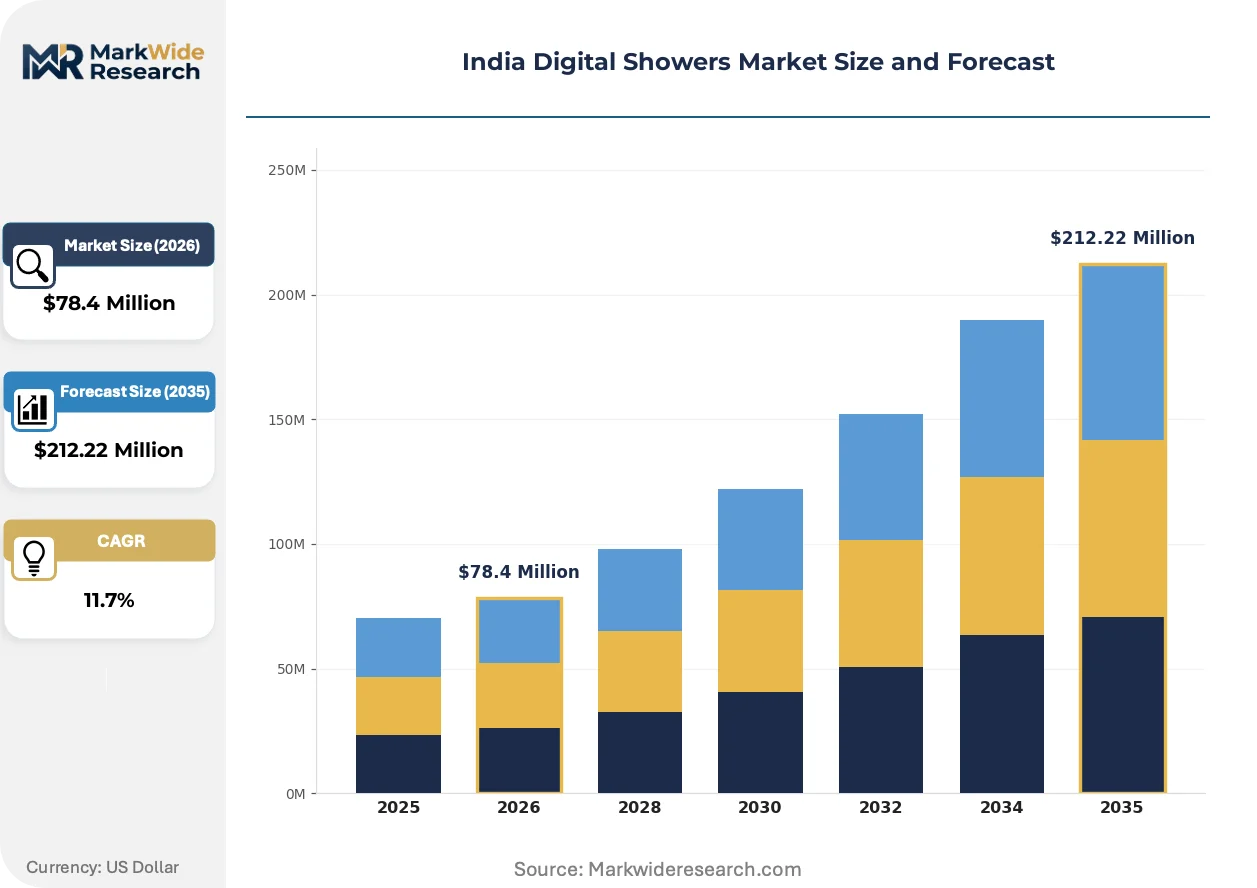
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $212.22 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Showers, Thermostatic Valves, Digital Temperature Control, Remote Control Systems End User: Residential, Commercial, Hospitality, Institutions Functionality: Temperature Regulation, Water Conservation, Voice Control, Customizable Settings Installation Type: Wall-Mounted, Ceiling-Mounted, Freestanding, Integrated Systems |
| Companies Covered | Kohler India, Jaquar Group, Grohe India, Hansgrohe Group, CERA Sanitaryware Ltd., LIXIL Corporation, Dornbracht India, TOTO Sanitary India, Hindware Homes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Digital Showers Market Trends and Innovations
Three forces are reshaping India's digital shower segment: firmware-based service monetization, regulatory compression of product development timelines, and specification behavior shifts among hospitality procurement teams.
Voice-activated shower control is automating user interface design across premium residential and hospitality installations. Luxury developers in Mumbai are specifying voice-enabled systems as standard in new-build projects. This technology is automating away manual dial interfaces and compressing the specification window for traditional thermostatic-only products.
The Bureau of Indian Standards has tightened electrical safety certification requirements for all electronically actuated water fixtures. Manufacturers must redesign control modules with enhanced power isolation and grounding architectures to achieve compliance. Integrated digital shower systems face the longest recertification timelines, while simpler thermostatic valves adapt more rapidly.
After-sales service unbundling is fragmenting traditional distribution relationships in the hospitality vertical. Large hotel operators in Gujarat and Maharashtra are negotiating direct firmware support contracts with manufacturers, bypassing regional plumbing distributors. This behavior concentrates procurement authority with national hospitality chains and compresses margin pools for intermediary channel partners.
India Digital Showers Market Segmentation
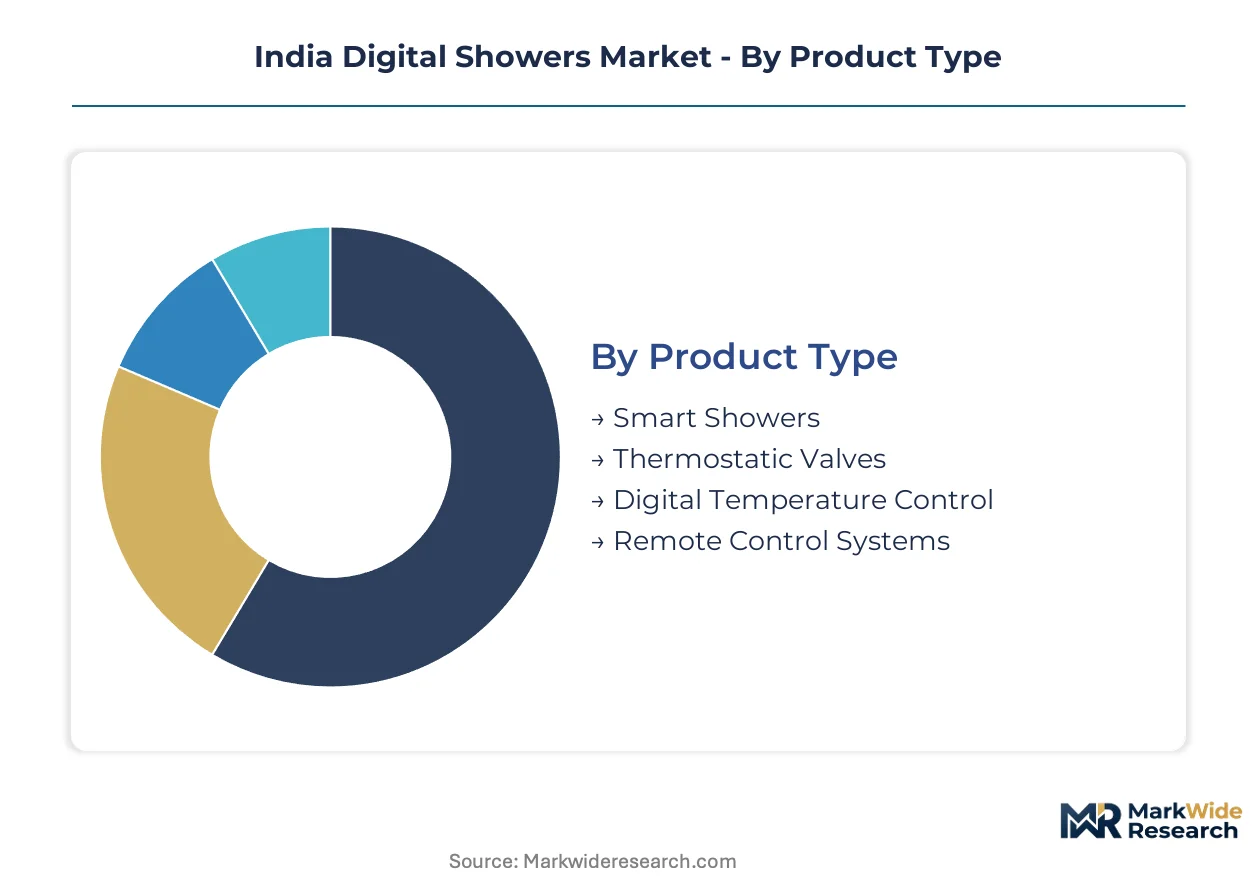
Product architecture in India's digital shower market splits sharply between retrofit-friendly thermostatic hardware and fully integrated smart systems requiring concealed plumbing. Specification behavior varies dramatically across hospitality procurement teams, residential developers, and institutional maintenance departments, each prioritizing different performance-cost trade-offs.
Product Type:
Thermostatic precision and connectivity depth define the technology axis across this category.
- Smart Showers:Voice-activated and app-scheduled systems with IoT-enabled user interfaces command premium positioning in Mumbai luxury residential towers. Bangalore hospitality chains specify these for guest experience differentiation, though BIS electrical safety recertification timelines extend product development cycles.
- Thermostatic Valves:Electronic mixing modules deliver precise temperature management without full digital integration, anchoring volume through simpler installation requirements. Maharashtra and Karnataka municipal smart metering codes are pulling specification toward these systems as baseline compliance hardware.
- Digital Temperature Control:Mid-tier electronic interfaces with programmable presets target tier-two residential developers in Pune and Hyderabad seeking price-accessible precision.
- Remote Control Systems:Wireless activation modules enable retrofit upgrades without concealed plumbing modification, penetrating aging urban housing stock in Delhi and Kolkata.
Thermostatic Valves leads on scale; Smart Showers leads on momentum.
End User:
Procurement authority and specification complexity diverge sharply across buyer types.
- Hospitality:Sustainability-focused hotel developers in Gujarat and Maharashtra concentrate volume in premium categories, negotiating direct firmware support contracts that bypass regional distributors. Water conservation functionality is now a mandatory procurement criterion for this segment.
- Residential:Luxury developers in Mumbai and Bangalore specify thermostatic digital systems at rising rates, while tier-two markets remain underpenetrated relative to saturation in these metros.
- Commercial:Office and retail fit-outs prioritize wall-mounted retrofit compatibility over full integration, constrained by tenant improvement budgets and accelerated project timelines.
- Institutions:Educational and healthcare facilities emphasize durability and maintenance accessibility, favoring exposed valve architectures over concealed integrated systems.
Residential commands absolute volume; Hospitality climbs the fastest on specification intensity.
Functionality:
Performance modules stack from basic safety compliance through experiential customization layers.
- Temperature Regulation:Core thermostatic mixing with anti-scald protection forms the non-negotiable baseline across all end-user categories, required for BIS certification eligibility.
- Water Conservation:Flow-logic systems with integrated metering respond directly to Maharashtra and Karnataka municipal code mandates, creating compliance-driven demand concentration.
- Voice Control:Hands-free activation interfaces are automating specification in luxury residential projects where full-home automation is standard, compressing demand windows for manual-dial alternatives.
- Customizable Settings:User-profile memory and programmable scheduling enable subscription firmware monetization, with hospitality chains in Bangalore and Mumbai as early adopters of recurring revenue models.
Temperature Regulation anchors universal specification; Voice Control gains share fastest on automation convergence.
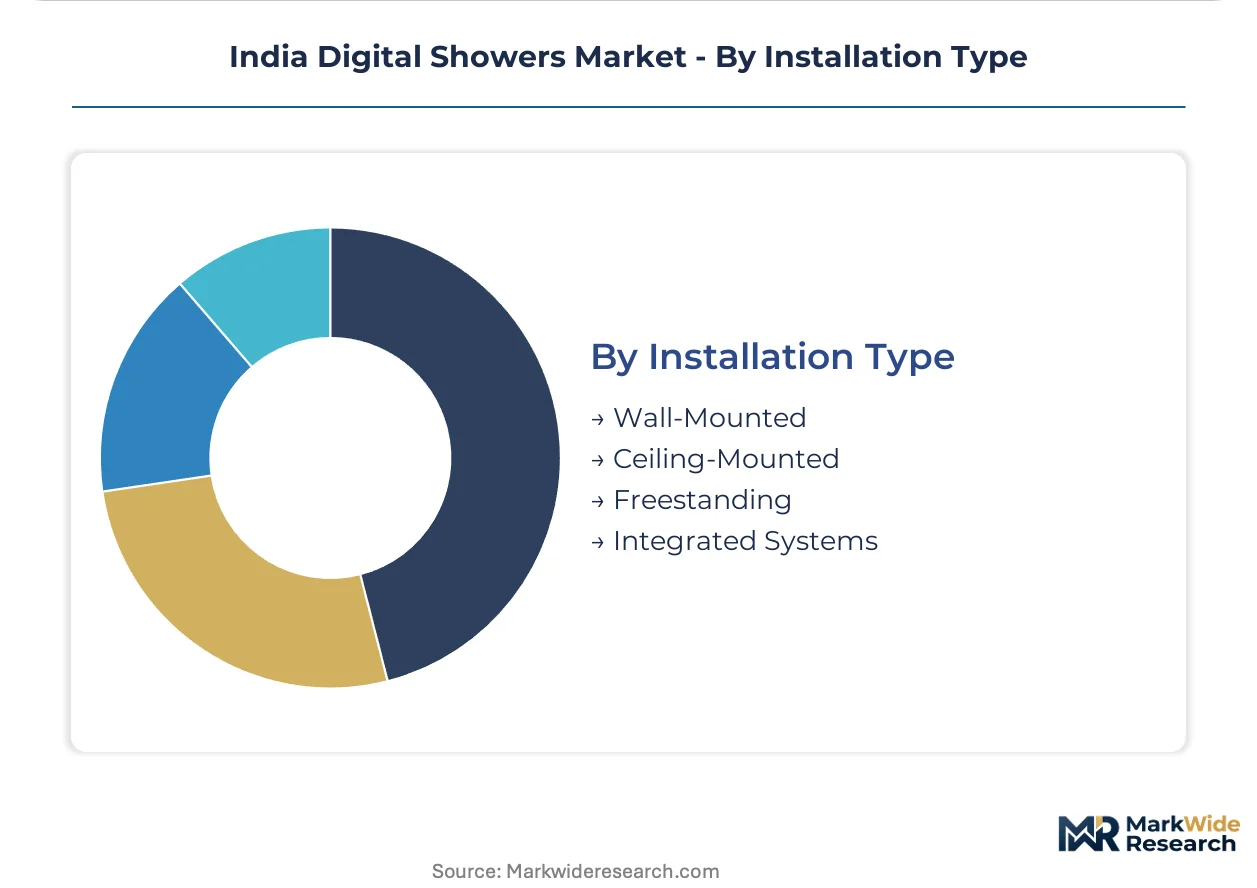
Installation Type:
Physical integration depth determines addressable market scope and technical barrier height.
- Wall-Mounted:Exposed plumbing compatibility dominates retrofit demand across India's aging urban housing stock, requiring minimal concealed modification for digital upgrade.
- Integrated Systems:Concealed plumbing with full digital integration captures new-build premium projects, though skilled installation bottlenecks in tier-two and tier-three markets constrain penetration velocity.
- Ceiling-Mounted:Rainfall and overhead delivery configurations target luxury hospitality and residential wellness specifications, requiring structural coordination during construction phase.
- Freestanding:Portable and modular units serve temporary installations and institutional flexibility requirements, occupying a niche outside permanent construction specification.
Wall-Mounted dominates retrofit accessibility; Integrated Systems holds steepest expansion trajectory in new-build premium pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Karnataka concentrate India's digital shower demand through municipal smart metering mandates, while Gujarat's hospitality sustainability specifications pull premium volume in parallel.
Maharashtra
Mumbai's luxury residential developers specify thermostatic digital systems at rising rates for new-build towers. BIS electrical safety certification requirements tighten compliance standards for all electronic plumbing fixtures entering this market. Pune's tier-two developer segment remains underpenetrated relative to Mumbai saturation, creating specification runway for price-accessible variants.
Karnataka
Bangalore hospitality chains negotiate direct firmware support contracts with manufacturers, bypassing regional plumbing distributors entirely. State-level municipal corporations embed smart water metering into building codes, mandating flow-logic integration for new construction. The city's technology-forward residential base accelerates voice-activation adoption in full-home automation projects.
Gujarat
Sustainability-focused hotel developers concentrate procurement volume in premium digital shower categories with integrated water conservation functionality. Bureau of Energy Efficiency water-heating efficiency norms reward systems compatible with solar thermal sources common in this region. Ahmedabad's hospitality procurement teams now mandate conservation-logic as a non-negotiable criterion.
Telangana
Hyderabad's tier-two residential developers seek price-accessible digital temperature control variants from domestic manufacturers. Skilled installation bottlenecks for concealed integrated systems constrain penetration velocity relative to wall-mounted retrofit alternatives. The city's emerging luxury residential pipeline in western corridors creates specification entry points for smart shower categories.
Tamil Nadu
Chennai's commercial office fit-outs prioritize wall-mounted retrofit compatibility over full digital integration, constrained by tenant improvement budgets. Brass input cost volatility from copper and zinc price fluctuations compresses margins for regional valve body fabricators. The city's aging urban housing stock in central districts sustains demand for minimal-concealment digital upgrades.
India Digital Showers Market Competitive Landscape
Top-tier vendors anchor premium hospitality and luxury residential specification, while mid-tier domestic fabricators compete on price-accessible variants for tier-two developers. The vendor base stratifies across three tiers: international brands with service infrastructure, domestic specialists with backward integration into brass forging, and regional assemblers of imported electronic valve components. Two strategic archetypes dominate: firmware monetization specialists capturing recurring revenue from hospitality accounts, and integrated manufacturers controlling input costs through captive plating and forging operations. Competitive moves concentrate on direct contract negotiation with national hospitality chains and BIS certification pre-emption to lock out smaller importers.
Among international-origin specialists, Kohler India leverages established service infrastructure to secure premium hospitality accounts in Bangalore and Mumbai. Jaquar Group anchors its competitive position through deep backward integration into brass forging and chrome plating operations. CERA Sanitaryware Ltd. occupies the price-accessible tier, targeting tier-two residential developers with simplified digital temperature control variants.
| Leading Market Players |
|---|
| Kohler India |
| Jaquar Group |
| Grohe India |
| Hansgrohe Group |
| CERA Sanitaryware Ltd. |
| LIXIL Corporation |
| Dornbracht India |
| TOTO Sanitary India |
| Hindware Homes |
| Others |
Pricing and Supply Chain Analysis
Skilled plumbing technician concentrations in Maharashtra and Karnataka create labor-cost differentials that widen pricing-tier spreads between metro and tier-two markets. Brass forging clusters in Gujarat and Tamil Nadu feed component costs directly into manufacturer margin structures, while BIS certification timelines add compliance premiums that stratify final pricing.
Pricing Analysis
Capacity additions in Gujarat's brass forging corridor are reshaping price floors for thermostatic valve assemblies. Three-tier pricing structure across premium, standard, and economy levels separates hospitality-specified smart showers from residential thermostatic variants. Price differentiation hinges on BIS electrical safety certification grade and after-sales firmware support bundling. Pricing pressure stems from copper and zinc input volatility compressing margins for domestic fabricators. Tier-two residential developers in Pune and Hyderabad exhibit highest price sensitivity, while Mumbai luxury developers absorb premium positioning with minimal negotiation.
Supply Chain Analysis
BIS electrical safety mandates and Bureau of Energy Efficiency water-heating norms are reshaping sourcing toward domestic control module assembly. Component supply draws from China for electronic valve actuators, Germany for precision thermostatic cartridges, and domestic Gujarat-Tamil Nadu brass forging clusters for valve bodies. Raw material dependencies center on copper-zinc alloy feedstock, ceramic disc cartridges, and IoT-enabled control modules. Single-source vulnerability concentrates in imported electronic valve assemblies subject to DGFT import licensing variability. Distribution runs through regional plumbing distributors, though hospitality chains in Bangalore and Mumbai increasingly negotiate direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India digital showers market functions as a stable compounder, with municipal smart metering mandates across Maharashtra and Karnataka generating steady specification pull for compliance-integrated systems.
For Market Incumbents: To counter firmware monetization specialists capturing recurring revenue from hospitality accounts, incumbents should deepen backward integration into brass forging and chrome plating to defend input cost positions. BIS certification pre-emption investments will lock out smaller valve assembly importers and consolidate specification authority with national hospitality chains.
For New Entrants and Emerging Players: The price-point gap between premium smart showers and economy thermostatic valves creates entry space for mid-tier digital temperature control variants targeting tier-two residential developers in Pune, Hyderabad, and Chennai. Voice-activation convergence with existing smart home ecosystems offers specification pathways in Bangalore's technology-forward residential base. Direct contractor partnerships bypassing regional distributor markups provide the most viable go-to-market angle.
For Investors and Strategic Acquirers: National hospitality chains are the most active acquirer in this space, consolidating procurement authority through direct firmware support contracts. Long-term viability centers on manufacturers with captive brass forging and established BIS laboratory relationships. Watch for tier-two municipal smart metering code adoptions as the inflection signal indicating geographic demand expansion beyond Maharashtra and Karnataka saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Pre-emption | Electrical safety testing investments lock out smaller importers from Maharashtra and Karnataka specification pools. |
| Backward Integration into Brass Forging | Captive copper-zinc alloy processing insulates margin compression from commodity price volatility. |
| Subscription Firmware Monetization | Remote diagnostics contracts with Bangalore hospitality chains establish recurring revenue atop hardware sales. |
| Voice-Activation Platform Integration | Smart home ecosystem convergence opens specification pathways in Mumbai luxury residential towers. |
| Tier-Two Distribution Expansion | Direct contractor partnerships in Pune and Hyderabad penetrate underdeveloped price-accessible segments. |
Research Methodology
Multiple input streams — primary interviews with plumbing contractors and hospitality procurement directors, secondary validation through BIS certification databases and Bureau of Energy Efficiency filings, and customs records on electronic valve component imports — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations encompassed regional distributor principals, luxury residential developers in Mumbai and Bangalore, tier-two contractor networks in Pune and Hyderabad, and firmware engineering leads at domestic manufacturers. Secondary sources included state municipal corporation building code amendments, DGFT import policy notifications, and brass alloy price indices from commodity exchanges.
Historical volume trajectories were cross-referenced against panel input from specification professionals to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product architecture, end-user procurement authority, installation type compatibility, and regional regulatory cluster variations. CAGRs were derived from installed base expansion rates, replacement cycle assumptions, and new-build construction pipeline tracking. Forecast inputs included heat-pump adoption curves, smart water metering code propagation timelines, and hospitality sustainability specification intensity indices.
Caveats apply where BIS electrical safety mandate enforcement intensity, copper-zinc price volatility, or tier-two skilled technician availability could materially shift the outlook. Forecasts reflect assumptions on municipal code adoption velocity and hospitality chain procurement centralization trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Asia-Pacific Digital Showers Market
Household Items
India Cookware Market
Household Items
Integrated Smart Toilet Market
Household Items
Dry Vacuum Cleaner Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Hydration Containers Market
Household Items
Hand Dryer Market
Household Items
Party Supplies Market
Household Items
China Digital Showers Market
Household Items
Garbage Disposals Market
Household Items
Thermos Drinkware Market
Household Items
Permanent Marker Market
Household Items
Kick Bucket Market
Household Items
Infuser Water Bottles Market
Household Items
Flushable Wipes Market
Household Items
Candle Air Fresheners Market