
 Hand-Held Vacuum Cleaner Market | 2026-2036
Hand-Held Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Hand-Held Vacuum Cleaner Market Insights
Subscription-based filter replacement and battery refresh programs is hardening into a standard revenue layer alongside hardware sales. Dyson leverages its direct-to-consumer channel to lock in recurring revenue from accessory replenishment. SharkNinja competes through aggressive retail partnerships that bundle extended service plans at point of sale. Panasonic Holding Corporation anchors its position in Asia-Pacific through localized battery swap networks.
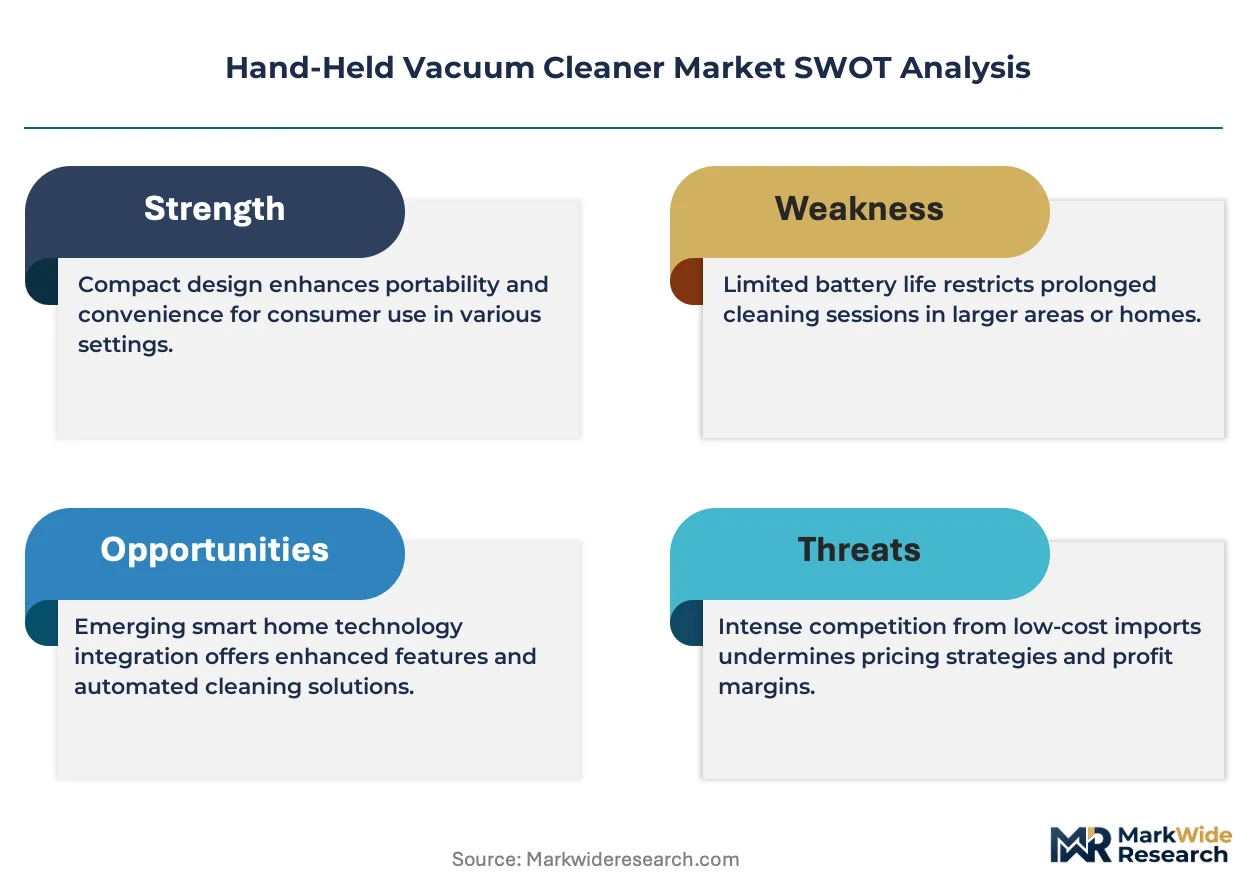
A hand-held vacuum cleaner is a portable, electrically powered suction device typically weighing under five kilograms, designed for spot cleaning and debris removal in confined spaces where full-size units cannot maneuver. The appliance employs a motorized fan to create negative pressure, drawing particulate matter into a collection chamber or bag for disposal. Cordless configurations now lead volume shipments as lithium-ion cell energy density improves runtime without adding mass. HEPA filtration technology commands the strongest margin pool, since allergen-trapping certification justifies price premiums in the household segment. The automotive application category shows the steepest trajectory, driven by ride-share drivers and fleet operators performing frequent interior detailing.
The US EPA Energy Star program and the EU Ecodesign Directive both enforce minimum motor-efficiency thresholds that disqualify older brushed-motor architectures from legal sale. Japan's METI administers Top Runner standards that ratchet upward performance benchmarks every product cycle, forcing manufacturers to redesign air paths and impeller geometries. China's GB standards and SAMR market-surveillance protocols add compliance layers for brands sourcing components across multiple jurisdictions. Stakeholders must monitor how solid-state battery commercialization timelines intersect with their platform refresh cycles, since early integration could reset competitive rankings across all price tiers.
Market Dynamics
Lithium-ion energy density improvements are compressing runtime gaps between corded and cordless architectures, while EU Ecodesign Directive motor-efficiency mandates are disqualifying legacy brushed-motor designs from legal commerce.
Growth Catalysts
- EU Ecodesign Directive:Minimum motor-efficiency thresholds force manufacturers toward brushless DC architectures, accelerating product refresh cycles and expanding addressable market for compliant suppliers.
- Ride-share fleet detailing:Automotive application demand steepens as Uber and Lyft drivers perform frequent interior cleaning, creating volume pull for compact suction devices with automotive charging compatibility.
- HEPA certification premiums:Allergen-trapping filtration standards justify price escalation in German and Japanese households, where asthma prevalence drives specification sensitivity.
Market Restraints
- Lithium cell cost volatility:Cathode material price swings, particularly nickel and cobalt, compress margin stability for cordless-first manufacturers dependent on battery cost predictability.
- South Korean battery supply concentration:Cell production clusters around LG Energy Solution and Samsung SDI facilities, creating single-source vulnerability for brands without dual-qualified suppliers.
- Brushed-motor obsolescence:Technical limitation in heat dissipation prevents older architectures from meeting EU efficiency floors, forcing write-downs of existing inventory and tooling.
Strategic Opportunities
- India urban rental expansion:Underpenetrated geography in compact appliance ownership among Mumbai and Bangalore apartment dwellers offers first-mover positioning before saturation.
- Solid-state battery convergence:Technology pairing of ceramic electrolytes with silicon anodes promises energy density doubling, enabling sub-kilogram designs with forty-plus minute runtime.
- Direct-to-consumer filter subscriptions:Channel innovation through automated replenishment locks recurring revenue and reduces customer acquisition cost versus retail dependency.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous compliance with US EPA Energy Star, EU CE marking, and China GB standards stretches product launch windows and engineering bandwidth.
- Air path simulation expertise:Talent gap in computational fluid dynamics specialists who can optimize impeller geometry for noise reduction without sacrificing suction pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand-Held Vacuum Cleaner Market |
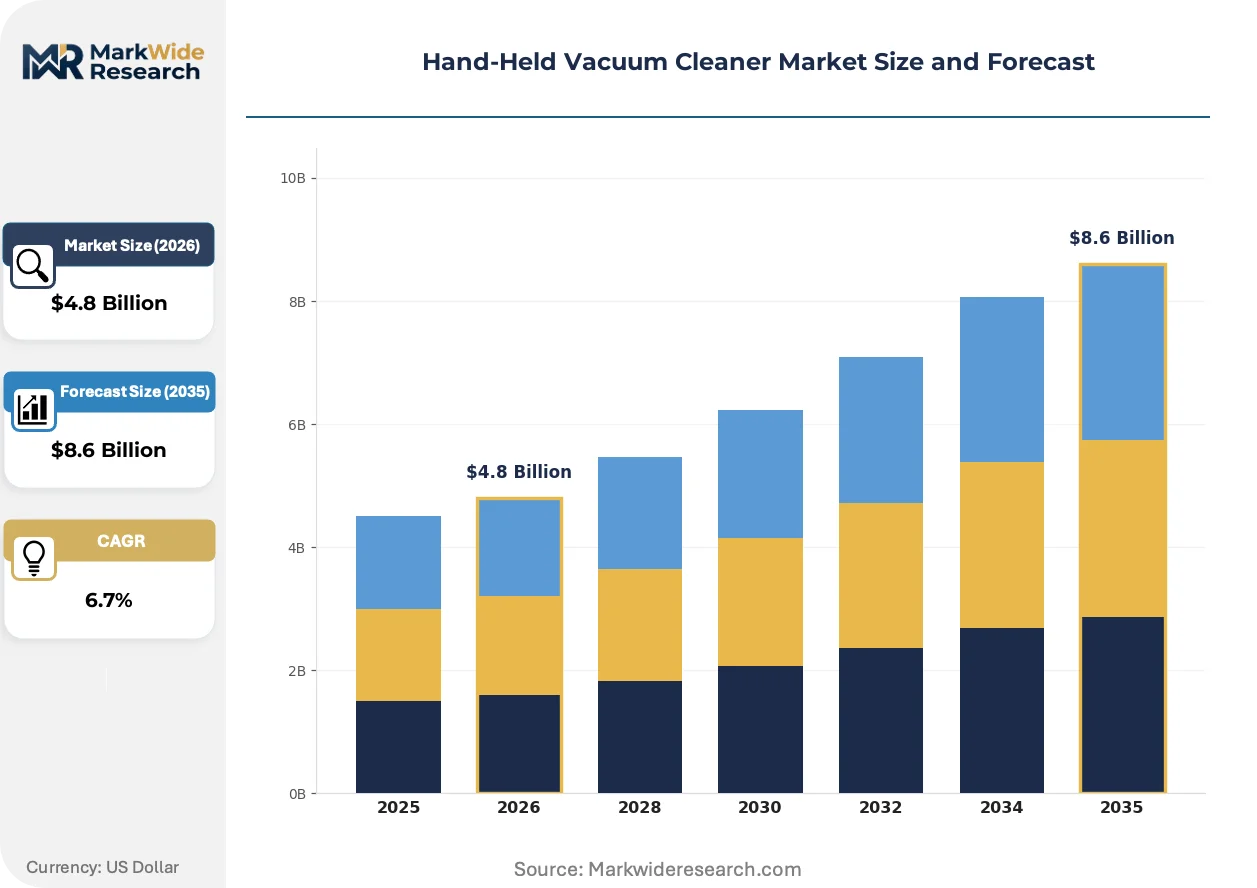
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless, Corded, Handheld Wet/Dry, Robotic Technology: Cyclone, Bagless, HEPA, Dual Motor Application: Household, Automotive, Commercial, Industrial End User: Homeowners, Renters, Facility Managers, OEMs |
| Companies Covered | Dyson, SharkNinja, Panasonic Holding Corporation, Bissell, Haier Group, Black+Decker, Samsung Electronics, iRobot Corporation, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand-Held Vacuum Cleaner Market Trends and Innovations
Product development trajectories center on energy storage chemistry, regulatory-driven motor architecture transitions, and service-model reinvention that decouples hardware margins from recurring revenue streams.
Brushless DC motor technology is absorbing engineering investment across premium and mid-tier product lines as manufacturers race to exceed EU Ecodesign Directive efficiency floors. Japanese METI Top Runner standards ratchet performance benchmarks each product cycle, forcing redesign of air paths and impeller geometries. The structural consequence is compressing competitive differentiation around suction-per-watt metrics rather than raw power claims.
REACH substance restrictions and RoHS hazardous material limits are tightening compliance scope for plastics and electronic components in European-bound units. Industrial consequence includes accelerated phase-out of certain flame retardants and PVC formulations in housing materials. The household segment responds fastest, as German retailers demand full material disclosure ahead of regulatory effective dates.
Fleet operators and property management groups are consolidating purchase authority through centralized procurement platforms that unbundle after-sales service from hardware acquisition. Channel disruption displaces traditional retail relationships with direct commercial contracts. This concentration is most visible in US multi-family housing management, where standardized appliance specifications reduce maintenance complexity across property portfolios.
Hand-Held Vacuum Cleaner Market Segmentation
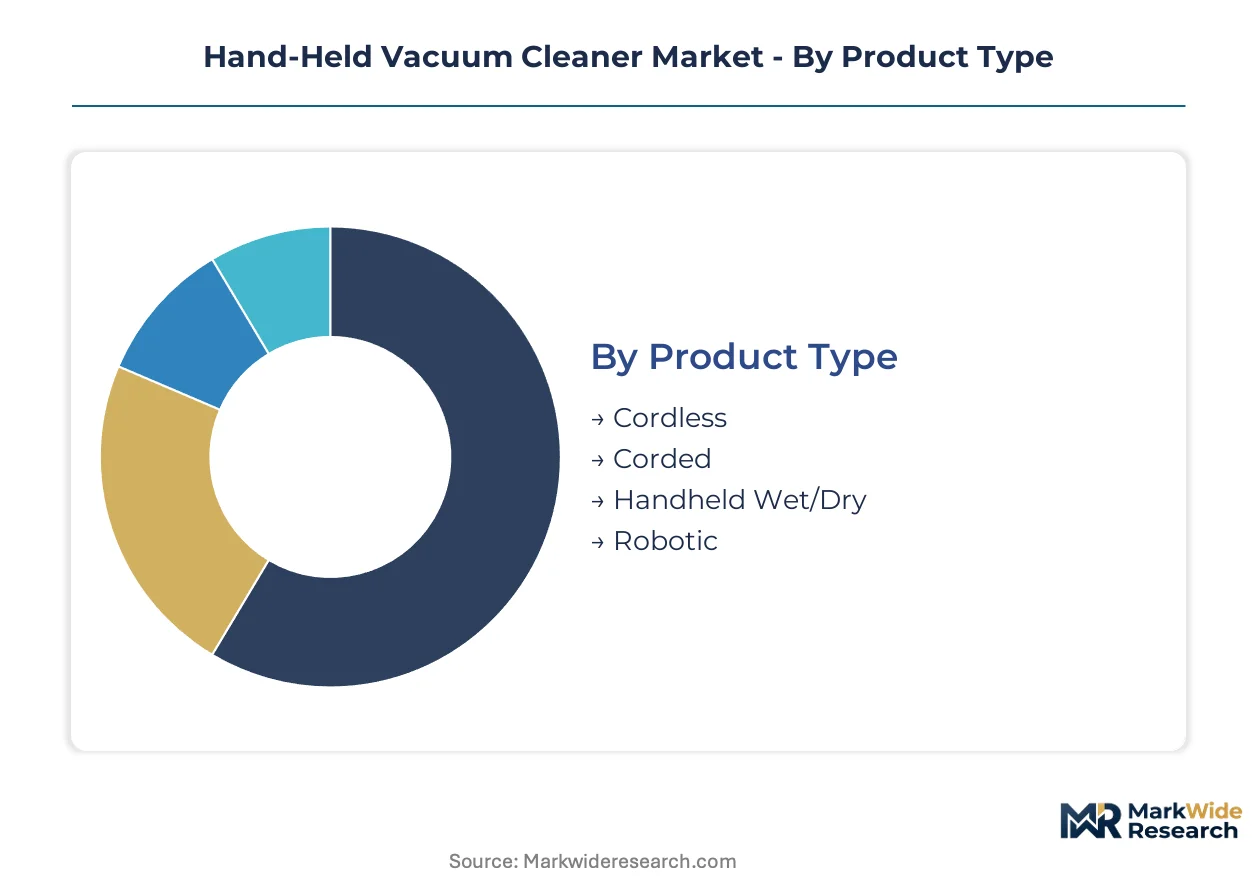
Segmentation in hand-held vacuum cleaners reveals how runtime requirements, filtration standards, and end-use intensity create distinct product-positioning opportunities. Manufacturers align R&D spend against upgrade-cycle frequency and replacement-part monetization potential within each slice.
Product Type:
Upgrade cycles vary dramatically by power architecture, with cordless platforms refreshing every 3-4 years as battery chemistry advances while corded units persist for 7-10 years.
- Cordless:Lithium-ion cell configurations now dominate urban household purchases where outlet proximity limits maneuverability. German and Japanese renters in compact apartments drive specification sensitivity toward sub-2kg designs with 30-plus minute runtime.
- Corded:Brushed-motor architectures persist in price-sensitive segments despite EU Ecodesign Directive pressure, though inventory obsolescence risk mounts as efficiency floors tighten. Fleet operators in US ride-share detailing favor these for unlimited runtime during vehicle turnaround operations.
- Handheld Wet/Dry:Sealed motor housings and corrosion-resistant impellers address spill recovery and workshop debris. Facility managers in Japanese commercial kitchens specify these for compliance with METI sanitation protocols.
- Robotic:Autonomous navigation and docking systems command premium positioning in South Korean smart-home ecosystems. Integration with home automation platforms determines vendor selection among tech-forward homeowners.
Cordless sits at the top of the volume ranking, with robotic climbing the fastest as navigation algorithms improve cost accessibility.
Technology:
Cost tier stratification separates certified filtration systems from basic particle capture, with price spreads widening as asthma prevalence drives medical-grade specification in affluent households.
- Cyclone:Centrifugal separation eliminates bag replacement costs while maintaining suction consistency across debris loads. German retailers demand transparent dust-bin designs that demonstrate separation efficiency to in-store shoppers.
- Bagless:Direct-empty canisters reduce recurring consumable spend for budget-conscious renters in Indian urban centers. Emptying hygiene concerns limit penetration among allergy-sensitive segments despite lower total cost of ownership.
- HEPA:Medical-grade filtration captures 99.97% of 0.3-micron particles, justifying 40-60% price premiums in Japanese and German markets where allergen sensitivity shapes purchase criteria. Certification maintenance requires scheduled filter replacement that locks subscription revenue.
- Dual Motor:Separate suction and brush-roll motors optimize power allocation for carpet agitation versus hard-floor pickup. South Korean manufacturers lead miniaturization of this architecture for cordless platforms.
HEPA commands the steepest margin expansion, with cyclone gaining share fastest as durability concerns shift preference away from bagged alternatives.
Application:
End-use intensity determines duty-cycle engineering, with commercial and industrial segments demanding thermal management systems that residential designs omit.
- Household:Spot-cleaning ergonomics and storage footprint dominate specification for apartment dwellers. HEPA certification and noise reduction justify premium positioning in German and Japanese markets.
- Automotive:Compact nozzle sets and 12V charging compatibility address ride-share driver workflows. Fleet procurement platforms in the US consolidate purchase authority around standardized specifications that reduce maintenance complexity.
- Commercial:Extended runtime and rapid battery swap systems support housekeeping operations in hospitality and healthcare settings. METI efficiency standards in Japan force brushless motor adoption ahead of regulatory effective dates.
- Industrial:Metal impellers and sealed bearings withstand abrasive debris in manufacturing and construction environments. REACH substance restrictions in Europe accelerate phase-out of certain housing materials in these heavy-use designs.
Household maintains volume leadership, with automotive expanding most quickly as gig-economy fleet operators professionalize interior detailing operations.
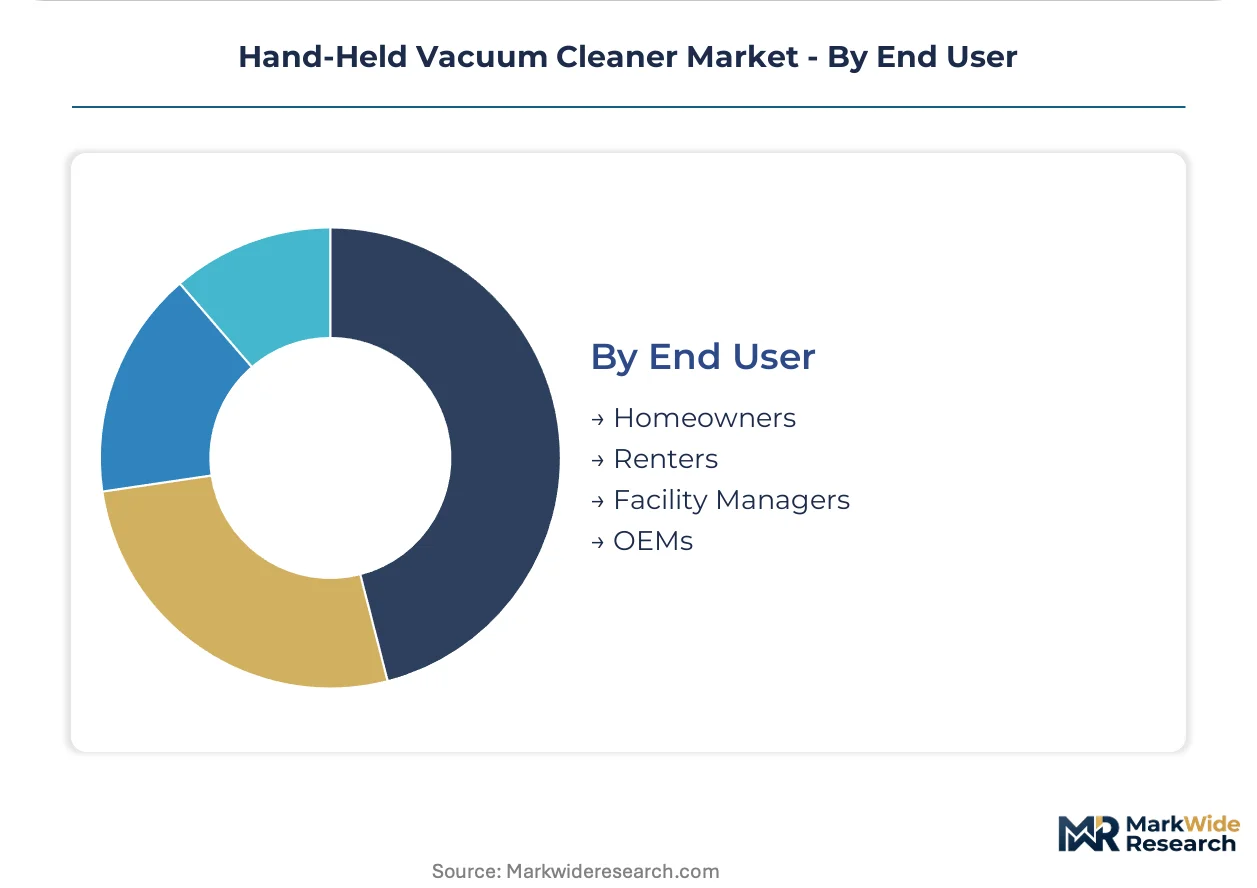
End User:
Customer type shapes channel strategy and service-model design, with facility managers and OEMs demanding outcome-based contracts that decouple hardware from maintenance economics.
- Homeowners:Aesthetic integration with domestic interiors and brand prestige sensitivity drive premium cordless adoption. D2C filter subscriptions capture recurring revenue from this sticky installed base.
- Renters:Storage constraints and lease-term uncertainty favor compact, portable designs with minimal installation requirements. Urban clusters in Mumbai and Bangalore represent underpenetrated first-mover opportunity.
- Facility Managers:Centralized procurement platforms standardize specifications across property portfolios, displacing retail relationships with direct commercial contracts. Total cost of ownership calculations include battery refresh and filter logistics.
- OEMs:Automotive and appliance manufacturers embed hand-held suction modules into larger systems, requiring custom form factors and electrical integration support. Volume commitments and qualification timelines extend sales cycles.
Homeowners anchor revenue concentration, with facility managers gaining procurement influence fastest as multi-family housing operators consolidate appliance standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households demand HEPA-certified compact designs while Japanese renters prioritize sub-2kg cordless units for dense urban living. South Korea's smart-home integration and India's emerging urban rental clusters create divergent specification requirements across major demand centers.
United States
Ride-share fleet operators drive automotive application volume through centralized procurement platforms. The EPA Energy Star program enforces minimum motor-efficiency thresholds that accelerate brushless DC adoption. California and Texas multi-family housing managers standardize specifications across property portfolios, displacing traditional retail relationships.
Germany
Asthma prevalence and allergen sensitivity command 40-60% price premiums for medical-grade filtration systems. The EU Ecodesign Directive disqualifies legacy brushed-motor architectures from legal commerce. Berlin and Munich retailers demand transparent dust-bin designs that demonstrate cyclone separation efficiency to in-store shoppers.
Japan
Compact apartment dwellers drive specification sensitivity toward sub-2kg designs with 30-plus minute runtime. METI Top Runner standards ratchet performance benchmarks every product cycle, forcing air path redesigns. Osaka and Nagoya facility managers specify handheld wet/dry units for commercial kitchen compliance with sanitation protocols.
South Korea
Tech-forward homeowners prioritize autonomous navigation and home automation platform integration. The country's national efficiency standards force brushless motor adoption ahead of regulatory effective dates. Seoul Capital Area smart-home ecosystems determine vendor selection through docking system compatibility.
India
Mumbai and Bangalore apartment dwellers represent underpenetrated first-mover opportunity in compact appliance ownership. The Bureau of Indian Standards and DGFT protocols add compliance layers for component sourcing. Urban rental expansion in Maharashtra and Karnataka clusters demand portable designs with minimal installation requirements.
Hand-Held Vacuum Cleaner Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium cordless architectures consolidating around direct-to-consumer channels while price-sensitive tiers fragment across retail partnerships. The vendor base organizes into three strategic archetypes: integrated technology platforms, retail-anchored volume players, and regional battery-system specialists. Dominant competitive moves include geographic expansion into underpenetrated urban rental clusters and technology licensing for solid-state battery convergence.
Within the integrated technology tier, Dyson exemplifies direct-to-consumer channel control, while SharkNinja occupies a position anchored in aggressive retail partnership structures. Panasonic Holding Corporation represents the regional battery-system archetype through localized service network deployment.
| Leading Market Players |
|---|
| Dyson |
| SharkNinja |
| Panasonic Holding Corporation |
| Bissell |
| Haier Group |
| Black+Decker |
| Samsung Electronics |
| iRobot Corporation |
| Philips |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up appliance specialists have consolidated component sourcing across Southeast Asian contract manufacturers, compressing procurement leverage into fewer hands while enforcing three-tier pricing discipline across premium, standard, and economy levels. This ownership concentration tightens margin management as lithium cell cost volatility feeds directly into cordless product line profitability.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for brushed-motor corded units even as EU Ecodesign Directive compliance costs elevate brushless DC premiums. Pricing stratifies across premium, standard, and economy tiers based on HEPA certification grade and battery chemistry tier, with price erosion running through economy cordless segments due to cathode material cost compression. Fleet procurement platforms exhibit lowest price sensitivity while Indian urban renters demonstrate highest elasticity.
Supply Chain Analysis
CE marking and METI Top Runner qualification gates restrict supplier pools to pre-certified motor and battery vendors. Cell production concentrates in South Korea, China, and Japan, while final assembly draws from Vietnam, Indonesia, and Mexico. Nickel and cobalt cathode materials, brushless DC motors, and HEPA filtration media constitute critical dependencies. Single-source vulnerability around LG Energy Solution and Samsung SDI cell supply creates concentration risk. Distribution runs through direct-to-consumer channels, retail partnerships, and fleet procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hand-held vacuum cleaner market represents a late-cycle quality story as German and Japanese households shift demand toward medical-grade HEPA certification and sub-2kg cordless specifications that justify sustained premium pricing.
For Market Incumbents: Anchor defensive positioning through backward integration into brushless DC motor production and captive battery cell qualification, countering margin pressure from lithium cost volatility and South Korean supply concentration. Prioritize direct-to-consumer channel control to lock recurring filter subscription revenue against retail partnership erosion. For New Entrants and Emerging Players: Direct-to-consumer marketplace routes offer lowest customer acquisition cost entry into Mumbai and Bangalore apartment clusters, the most penetrable geography in compact appliance ownership. Target cordless wet/dry specifications for Japanese commercial kitchen compliance, leveraging localized service network partnerships against established battery swap infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among regional battery-system specialists with qualified supplier relationships and localized service networks. Long-term viability hinges on solid-state battery convergence readiness and multi-jurisdiction certification bandwidth. Watch for solid-state battery pilot production announcements as inflection indicator for competitive reordering.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Dyson and SharkNinja compete through D2C versus retail partnership structures that capture recurring filter revenue. |
| Brushless DC Motor Integration | EU Ecodesign Directive and METI Top Runner standards force architecture transitions that disqualify legacy suppliers. |
| Localized Battery Swap Networks | Panasonic Holding Corporation anchors Asia-Pacific positioning through service infrastructure that reduces customer churn. |
| HEPA Certification Investment | German and Japanese allergen sensitivity justifies 40-60% price premiums that sustain margin expansion. |
| Solid-State Battery Convergence | Early integration of ceramic electrolyte chemistry could reset competitive rankings across all price tiers. |
Research Methodology
Coverage spans Germany, Japan, South Korea, the United States, and India, with primary inputs from each market combining interviews with product development executives, battery procurement leads, retail category managers, and fleet operations directors. Secondary validation draws from EPA Energy Star filings, EU Ecodesign Directive implementation guidance, METI efficiency standard publications, and BIS certification records. Bottom-up segment modeling triangulates against top-down macroeconomic indicators.
Granularity extends to product type, filtration technology, application intensity, and end-user archetype across the analysis window. CAGRs derive from modeled unit shipments and average selling price trajectories, incorporating lithium-ion cell cost curves, motor efficiency regulatory phase-in schedules, and urban rental household formation rates as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions around regulatory enforcement timing and cathode material price stabilization. Deviation in EU Ecodesign Directive implementation pace or South Korean cell supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Silicone Soap Mold Market
Household Items
Hangers Market
Household Items
Range Hood Cleaning Service Market
Household Items
Coin-Operated Laundries Market
Household Items
Smart Bathtub Market
Household Items
Portable Steamers Market
Household Items
Toilet Brush Market
Household Items
Portable Showers Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Smart Memory Foam Market
Household Items
Cutlery Steel Market
Household Items
Sleeping Pods Market
Household Items
China Digital Showers Market
Household Items
Asean Cookware Market
Household Items
Towel Warmers Market
Household Items
Electric Clothes Drying Hanger Market