
 Shower Heads and Systems Market | 2026-2036
Shower Heads and Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Shower Heads and Systems Market Analytics
EPA WaterSense certification is shifting procurement criteria across the North American shower heads and systems market, compelling manufacturers to redesign flow architectures below 2.0 gallons per minute without sacrificing user experience. Kohler leverages captive foundry capacity to control brass supply chains for premium valve assemblies. Moen sustains dominant retail shelf space through exclusive big-box distribution agreements. Grohe anchors European engineering credibility with German-manufactured thermostatic cartridge technology.
Shower heads and systems encompass plumbed fixtures and integrated assemblies that deliver thermally controlled water spray for personal hygiene, typically incorporating flow restrictors, aerators, and pressure-compensating valves to balance performance against water consumption limits. Stainless steel rain shower heads command premium positioning due to corrosion resistance and architectural integration with modern ceiling-mounted installation frameworks. Handheld variants compete on flexibility for aging-in-place residential retrofits and commercial accessibility compliance. Multi-function feature sets differentiate mid-market offerings through spray-pattern variability that mimics spa hydrotherapy without requiring full shower panel capital outlay.
The US EPA administers WaterSense labeling that governs flow-rate ceilings and performance testing protocols, while California CEC Title 20 imposes stricter 1.8 GPM limits that de facto shape national product portfolios. The EU Ecodesign Directive and associated F-Gas Regulation for thermostatic components create parallel compliance burdens for exporters serving dual markets. Stakeholders must monitor diverging regional efficiency thresholds that threaten SKU proliferation costs or force platform standardization sacrifices.
Market Dynamics
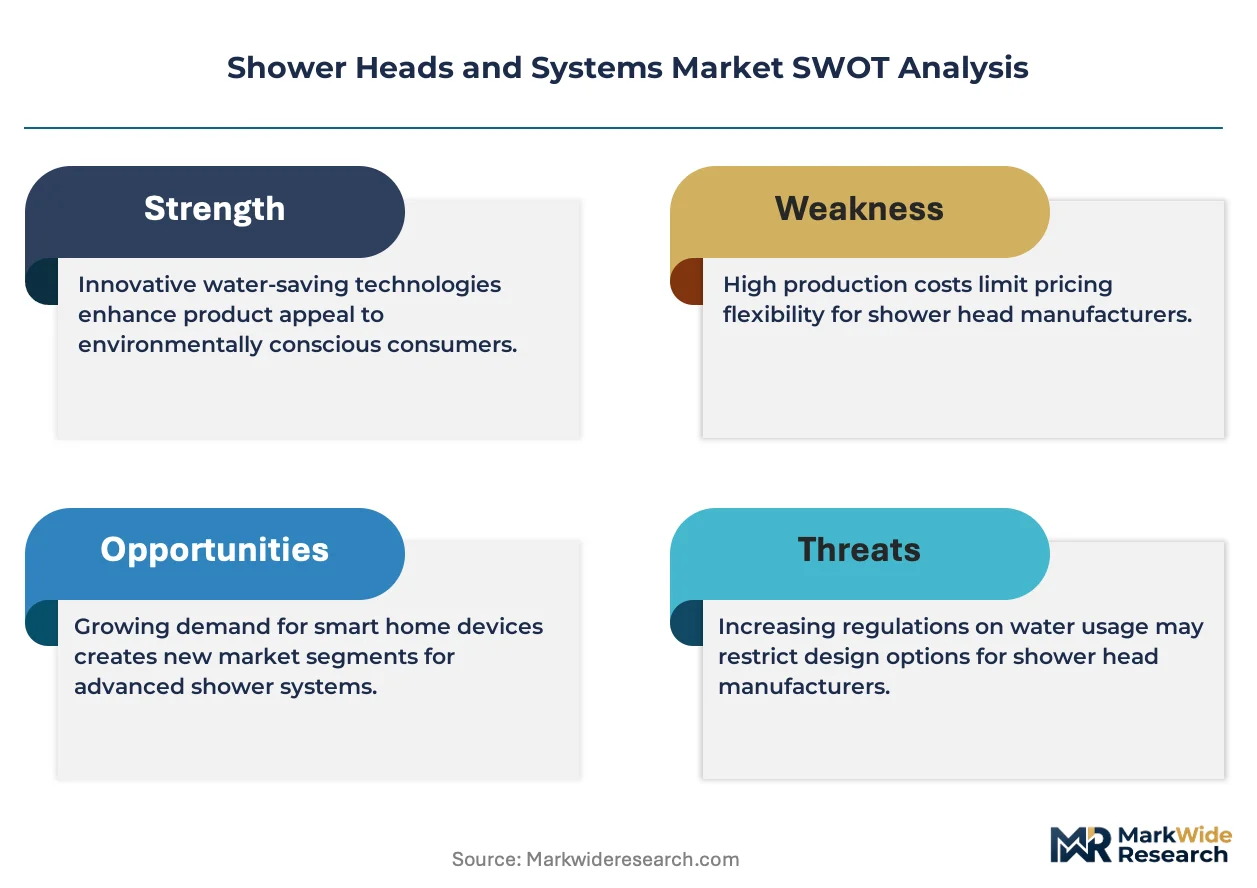
Water-efficiency mandates are compressing flow-rate architectures while manufacturers race to preserve spray quality, forcing fundamental redesigns of valve geometries and aerator engineering across product portfolios.
Growth Catalysts
- Residential bathroom renovation cycles:Aging housing stock in the United States and utility rebate programs are accelerating fixture replacement timelines, particularly in pre-1990 dwellings with legacy high-flow installations.
- EPA WaterSense certification thresholds:The program's 2.0 GPM ceiling and performance testing protocols are creating procurement preference hierarchies that favor certified manufacturers in institutional and municipal specification channels.
- Thermostatic cartridge precision:German-engineered temperature control technology is penetrating mid-market segments, reducing scald risk and enabling accessibility compliance for aging-in-place retrofits.
Market Restraints
- Brass alloy cost volatility:Foundry capacity concentration and copper-zinc price fluctuations are squeezing margin structures for valve assembly producers dependent on sand-cast component sourcing.
- California CEC Title 20 fragmentation:The state's 1.8 GPM limit creates SKU proliferation burdens for manufacturers attempting to serve unified national distribution with bifurcated product lines.
- Ceramic disc seal durability limits:Hard water mineral accumulation in regions with elevated calcium carbonate content accelerates cartridge failure rates, elevating warranty exposure and replacement part costs.
Strategic Opportunities
- India urban sanitation infrastructure:Government housing initiatives and rising middle-class bathroom upgrade expenditure are opening specification channels for pressure-compensating low-flow designs adapted to variable municipal supply pressure.
- Digital shower system convergence:Integration of Bluetooth-enabled preset programming with thermostatic hardware is expanding into wellness-oriented residential new construction and hospitality renovation segments.
- EU Ecodesign Directive alignment:Compliance infrastructure investments for F-Gas Regulation and water-efficiency labeling are creating first-mover advantages for exporters with dual-certification capabilities.
Industry Challenges
- Cross-threaded installation skill gaps:Plumber training deficits in proper sealing torque for NPT and BSP thread standards are elevating callback rates and damaging brand reputation in retail-channel warranty claims.
- WaterSense certification timeline compression:EPA testing queue congestion and documentation revision cycles are extending product launch windows, delaying revenue recognition for seasonal selling periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shower Heads and Systems Market |
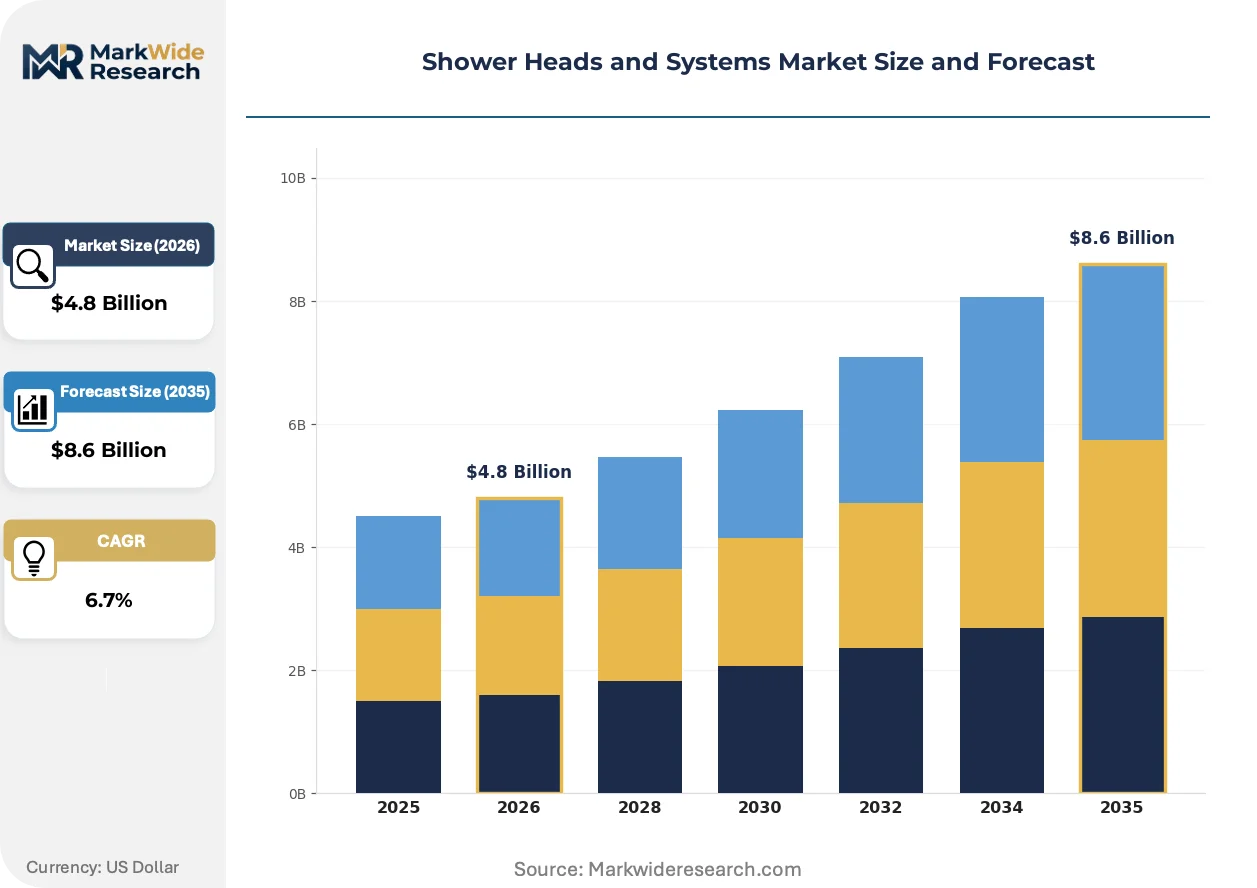
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Shower Heads, Handheld Shower Heads, Rain Shower Heads, Shower Panels Installation Type: Wall-Mounted, Ceiling-Mounted, Hydromassage Systems, Portable Units Material: Plastic, Stainless Steel, Brass, Chrome Feature: Water-Saving, Adjustable Spray, LED Lighting, Multi-Function |
| Companies Covered | Grohe, Waterpik, Kohler, Hydroluxe, Speakman, Moen, American Standard, FontanaShowers, Delta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shower Heads and Systems Market Evolving Landscape
Smart connectivity and material science advances are redefining user interaction models while regulatory divergence forces platform architecture decisions that will determine competitive viability through the forecast period.
Air-induction spray technology is expanding into premium residential and hospitality specification channels by infusing water streams with pressurized air volumes that amplify perceived flow intensity while maintaining sub-2.0 GPM consumption. Marriott and Hilton renovation standards are adopting these systems for guest bathroom consistency. The technology is expanding into mid-market replacement demand as price points compress through scaled aerator manufacturing.
California CEC Title 20 amendments are tightening flow-rate ceilings below federal WaterSense thresholds, forcing manufacturers to maintain parallel inventory or sacrifice performance parity in non-compliant jurisdictions. National retailers are consolidating procurement around Title 20-compliant SKUs to simplify supply chain logistics. Thermostatic mixing valve categories face the steepest redesign burden due to precision requirements at reduced flow volumes.
Specification influence is migrating from plumbing contractors to interior designers and architects controlling bathroom aesthetic decisions, shifting purchase authority upstream in residential new construction and luxury renovation projects. Showroom-based selection and digital visualization tools are displacing traditional wholesale counter transactions. This pattern concentrates in coastal United States metropolitan markets where design-build firms dominate project delivery.
Shower Heads and Systems Market Segmentation
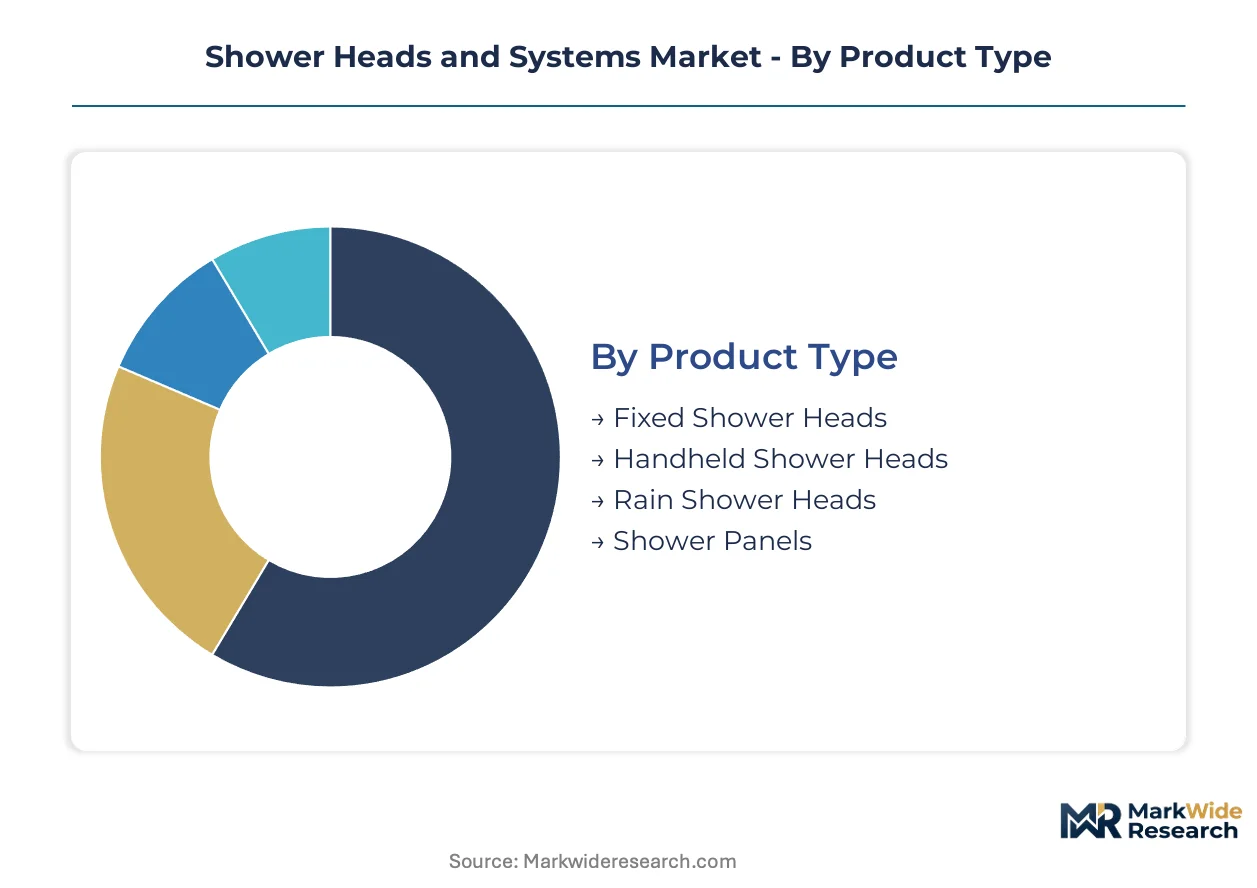
Product architecture decisions in shower heads and systems hinge on installation constraints, water pressure variability, and regulatory flow-rate ceilings that differ sharply across residential renovation versus new construction channels. Segmentation reveals how manufacturers balance SKU complexity against specification influence in fragmented distribution environments.
Product Type:
Buyers differentiate primarily by fixture mobility and spray coverage requirements, with aging-in-place retrofits demanding flexibility that conflicts with architectural integration trends in luxury new construction.
- Fixed Shower Heads:Traditional wall-mounted units dominate replacement demand in pre-1990 US housing stock where existing plumbing rough-ins constrain upgrade options. Volume concentrates in big-box retail channels serving DIY renovators responding to utility rebate programs for WaterSense-certified models.
- Handheld Shower Heads:Detachable hose assemblies with mounting brackets address accessibility compliance requirements for aging-in-place residential retrofits and commercial ADA specifications. Demand is accelerating fastest in coastal US metropolitan markets where design-build firms specify these for multi-generational household renovations.
- Rain Shower Heads:Ceiling-mounted spray discs deliver drenching coverage through enlarged faceplates, requiring dedicated rough-in plumbing that limits retrofit applicability.
- Shower Panels:Integrated vertical assemblies combining multiple spray outlets, thermostatic controls, and body jets command premium positioning in hospitality renovation and luxury residential new construction.
Fixed shower heads lead volumes today; handheld variants are gaining share fastest.
Installation Type:
Plumbing rough-in geometry and ceiling structural capacity determine specification feasibility, with hydromassage systems requiring dedicated water supply lines that elevate contractor skill requirements.
- Wall-Mounted:Standard bracket assemblies anchor to existing shower arms, minimizing labor cost for replacement cycles and dominating residential renovation volume.
- Ceiling-Mounted:Overhead spray delivery requires reinforced backing and dedicated supply risers, limiting adoption to new construction and gut renovations where framing access permits proper installation.
- Hydromassage Systems:Multi-jet vertical panels with integrated controls demand higher flow capacity and pressure-balancing infrastructure, concentrating in hospitality and wellness-oriented residential segments.
- Portable Units:Temporary fixtures with suction or clamp mounting serve rental properties and outdoor applications where permanent installation is prohibited.
Wall-mounted installations dominate current volumes; ceiling-mounted configurations are climbing the fastest as architectural ceiling integration gains specification influence.
Material:
Cost-positioning and corrosion resistance requirements split procurement between commodity plastics for volume replacement and architectural metals for visible fixture applications.
- Plastic:ABS and polycarbonate housings dominate economy-tier retail SKUs, with manufacturers leveraging injection molding scale to hit price points below twenty dollars for basic replacement demand.
- Stainless Steel:Grade 304 and 316 alloys deliver corrosion immunity for coastal environments and ceiling-mounted rain heads where weight-bearing capacity matters.
- Brass:Sand-cast and forged valve bodies provide machinability for precision cartridge seating, though copper-zinc price volatility squeezes margin structures for mid-market producers.
- Chrome:Electroplated finishes over brass or zinc substrates dominate visible surface specifications, with PVD coating advances extending wear resistance in hard water regions.
Plastic leads volumes today; stainless steel is expanding most quickly in premium specification channels.
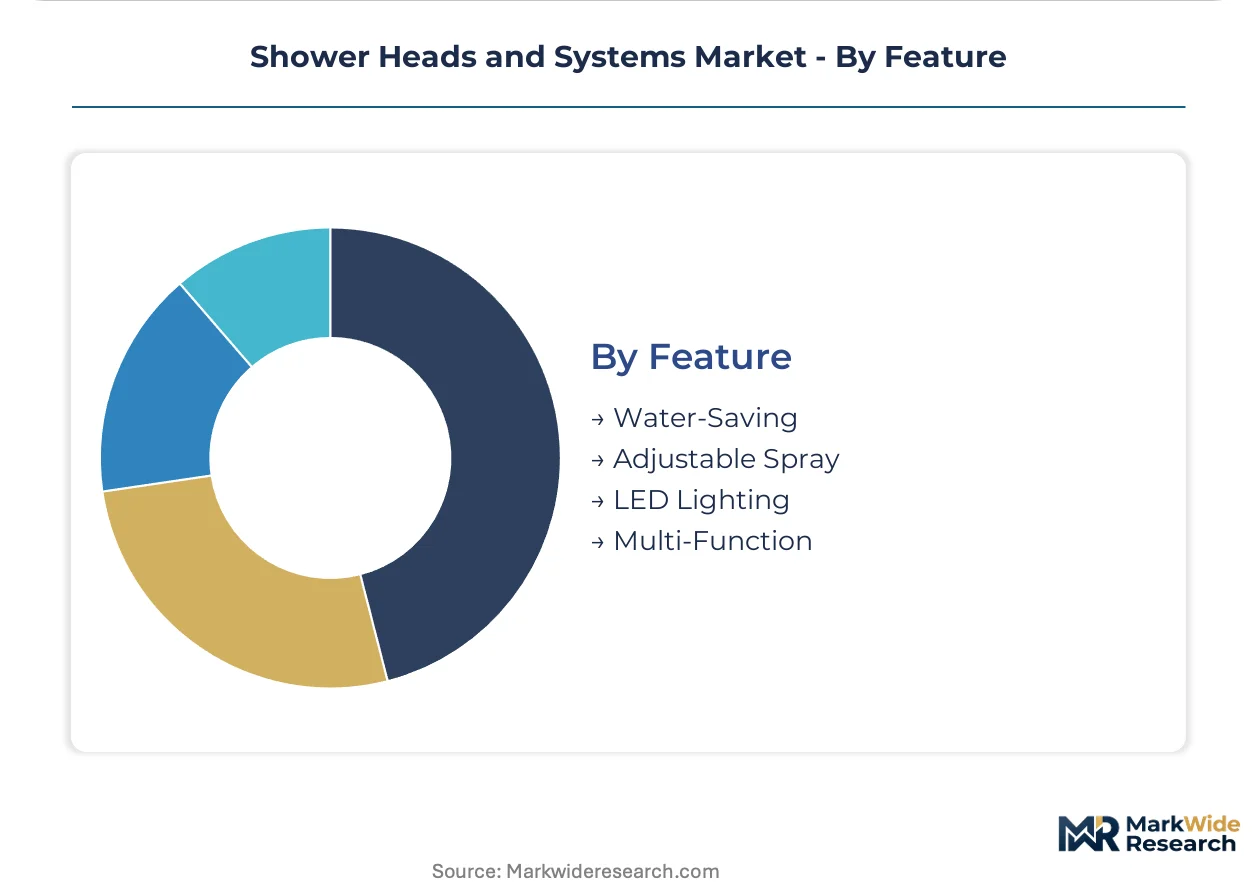
Feature:
Regulatory compliance and wellness positioning drive feature bundling, with water-saving mandates now baseline rather than differentiating.
- Water-Saving:Flow restrictors and aerator engineering delivering sub-2.0 GPM performance are mandatory for EPA WaterSense certification and California CEC Title 20 compliance, reshaping baseline product architecture across all price tiers.
- Adjustable Spray:Dial-actuated pattern selection covering massage, mist, and concentrated streams differentiates mid-market offerings without requiring full panel capital outlay.
- LED Lighting:Temperature-indicating color change and chromotherapy positioning add electronics complexity that elevates warranty exposure and concentrates in wellness-oriented hospitality specifications.
- Multi-Function:Combined fixed and handheld delivery through diverter valves addresses flexibility demands in single-head installations, bridging retrofit constraints with user experience expectations.
Water-saving features lead volumes today; multi-function configurations are gaining share fastest as manufacturers consolidate spray flexibility into single-fixture solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The shower heads and systems industry traces its modern mass-production origins to post-war American suburbanization, when standardized plumbing codes and tract housing construction created the first national fixture markets. European precision engineering later introduced thermostatic safety technology, while Asian manufacturing scale reshaped cost structures from the 1990s onward.
United States
Aging housing stock built before 1990 drives replacement demand, with pre-1990 dwellings containing legacy high-flow fixtures now targeted by utility rebate programs. The EPA WaterSense certification program mandates 2.0 GPM flow-rate ceilings and performance testing protocols that govern institutional procurement. California's CEC Title 20 imposes stricter 1.8 GPM limits that de facto shape national product portfolios, with Los Angeles and San Francisco metropolitan areas serving as testbeds for ultra-low-flow architectural integration.
Germany
Engineering-intensive thermostatic cartridge technology anchors premium positioning, with German-manufactured precision components penetrating mid-market segments globally. The EU Ecodesign Directive and F-Gas Regulation create compliance frameworks for water-efficiency labeling and thermostatic component standards. The Rhine-Ruhr industrial corridor hosts specialized foundry and machining clusters that supply valve assembly producers across Europe.
China
Mass-scale manufacturing of ABS and polycarbonate housings supplies economy-tier retail SKUs worldwide, with injection molding scale enabling sub-twenty-dollar price points. GB standards for water-efficiency labeling and MIIT industrial policy guide domestic product architecture. The Pearl River Delta manufacturing cluster dominates export production, with Shenzhen and Dongguan facilities serving as primary sourcing hubs for North American and European distributors.
India
Government housing initiatives and rising middle-class bathroom upgrade expenditure are opening specification channels for pressure-compensating low-flow designs. The Bureau of Indian Standards (BIS) certification requirements and state-level urban sanitation programs shape procurement criteria. Mumbai and Bangalore metropolitan areas concentrate retail distribution infrastructure, with design-build firms specifying adapted fixtures for variable municipal supply pressure conditions.
Japan
Wellness-oriented hospitality renovation and residential new construction sustain demand for digital shower system integration. METI energy-efficiency standards and JIS certification protocols govern thermostatic performance and water consumption limits. The Kanto region around Tokyo hosts specification influence clusters where interior designers and architects control bathroom aesthetic decisions in luxury project delivery.
Shower Heads and Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and material grade, with architectural specification influence concentrating among European-engineered thermostatic specialists while retail volume flows through scale-oriented manufacturers with captive foundry or molding capacity. The market structure splits across three strategic archetypes: integrated brass foundry operators controlling valve supply chains, injection-molding scale players dominating economy-tier retail, and precision-engineering specialists commanding thermostatic premium positioning. Dominant competitive moves include exclusive big-box distribution agreements locking retail shelf space and backward integration into brass alloy sourcing to buffer copper-zinc price volatility.
Among the named manufacturers, Grohe and Kohler occupy positions on the premium-engineering vector, with Grohe exemplifying European thermostatic precision and Kohler representing integrated foundry capacity for valve assembly control. Moen anchors the retail-scale tier through big-box distribution presence. These three illustrate how geographic origin and corporate structure correlate with strategic archetype: the German GmbH format signals engineering credibility, the American Inc. structure supports retail scale, and diversified manufacturing groups enable supply chain verticality.
| Leading Market Players |
|---|
| Grohe |
| Waterpik |
| Kohler |
| Hydroluxe |
| Speakman |
| Moen |
| American Standard |
| FontanaShowers |
| Delta |
| Others |
Value Network & Pricing Analysis
Precision machining labor pools in the Rhine-Ruhr corridor anchor German thermostatic cartridge production, while Guangdong injection molding workforces enable Chinese economy-tier manufacturing at order-of-magnitude lower wage bases, creating pricing-tier spreads that separate premium engineering from commodity replacement demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates WaterSense-certified brass valve assemblies from basic plastic fixed heads. Price differentiation hinges on EPA certification tier and captive foundry integration, with California CEC Title 20 compliance adding cost premiums. Pricing pressure stems from copper-zinc alloy volatility squeezing mid-market producers. DIY renovators at big-box retail show highest price sensitivity; hospitality specifiers demonstrate lowest.
Supply Chain Analysis
Refurbishment flows for failed thermostatic cartridges concentrate in German technical service networks, while Chinese manufacturing clusters generate minimal reverse logistics due to replace-rather-than-repair economics. Supply concentrates in China for ABS housings, Germany for precision valves, and India for emerging pressure-compensating designs. Raw material dependencies span copper-zinc brass alloys, 304/316 stainless steel, and engineering-grade polycarbonate. Single-source vulnerability sits with sand-cast brass foundry capacity. Distribution runs through big-box retail for replacement volume and showroom-specification channels for new construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between California's 1.8 GPM regulatory ceiling and federal WaterSense thresholds creates manufacturing cost differentials that reward dual-certification platform investments over single-standard SKU proliferation.
For Market Incumbents: To counter brass alloy cost volatility, secure captive foundry capacity or long-term copper-zinc supply agreements. Consolidate specification influence through exclusive design-build firm partnerships in coastal US metropolitan markets where architect-driven procurement concentrates. For New Entrants and Emerging Players: Air-induction spray technology offers entry wedge into mid-market wellness positioning without thermostatic engineering barriers. Target India's pressure-compensating low-flow segment where municipal supply variability creates specification gaps. Pursue direct-to-plumber digital channels bypassing wholesale counter gatekeepers. For Investors and Strategic Acquirers: Plumbing fixture conglomerates are the most active acquirer in this space, seeking thermostatic engineering capabilities to complete wellness portfolios. Five-to-ten year viability favors dual-certification platform owners with India distribution infrastructure. Monitor California CEC amendment trajectories for regulatory arbitrage inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Platform Investment | California CEC Title 20 and EPA WaterSense alignment reduces SKU fragmentation costs for national distribution. |
| Captive Brass Foundry Integration | Upstream control over copper-zinc alloy supply buffers margin compression from London Metal Exchange volatility. |
| Air-Induction Technology Licensing | Marriott and Hilton renovation standards create specification pull for aerator engineering without full panel capital outlay. |
| India Distribution Infrastructure Buildout | Bureau of Indian Standards certification and state sanitation programs open pressure-compensating low-flow specification channels. |
| Digital Shower System Convergence | Bluetooth-enabled preset programming integration expands wellness positioning in hospitality renovation and residential new construction. |
Research Methodology
Bottom-up residential renovation and new construction modeling reconciled against top-down brass foundry and injection molding capacity tracking forms the analytical core. Primary interviews with plumbing contractor purchasing managers, big-box retail category buyers, design-build firm specification directors, and thermostatic cartridge engineering directors combined with secondary validation from EPA WaterSense certification databases, California CEC Title 20 compliance filings, EU Ecodesign Directive implementation reports, and customs trade data for brass alloy and plastic housing imports.
Input-output matrices map fixture unit demand against rough-in installation type, material grade, and regulatory certification tier across the projection horizon. Segmentation dimensions span product mobility, installation geometry, material composition, and feature bundling. CAGRs derive from replacement cycle velocity, housing stock age distribution, and utility rebate program expansion trajectories. Forecast inputs incorporate copper-zinc price band scenarios and municipal water pressure variability indices for emerging market penetration modeling.
The model holds under stable regulatory divergence between federal and state efficiency thresholds; deviation in California CEC amendment timing or EPA WaterSense protocol revision would shift platform standardization economics. Practitioners should monitor brass alloy spot price volatility and WaterSense testing queue congestion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Europe Digital Showers Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Electric Blankets Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Dosage Spoon Market
Household Items
Gas Hobs Market
Household Items
Titanium Thermos Cup Market
Household Items
Japan Digital Showers Market
Household Items
Home Use Air Purifiers Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Ultrasonic Diffusers Market
Household Items
Soap Dispenser Market
Household Items
Household Sewing Machines Market
Household Items
Collapsible Water Bottle Market