
 Commercial Locker Market | 2026-2036
Commercial Locker Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Locker Market Insights
Buyer concentration across fitness center chains and co-working operators is restructuring procurement dynamics toward multi-site contracts with integrated technology requirements. Penco leverages its manufacturing scale to serve large-format gym deployments, while Hollman Inc. differentiates through custom wood and laminate configurations for premium corporate installations. Lyon LLC anchors its position in educational institutions with heavy-gauge steel products designed for high-traffic durability.
Commercial lockers are enclosed storage compartments fabricated from steel, aluminum, plastic, or wood, typically ranging from 12 to 18 inches in width and engineered with ventilation, locking mechanisms, and modular stacking capability for secure personal item storage in shared facilities. Steel lockers sustain the largest installed base across transportation hubs and schools due to cost efficiency and impact resistance, while electronic and biometric lock technologies capture expanding margin pools as facilities prioritize keyless access and audit trails. Plastic lockers are gaining share in aquatic and outdoor environments where corrosion resistance outweighs premium pricing.
The EPA's VOC emissions standards for indoor furnishings and the EU's REACH restrictions on surface coatings directly shape material selection and finishing processes for locker manufacturers serving North American and European buyers. OSHA workplace safety guidelines influence locker dimensioning and ventilation in industrial employee facilities, while the ISO 9001 quality management framework conditions supplier qualification for institutional tenders. Stakeholders must evaluate how smart lock interoperability standards and evolving cybersecurity requirements for connected access systems will reshape R&D priorities and partnership strategies across the vendor landscape.
Market Dynamics
Multi-site fitness chains and co-working operators are consolidating procurement into centralized technology-integrated contracts, compressing vendor margins while elevating interoperability requirements for smart access systems.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Manufacturers accelerate recycled steel and aluminum adoption to qualify for public sector tenders across Germany, France, and the Netherlands.
- Biometric lock integration:Fitness centers deploy fingerprint and facial recognition systems to eliminate key management costs and strengthen member retention metrics.
- Transit hub modernization:Germany's Deutsche Bahn and municipal operators replace legacy locker banks with modular, corrosion-resistant units in high-traffic stations.
Market Restraints
- Aluminum and steel price volatility:Raw material input swings compress fabrication margins, particularly for mid-tier suppliers lacking long-term supply agreements.
- REACH surface coating restrictions:ECHA limitations on solvent-based finishes force costly process retooling for manufacturers serving European institutional buyers.
- Plastic locker durability ceiling:HDPE and phenolic alternatives face penetration limits in high-impact environments where steel maintains structural superiority.
Strategic Opportunities
- India transit infrastructure buildout:Metro expansions in Delhi, Mumbai, and Bangalore create first-mover positioning for corrosion-resistant locker systems in tropical climates.
- Cybersecurity certification tailwinds:ISO 27001 and IEC 62443 alignment for connected locks opens institutional segments with mandatory audit trail requirements.
- Co-working amenity arms race:WeWork competitors and boutique operators differentiate through premium wood-laminate configurations with integrated charging and climate control.
Industry Challenges
- Smart-legacy system interoperability:Facilities with existing mechanical infrastructure face complex retrofitting paths when upgrading to networked access platforms.
- Embedded software talent scarcity:Manufacturers struggle to recruit firmware engineers capable of integrating biometric sensors with cloud-based management dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Locker Market |
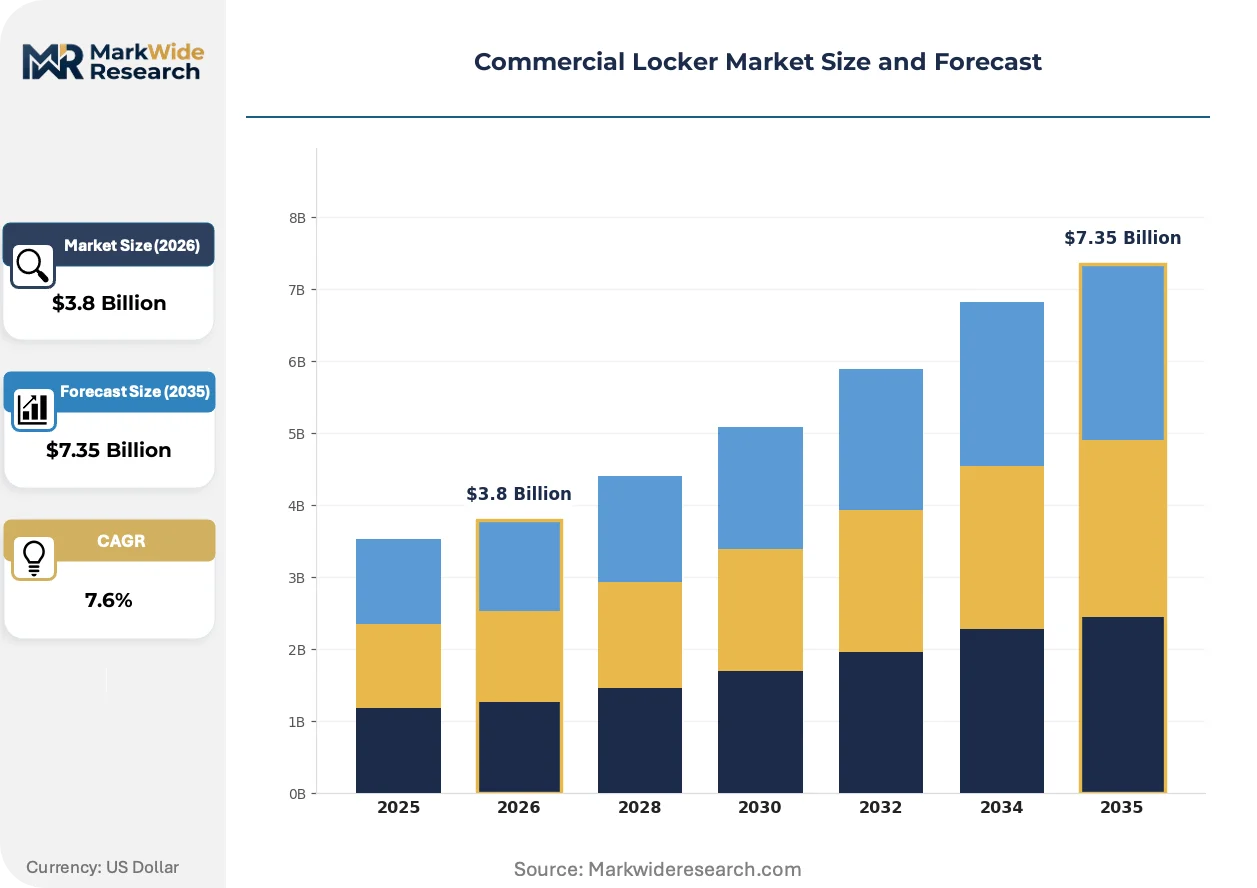
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Lockers, Wooden Lockers, Plastic Lockers, Aluminum Lockers, Wire Mesh Lockers Application: Corporate Offices, Educational Institutions, Transportation Hubs, Fitness Centers, Public Libraries Technology: Mechanical Lock, Electronic Lock, Biometric Lock, RFID Lock, Digital Keypad End User: Employees, Students, Travelers, Gym Members, Library Patrons |
| Companies Covered | Penco, Hollman Inc., Lyon LLC, Salsbury Industries, DeBourgh Mfg, American Locker, Hadrian Manufacturing Inc., List Industries, Hamilton Safe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Locker Market Trends and Innovations
Connected access architectures and sustainable material specifications are redefining product roadmaps, with vendor R&D budgets pivoting toward software-defined functionality and circular design principles.
RFID and NFC-enabled locker systems are electrifying facility management workflows across airport lounges and corporate campuses. Hospitality operators at Frankfurt Airport and Singapore Changi deploy tap-to-open units that eliminate front-desk key handoffs. The technology is electrifying margin structures by converting hardware sales into recurring SaaS revenue streams for access analytics.
REACH Annex XVII restrictions on chromium VI in surface treatments are forcing coating reformulations across European supply chains. Manufacturers serving German educational and transit sectors now qualify electrophoretic deposition and powder-coat alternatives for institutional tenders. Steel locker fabricators with in-house finishing capabilities capture preferential positioning as import-dependent competitors face compliance delays.
Subscription-based locker-as-a-service models are displacing capital purchase arrangements in flexible workspace verticals. Operators in London, Berlin, and Amsterdam lease units with bundled maintenance and technology refresh guarantees. Facility managers in Nordic co-working clusters prioritize opex-aligned contracts that transfer obsolescence risk to vendors while preserving upgrade flexibility.
Commercial Locker Market Segmentation
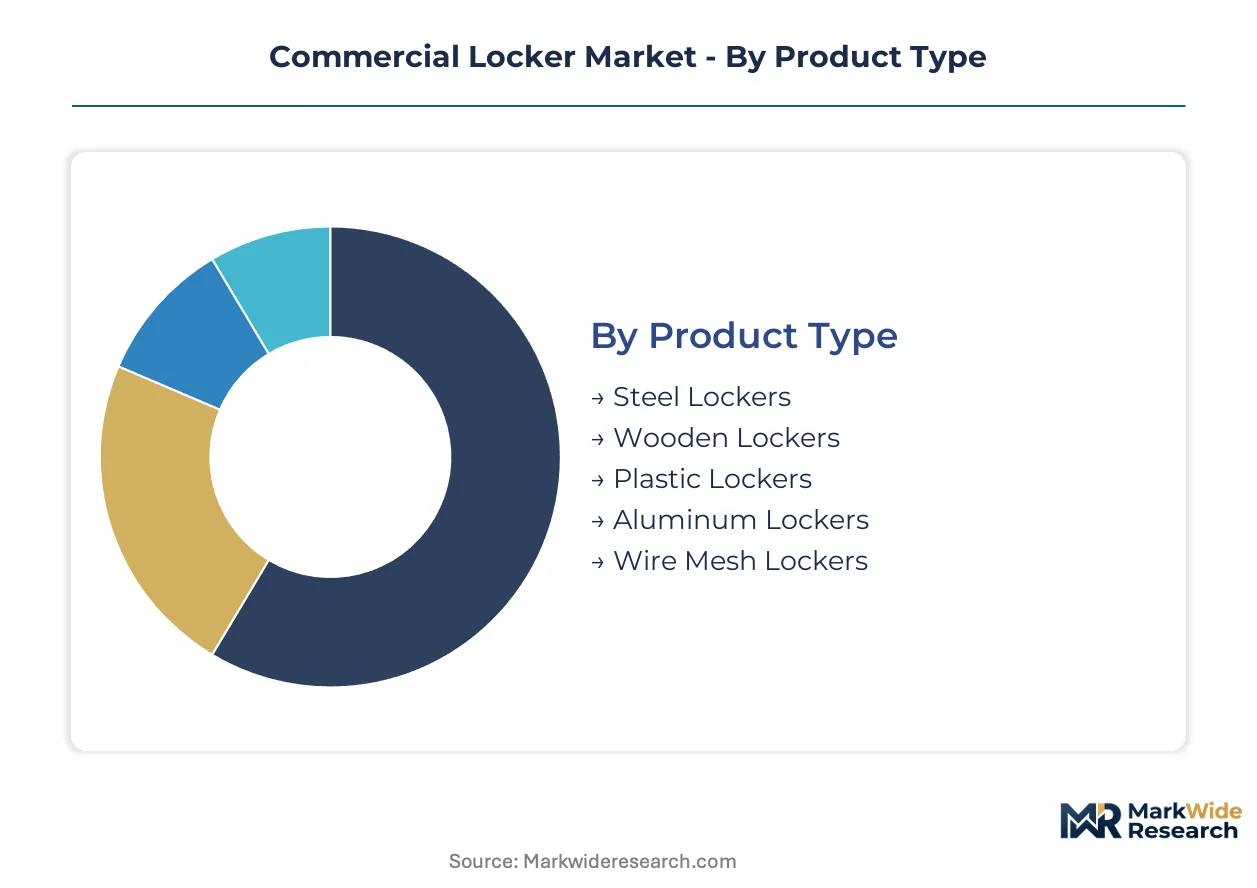
Facility operators segment procurement by durability requirements, aesthetic specifications, and access technology maturity. Replacement cycles vary dramatically across verticals, with transit hubs and fitness centers driving faster refresh rates than educational institutions.
Product Type:
Upgrade cycles accelerate where corrosion resistance and smart-lock compatibility reshape capital planning decisions.
- Steel Lockers:Cold-rolled steel construction with powder-coat finishing delivers impact resistance for high-traffic environments. Deutsche Bahn and municipal German transit operators specify these units for station modernization programs facing heavy daily use. The EU Green Deal's embodied carbon mandates push fabricators toward recycled steel feedstocks to qualify for public tenders.
- Plastic Lockers:HDPE and phenolic resin formulations resist moisture and chemical exposure in aquatic centers and outdoor installations. Operators in tropical climates prioritize these units where humidity degradation threatens metal alternatives, though structural load limits constrain deployment in high-impact settings.
- Wooden Lockers:Custom laminate and veneer configurations serve premium corporate installations and boutique fitness studios seeking differentiated member experiences.
- Aluminum Lockers:Lightweight extruded profiles offer corrosion immunity for coastal facilities and swimming pool environments.
- Wire Mesh Lockers:Open-grid steel construction provides ventilation and visual security for industrial employee facilities and warehouse operations.
Volume placements concentrate in steel configurations; the faster expansion belongs to plastic alternatives.
Application:
Procurement patterns diverge sharply between capital-constrained public sectors and experience-investing private operators.
- Fitness Centers:Multi-site chains deploy technology-integrated banks with biometric access and member analytics integration. Smart locker investments now rank alongside equipment quality in retention strategy, with operators in Germany and the Netherlands leading European deployment.
- Transportation Hubs:Modular corrosion-resistant systems replace legacy installations across high-traffic stations. Germany's facility modernization accelerates replacement cycles, while India's metro expansions in Delhi and Mumbai create new demand corridors for tropical-grade specifications.
- Corporate Offices:Hybrid workplace models drive amenity-focused specifications with integrated charging and climate control.
- Educational Institutions:Heavy-gauge steel products dominate K-12 and university installations where durability outweighs technology integration.
- Public Libraries:Budget-constrained procurement favors basic mechanical-lock configurations with extended service life requirements.
Installed base dominance rests with educational institutions; steepest expansion trajectory appears in fitness center deployments.
Technology:
Margin structures electrify where hardware sales convert to recurring SaaS revenue through connected access platforms.
- Biometric Lock:Fingerprint and facial recognition systems eliminate key management overhead while strengthening audit trail capabilities. Fitness centers in Germany and Singapore deploy these units to differentiate member experience and reduce operational friction.
- RFID Lock:NFC-enabled tap-to-open systems streamline access across airport lounges and corporate campuses. Frankfurt Airport and Singapore Changi hospitality operators deploy these for front-desk elimination and usage analytics.
- Electronic Lock:Battery-powered digital mechanisms bridge cost and functionality for mid-tier facility upgrades.
- Mechanical Lock:Traditional key and combination systems retain dominance in budget-constrained public sector tenders.
- Digital Keypad:PIN-code entry offers keyless convenience without network dependency for facilities with limited IT infrastructure.
Mechanical locks retain volume leadership; biometric systems gain share fastest in premium verticals.
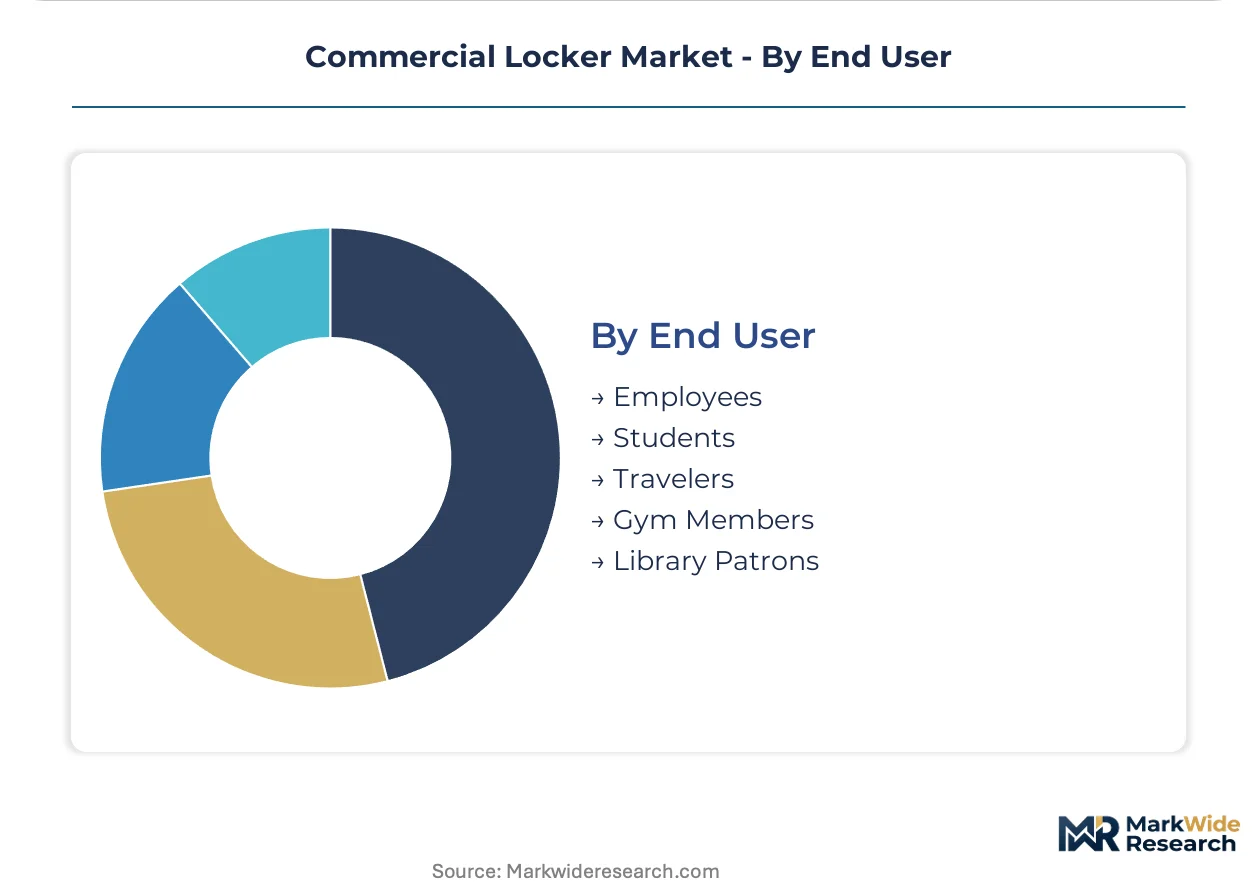
End User:
User behavior patterns dictate durability specifications, access convenience requirements, and technology integration depth.
- Employees:Industrial facilities require OSHA-compliant ventilation and dimensioning, while corporate campuses demand amenity-grade finishes with charging integration.
- Gym Members:Fitness operators prioritize seamless access experience and hygiene-resistant materials to support retention metrics.
- Travelers:Transit users need intuitive operation under time pressure and secure storage for luggage and valuables.
- Students:Educational settings demand vandal-resistant construction with minimal maintenance requirements across extended replacement cycles.
- Library Patrons:Occasional-use scenarios favor simple mechanical access with low operational complexity.
Employee-facing installations represent the largest addressable base; gym member applications show the quickest technology uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness center chains and transit operators in Germany concentrate replacement demand as the EU Green Deal reshapes material specifications. Procurement patterns diverge sharply between carbon-conscious European tenders and cost-optimized emerging market deployments.
Germany
Deutsche Bahn and municipal transit operators accelerate station modernization with modular, corrosion-resistant locker banks. The EU Green Deal's embodied carbon mandates push fabricators toward recycled steel feedstocks to qualify for public tenders. Manufacturing clusters in North Rhine-Westphalia supply heavy-gauge steel units for educational and industrial facilities.
United States
Multi-site fitness chains consolidate procurement into technology-integrated contracts with biometric access requirements. EPA VOC emissions standards for indoor furnishings shape coating and finishing process selections. Fabricators in the Midwest industrial corridor serve institutional buyers with OSHA-compliant ventilation and dimensioning specifications.
India
Metro expansions in Delhi, Mumbai, and Bangalore generate demand for tropical-grade, corrosion-resistant locker systems. The Bureau of Indian Standards (BIS) certification requirements condition supplier qualification for transit infrastructure tenders. Manufacturing activity concentrates in Gujarat and Maharashtra as domestic fabrication capacity expands to serve South Asian transit buildouts.
Netherlands
Co-working operators in Amsterdam and Rotterdam deploy subscription-based locker-as-a-service models with bundled maintenance guarantees. REACH Annex XVII restrictions on chromium VI surface treatments force coating reformulations across supply chains. Randstad-based facility managers prioritize opex-aligned contracts that transfer obsolescence risk to vendors.
Singapore
Changi Airport hospitality operators deploy RFID-enabled tap-to-open systems for front-desk elimination and usage analytics. The tropical climate drives specification toward corrosion-immune aluminum and phenolic resin configurations. Premium fitness studios in the central business district differentiate through biometric access integration.
Commercial Locker Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart-lock integration and circular material sourcing. The vendor base stratifies across three capability levels: scale-driven fabricators serving multi-site contracts, customization specialists capturing premium corporate installations, and regional metalworkers competing on price for public sector tenders. Dominant competitive moves include backward integration into recycled steel supply chains and strategic partnerships with access technology providers.
Among North American fabricators, Penco, Hollman Inc., and Lyon LLC occupy distinct positioning archetypes. Penco represents the scale-driven tier serving large-format gym deployments through manufacturing breadth. Hollman Inc. exemplifies the customization specialist archetype with wood and laminate configurations for premium installations. Lyon LLC anchors the institutional durability segment with heavy-gauge steel products designed for high-traffic educational environments.
| Leading Market Players |
|---|
| Penco |
| Hollman Inc. |
| Lyon LLC |
| Salsbury Industries |
| DeBourgh Mfg |
| American Locker |
| Hadrian Manufacturing Inc. |
| List Industries |
| Hamilton Safe |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent scarcity in North Rhine-Westphalia and Gujarat widens pricing spreads between premium smart-lock systems and basic mechanical configurations. Labor-cost differentials between German fabrication clusters and South Asian assembly operations translate into three-tier pricing architecture across subscription SaaS, project-based, and commodity spot models.
Pricing Analysis
Volume placements concentrate in mechanical-lock steel configurations where per-unit transactional pricing dominates public sector tenders; margin pools electrify in biometric and RFID-enabled systems where SaaS-tiered subscriptions convert hardware sales into recurring access analytics revenue. Price differentiation hinges on ISO 27001 cybersecurity certification and after-sales service bundling. Pricing pressure stems from aluminum and steel input volatility compressing fabrication margins for mid-tier suppliers lacking long-term supply agreements. Budget-constrained educational institutions exhibit highest price sensitivity; premium fitness chains and co-working operators prioritize interoperability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cold-rolled steel feedstock and Taiwanese electronic lock component suppliers serving European and North American fabricators. Manufacturing gravity centers on Germany, the United States, and India, with raw material dependencies spanning recycled steel billets, aluminum extrusions, and biometric sensor modules. Tariff exposure on Chinese steel inputs threatens margin stability for import-dependent competitors. Distribution runs through direct multi-site contracts with fitness chains and transit operators, supplemented by regional metalworkers competing on price for institutional tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around technology-integrated procurement contracts that squeeze weaker fabricators lacking smart-lock development capabilities or circular material sourcing credentials.
For Market Incumbents: To counter embedded software talent scarcity eroding R&D timelines, Penco-scale fabricators should deepen backward integration into recycled steel supply chains and pursue ISO 27001 certification for connected lock platforms. Capacity expansion in Gujarat serves Indian transit infrastructure buildouts while insulating against EU REACH compliance delays.
For New Entrants and Emerging Players: Boutique co-working operators in Amsterdam and Rotterdam represent an underserved buyer archetype seeking subscription-based locker-as-a-service models with bundled maintenance guarantees. First-mover positioning in India's tropical-grade corrosion-resistant segment offers white-space access, with go-to-market leverage through BIS certification partnerships.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier customization specialists given accelerating biometric lock integration across German fitness chains. Long-term viability favors fabricators with in-house finishing capabilities circumventing REACH Annex XVII coating restrictions. Watch Deutsche Bahn procurement volumes as inflection indicator for European public sector technology refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Lock Platform Development | Fingerprint and facial recognition integration captures premium fitness center contracts in Germany and Singapore. |
| Recycled Steel Feedstock Integration | EU Green Deal embodied carbon mandates condition public tender qualification across Deutsche Bahn modernization programs. |
| Cybersecurity Certification Investment | ISO 27001 and IEC 62443 alignment opens institutional segments with mandatory audit trail requirements. |
| Locker-as-a-Service Model Launch | Subscription contracts transfer obsolescence risk to vendors while aligning with Nordic co-working opex preferences. |
| India Manufacturing Footprint Expansion | BIS certification and Gujarat production capacity serve Delhi and Mumbai metro buildouts with tropical-grade specifications. |
Research Methodology
Independent corroboration across facility procurement directors, smart-lock firmware engineers, and coating process specialists underwrites the qualitative findings. Primary interviews with fitness chain operations executives, transit authority asset managers, and co-working space facility directors combined with secondary validation from SEC filings of publicly traded fabricators, EPA VOC emissions documentation, and EU Green Deal tender databases. Bottom-up unit economics triangulate against top-down sector spend estimates across educational, corporate, and transportation verticals.
Rate-of-change decomposition separates replacement cycle acceleration from net new installation growth across the projection horizon. Segmentation dimensions span product type, application vertical, access technology maturity, and end-user behavior pattern. CAGRs derive from installed base turnover analysis and technology penetration curves, with biometric lock adoption rates and recycled steel feedstock cost trajectories as industry-specific forecast inputs.
Revisions become necessary when raw material price volatility exceeds historical bands, REACH regulatory scope expands to additional coating chemistries, or smart-lock interoperability standards fragment across vendor ecosystems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Snow Blower Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Europe Cookware Market
Household Items
Oman Gas Hobs Market
Household Items
Commercial Lawnmower Market
Household Items
Folded Tissues Market
Household Items
Insulated Water Bottles Market
Household Items
Electric Air Freshener Market
Household Items
Party Supplies Market
Household Items
Paper Towel Dispenser Market
Household Items
Home Use Air Purifiers Market
Household Items
Drinkware Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Residential Water Purifier Market
Household Items
Integrated Smart Toilet Market
Household Items
US Air Purifier Market