
 Europe Ice/Cooler Box Market | 2026-2036
Europe Ice/Cooler Box Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ice/Cooler Box Market Insights
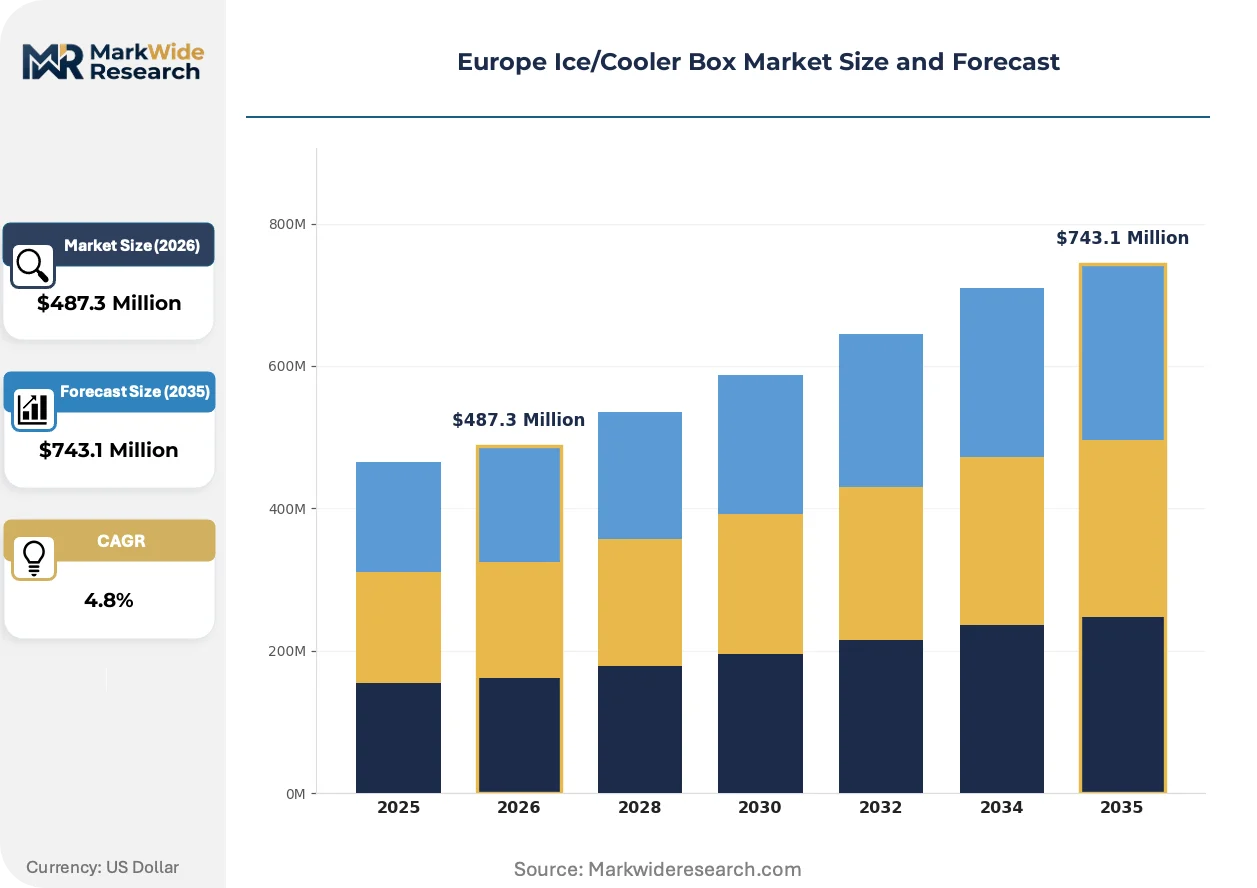
A widening vacuum-panel manufacturing scale is redrawing competitive boundaries across the Europe ice/cooler box landscape. YETI COOLERS LLC leverages rotational-molding expertise to dominate premium hard-sided segments with extended ice-retention claims. va-Q-tec AG anchors its position through proprietary vacuum insulation panel technology originally developed for pharmaceutical cold chain. CSafe Global competes on airline-certified passive thermal packaging validated across EU temperature lanes.
Europe ice/cooler boxes are thermally insulated enclosures engineered to maintain sub-ambient temperatures for perishable cargo, typically achieving 48–120 hour stability through polyurethane foam or vacuum insulation panel cores with phase-change materials. Their primary commercial purpose spans pharmaceutical distribution, fresh food logistics, and recreational outdoor consumption where mechanical refrigeration is unavailable. Hard coolers occupy the dominant value position due to durability requirements in pharmaceutical and event catering channels, while soft cooler demand accelerates among recreational vehicle owners seeking collapsible storage. Electric cooler adoption remains nascent outside Germany and France where auxiliary power infrastructure in camper vans is most developed.
The EU F-Gas Regulation and ECHA REACH framework govern refrigerant alternatives and chemical composition of insulation foams, directly shaping material substitution timelines for manufacturers. CE marking under the EU Packaging and Packaging Waste Directive additionally constrains recyclability claims and end-of-life obligations for plastic-intensive designs. Stakeholders must monitor evolving Ecodesign requirements and national extended producer responsibility schemes as Brussels tightens circular economy enforcement across thermal packaging categories.
Market Dynamics
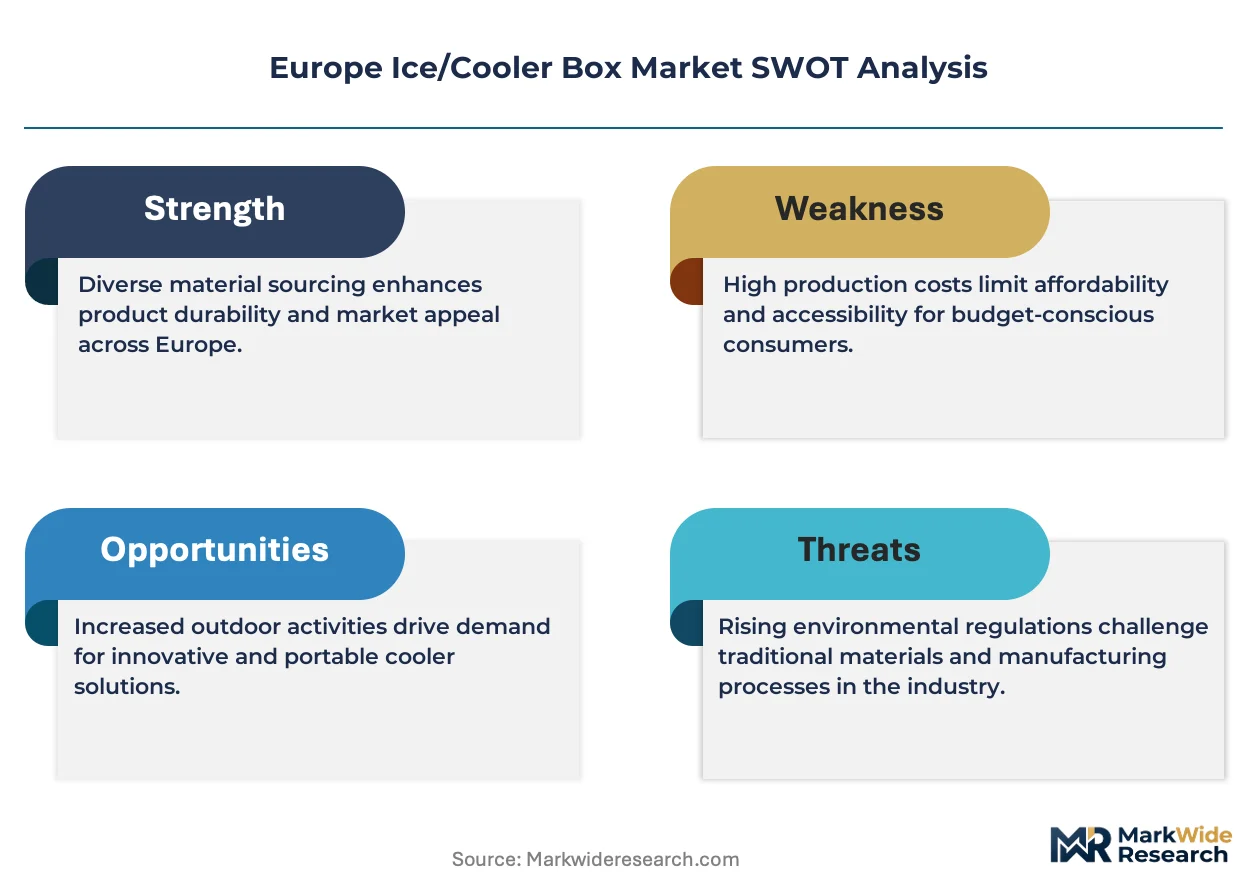
The EU F-Gas Regulation is forcing a wholesale material transition across Europe ice/cooler box manufacturing, eliminating hydrofluorocarbon-based blowing agents from polyurethane foam cores and accelerating vacuum insulation panel adoption. This regulatory compression is redrawing supplier capabilities and procurement criteria simultaneously.
Growth Catalysts
- Pharmaceutical Cold-Chain Expansion:Biotech distributors across Germany, Switzerland, and the Netherlands are procuring airline-certified passive thermal packaging for temperature-sensitive biologics. EMA validation requirements for last-mile distribution are tightening performance specifications.
- REACH-Driven Material Substitution:ECHA restrictions on isocyanates and flame retardants are pushing manufacturers toward bio-based polyols and non-halogenated insulation cores. Reformulation investments are creating first-mover advantages for compliant suppliers.
- Camping and Outdoor Recreation Surge:Post-pandemic vehicle-based tourism in France, Italy, and Scandinavia is driving collapsible soft cooler demand among recreational vehicle owners. Auxiliary power infrastructure in German camper vans is additionally stimulating electric cooler adoption.
Market Restraints
- Raw Material Concentration Risk:Vacuum insulation panel core materials depend on precipitated silica supply concentrated in German and Belgian chemical clusters. Disruption to these feedstocks propagates through European cooler box manufacturing within weeks.
- Technical Performance Ceiling:Passive insulation systems face hard physical limits on duration-to-weight ratios beyond 120 hours, constraining ultra-long-haul pharmaceutical shipments without active refrigeration backup.
- Regulatory Friction from Packaging Waste Directive:CE marking requirements under extended producer responsibility schemes impose end-of-life recycling obligations that increase compliance costs for multi-material hard-sided designs.
Strategic Opportunities
- Underpenetrated Eastern European Logistics:Poland, Hungary, and Romania lack dedicated pharmaceutical cold-chain infrastructure, creating white space for temperature-validated packaging rental services and depot networks.
- EU Green Deal Procurement Incentives:Public sector catering and healthcare purchasing mandates are prioritizing circular-economy-certified thermal packaging, rewarding designs with take-back programs and recyclable mono-material construction.
- Phase-Change Material Convergence:Integration of salt-hydrate and paraffin-based thermal batteries with IoT temperature loggers is enabling real-time custody documentation for high-value pharmaceutical cargo.
Industry Challenges
- Thermal Engineering Talent Scarcity:European universities produce limited graduates specializing in passive thermal system design, forcing manufacturers to recruit from aerospace and building insulation sectors.
- Airline Certification Timeline Compression:IATA CEIV Pharma and individual carrier validation protocols require 12-18 month testing cycles, delaying product launches and freezing development roadmaps.
- Legacy Equipment Integration Complexity:Pharmaceutical distributors operating SAP and Oracle warehouse management systems demand API-compatible temperature data streams, forcing cooler box vendors into costly software development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ice/Cooler Box Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Cooler, Soft Cooler, Electric Cooler, Insulated Container End User: Camping Enthusiasts, Beachgoers, Outdoor Events, Recreational Vehicle Owners Material: Plastic, Metal, Foam, Composite Size: Small, Medium, Large, Extra Large |
| Companies Covered | Azenta Inc., va-Q-tec AG, YETI COOLERS LLC, FEURER GmbH, Softbox Systems Ltd., Polar Bear Coolers, Eurobox Logistics, CSafe Global, Sonoco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ice/Cooler Box Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are actively restructuring competitive differentiation across Europe ice/cooler box manufacturing. Performance claims now center on validated duration metrics rather than marketing assertions.
Vacuum insulation panel technology is bifurcating the European cooler box landscape into premium pharmaceutical-grade systems and commodity recreational products. va-Q-tec AG and specialized German chemical processors dominate VIP core manufacturing, supplying biotech cold-chain distributors with sub-0.005 W/mK thermal conductivity enclosures. This capability concentration is compressing margins for conventional polyurethane foam producers serving recreational segments.
The EU F-Gas Regulation is eliminating hydrofluorocarbon blowing agents from polyurethane foam production by 2030. ECHA enforcement timelines are forcing insulation manufacturers in Belgium, Germany, and Italy to reformulate with hydrocarbon or hydrofluoroolefin alternatives. Hard-sided cooler producers serving event catering and pharmaceutical channels face accelerated R&D cycles to maintain CE marking compliance.
Pharmaceutical procurement departments are consolidating vendor panels around outcome-based performance contracts. Biotech distributors in Frankfurt, Basel, and Amsterdam now specify guaranteed temperature excursions rather than equipment purchase, shifting risk to packaging suppliers. This contractual evolution is most advanced in German-speaking markets where large CMOs operate centralized logistics functions.
Europe Ice/Cooler Box Market Segmentation
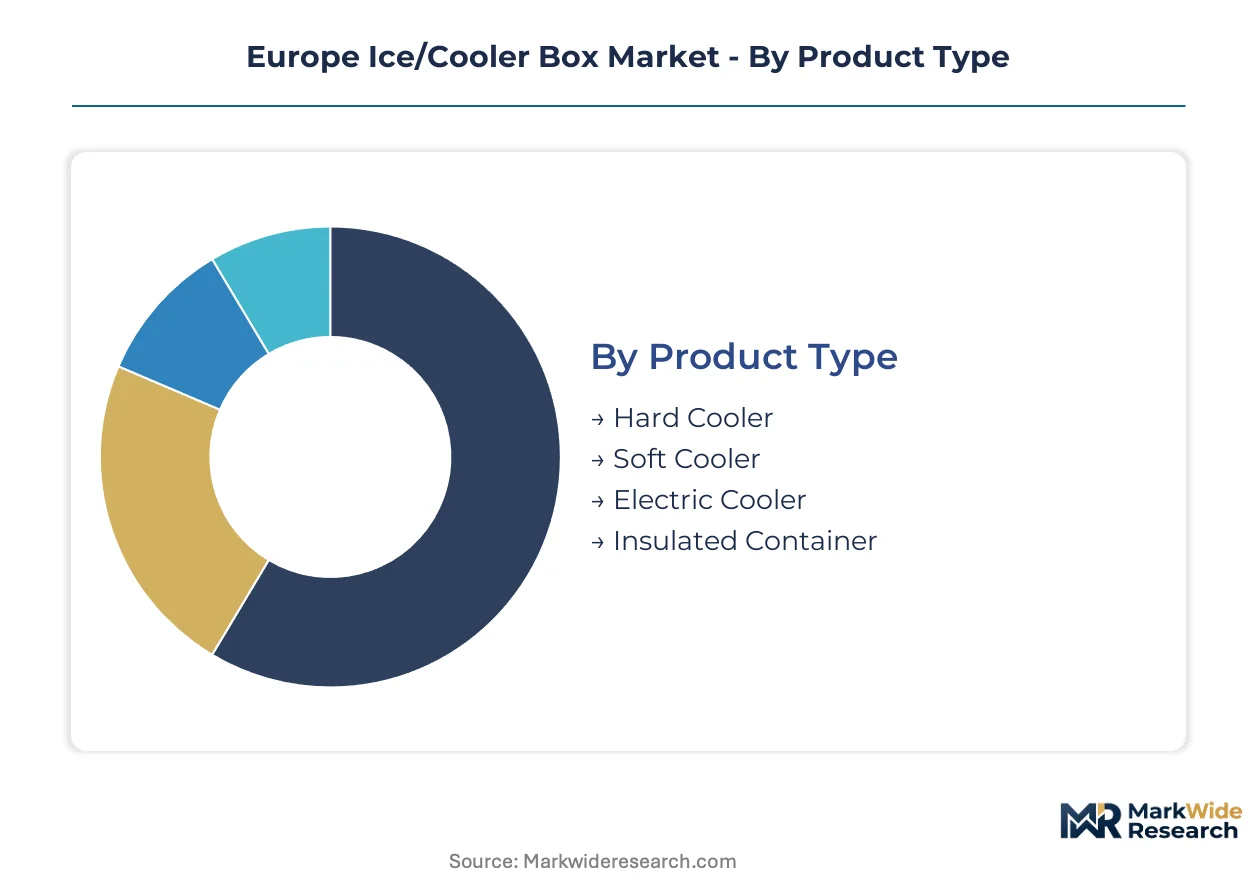
Segmentation in the Europe ice/cooler box market reveals divergent margin structures between recreational and pharmaceutical channels. Product type and material composition determine compliance burden and thermal performance certification requirements.
Product Type:
Premium margin pools concentrate in pharmaceutical-validated systems requiring extended duration guarantees and airline certification.
- Hard Cooler:Rotational-molded polyethylene shells with polyurethane foam cores deliver 48-120 hour thermal stability. Pharmaceutical distributors in Germany and Switzerland specify these for biologics transport under EMA validation protocols. Durability requirements in event catering and cold-chain logistics sustain pricing power despite higher material costs.
- Soft Cooler:Collapsible designs with insulated fabric enclosures target recreational vehicle owners in France and Scandinavia. Post-pandemic vehicle-based tourism has compressed purchase cycles for lightweight, stowable alternatives to rigid systems.
- Electric Cooler:Thermoelectric or compressor-based units depend on auxiliary power infrastructure prevalent in German camper van conversions. Adoption remains constrained outside France and Germany by battery capacity limitations.
- Insulated Container:Modular systems for pharmaceutical depot networks and rental pooling services. Standardized footprints align with EU pallet dimensions for intermodal compatibility.
The dominant share belongs to Hard Cooler, while Soft Cooler is closing the gap fastest.
End User:
Customer archetypes map directly to performance tier requirements and procurement sophistication levels.
- Camping Enthusiasts:Individual purchasers prioritizing weight-to-duration ratios for backcountry use. German and Austrian alpine tourism corridors concentrate demand for sub-5kg portable systems.
- Beachgoers:Day-trip consumers driving seasonal volume spikes in Mediterranean markets. Price sensitivity limits average transaction values despite high unit velocity.
- Outdoor Events:Catering contractors and festival operators requiring certified food-grade sanitation and stackable logistics. Multi-day duration specifications separate premium tenders from commodity procurement.
- Recreational Vehicle Owners:Integrated power systems enable electric cooler adoption. German KBA vehicle certification standards influence aftermarket installation requirements.
Outdoor Events commands the largest contract values, though Recreational Vehicle Owners show the steepest expansion trajectory.
Material:
REACH compliance timelines and F-Gas Regulation phase-downs are restructuring supplier economics across material categories.
- Plastic:Polyethylene and polypropylene dominate rotational molding. ECHA restrictions on isocyanates in polyurethane foam cores are forcing reformulation with hydrocarbon blowing agents.
- Metal:Stainless steel interiors for pharmaceutical-grade sanitization. Swissmedic and EMA hygiene protocols drive specification in Basel and Frankfurt logistics clusters.
- Foam:Vacuum insulation panels with precipitated silica cores achieve sub-0.005 W/mK conductivity. German and Belgian chemical processors control feedstock supply.
- Composite:Hybrid constructions balancing structural rigidity with thermal performance. Emerging in rental pooling systems requiring damage resistance.
Plastic retains volume leadership, yet Foam captures the highest unit margins in pharmaceutical applications.
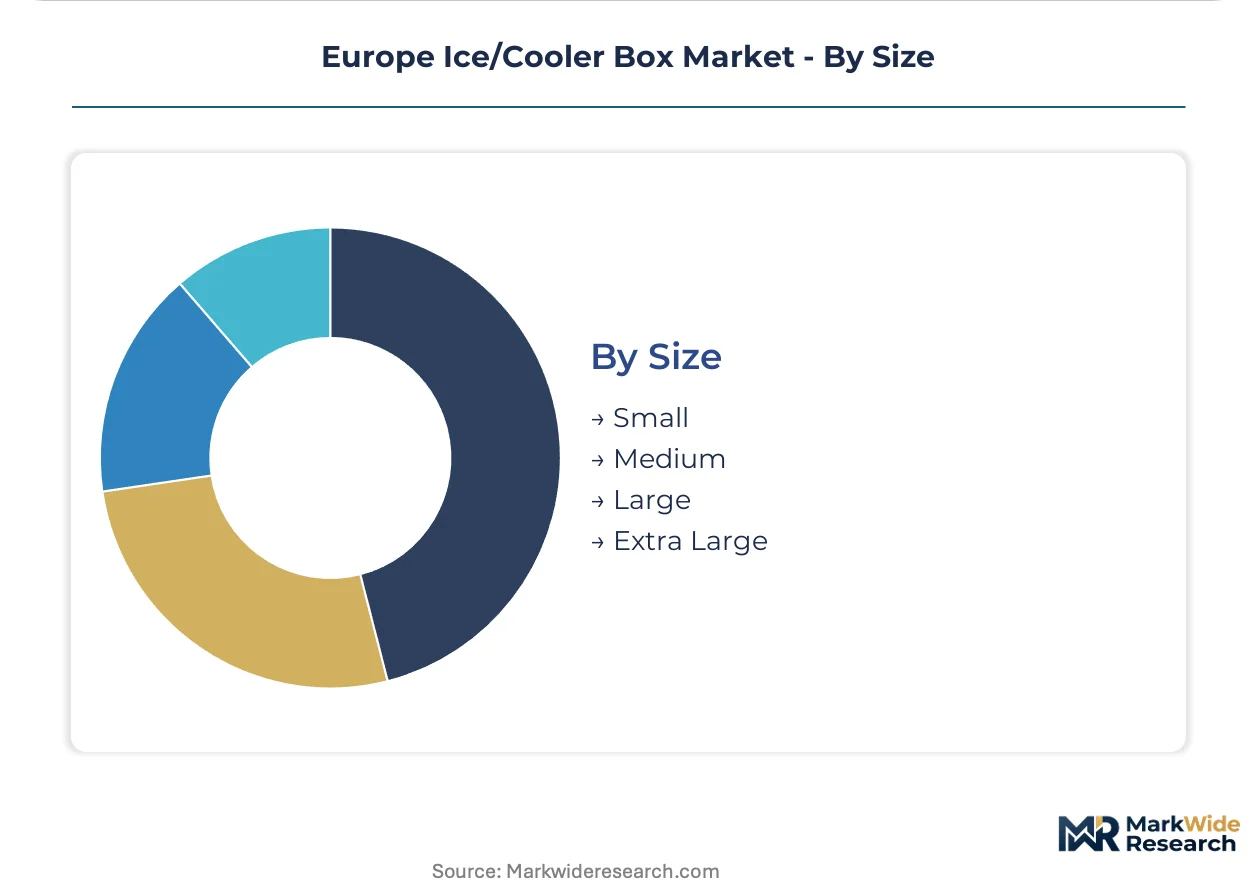
Size:
Dimensional segmentation aligns with payload economics in pharmaceutical distribution and vehicle storage constraints in recreational use.
- Small:Personal medication and vaccine courier formats. Last-mile pharmacy delivery in Dutch and Belgian urban networks.
- Medium:Standard clinical trial kit configurations. CMOs in Frankfurt and Munich specify these for investigator site shipments.
- Large:Pallet-compatible pharmaceutical depot containers. Bulk biologics transport between manufacturing and distribution centers.
- Extra Large:Event catering and commercial fishing operations. Limited pharmaceutical applicability due to handling constraints.
Medium sizes dominate pharmaceutical procurement, while Large formats are gaining share fastest in rental pooling networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational buyers in Mediterranean markets exhibit acute price sensitivity for day-trip formats, while pharmaceutical procurement in German-speaking corridors absorbs substantial premiums for validated thermal performance. This demand-elasticity contrast structures regional margin capture across the continent.
Germany
Pharmaceutical clustering around Frankfurt and Munich sustains premium cooler box procurement for biologics distribution. The KBA vehicle certification framework shapes electric cooler installation standards in camper van conversions. Bavaria's chemical processing belt supplies precipitated silica cores for vacuum insulation panels serving EMA-validated cold chains.
France
Post-pandemic vehicle-based tourism concentrates soft cooler demand along coastal corridors and alpine routes. ANSM pharmaceutical regulations align with EMA standards for temperature-sensitive cargo validation. The Provence-Alpes-Côte d'Azur region hosts seasonal catering procurement for festival and outdoor event logistics.
Switzerland
Swissmedic hygiene protocols drive stainless steel interior specifications for Basel-based biotech logistics. The country's pharmaceutical export intensity generates concentrated demand for airline-certified passive thermal packaging. Zurich and Geneva logistics clusters specialize in clinical trial kit configuration for international shipment.
Netherlands
Last-mile pharmacy delivery networks in Amsterdam and Rotterdam utilize small-format insulated containers for vaccine distribution. Dutch urban logistics density supports rental pooling models for temperature-validated packaging. The Port of Rotterdam serves as a consolidation hub for pharmaceutical depot container traffic.
Italy
Beachgoer demand for collapsible coolers peaks seasonally along Adriatic and Tyrrhenian coasts. REACH compliance timelines pressure polyurethane foam reformulation among northern Italian insulation manufacturers. Lombardy's industrial base supplies rotational-molded shells for event catering and commercial fishing operations.
Europe Ice/Cooler Box Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European cooler box landscape. Vacuum insulation panel specialists command premium positioning in pharmaceutical channels, while rotational-molding houses serve volume recreational segments. The market structures around three strategic archetypes: materials-science innovators, manufacturing-scale operators, and cold-chain validation specialists. Dominant competitive moves include portfolio diversification into adjacent temperature-control formats and strategic partnerships with pharmaceutical logistics providers.
Within the materials-science tier, va-Q-tec AG anchors proprietary vacuum insulation capabilities developed for pharmaceutical applications. YETI COOLERS LLC occupies a position exemplifying rotational-molding expertise and premium recreational positioning. CSafe Global represents the airline-certification archetype, validating passive thermal packaging across EU temperature lanes. These three entities collectively illustrate the technology-cost bifurcation structuring competitive dynamics.
| Leading Market Players |
|---|
| Azenta Inc. |
| va-Q-tec AG |
| YETI COOLERS LLC |
| FEURER GmbH |
| Softbox Systems Ltd. |
| Polar Bear Coolers |
| Eurobox Logistics |
| CSafe Global |
| Sonoco |
| Others |
Pricing and Supply Chain Analysis
Rotational-molding capacity utilization above 85% in German and Italian plants compresses margin buffers for polyethylene shell producers while simultaneously elevating price floors for pharmaceutical-grade hard coolers. This scale concentration enables incumbent molders to defend position against Asian imports through faster EMA validation turnaround, yet leaves limited room for cost absorption when REACH-driven foam reformulation accelerates.
Pricing Analysis
After-sales revenue from refurbishment services and extended validation contracts drives lifetime value for pharmaceutical-grade cooler box vendors. Three-tier pricing structure across premium, standard, and economy levels separates EMA-certified systems with 120-hour guarantees from recreational products with 48-hour claims. Cost compression in the recreational tier is intensifying because Chinese rotational-molded imports capture Mediterranean beachgoer demand. Event catering contractors exhibit acute price sensitivity, while Basel-based biotech distributors absorb substantial premiums for Swissmedic-validated stainless steel interiors.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for precipitated silica feedstock sourced from German and Belgian chemical clusters. Vacuum insulation panel manufacturing draws from specialty silica processors in Bavaria, rotational molding houses in Lombardy, and phase-change material compounders in the Netherlands. Single-source vulnerability concentrates in the precipitated silica supply chain, where three chemical processors control European pharmaceutical-grade core production. Distribution runs through pharmaceutical depot networks in Frankfurt, Basel, and Amsterdam, with rental pooling models expanding into Eastern European logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical procurement departments consolidating vendor panels around outcome-based performance contracts, with German CMOs and Dutch hospital networks driving consolidation among temperature-validated packaging suppliers.
For Market Incumbents: Fortify position through captive supply of vacuum insulation panel cores via backward integration into Bavarian silica processing, while accelerating EMA validation pipeline investments to outpace 12-18 month airline certification timelines that freeze competitor development roadmaps. Threat substitution from active refrigeration backup systems in ultra-long-haul pharmaceutical shipments demands defensive R&D in hybrid passive-active architectures. For New Entrants and Emerging Players: Last-mile pharmacy delivery service gaps in Polish and Hungarian urban networks present white-space targets where incumbent Western European vendors under-serve temperature-validated packaging rental needs. Poland's underpenetrated pharmaceutical cold-chain infrastructure offers the most penetrable geography, with depot network partnerships as the specific go-to-market angle against established German and Swiss competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials-science specialists with proprietary vacuum insulation capabilities over rotational-molding scale operators facing commodity margin compression. Long-term viability across the projection horizon hinges on regulatory chemistry compliance rather than manufacturing scale alone. Acquisition target archetype: German or Swiss vacuum insulation panel specialists with EMA-validated pharmaceutical certifications. The signal to watch is F-Gas Regulation enforcement acceleration forcing polyurethane foam reformulation failures among recreational-focused producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Processing | Captive supply of VIP cores insulates margins from German-Belgian feedstock concentration. |
| EMA Validation Pipeline Expansion | Accelerated certification cycles defend against 12-18 month airline protocol delays freezing rival roadmaps. |
| Depot Network Partnership in Eastern Europe | Polish and Hungarian logistics gaps offer first-mover rental pooling opportunities beyond saturated Western corridors. |
| Hybrid Passive-Active Architecture R&D | Ultra-long-haul pharmaceutical demand exceeds 120-hour passive limits, requiring active refrigeration backup development. |
| Take-Back Program Implementation | EU Green Deal procurement incentives reward circular-economy-certified thermal packaging with mono-material construction. |
Research Methodology
A standing panel of pharmaceutical logistics directors, cold-chain packaging engineers, EMA regulatory consultants, and biotech procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA submission databases, EU F-Gas Regulation enforcement records, REACH compliance filings, and customs trade data for rotational-molded polyethylene imports. Bottom-up demand modeling across pharmaceutical, recreational, and catering channels triangulated against top-down market sizing from insulation material consumption data.
Consistency checks validated volume and value outputs against external benchmarks including IATA CEIV Pharma certification registries and chemical industry capacity utilization reports. Segmentation modeling spanned product type, material composition, end-user archetype, and size tier across the analysis window. CAGRs were derived from regression analysis of historical pharmaceutical cold-chain expenditure patterns and recreational vehicle ownership trends, with explicit incorporation of F-Gas Regulation phase-down timelines and REACH reformulation investment cycles as industry-specific forecast inputs.
Underlying assumptions cover sustained EMA validation requirement tightening and precipitated silica supply stability, with deviation risk concentrated in REACH enforcement acceleration or Eastern European logistics infrastructure buildout delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Soap Dispenser Market
Household Items
Drinkware Accessories Market
Household Items
Smart Shower Market
Household Items
US Hand Dryers Market
Household Items
Russia Residential Water Heaters Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Kitchen Towel Market
Household Items
United Kingdom Air Purifier Market
Household Items
Liquid Hand Soap Market
Household Items
Facial Tissue Market
Household Items
Fine Mist Sprayer Market
Household Items
Memory Foam Market
Household Items
Cutlery Steel Market
Household Items
Robotic Pool Cleaner Market
Household Items
Car Air Freshener Market