
 Netherlands Cookware Market | 2026-2036
Netherlands Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Cookware Market Foresight
Belgian manufacturing expansion near the Dutch border is reshaping regional supply dynamics for enameled cast iron. Le Creuset leverages its foundry heritage to sustain premium positioning across Dutch specialty retail channels. GreenPan anchors the non-stick segment through PFAS-free ceramic technology leadership. Staub competes on French design credentials and heat retention engineering in professional kitchen segments.
Netherlands cookware encompasses food preparation vessels engineered from metals, ceramics, or composites with specified thermal conductivity measured in watts per meter-kelvin and wall thickness calibrated for even heat distribution across domestic and commercial cooking applications. Stainless steel dominates volume across Dutch supermarkets and department stores due to durability and dishwasher compatibility, while cast iron commands margin pools in specialty channels where enameled Dutch ovens from heritage brands fetch significant price premiums. Non-stick coatings face structural pressure as EU REACH restrictions on perfluorinated compounds force reformulation toward ceramic and mineral-based alternatives.
The Netherlands Food and Consumer Product Safety Authority enforces EU Food Contact Materials Regulation compliance for all cookware sold domestically, while the Dutch Medicines Evaluation Board monitors incidental chemical migration claims. The EU Green Deal's Chemicals Strategy for Sustainability tightens substance restrictions, compelling manufacturers to redesign coating chemistries and accelerate third-party certification investments. Stakeholders must monitor evolving PFAS thresholds and prepare supply chain disclosures ahead of anticipated EU-wide bans.
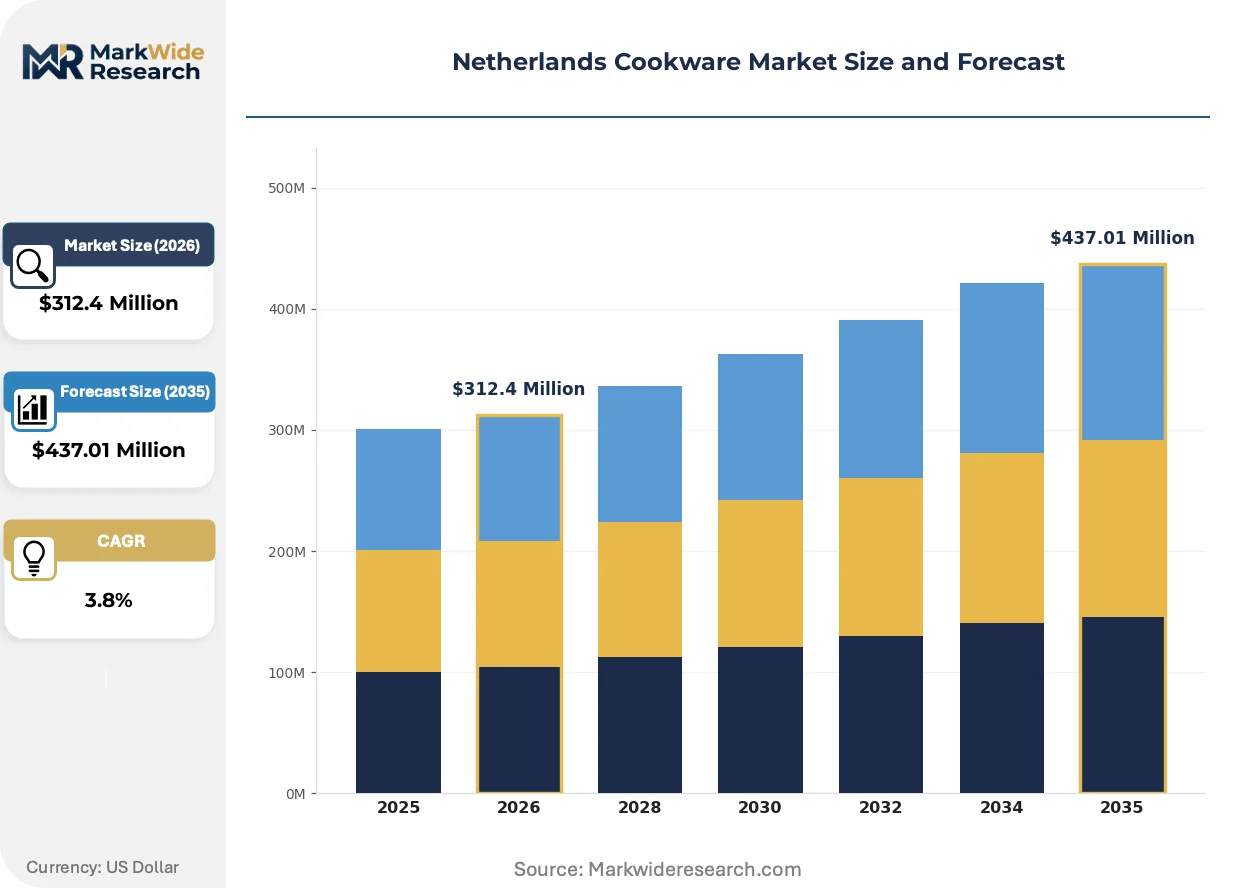
Market Dynamics
EU REACH restrictions on perfluorinated compounds are forcing Dutch manufacturers to reformulate non-stick coating chemistries, compressing margins while accelerating certification investments across the supply chain.
Growth Catalysts
- EU Green Deal Chemicals Strategy:Mandates for PFAS-free alternatives are pulling ceramic and mineral-based coatings into mainstream Dutch retail channels ahead of schedule.
- Amsterdam-Rotterdam premium foodservice corridor:Michelin-starred kitchens sustain demand for copper and enameled cast iron with thermal conductivity specifications above 200 W/m·K.
- Belgian border manufacturing cluster:Proximity to Dutch distribution hubs shortens lead times for enameled Dutch ovens and specialty cookware.
Market Restraints
- Raw material cost volatility:Nickel and chromium price swings squeeze stainless steel margin pools for Dutch supermarket private-label suppliers.
- Coating reformulation R&D burden:Third-party laboratory testing for EU Food Contact Materials Regulation compliance adds six to nine months to product launch timelines.
- Substitution pressure from meal-kit services:Pre-portioned ingredient deliveries reduce frequency of scratch-cooking among younger Dutch households.
Strategic Opportunities
- Utrecht-The Hague stainless steel corridor:Urban household density supports premium set configurations with modular stackability features.
- Induction compatibility retrofit demand:Magnetic base conversion technology opens replacement cycles for legacy aluminum collections in Dutch rental housing.
- CSRD-aligned supply chain disclosure:Early compliance with corporate sustainability reporting requirements differentiates B2B procurement bids for hospitality group contracts.
Industry Challenges
- Coating chemist talent scarcity:PFAS-phaseout timelines outpace Netherlands-based formulation expertise availability.
- Multi-standard certification complexity:Simultaneous EU Food Contact Materials and national Keurmerk requirements fragment quality assurance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Cookware Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skillets, Saucepans, Stock Pots, Dutch Ovens Material: Stainless Steel, Cast Iron, Non-Stick, Copper End User: Households, Restaurants, Catering Services, Hotels Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | Calphalon, Misen, Le Creuset, T-Fal, Caraway, Staub, All-Clad, OXO, GreenPan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Cookware Market Shifts & Advancements
Digital thermal profiling and connected cookware are reshaping how Dutch manufacturers differentiate performance claims, while regulatory chemistry mandates compress legacy coating portfolios.
Smart temperature-sensing cookware is virtualizing traditional heat-distribution marketing claims. Dutch direct-to-consumer brands embed Bluetooth-enabled probes that relay real-time surface temperature data to smartphone applications. Professional kitchens in Rotterdam now specify connected Dutch ovens for recipe-standardization across multi-location operations.
REACH authorization list expansions are accelerating substance-by-substance restrictions on perfluorinated compounds used in legacy non-stick formulations. Dutch importers face expanded documentation requirements for cookware originating outside the European Economic Area. Specialty retailers are pre-emptively delisting SKUs with pending regulatory uncertainty to avoid inventory write-downs.
Subscription-based cookware refresh programs are displacing traditional ownership models among urban Dutch millennials. Direct-to-consumer brands offer annual exchange entitlements for worn ceramic coatings or damaged enamel surfaces. This pattern concentrates in Amsterdam's dense rental housing market where kitchen storage constraints limit permanent collection accumulation.
Netherlands Cookware Market Segmentation
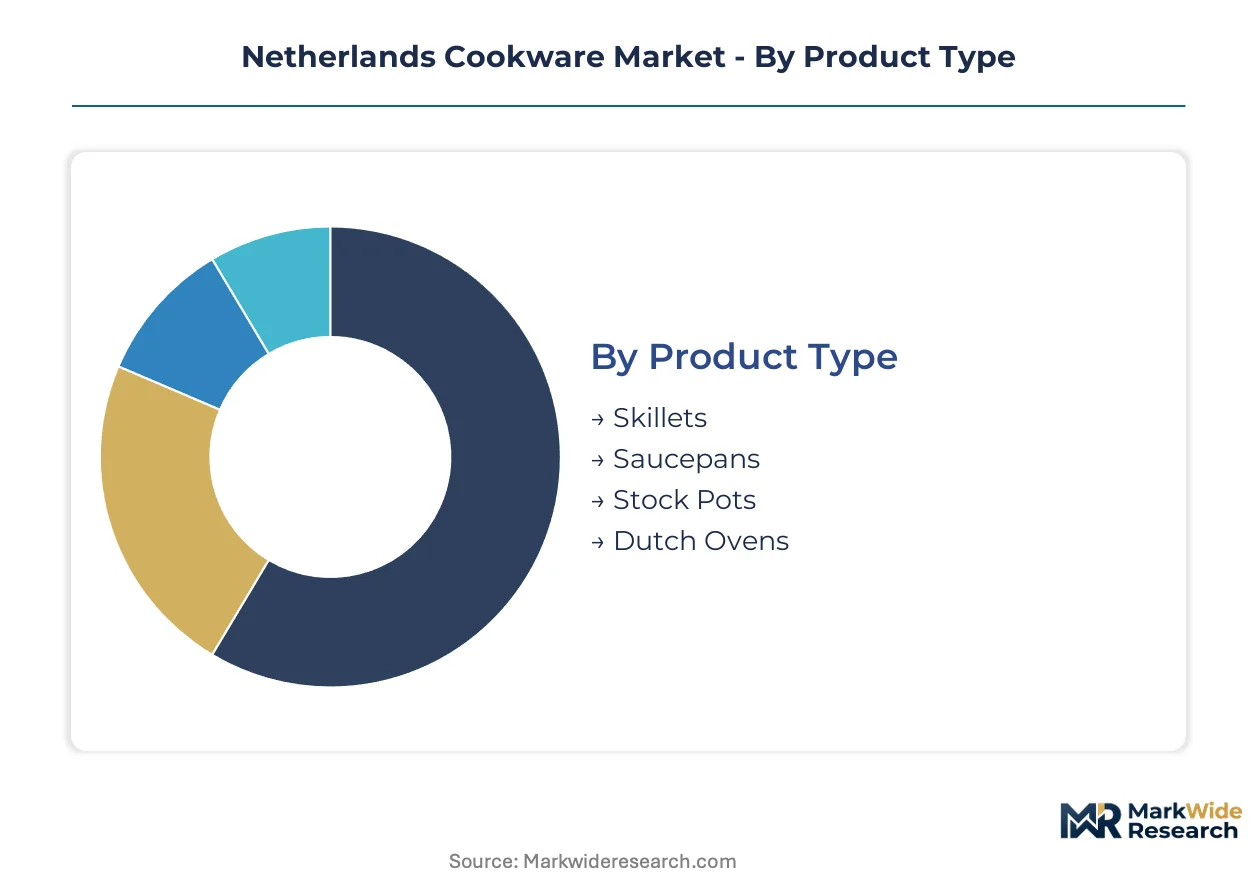
Cookware segmentation in the Netherlands reveals distinct service intensity patterns across product lifecycles. Enameled cast iron and premium stainless steel collections demand extensive warranty support and refurbishment programs, while mass-market non-stick lines prioritize rapid replacement over repair.
Product Type:
After-sales-service intensity varies sharply across vessel categories, with enameled pieces requiring specialized repair networks and standard skillets depending on disposable replacement economics.
- Dutch Ovens:Thick-walled cast iron or enameled vessels with thermal mass exceeding 4 kg retain heat for slow-cooking applications. Amsterdam and Rotterdam restaurant groups specify these for braising workflows, driving premium replacement cycles when enamel surfaces crack.
- Skillets:Shallow, wide-diameter pans with sloped sides engineered for searing and sautéing at temperatures above 200°C. Utrecht households favor induction-compatible stainless steel variants, though ceramic-coated aluminum dominates volume through supermarket channels.
- Saucepans:Medium-depth vessels with long handles and tight-fitting lids for liquid reduction. Dutch rental kitchens standardize on stackable sets with universal lid compatibility to minimize storage footprint.
- Stock Pots:Tall, large-capacity vessels for boiling pasta or preparing broth in volumes exceeding 5 liters. Catering services in The Hague concentrate demand for restaurant-grade stainless steel with encapsulated aluminum bases.
By volume, Skillets leads. By growth pace, Dutch Ovens is ahead.
Material:
Cost tier stratification determines margin architecture, with raw material chemistry and manufacturing complexity separating commodity from specialty positioning.
- Stainless Steel:Iron-chromium-nickel alloys with minimum 10.5% chromium content resist corrosion and maintain structural integrity across dishwasher cycles. Dutch supermarkets anchor volume here, though nickel price volatility compresses margin pools for private-label suppliers.
- Non-Stick:Aluminum substrates coated with ceramic or mineral-based formulations replacing legacy PFAS chemistries under EU REACH pressure. GreenPan anchors this segment through PFAS-free technology leadership in Dutch specialty retail.
- Cast Iron:Carbon-rich ferrous alloys requiring seasoning or enameling to prevent oxidation. Heritage brands command significant price premiums in Netherlands specialty channels where enameled collections fetch multiples over bare iron.
- Copper:Pure or tin-lined vessels with thermal conductivity exceeding 380 W/m·K for precise temperature control. Michelin-starred kitchens in Amsterdam sustain niche demand despite maintenance-intensive polishing requirements.
Stainless Steel dominates unit shipments. Copper captures the steepest expansion trajectory among premium tiers.
End User:
Application context dictates performance specifications, with commercial operators prioritizing durability certifications and domestic buyers emphasizing aesthetic integration.
- Households:Domestic cooking environments where vessel count averages 8-12 pieces per kitchen. Urban centers concentrate demand, with Utrecht and The Hague showing strong preference for modular stainless steel configurations.
- Restaurants:High-throughput foodservice operations requiring NSF or equivalent hygiene certifications. Amsterdam-Rotterdam corridor kitchens sustain copper and cast iron adoption for thermal performance in precise applications.
- Catering Services:Mobile or event-based food preparation demanding lightweight, stackable vessels for transport efficiency. Aluminum and stainless steel dominate this segment due to weight constraints.
- Hotels:Branded hospitality properties standardizing cookware across room service, buffet, and restaurant operations. Procurement concentrates through hospitality group contracts with CSRD-aligned disclosure requirements.
Households generate the largest addressable base. Restaurants drive the fastest specification upgrades.
Distribution Channel:
Customer type and purchase occasion fragment across channel formats, with digital-native buyers prioritizing subscription flexibility and traditional shoppers valuing tactile evaluation.
- Specialty Stores:Curated retail environments with trained staff demonstrating thermal properties and maintenance protocols. Le Creuset and Staub sustain premium positioning here through foundry heritage narratives.
- Online Retail:Direct-to-consumer platforms enabling subscription-based refresh programs. Amsterdam millennials concentrate in this channel, exchanging worn ceramic coatings annually rather than owning permanent collections.
- Supermarkets:High-frequency grocery destinations stocking entry-level stainless steel and aluminum vessels. Private-label suppliers compete on price point with dishwasher compatibility as primary selling feature.
- Department Stores:Mid-tier retail formats bridging mass-market accessibility and brand recognition. Seasonal gift sets drive volume concentration, particularly in Q4 purchasing patterns.
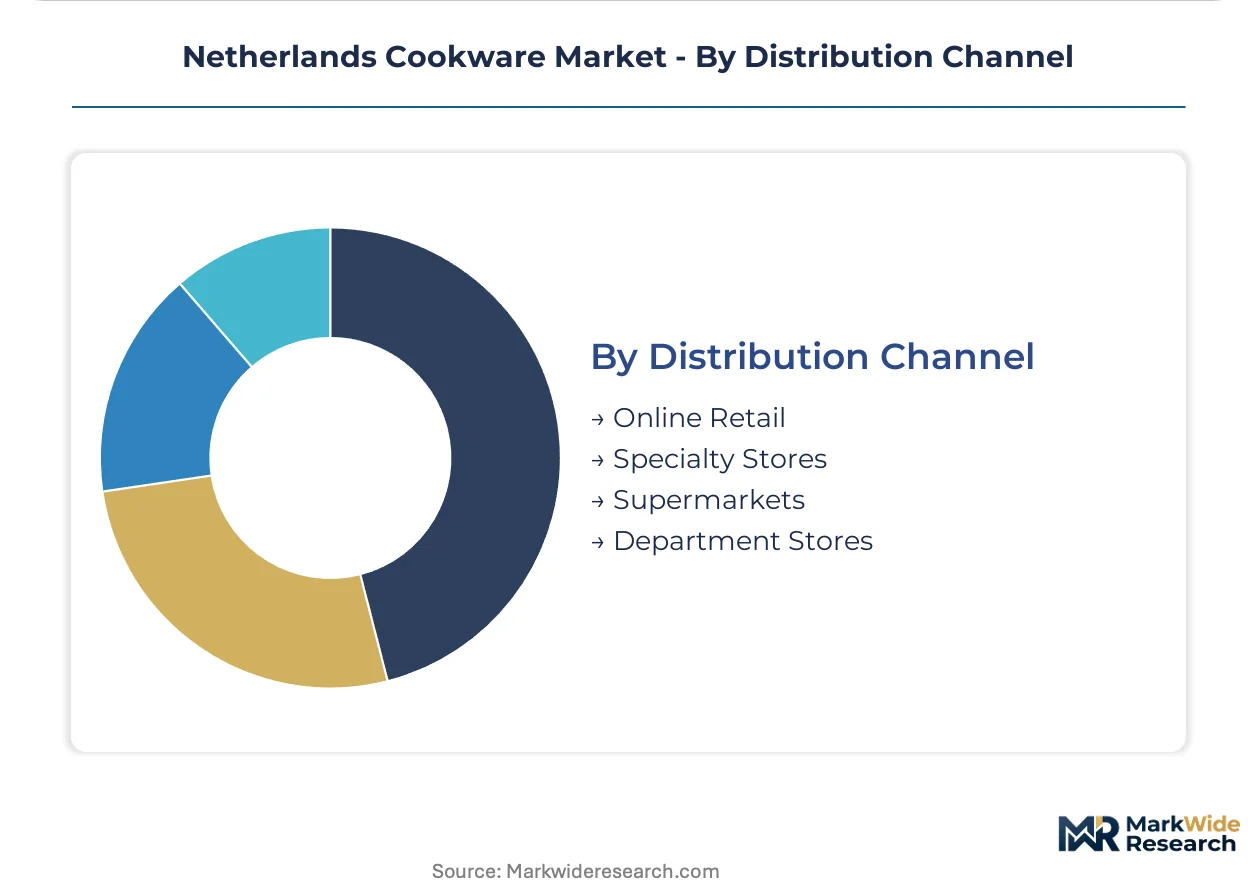
Supermarkets move the highest unit volumes. Online Retail is climbing the fastest as subscription models displace traditional ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian manufacturing capacity near the Dutch border shortens lead times for enameled cast iron vessels bound for Rotterdam distribution hubs. ECHA REACH enforcement tightens chemical migration thresholds across all cookware entering the single market.
Germany
Industrial cookware procurement from hospitality groups in Berlin and Munich sustains demand for NSF-certified stainless steel collections. The country's national consumer protection regulator enforces strict food contact material compliance timelines. Bavaria's precision metalworking clusters supply induction-compatible base technology to Dutch retailers.
France
Heritage foundry brands anchor premium positioning in Dutch specialty channels through enameled Dutch oven collections. ANSM chemical safety mandates accelerate PFAS-free coating transitions across cross-border supply chains. The Lyon-Roanne manufacturing corridor exports enameled cast iron vessels through Antwerp port logistics.
Belgium
Border-adjacent foundry operations capture Dutch wholesale demand for thick-walled cooking vessels. The country's federal public health service coordinates with ECHA on REACH substance restriction implementation. Flanders-based logistics providers manage last-mile distribution to Utrecht and The Hague retail networks.
United Kingdom
Post-Brexit import documentation requirements add friction for cookware entering Dutch ports via Rotterdam. The UK's Office for Product Safety and Standards maintains divergent chemical migration thresholds from EU REACH standards. London-based hospitality procurement groups source copper collections for Amsterdam restaurant satellite locations.
Netherlands Cookware Market Competitive Landscape
Heritage foundry specialists and ceramic-coating technology leaders split the market along premium-performance and health-conscious vectors. The competitive structure concentrates around three strategic archetypes: enameled cast iron heritage houses, PFAS-free ceramic innovators, and stainless steel volume suppliers. Consolidation pressure is mounting through foundry capacity partnerships and coating chemistry licensing arrangements.
Within the heritage foundry tier, Le Creuset and Staub represent archetypal positioning through French manufacturing pedigree and thermal retention engineering. GreenPan anchors the ceramic-coating innovation vector with PFAS-free technology leadership. These three companies exemplify how regulatory chemistry mandates and premium foodservice demand reshape competitive differentiation across Dutch retail and hospitality channels.
| Leading Market Players |
|---|
| Calphalon |
| Misen |
| Le Creuset |
| T-Fal |
| Caraway |
| Staub |
| All-Clad |
| OXO |
| GreenPan |
| Others |
Supply & Pricing Matrix
Antwerp-Rotterdam port logistics corridors govern freight cost dynamics that concentrate supply power among Belgian foundry operators while enabling downstream price differentiation between heritage enameled collections and mass-market stainless steel sets.
Pricing Analysis
EU REACH chemical safety mandates dictate the pricing tier structure across Dutch cookware channels. Three-tier pricing separates heritage enameled cast iron from mid-market ceramic-coated aluminum and entry-level supermarket private-label stainless steel. Price differentiation rests on certification grade for food contact compliance and brand heritage narrative. Margins are tightening in non-stick segments due to coating reformulation R&D burdens. Supermarket private-label buyers exhibit highest price sensitivity; Amsterdam restaurant procurement groups show lowest.
Supply Chain Analysis
Belgian contract foundries and French enameling specialists hold concentrated capacity for premium Dutch oven production. Manufacturing draws from France, Belgium, and Germany for enameled vessels; China and Vietnam for ceramic-coated aluminum substrates. Raw material dependencies include nickel-chromium alloys, cobalt-based enamel pigments, and kaolin ceramic substrates. Single-source vulnerability concentrates in PFAS-free coating chemist expertise. Distribution runs through Rotterdam port consolidation with last-mile specialization via Utrecht and The Hague retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Netherlands cookware is restructuring around service-attach revenue models, with subscription-based coating refresh programs and warranty refurbishment layers expanding faster than hardware unit sales among Amsterdam millennial households.
For Market Incumbents: Pre-empt coating chemist talent scarcity by captive hiring from Dutch technical universities or acquisition of specialized formulation laboratories. Defend margin pools in enameled cast iron through foundry capacity partnerships with Belgian border operators. Vertical integration into ceramic coating R&D offsets regulatory compliance timeline compression from ECHA authorization list expansions. For New Entrants and Emerging Players: Establish a beachhead in induction-compatible retrofit technology for legacy aluminum collections across Dutch rental housing markets. Target Utrecht-The Hague corridor households with modular stackable stainless steel configurations. Direct-to-consumer subscription models bypass specialty retail gatekeeper economics. For Investors and Strategic Acquirers: Carve-out targets emerge from distressed private-label suppliers facing nickel price volatility and REACH compliance cost burdens. Long-term viability favors assets with captive coating formulation capabilities and CSRD-aligned supply chain disclosure infrastructure. Watch PFAS threshold tightening announcements as inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry R&D Partnership | Accelerates PFAS-free ceramic formulation ahead of ECHA restriction timelines. |
| Belgian Foundry Capacity Expansion | Shortens lead times for enameled Dutch ovens bound for Rotterdam distribution. |
| Subscription Refresh Program Launch | Captures Amsterdam millennial demand for flexible cookware ownership models. |
| CSRD Supply Chain Certification | Unlocks hospitality group procurement contracts requiring sustainability disclosure. |
| Induction Base Retrofit Technology | Opens replacement cycles for legacy aluminum in Dutch rental housing stock. |
Research Methodology
A spread of perspectives from cookware brand managers, Dutch supermarket category buyers, Belgian foundry operations directors, and hospitality procurement specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Food Contact Materials Regulation filings, ECHA REACH substance restriction databases, Dutch customs trade records, and hospitality group sustainability disclosure reports. Bottom-up demand modeling triangulated against top-down market sizing across product type, material composition, end-user segment, and distribution channel dimensions.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation modeling captured product type, material chemistry, end-user application, and distribution format variations. CAGRs were derived from fitted growth curves applied to validated baseline estimates. Industry-specific forecast inputs included nickel price volatility indices, ECHA authorization list expansion schedules, and Dutch rental housing kitchen appliance penetration rates.
Stress conditions across raw material cost swings, regulatory timeline acceleration, and subscription model adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about PFAS phaseout pacing and Belgian manufacturing capacity expansion. Quarterly review of ECHA substance restriction announcements and Dutch hospitality procurement contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Portable Iron Market
Household Items
Global Aluminum Cookware Market
Household Items
Soap Dispenser Market
Household Items
Domestic Sauna Heaters Market
Household Items
Replacement Sheets Market
Household Items
Mosquito Trap Market
Household Items
Electric Brooms Market
Household Items
Hangers Market
Household Items
Infuser Water Bottles Market
Household Items
Powered Lawn Mowers Market
Household Items
Electric Hedge Trimmer Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Countertop Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Knife Market