
 Smart Bathroom Products Market | 2026-2036
Smart Bathroom Products Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bathroom Products Market Intelligence
The capital-intensity divergence between sensor-platform specialists and traditional fixture manufacturers is unwinding competitive boundaries across the industry. TOTO leverages its vertical integration in ceramic and electronic component manufacturing to sustain premium positioning in integrated bidet-toilet systems. Kohler anchors North American distribution through designer-showroom networks while competing aggressively in voice-activated shower controls. Moen differentiates through proprietary leak-detection algorithms that extend its IoT faucet portfolio beyond basic touchless operation.
Smart bathroom products encompass digitally connected fixtures and wellness-oriented systems that integrate sensors, microprocessors, and network interfaces to automate hygiene, water delivery, and environmental control functions. These products typically operate on low-voltage DC power with IPX4 minimum ingress protection, communicating via Bluetooth Low Energy or Wi-Fi protocols to central hubs or cloud platforms for usage analytics and predictive maintenance. Smart toilets and sensor-technology platforms lead current revenue generation, while voice-control interfaces represent the fastest-expanding margin pool as hospitality and healthcare end users prioritize hands-free operation. Retrofitting installations dominate residential channels, whereas new construction captures higher-margin integrated systems in commercial and healthcare verticals.
The EPA WaterSense program, Japan's METI energy-efficiency standards for household equipment, and the EU Ecodesign Directive collectively shape product certification requirements and market access thresholds for water-consuming electronics. China's GB standards for smart home interoperability and India's BIS certification for electronic fixtures add compliance layers that favor established manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving cybersecurity mandates for IoT-enabled plumbing devices, as firmware vulnerability disclosures increasingly influence procurement specifications from institutional buyers and insurer risk assessments.
Market Dynamics
Water-efficiency mandates from EPA, METI, and the EU Ecodesign Directive are compressing product development cycles and forcing fixture manufacturers to absorb sensor-platform R&D costs or cede market position to electronics specialists.
Growth Catalysts
- EPA WaterSense certification:Mandatory water-consumption thresholds for commercial buildings in the United States are accelerating replacement of conventional fixtures with sensor-enabled alternatives in hospitality and healthcare facilities.
- Touchless operation protocols:Post-pandemic hygiene standards in Germany and Japan are institutionalizing hands-free interfaces as baseline procurement specifications for institutional buyers.
- Residential renovation clusters:Aging housing stock in the United States and Germany is driving retrofit installations of smart toilets and connected shower systems through contractor and designer channels.
Market Restraints
- Semiconductor supply concentration:MEMS sensor and microcontroller sourcing from concentrated East Asian foundries exposes manufacturers to input volatility and extended lead times.
- Installation skill scarcity:Licensed plumbers with electrical certification for low-voltage DC integration remain scarce in secondary US markets and German rural regions.
- Legacy infrastructure incompatibility:Pre-1990 residential plumbing in Germany and Japan lacks the water pressure stability required for sensor-actuated flush and flow systems without costly pipe replacement.
Strategic Opportunities
- India BIS certification pathway:Emerging middle-class housing construction and government smart-city initiatives are creating first-mover advantage for compliant manufacturers in premium residential segments.
- Ambient wellness convergence:Integration of chromotherapy lighting, aromatherapy diffusion, and acoustic masking into shower enclosures is opening margin expansion in luxury hospitality fit-outs.
- Voice-control standardization:Matter protocol adoption across Amazon Alexa, Google Assistant, and Apple HomeKit is reducing platform fragmentation and enabling unified smart bathroom ecosystem control.
Industry Challenges
- Cybersecurity firmware maintenance:IoT-enabled plumbing devices require continuous vulnerability patching to satisfy institutional procurement specifications and insurer risk assessments.
- Interoperability certification delays:China's GB standards for smart home device communication are evolving faster than testing laboratory capacity, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bathroom Products Market |
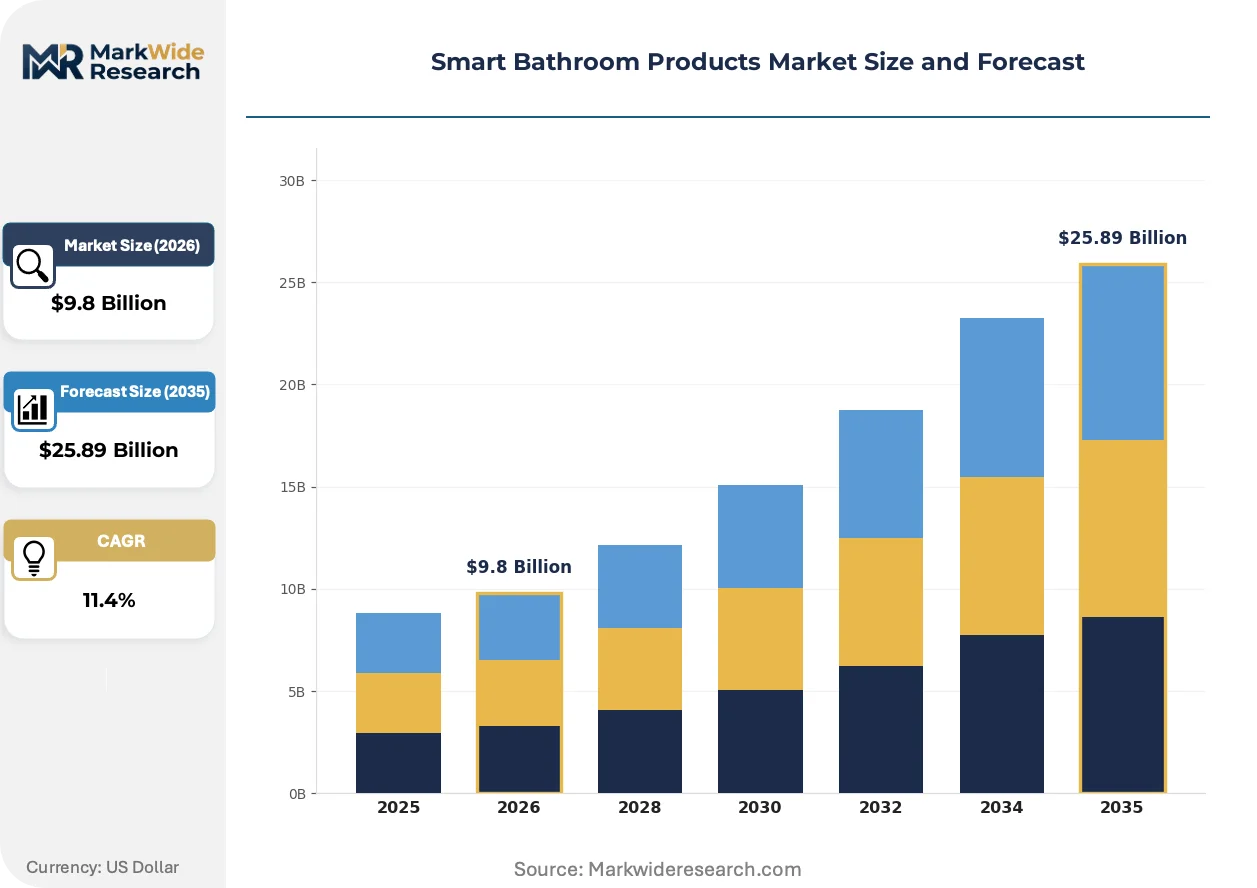
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Toilets, Shower Systems, Faucets, Mirror Displays Technology: IoT, Voice Control, Sensor Technology, Mobile App Integration End User: Residential, Commercial, Hospitality, Healthcare Installation: Standalone Units, Integrated Systems, Retrofitting, New Construction |
| Companies Covered | Grohe, Delta Faucet Company, TOTO, Villeroy & Boch, Woodbridge, Kohler, Moen, Geberit, Duravit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bathroom Products Market Strategic Shifts & Innovations
Sensor fusion and edge computing are migrating processing from cloud platforms to fixture-mounted microcontrollers, reducing latency for real-time water temperature and pressure adjustments while addressing data privacy concerns in institutional deployments.
Capacitive proximity sensing is displacing infrared motion detection in premium faucet and flush valve applications. Hospitality operators in Germany and Japan are specifying capacitive platforms for their immunity to steam interference and reduced false-trigger rates in high-humidity environments. This displacement is compressing the addressable market for legacy infrared module suppliers and accelerating consolidation among sensor-platform vendors.
The EU Ecodesign Directive's expanding scope to networked water-consuming equipment is mandating standby power limits and disassembly requirements for smart toilets and connected showers. Manufacturers are responding by redesigning power management architectures and modularizing electronic subassemblies for end-of-life recycling compliance. Germany's implementation through national transposition laws is setting the enforcement benchmark for other EU member states.
Specification authority is migrating from mechanical contractors to facilities technology managers in US healthcare and hospitality procurement. These buyers prioritize predictive maintenance dashboards and usage analytics over fixture brand heritage, forcing traditional manufacturers to unbundle hardware from software service contracts. This shift is most visible in hospital system RFPs in California and Texas, where total-cost-of-ownership models now dominate capital allocation decisions.
Smart Bathroom Products Market Segmentation
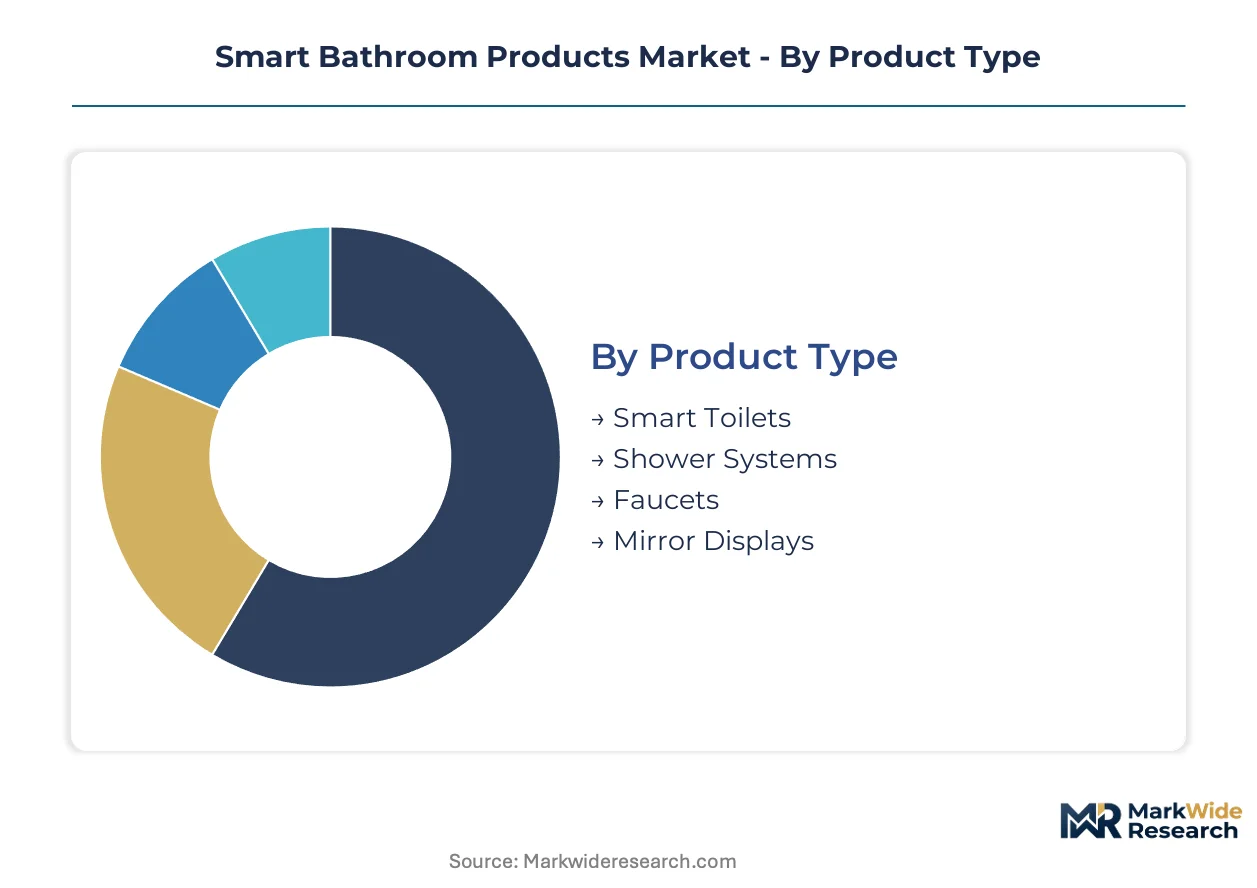
Segmentation in smart bathroom products reveals where substitution pressure concentrates and how technology migration reshapes procurement authority. Manufacturers must align R&D investment with the segments where sensor platforms displace conventional fixtures fastest.
Product Type:
Substitution pressure runs strongest against conventional ceramic fixtures without electronic augmentation, as water-efficiency mandates and hygiene protocols accelerate displacement.
- Smart Toilets:Integrated bidet-toilet systems combine ceramic bowls with heated seats, automated flushing, and self-cleaning nozzles operating on low-voltage DC power. Demand concentrates in Japan and Germany where aging demographics and institutional hygiene standards drive replacement of conventional toilets in healthcare facilities and premium residential renovations.
- Shower Systems:Digitally controlled water delivery platforms integrate thermostatic mixing, chromotherapy lighting, and voice-activated flow adjustment through IPX4-rated enclosures. Hospitality operators in the United States specify these systems for guest experience differentiation in luxury hotel fit-outs.
- Faucets:Sensor-actuated and voice-controlled water delivery fixtures with MEMS flow sensors and leak-detection algorithms.
- Mirror Displays:LED-illuminated surfaces with embedded touchscreens, defogging systems, and Bluetooth connectivity for media streaming.
Smart toilets anchor the volume base while shower systems gain share at the steepest rate.
Technology:
Cost tier stratification separates premium integrated platforms from entry-level point solutions, with voice control commanding the widest margin spread.
- IoT:Network-connected fixtures communicating via Wi-Fi or Bluetooth Low Energy to central hubs for usage analytics and predictive maintenance scheduling. Commercial buyers in the United States prioritize IoT-enabled platforms for facilities management integration.
- Voice Control:Hands-free operation interfaces compatible with Amazon Alexa, Google Assistant, and Apple HomeKit through Matter protocol standardization. Healthcare procurement in Germany mandates voice control for infection prevention in surgical preparation areas.
- Sensor Technology:Capacitive proximity and infrared motion detection systems for touchless actuation of flush, flow, and lighting functions.
- Mobile App Integration:Smartphone-based configuration and monitoring interfaces for water temperature presets and usage tracking.
Sensor technology anchors the volume base while voice control gains share at the steepest rate.
End User:
Application-specific certification requirements create divergent compliance burdens, with healthcare and hospitality facing the most stringent procurement specifications.
- Residential:Retrofit-focused installations in aging housing stock across the United States and Germany, driven by renovation contractor channels and designer-showroom influence. EPA WaterSense certification shapes product selection for water-conscious homeowners.
- Commercial:Office building and institutional deployments prioritizing total-cost-of-ownership models and predictive maintenance dashboards over upfront hardware costs.
- Hospitality:Premium hotel chain installations emphasizing guest experience differentiation through ambient wellness features and seamless technology integration.
- Healthcare:Hospital and clinic deployments with strict infection control protocols mandating hands-free operation and antimicrobial surface specifications.
Residential anchors the volume base while healthcare gains share at the steepest rate.
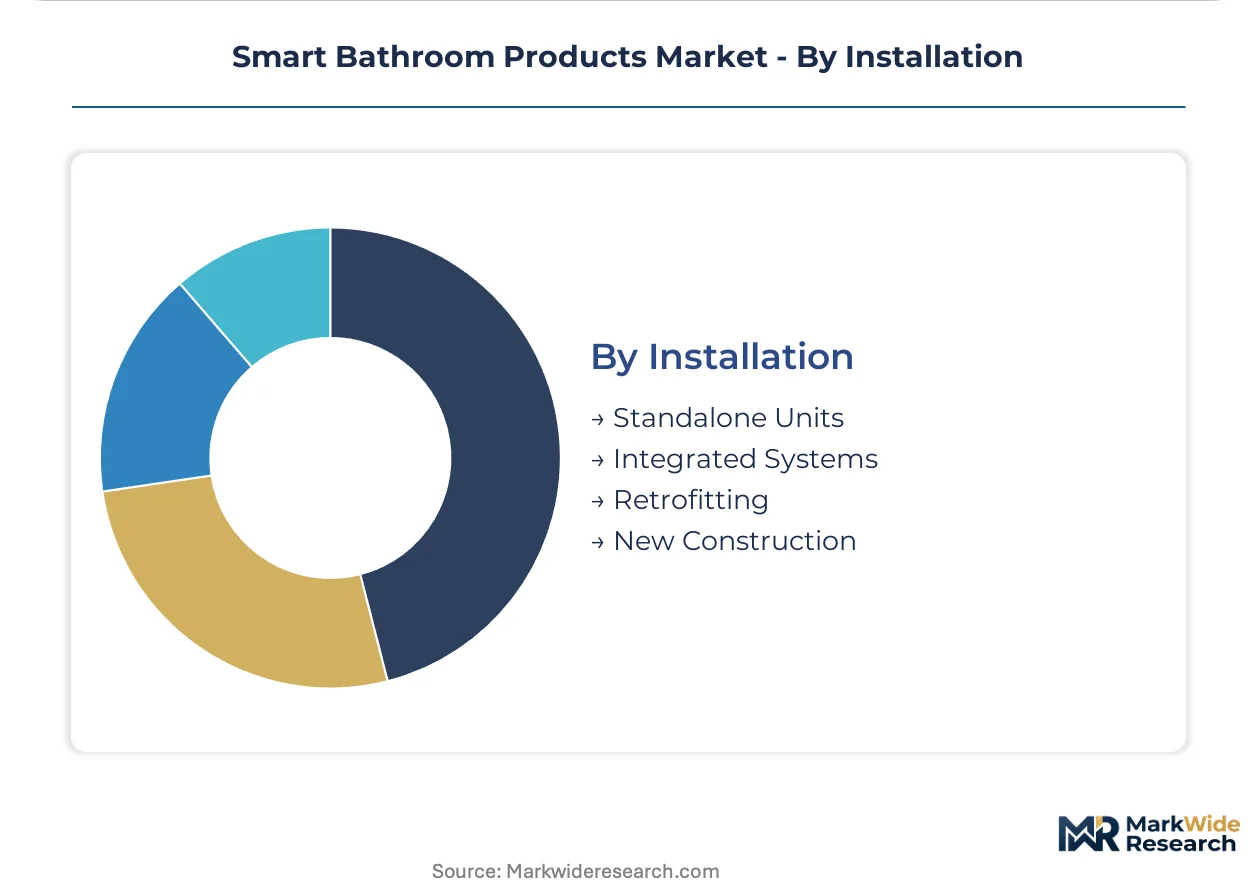
Installation:
Maturity gradients separate established retrofit channels from emerging integrated system specifications in new construction verticals.
- Standalone Units:Self-contained fixtures requiring minimal plumbing modification, dominating residential replacement cycles and contractor-driven renovations in the United States.
- Integrated Systems:Whole-bathroom technology platforms with unified control architecture, specified in new commercial and healthcare construction for seamless ecosystem operation.
- Retrofitting:Adaptation of existing plumbing infrastructure to accommodate sensor platforms and electronic controls, constrained by pre-1990 pipe compatibility in Germany and Japan.
- New Construction:Built-in smart bathroom specifications with dedicated electrical rough-in and network infrastructure, capturing higher margins in commercial and hospitality verticals.
Retrofitting anchors the volume base while integrated systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese consumers deploy integrated bidet-toilet systems at household penetration rates unmatched elsewhere, while German buyers prioritize water-efficiency certification and US hospitality operators drive voice-control specifications for guest experience differentiation.
United States
EPA WaterSense mandates in commercial buildings accelerate sensor-enabled fixture replacement across hospitality and healthcare facilities. The Inflation Reduction Act's efficiency incentives shape residential renovation decisions in aging housing stock. California and Texas hospital systems now specify predictive maintenance dashboards over brand heritage in capital allocation.
Germany
EU Ecodesign Directive transposition through national laws enforces standby power limits and modular disassembly requirements for networked water-consuming equipment. Villeroy & Boch and Duravit anchor ceramic-electronics integration in the Saarland and Rhineland industrial clusters. Facilities technology managers in Berlin and Munich procurement offices prioritize total-cost-of-ownership analytics.
Japan
METI energy-efficiency standards for household equipment institutionalize heated-seat and automated-flush specifications as baseline expectations. TOTO's vertical control over ceramic and electronic component manufacturing sustains premium positioning in integrated systems. Tokyo and Osaka healthcare facilities mandate hands-free interfaces for infection prevention in surgical preparation areas.
China
GB standards for smart home interoperability create compliance layers favoring manufacturers with dedicated regulatory affairs capacity. Dual carbon goals accelerate water-efficiency technology adoption in premium residential construction. Shenzhen and Shanghai smart-city initiatives drive integrated system specifications in new commercial developments.
India
BIS certification for electronic fixtures creates first-mover advantage for compliant manufacturers in premium residential segments. Government smart-city initiatives in Mumbai and Delhi-NCR expand addressable market for sensor-actuated public infrastructure. Emerging middle-class housing construction concentrates demand in Maharashtra and Gujarat contractor channels.
Smart Bathroom Products Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with ceramic-electronics convergence blurring historical boundaries between fixture manufacturers and sensor-platform vendors. Three archetypes dominate: vertically integrated hygiene-system specialists, North American distribution-anchored brands competing through designer-showroom networks, and European precision-engineering houses with regulatory compliance depth. Competitive moves concentrate on strategic partnerships for IoT platform integration and geographic expansion through certification-first market entry.
Among German precision-engineering houses, Grohe and Geberit exemplify the regulatory-compliance archetype, anchoring EU market access through Ecodesign Directive expertise. TOTO represents the vertically integrated specialist model with captive ceramic and electronics production. Kohler and Moen occupy positions within the North American distribution-anchored tier, competing through specification authority in hospitality and healthcare procurement channels.
| Leading Market Players |
|---|
| Grohe |
| Delta Faucet Company |
| TOTO |
| Villeroy & Boch |
| Woodbridge |
| Kohler |
| Moen |
| Geberit |
| Duravit |
| Others |
Cost & Logistics Intelligence
EPA WaterSense certification gates both supplier qualification and price differentiation simultaneously, as manufacturers must absorb sensor-platform R&D costs to access commercial building mandates while tiering offerings across premium integrated systems and basic sensor-actuated alternatives. This regulatory threshold compresses margins for non-compliant producers while rewarding incumbents with dedicated regulatory affairs capacity.
Pricing Analysis
Long-term offtake agreements dominate hospitality and healthcare procurement, with institutional buyers locking in multi-year service contracts bundling hardware, predictive maintenance dashboards, and firmware updates. Three-tier pricing structure across premium integrated systems, standard IoT-enabled fixtures, and economy sensor-actuated units separates TOTO and Kohler at the top from mass-market alternatives. Cost compression in the standard tier is intensifying because MEMS sensor sourcing volatility forces manufacturers to internalize component price swings. Residential renovation contractors exhibit highest price sensitivity, while luxury hotel chains prioritize total-cost-of-ownership models over upfront hardware expenditure.
Supply Chain Analysis
China and Taiwan anchor MEMS sensor and microcontroller fabrication for smart bathroom electronics, while Germany and Japan concentrate precision ceramic manufacturing and thermostatic valve engineering. Raw material dependencies span rare-earth elements for capacitive proximity sensors, semiconductor-grade silicon for edge-computing microcontrollers, and specialized ceramics for heated-seat substrates. Single-source vulnerability runs through concentrated East Asian foundry capacity for low-power Bluetooth modules. Distribution runs through designer-showroom networks in North America, plumbing merchant channels in Germany, and direct-to-contractor specification in Japan's renovation market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in smart bathroom products rest on regulatory entrenchment, as certification requirements for EPA WaterSense, EU Ecodesign, and BIS compliance create switching costs that institutionalize incumbent relationships with facilities technology managers.
For Market Incumbents: Secure firmware maintenance capabilities as a recurring revenue anchor, as cybersecurity vulnerability patching becomes a procurement specification in hospital system RFPs. Deepen backward integration into MEMS sensor design to insulate margin structures from East Asian foundry volatility. Channel control through exclusive designer-showroom networks in California and Texas defends against emerging IoT-platform specialists seeking direct specification authority. For New Entrants and Emerging Players: Lead with BIS certification-first market entry in Maharashtra and Gujarat contractor channels, where government smart-city initiatives expand addressable market for compliant electronic fixtures. Voice-control integration for surgical preparation areas in Indian healthcare facilities represents the most penetrable application, as infection prevention protocols institutionalize hands-free operation mandates. Partner with established plumbing merchants for downstream distribution rather than building specification authority from zero. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European precision-engineering houses possessing Ecodesign Directive expertise but lacking IoT platform integration. Five-to-ten year viability hinges on software service contract attach rates overtaking hardware margin dependence. The signal to watch is Matter protocol adoption velocity across Amazon Alexa and Google Assistant ecosystems, as unified smart bathroom control standardization determines which sensor-platform vendors capture specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Reduces platform fragmentation across Amazon Alexa, Google Assistant, and Apple HomeKit ecosystems. |
| Sensor-Platform Acquisition | Accelerates capacitive proximity capabilities for hospitality steam-immunity specifications. |
| Predictive Maintenance Dashboard Launch | Captures facilities technology manager specification authority in California hospital systems. |
| India BIS Certification Investment | Unlocks first-mover positioning in Maharashtra smart-city infrastructure deployments. |
| Backward Integration into MEMS Design | Insulates margin structures from Taiwan foundry lead-time volatility. |
Research Approach
Initial hypotheses were tested against primary input from facilities technology managers, plumbing contractor specification leads, hospitality procurement officers, and sensor-platform R&D directors, and refined through secondary validation across EPA WaterSense certification databases, EU Ecodesign Directive implementation documents, METI energy-efficiency filings, and hospital system RFP archives. Bottom-up unit economics triangulated against top-down market sizing across product type, technology tier, end-user vertical, and installation mode segmentation dimensions.
Variance-decomposition across the projection horizon isolates volume drivers from price-mix effects, with CAGRs derived from replacement cycle modeling in aging US and German housing stock and new construction penetration in China smart-city developments. Segmentation dimensions span product type substitution pressure, voice-control adoption velocity, healthcare infection-control mandate expansion, and integrated versus standalone installation economics.
The analysis sits within stated boundaries; outcomes outside sustained EPA WaterSense mandate enforcement, MEMS sensor supply normalization, or Matter protocol adoption velocity would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and semiconductor input cost trajectories. Recalibration cycles align with material shifts in EPA commercial building thresholds, EU networked equipment standby power limits, and cybersecurity firmware disclosure patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Flushable Wipes Market
Household Items
Thermos Drinkware Market
Household Items
Canada Digital Showers Market
Household Items
Acrylic Aquarium Market
Household Items
Nebulizing Diffuser Market
Household Items
Desktop Air Purifier Market
Household Items
Pet Safe Cleaners Market
Household Items
Remote Control Holder Market
Household Items
Towel Warmers Market
Household Items
Mosquito Lamps Market
Household Items
Car Air Freshener Market
Household Items
Crash Mat Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Bristle Brush Market
Household Items
US Soap Dispenser Market
Household Items
US Coin-Operated Commercial Laundry Market