
 Electric Vehicle Operations Management Solutions Market | 2026-2036
Electric Vehicle Operations Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Operations Management Solutions Market Foresight
The premium fleet analytics tier is rebalancing away from basic telematics as large-scale operators demand predictive energy forecasting and real-time charge state orchestration. Geotab leverages its open-platform architecture to anchor enterprise accounts with deep API extensibility. Samsara competes through integrated video and vehicle data streams that sustain high switching costs among logistics customers. Motive specializes in AI-driven safety scoring alongside energy metrics, differentiating its value proposition for mixed ICE-EV fleets transitioning to full electrification.
Electric Vehicle Operations Management Solutions encompass software platforms that coordinate fleet telematics, charging infrastructure scheduling, route optimization algorithms, and energy consumption analytics through cloud-native or edge-deployed architectures, typically processing vehicle CAN bus data at sub-minute intervals to minimize total cost of ownership per mile. Fleet Management solutions dominate current revenue as incumbent providers bundle telematics with emerging charge point controls, while Cloud-Based deployment is displacing on-premise installations as operators prioritize scalability across dispersed vehicle footprints and dynamic electricity pricing environments.
The US EPA tailpipe standards and NHTSA CAFE regulations mandate fleet emission reductions that directly expand addressable demand for EV operations platforms capable of documenting compliance across vehicle classes. China's MIIT dual carbon goals and GB standards for connected vehicle data security impose localization requirements that shape product architecture and market access for foreign solution providers. Stakeholders must monitor how fragmented utility rate structures and interconnection queue delays reshape the ROI calculus for charging infrastructure modules within integrated platform offerings.
Market Dynamics
Fleet electrification mandates are compressing deployment timelines for integrated charging-orchestration platforms as operators confront stranded-asset risk in legacy ICE infrastructure.
Growth Catalysts
- EU Green Deal ICE Phase-Out:Germany, France, and the Netherlands have enacted binding end dates for internal combustion engine sales, forcing logistics operators to procure EV operations platforms for compliance documentation and route recalibration.
- Last-Mile Logistics Electrification:E-commerce fulfillment networks are deploying dense EV fleets that require sub-minute CAN bus telemetry to optimize battery utilization across variable urban duty cycles.
- Dynamic Electricity Pricing:Cloud-native charge scheduling algorithms are capturing arbitrage value from time-of-use utility rates, improving total cost of ownership calculations for fleet finance teams.
Market Restraints
- Interconnection Queue Delays:Utility grid upgrade timelines in dense metropolitan areas are extending charging infrastructure commissioning by 18-36 months, degrading platform ROI projections.
- Semiconductor Supply Concentration:Vehicle telematics hardware remains exposed to foundry capacity constraints in East Asian manufacturing clusters, creating procurement volatility for module integrators.
- Data Localization Mandates:China's GB standards for connected vehicle data security impose architecture fragmentation costs on foreign platform providers seeking market access.
Strategic Opportunities
- Mixed-Fleet Transition Services:Operators running concurrent ICE and EV assets present demand for unified platforms that consolidate safety scoring, fuel tracking, and energy analytics within single dashboards.
- Predictive Energy Forecasting:Machine learning models trained on historical route and weather data are opening premium pricing tiers as large-scale operators prioritize battery state-of-health optimization over basic telematics.
- India PLI Scheme Alignment:Domestic manufacturing incentives for electric commercial vehicles are accelerating fleet electrification timelines, creating first-mover advantages for localized platform deployments.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortages of firmware engineers with automotive CAN protocol expertise are constraining development velocity for edge-computing telemetry modules.
- Legacy Fleet Management Integration:On-premise telematics installations at established operators require costly middleware development to synchronize with cloud-native charging orchestration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Operations Management Solutions Market |
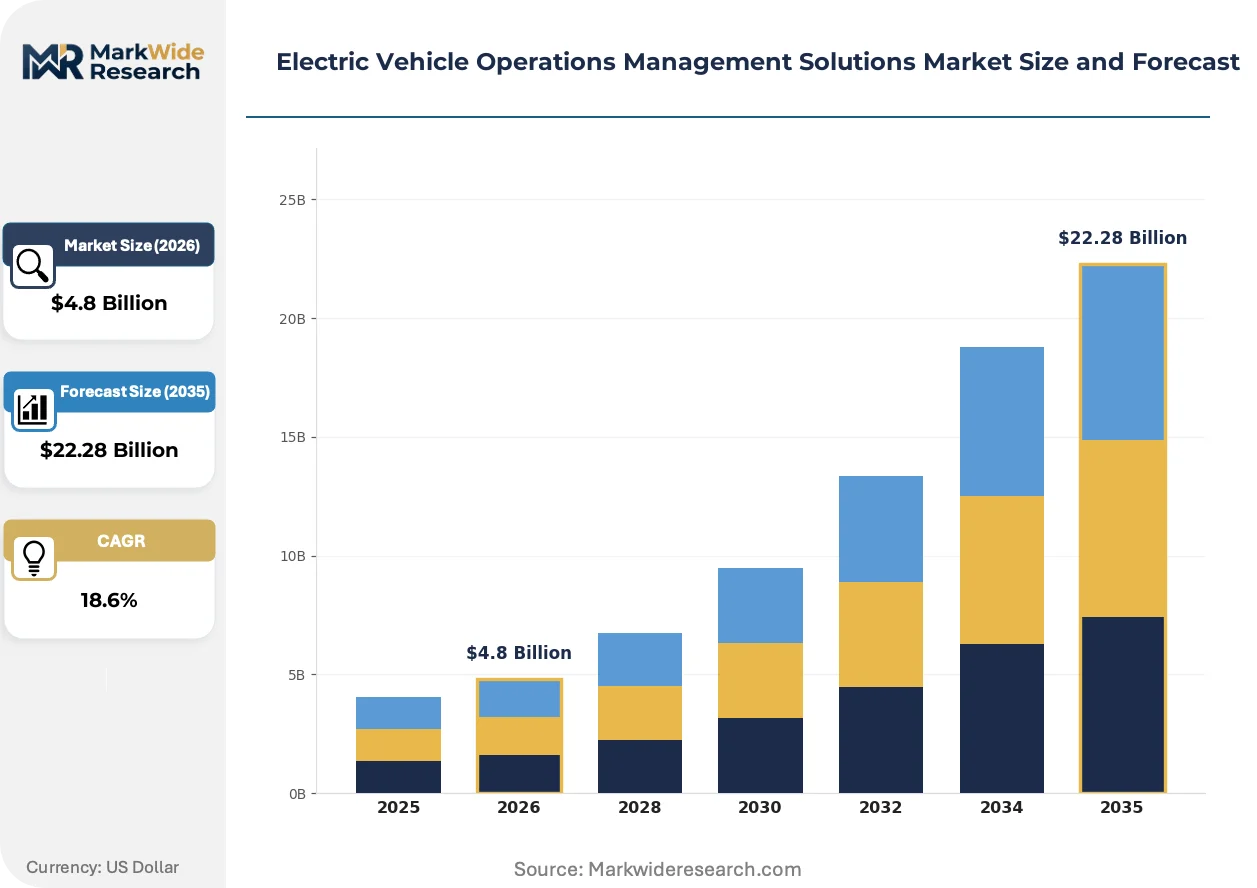
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Fleet Management, Charging Infrastructure, Route Optimization, Energy Management Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Logistics Companies, Government Agencies, Ride-Sharing Services, Corporations Integration Level: API Integration, Third-Party Interfaces, IoT Connectivity, Data Analytics |
| Companies Covered | Geotab, Samsara, Verizon Connect, ChargePoint, Element Fleet Management, Teletrac Navman, Motive, Trimble, Fleet Complete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Operations Management Solutions Market Shifts & Advancements
Edge-deployed inference engines are compressing decision latency for charge-state optimization, while regulatory data-reporting obligations are expanding platform functionality beyond traditional fleet visibility.
Digital twin architectures are rewriting how fleet operators simulate energy consumption across hypothetical route configurations. Large-scale logistics providers in China are deploying these models to pre-validate charging stop placement before physical infrastructure commitment. The technology is compressing capital deployment risk for electrification programs by enabling scenario testing without hardware installation.
The US EPA tailpipe standards and NHTSA CAFE regulations are mandating documented emission reductions across vehicle classes. Fleet operators must now maintain auditable records of energy sourcing and vehicle utilization to demonstrate compliance during regulatory inspections. Heavy-duty logistics segments are responding by prioritizing platforms with embedded carbon accounting modules and automated reporting pipelines.
Subscription-based platform access is displacing perpetual license arrangements as fleet operators prioritize scalability across dispersed vehicle footprints. Third-party logistics providers and regional delivery cooperatives are adopting usage-tiered pricing models that align software costs with seasonal fleet utilization. This shift is most visible in North American and European markets where operator balance sheets favor operational expenditure classification over capital-intensive on-premise deployments.
Electric Vehicle Operations Management Solutions Market Segmentation
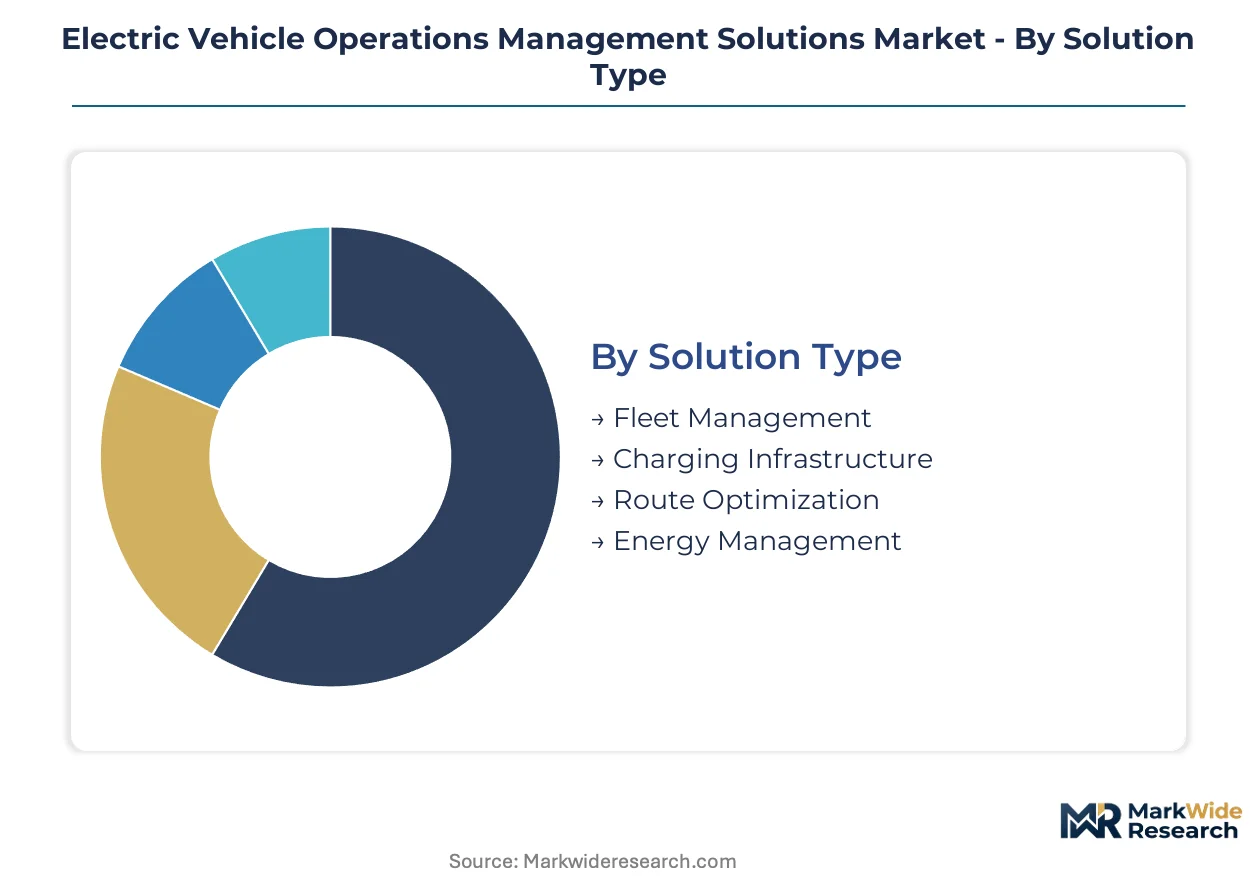
Fleet operators require modular platforms that align software capabilities with electrification maturity and infrastructure constraints. Segmentation reveals how solution architecture, deployment topology, and integration depth determine platform selection across operator types.
Solution Type:
Functional modules diverge sharply between operators managing mixed fleets versus those running full-electric deployments.
- Fleet Management:Incumbent providers bundle telematics with emerging charge point controls, processing vehicle CAN bus data at sub-minute intervals to minimize total cost of ownership per mile. Logistics companies in last-mile delivery networks anchor procurement here, driven by EU Green Deal compliance mandates for emission documentation.
- Charging Infrastructure:Scheduling algorithms coordinate depot and public charge point access, capturing arbitrage value from time-of-use utility rates. Demand concentrates in China, where state-backed electrification targets and domestic OEM scale create the world's largest deployment base for integrated charging-orchestration systems.
- Route Optimization:Algorithms recalibrate delivery sequences based on real-time battery state-of-charge and traffic conditions.
- Energy Management:Predictive forecasting modules optimize battery utilization across variable urban duty cycles.
Mature deployment sits with Fleet Management. Newer deployment is concentrated in Charging Infrastructure.
Deployment Model:
Capital structure and data sovereignty requirements shape whether operators prioritize cloud elasticity or local control.
- Cloud-Based:Scalable architectures process telemetry across dispersed vehicle footprints and dynamic electricity pricing environments. Subscription-based access aligns software costs with seasonal fleet utilization, displacing perpetual license arrangements among North American third-party logistics providers.
- Edge Computing:Deployed inference engines compress decision latency for charge-state optimization in bandwidth-constrained environments. Germany's KBA-connected vehicle regulations and China's GB standards for data security accelerate adoption where localization mandates fragment architecture requirements.
- On-Premise:Legacy installations at established operators require costly middleware to synchronize with cloud-native charging layers.
- Hybrid:Split architectures balance sensitive data retention with elastic compute scaling.
Cloud-Based deployment dominates new procurement. Edge Computing is climbing the fastest among operators confronting data localization mandates.
End User:
Procurement authority and electrification timelines vary substantially across organizational types.
- Logistics Companies:E-commerce fulfillment networks deploy dense EV fleets requiring sub-minute telemetry. US EPA tailpipe standards and NHTSA CAFE regulations mandate documented emission reductions, expanding addressable demand for platforms with embedded carbon accounting modules.
- Government Agencies:Public sector procurement follows ICE phase-out mandates in Germany, France, and the Netherlands, forcing compliance-driven platform adoption with auditable energy sourcing records.
- Ride-Sharing Services:High-utilization vehicle fleets prioritize battery state-of-health optimization over basic telematics.
- Corporations:Mixed-fleet transition services consolidate safety scoring and energy analytics within single dashboards.
Logistics Companies anchor current revenue. Government Agencies are expanding most quickly as binding ICE end dates compress deployment timelines.
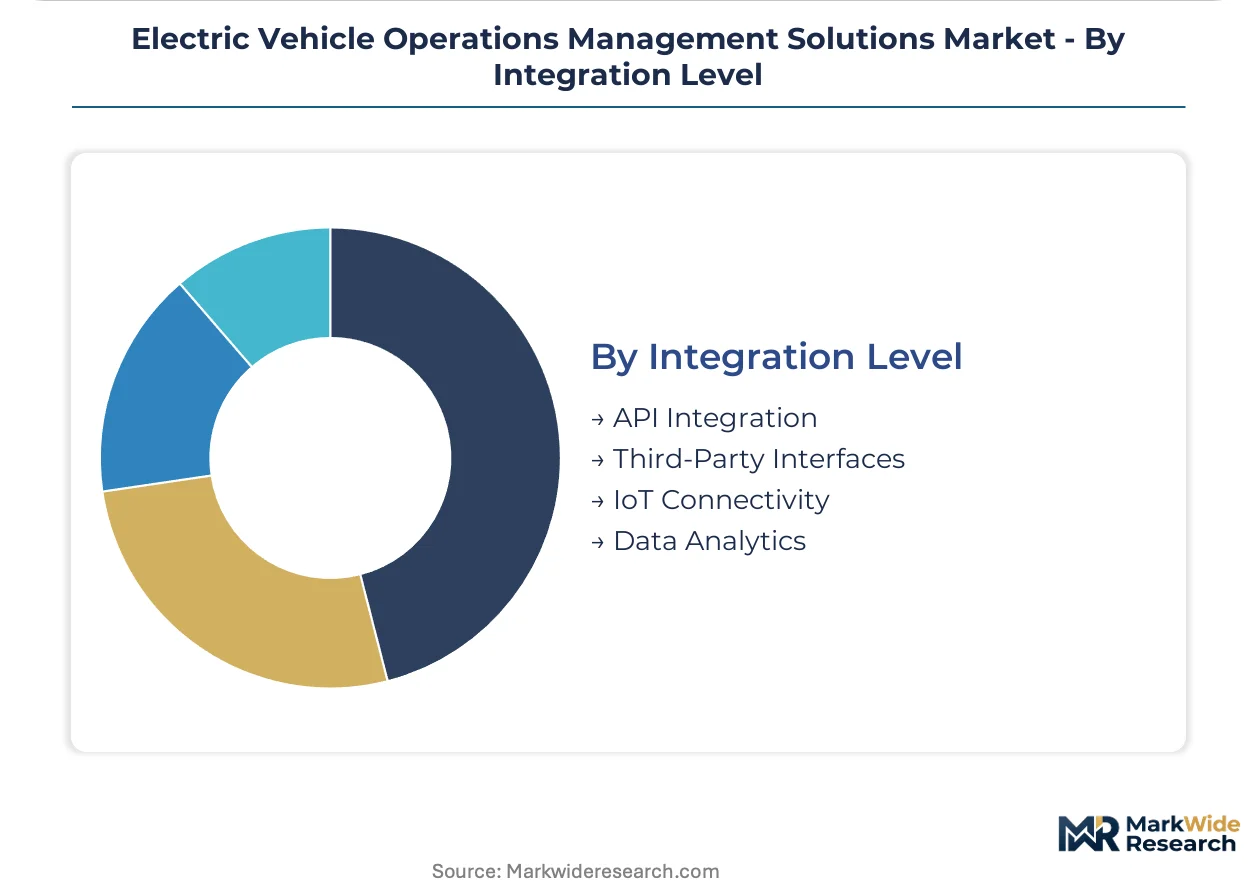
Integration Level:
Interoperability depth determines whether platforms function as standalone tools or embedded operational infrastructure.
- API Integration:Open-platform architectures anchor enterprise accounts through deep extensibility, enabling customization for predictive energy forecasting and real-time charge state orchestration. Large-scale operators demand this tier as basic telematics loses pricing power.
- IoT Connectivity:Vehicle-to-infrastructure protocols synchronize charging sessions with grid conditions and renewable energy availability. India's PLI scheme for domestic electric commercial vehicle manufacturing accelerates localized platform deployments requiring robust device interoperability.
- Third-Party Interfaces:Pre-built connectors reduce implementation friction for mid-market operators.
- Data Analytics:Embedded reporting pipelines automate compliance documentation for regulatory inspections.
API Integration commands premium pricing. IoT Connectivity represents the steepest expansion trajectory as grid-interactive charging becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the world's densest concentration of EV fleet management deployments, where state-backed electrification targets and domestic OEM scale generate unmatched platform demand.
United States
Logistics operators in California and Texas are procuring cloud-native platforms to satisfy EPA tailpipe standards and NHTSA CAFE regulations for documented emission reductions. The Inflation Reduction Act's commercial vehicle tax credits accelerate fleet electrification timelines. Chicago and Atlanta host dense last-mile fulfillment networks requiring sub-minute CAN bus telemetry.
Germany
Binding ICE phase-out mandates force logistics providers to adopt compliance-documentation platforms with auditable energy sourcing records. KBA-connected vehicle regulations accelerate edge-computing adoption for data localization. The Ruhr industrial corridor and Bavarian automotive clusters concentrate procurement authority for integrated charging-orchestration systems.
China
MIIT dual carbon goals and GB standards for connected vehicle data security shape product architecture for domestic and foreign platform providers. State grid corporations deploy scheduling algorithms capturing arbitrage from time-of-use electricity rates. The Yangtze River Delta and Pearl River Delta generate the world's largest deployment base for fleet management systems.
India
The PLI scheme for domestic electric commercial vehicle manufacturing accelerates localized platform deployments requiring robust device interoperability. Logistics operators in Maharashtra and Karnataka confront fragmented utility rate structures that reshape ROI calculus for charging infrastructure modules. Delhi-NCR and Tamil Nadu anchor early electrification programs for urban freight networks.
Netherlands
EU Green Deal compliance mandates and binding ICE end dates compress deployment timelines for integrated platforms. Randstad logistics corridors prioritize predictive energy forecasting modules over basic telematics. Rotterdam's port electrification program generates demand for vehicle-to-infrastructure protocols synchronizing charging with renewable availability.
Electric Vehicle Operations Management Solutions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across API extensibility and predictive analytics depth, with open-platform architectures commanding pricing power over closed telematics bundles. The vendor base stratifies into three tiers: enterprise-scale incumbents bundling charging controls, specialists in AI-driven safety scoring, and regional integrators serving mixed-fleet transitions. Dominant competitive moves include strategic partnerships with utility operators and portfolio diversification into carbon accounting modules.
Within the open-platform tier, Geotab and Samsara exemplify divergent anchoring strategies for enterprise accounts, while Motive occupies a position bridging safety analytics with energy metrics for operators managing concurrent ICE and EV assets. These three companies represent how solution providers differentiate through API depth, integrated data streams, and AI-driven scoring rather than commodity telematics functionality.
| Leading Market Players |
|---|
| Geotab |
| Samsara |
| Verizon Connect |
| ChargePoint |
| Element Fleet Management |
| Teletrac Navman |
| Motive |
| Trimble |
| Fleet Complete |
| Others |
Supply & Pricing Matrix
Lithium carbonate price indices cascade through EV fleet management hardware costs, compressing margins on telematics modules while amplifying pricing power for cloud-native software tiers that minimize physical component exposure.
Pricing Analysis
Per-vehicle-per-month subscription tiers anchor value-based pricing for fleet operators measuring platform ROI through uptime guarantees and fuel cost avoidance. Three-tier pricing structure across premium API-extensible, standard telematics-bundled, and economy charge-scheduling levels separates Geotab's open-architecture accounts from Samsara's integrated video bundles and Motive's safety-analytics positioning. Price differentiation hinges on predictive energy forecasting depth and carbon accounting module inclusion. Cost compression in hardware-dependent tiers is intensifying because semiconductor foundry capacity constraints in Taiwan and South Korea extend component lead times. Mid-market logistics cooperatives exhibit highest price sensitivity, while enterprise last-mile operators with EPA compliance mandates absorb premium tiers.
Supply Chain Analysis
Dual-sourcing requirements for vehicle telematics hardware mandate qualified suppliers across Taiwan, South Korea, and China to mitigate foundry concentration risk. Module integrators draw from automotive-grade microcontroller units, cellular modem chipsets, and CAN bus transceiver components. Single-source vulnerability concentrates in advanced node semiconductor fabrication where TSMC and Samsung anchor capacity. Distribution runs through Tier 1 automotive electronics suppliers and direct OEM channel partnerships, with cloud-native software layers bypassing physical logistics entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation accelerates as API-extensible architectures capture enterprise accounts and commodity telematics providers face margin compression from semiconductor cost volatility.
For Market Incumbents: Lock in enterprise logistics accounts through exclusive utility rate arbitrage partnerships that embed charging-orchestration into long-term fleet management contracts. Deepen backward integration into edge-computing firmware development to reduce dependency on scarce automotive CAN protocol engineering talent. The threat of AI-native entrants with pre-trained energy forecasting models demands defensive patent positioning in machine learning route optimization.
For New Entrants and Emerging Players: Enter via India's PLI-aligned electric commercial vehicle ecosystem, where localized platform deployments face limited foreign competition and fragmented utility structures create white-space for dynamic pricing algorithms. Target state transport corporation electrification mandates as the most penetrable government segment. Pursue white-label partnerships with domestic OEMs lacking proprietary fleet management software stacks.
For Investors and Strategic Acquirers: The window for entry favors specialized AI safety-scoring platforms with proven mixed-fleet deployments. Long-term viability rests on carbon accounting module integration as regulatory documentation requirements expand beyond basic telematics. Watch for MIIT data localization enforcement as the inflection signal separating compliant domestic architectures from excluded foreign providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Utility Rate Arbitrage Partnership | Locks in fleet operator retention through embedded electricity cost savings validated by FERC tariff structures. |
| Edge Computing Firmware Acquisition | Secures scarce automotive CAN protocol talent pools constrained by KBA and GB localization mandates. |
| Carbon Accounting Module Development | Captures EPA tailpipe standard compliance budgets as auditable emission documentation becomes mandatory. |
| India PLI Scheme Localization | Positions platforms for Maharashtra and Karnataka state transport electrification timelines ahead of foreign competitors. |
| Predictive Energy Forecasting R&D | Differentiates premium tiers as battery state-of-health optimization displaces basic telematics in procurement criteria. |
Research Methodology
SEC 10-K filings, utility interconnection queue databases, and MIIT connected vehicle policy releases formed the secondary backbone, cross-referenced with primary interviews involving fleet operations directors, charging infrastructure planners, and automotive telematics procurement managers. Bottom-up triangulation validated platform deployment counts against top-down addressable fleet size estimates across logistics, government, and ride-sharing segments.
Historical trendline analysis of telematics penetration rates and charging infrastructure commissioning timelines informed the projection framework across the analysis window. Segmentation dimensions modeled include deployment topology, solution module type, integration depth, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporate dynamic electricity pricing spread capture and ICE phase-out mandate compliance deadlines as industry-specific inputs.
Revisions become necessary when utility interconnection queue delays extend beyond current baselines or semiconductor foundry capacity constraints trigger component allocation rationing. Forecasts reflect assumptions around EU Green Deal enforcement consistency and China's GB standard implementation pace. A model refresh is warranted upon material change in EPA tailpipe standard stringency or NHTSA CAFE regulation timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market