
 Middle East Electric Vehicle Market | 2026-2036
Middle East Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Electric Vehicle Market Outlook
Asset-light leasing and pay-per-use financing is reconfiguring competitive entry barriers for fleet operators and ride-sharing platforms across the Middle East. Tesla leverages its Supercharger network to anchor premium positioning in Gulf markets. Lucid Group sustains manufacturing scale through its Saudi production facility. BYD Motors Inc. competes aggressively on battery cost structure for commercial vehicle contracts.
Middle East electric vehicles are battery-powered drivetrains rated for desert climate operation, typically employing thermal management systems to maintain cell stability above 45°C ambient temperatures, serving both private mobility and public transit decarbonization mandates. Passenger cars currently dominate volume, though commercial vehicles represent the fastest-expanding margin pool as logistics fleets electrify. Fast charging infrastructure leads capital deployment, while solid-state battery technology remains nascent but holds long-term relevance for range extension in high-temperature environments.
The UAE's Ministry of Energy and Infrastructure, Saudi Arabia's Saudi Standards, Metrology and Quality Organization, and Dubai's Roads and Transport Authority collectively shape vehicle homologation, charger interoperability mandates, and fleet electrification timelines across the region. These frameworks directly determine which manufacturers gain market access and which battery chemistries qualify for public procurement. Stakeholders must monitor regulatory alignment between national standards and emerging EU battery passport requirements to anticipate future compliance burdens.
Market Dynamics
Asset-light leasing structures are reconfiguring competitive entry barriers across Middle East fleet electrification, compressing upfront capital requirements while shifting margin capture toward charging network operators and battery-as-a-service providers.
Growth Catalysts
- Saudi Standards, Metrology and Quality Organization mandates:The national sustainability framework accelerates homologation timelines for electric commercial vehicles, forcing fleet operators into accelerated procurement cycles.
- Dubai's Roads and Transport Authority corridor buildout:Dense fast-charging infrastructure along highway networks eliminates range anxiety for inter-emirate logistics routes.
- Battery thermal management systems:Desert-rated cell stability above 45°C ambient temperatures unlocks year-round operational viability previously unattainable with temperate-zone battery packs.
Market Restraints
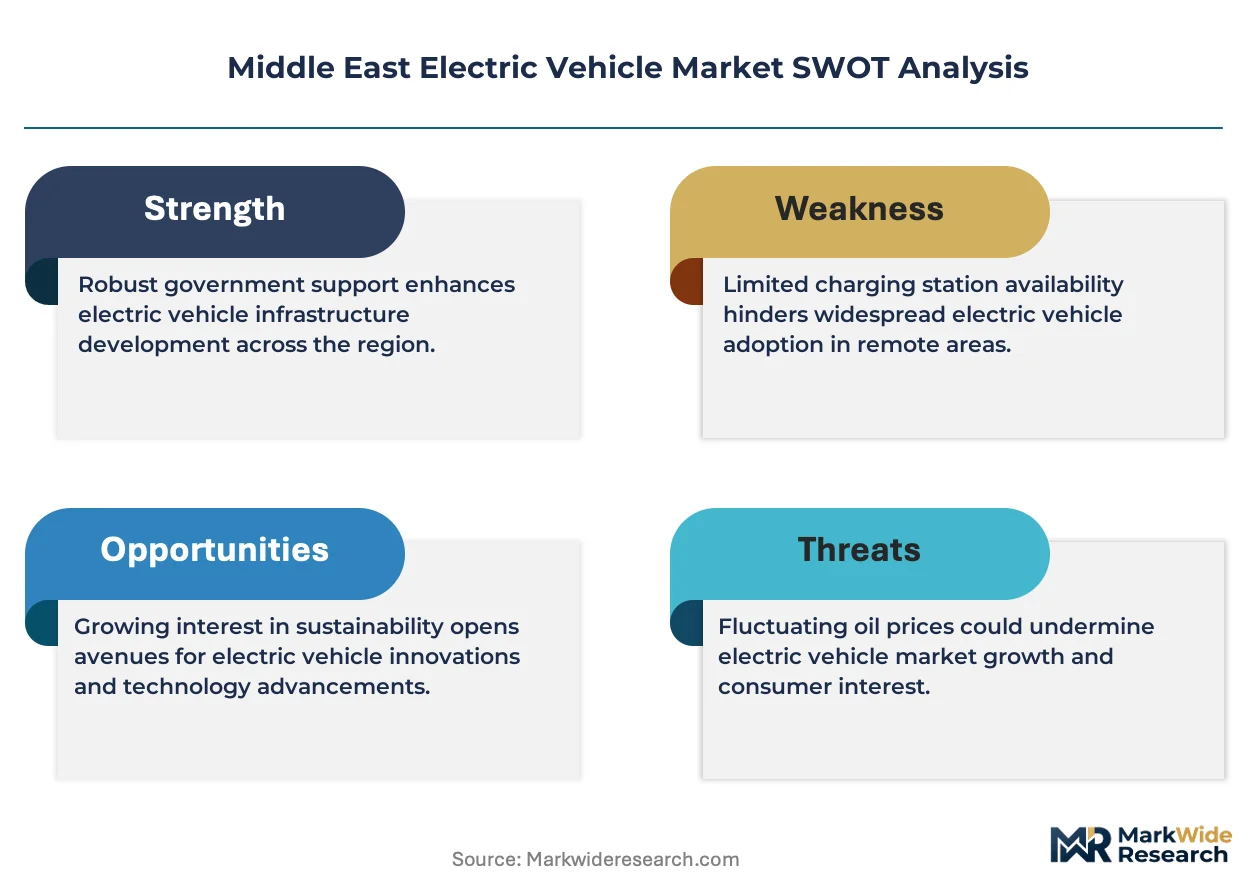
- Lithium supply concentration:Cathode material dependency on non-regional processing facilities exposes fleet operators to input cost volatility and currency fluctuation risk.
- Grid interconnection lag:Distribution network capacity constraints in secondary Saudi cities delay charging station commissioning despite permit approval.
- Residual value uncertainty:Battery degradation curves in high-temperature cycling conditions compress secondary market liquidity for leased commercial vehicles.
Strategic Opportunities
- Kuwait and Bahrain fleet penetration:Underdeveloped charging infrastructure creates first-mover positioning for integrated vehicle-energy-service bundles.
- EU battery passport alignment:Early compliance with emerging traceability mandates secures future export eligibility for regional assembly operations.
- Solid-state battery convergence:Next-generation thermal stability paired with existing desert-hardened packaging architectures promises extended range without cooling mass penalties.
Industry Challenges
- High-voltage technician scarcity:Certified repair capacity for 800V architectures lags vehicle deployment, extending downtime for commercial fleet operators.
- Multi-regulator homologation complexity:Divergent standards between UAE's Ministry of Energy and Infrastructure and Saudi certification bodies force redundant testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Electric Vehicle Market |
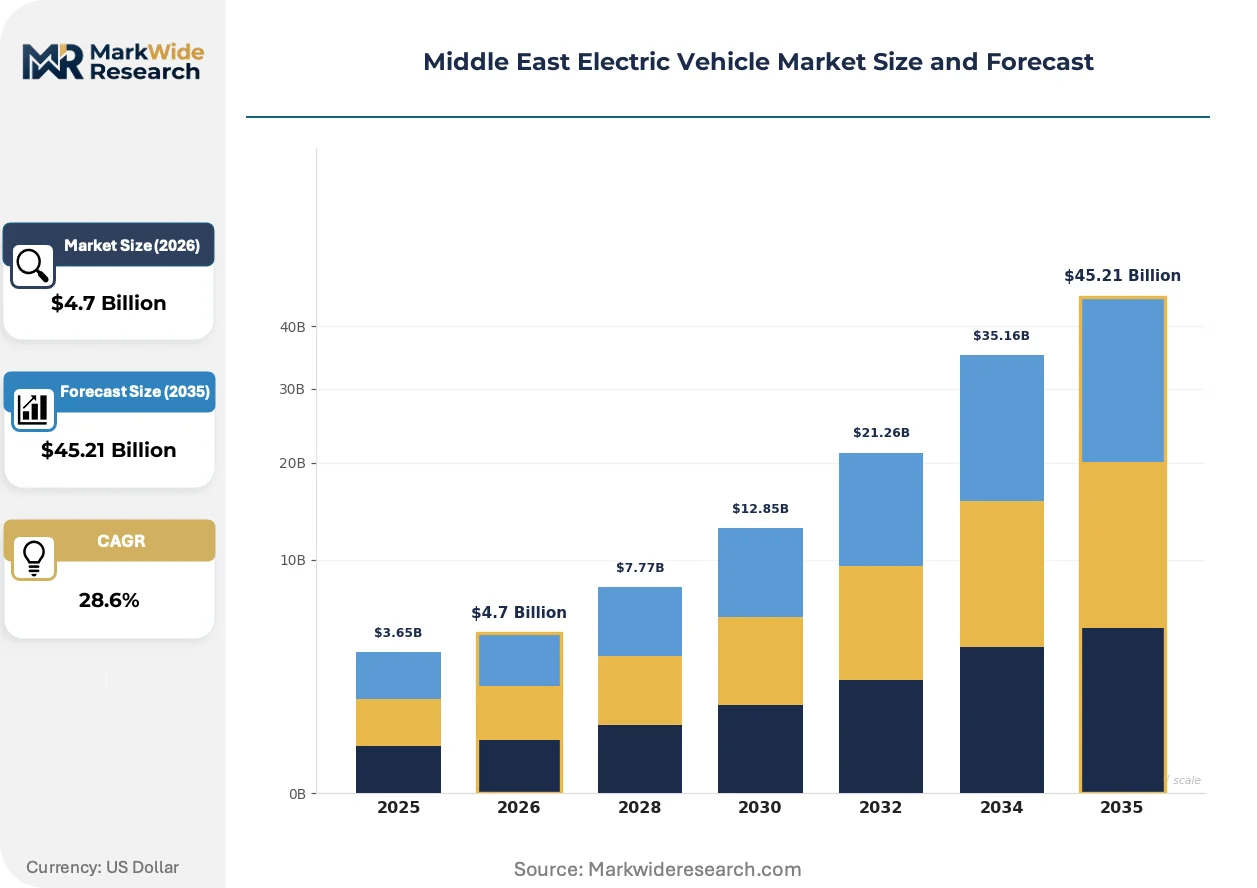
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vehicles, Two-wheelers, Buses Battery Technology: Lithium-ion, Solid-state, Lead-acid, Nickel-metal Hydride Charging Infrastructure: Fast Charging, Home Charging, Public Charging, Wireless Charging End User: Fleet Operators, Individual Consumers, Government Agencies, Ride-sharing Services |
| Companies Covered | Tesla, Lucid Group, BMW AG, Hyundai Motor Company, Nissan Motor Co., Ltd., Mercedes-Benz Group AG, Toyota Motor Corporation, Volkswagen AG, BYD Motors Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Electric Vehicle Market Strategic Shifts
Power electronics miniaturization and silicon carbide inverter deployment are compressing drivetrain packaging constraints while enabling faster charging protocols across Gulf temperature extremes.
Solid-state electrolyte formulations are collapsing the thermal management mass traditionally required for desert operation. Saudi-based fleet operators are piloting these cell architectures in airport shuttle applications where downtime minimization outweighs acquisition premiums. The technology is collapsing the historical trade-off between battery energy density and cooling system weight, enabling commercial vehicle platforms to reclaim payload capacity.
SFDA and MOHAP alignment on vehicle-to-grid interoperability standards is mandating bidirectional charging capability in all new public procurement contracts. This regulatory convergence forces manufacturers to redesign onboard power electronics for grid-feed certification. Commercial vehicle segments face the steepest compliance timeline, with Dubai's taxi fleet conversion serving as the operational testbed.
Fleet procurement is consolidating around total-cost-of-ownership contracting that unbundles vehicle acquisition from energy and maintenance obligations. Energy service companies are displacing traditional lessors as the primary counterparty for municipal bus operators. This shift is most visible in Abu Dhabi, where transport authorities now contract directly with charging network operators for guaranteed uptime rather than capitalizing vehicle assets.
Middle East Electric Vehicle Market Segmentation
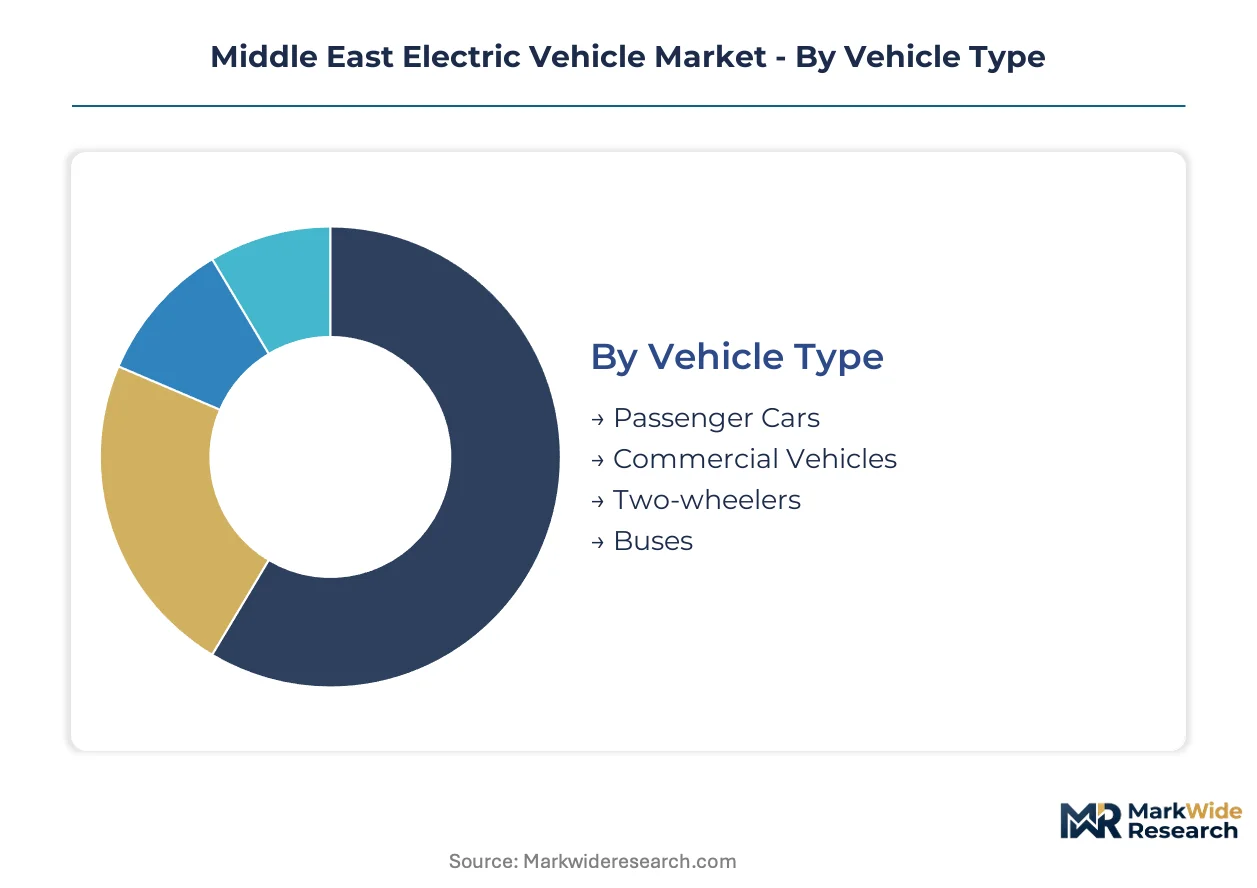
Segmentation in Middle East electric vehicles reveals divergent procurement cycles and capital intensity across vehicle classes and customer types. Fleet operators rotate assets on compressed timelines compared with individual consumers, while charging infrastructure investments lock in decade-long payback horizons.
Vehicle Type:
Passenger cars turn over every 4-5 years in Gulf markets, while commercial vehicles and buses cycle through 8-12 year replacement windows, creating asynchronous demand pulses across the forecast period.
- Passenger Cars:Battery-electric sedans and SUVs rated for 45°C ambient operation dominate private registrations in Dubai and Abu Dhabi. Dubai's Roads and Transport Authority mandates electrification targets for taxi and limousine fleets, concentrating demand in premium thermal-management-equipped platforms.
- Commercial Vehicles:Light-duty vans and medium trucks with modular battery packs serve last-mile logistics across Saudi Arabia's secondary cities. Saudi Standards, Metrology and Quality Organization homologation timelines are accelerating fleet procurement cycles for this segment.
- Two-wheelers:Electric motorcycles and scooters penetrate delivery fleet operations in dense urban cores.
- Buses:Single-deck and articulated electric buses with liquid-cooled battery systems anchor municipal transit electrification mandates.
Passenger cars anchor the volume base while commercial vehicles gain share at the steepest rate.
Battery Technology:
Cost tiers separate established chemistries from emerging architectures, with thermal management requirements adding premium layers specific to desert operation.
- Lithium-ion:NMC and LFP cell formats with active cooling circuits constitute the installed base across UAE and Saudi fleets. Procurement concentrates on LFP variants for commercial applications where cycle life outweighs energy density priorities.
- Solid-state:Sulfide and oxide electrolyte formulations promise collapsed thermal management mass. Saudi-based airport shuttle operators are piloting these cells where downtime minimization justifies acquisition premiums.
- Lead-acid:Flooded and AGM variants persist in low-speed utility vehicles and golf cart applications.
- Nickel-metal Hydride:NiMH packs retain niche presence in hybrid transition platforms and price-sensitive fleet segments.
Lithium-ion dominates current procurement volumes while solid-state expands most quickly in premium commercial deployments.
Charging Infrastructure:
Application context dictates hardware selection, with highway corridor economics diverging sharply from residential and depot configurations.
- Fast Charging:350kW liquid-cooled cable systems with CCS2 connectors anchor inter-emirate highway networks. Dubai's highway corridor buildout is eliminating range anxiety for long-haul logistics routes.
- Home Charging:Level 2 AC wallboxes with load management serve villa-dwelling consumers in Abu Dhabi and Riyadh. Grid interconnection lag in secondary Saudi cities delays commissioning despite permit approval.
- Public Charging:50-150kW destination chargers at retail and hospitality locations capture dwell-time charging revenue.
- Wireless Charging:Inductive pad systems pilot in taxi queue applications where connector wear and vandalism risk concentrate.
Fast charging captures the capital deployment majority while wireless charging climbs the fastest in controlled-access fleet environments.
End User:
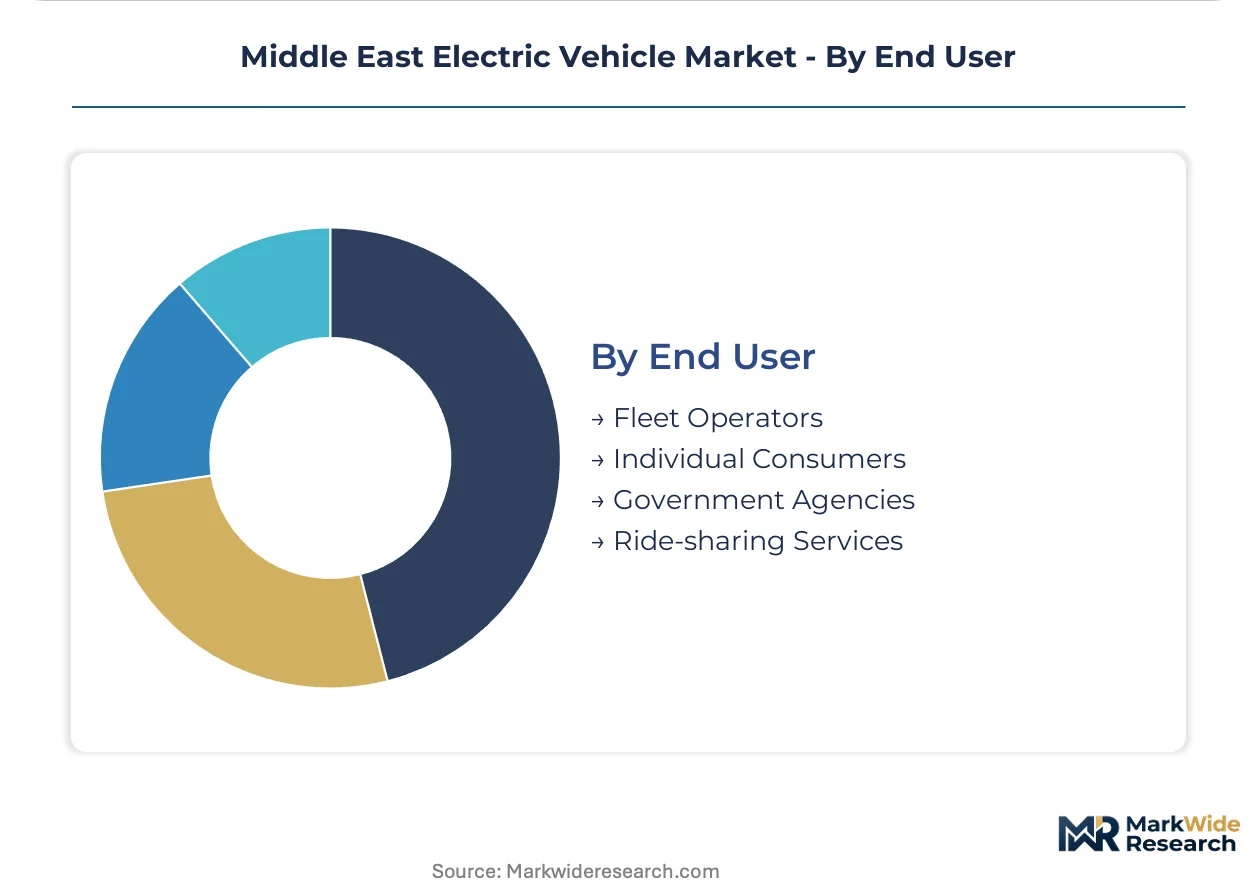
Customer type determines contract structure, with fleet operators consolidating procurement through energy-service agreements while individual consumers retain traditional ownership models.
- Fleet Operators:Logistics, delivery, and rental fleet managers contracting through total-cost-of-ownership structures. Asset-light leasing is compressing upfront capital requirements while shifting margin capture toward charging network operators.
- Individual Consumers:Private buyers in UAE and Saudi Arabia prioritizing brand prestige and Supercharger network access. Residual value uncertainty in high-temperature cycling conditions compresses secondary market liquidity for leased vehicles.
- Government Agencies:Municipal transport authorities and federal procurement bodies mandating electrification timelines. SFDA and MOHAP alignment on vehicle-to-grid standards is forcing bidirectional charging capability into public contracts.
- Ride-sharing Services:Platform operators with centralized charging depot requirements and maximized utilization targets.
Fleet operators anchor the volume base while government agencies gain share at the steepest rate through accelerated public procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's national sustainability framework and the UAE's charging corridor investments are channeling fleet procurement toward electric commercial vehicles across the Gulf. National regulators in both countries have compressed homologation timelines, forcing accelerated deployment schedules. Secondary markets in Kuwait, Bahrain, and Qatar present first-mover opportunities for integrated vehicle-energy-service bundles.
United Arab Emirates
Dubai and Abu Dhabi anchor regional demand through dense fast-charging highway networks and municipal fleet electrification mandates. Dubai's Roads and Transport Authority enforces taxi and limousine conversion targets, concentrating procurement in thermally rated platforms. Jebel Ali industrial corridor hosts logistics fleet operators contracting through total-cost-of-ownership structures with charging network guarantees.
Saudi Arabia
Riyadh and the Eastern Province drive commercial vehicle electrification through Saudi Standards, Metrology and Quality Organization procurement acceleration. The national sustainability framework mandates compressed timelines for electric bus and light truck homologation. NEOM Northwest serves as a testbed for solid-state battery pilots in controlled-climate shuttle applications.
Qatar
Doha's public transit authority is consolidating electric bus procurement ahead of major event infrastructure commitments. The country's national transport regulator mandates bidirectional charging capability in new municipal contracts. Lusail City development clusters depot-based charging infrastructure for integrated fleet operations.
Kuwait
Kuwait City logistics operators face underdeveloped charging infrastructure, creating entry gaps for bundled vehicle-energy-service offerings. The country's national electricity authority is piloting grid interconnection protocols for commercial depot charging. Shuwaikh industrial area hosts early fleet electrification trials for last-mile delivery consolidation.
Bahrain
Manama's compact urban geography favors electric two-wheeler penetration in delivery fleet operations. The national transport regulator aligns vehicle-to-grid standards with UAE and Saudi frameworks to ensure cross-border fleet interoperability. Muharraq logistics corridor presents concentrated demand for light commercial vehicle electrification.
Middle East Electric Vehicle Market Competitive Environment
Channel-controlling players compete with product-specialist players across charging infrastructure, battery supply, and vehicle assembly tiers. The market structure fragments between integrated energy-service providers and standalone automotive OEMs. Three archetypes dominate: network-anchored premium brands, manufacturing-scale cost competitors, and regional assembly operators. Strategic moves concentrate on charging infrastructure lock-in and thermal management technology licensing.
Within the network-anchored tier, Tesla and Lucid Group exemplify positioning built on proprietary fast-charging ecosystems and Gulf-specific climate engineering. BYD Motors Inc. represents manufacturing-scale cost competition targeting commercial fleet contracts through battery cost structure advantages. These three players occupy distinct competitive vectors rather than direct confrontation, with each anchoring separate procurement channels.
| Leading Market Players |
|---|
| Tesla |
| Lucid Group |
| BMW AG |
| Hyundai Motor Company |
| Nissan Motor Co., Ltd. |
| Mercedes-Benz Group AG |
| Toyota Motor Corporation |
| Volkswagen AG |
| BYD Motors Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese lithium-ion cell manufacturing is compressing cathode material pricing while forcing Middle East fleet operators into longer-term offtake negotiations to secure supply certainty. This utilization dynamic simultaneously erodes supplier margins and transfers volume-commitment risk downstream to buyers locking in desert-rated thermal management configurations.
Pricing Analysis
Certification level (SASO/ECAS-grade homologation) creates the primary spread between premium and standard vehicle tiers. Three-tier pricing structure across premium, standard, and economy levels dominates fleet procurement, with thermal management system sophistication and battery cycle-life guarantees as key differentiation drivers. Cost compression in LFP cell tiers is intensifying because of cathode oversupply, though high-voltage architecture certification costs insulate premium platforms. Municipal bus operators exhibit highest price sensitivity due to total-cost-of-ownership contracting, while airport shuttle operators prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Extended payment terms from Chinese cell manufacturers are restructuring working capital requirements for Middle East fleet lessors. Geographic supply concentration centers on China for LFP cathodes, South Korea for NMC precursors, and Japan for power electronics silicon carbide substrates. Raw material dependencies span lithium carbonate from Chilean salares, cobalt hydroxide from the DRC, and copper foil from Taiwanese rolling mills. Single-source vulnerability in 800V inverter chip supply exposes charging infrastructure builders to allocation risk. Distribution runs through Jebel Ali free zone consolidation hubs before last-mile deployment to Saudi secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-voltage technician certification gaps and bidirectional charging engineering scarcity are constraining fleet deployment velocity across the Gulf, creating asymmetric returns for stakeholders who close these capability gaps before regulatory mandates harden.
For Market Incumbents: Build charging network lock-in as the primary moat against manufacturing-scale competitors. Secure exclusive depot-service agreements with Dubai's Roads and Transport Authority and Saudi municipal bus operators to forestall BYD's battery-cost advantage. Deepen backward integration into thermal management system production to defend margin position against LFP cell commoditization. Prioritize 800V technician training academy investments ahead of SFDA-MOHAP interoperability mandate enforcement. For New Entrants and Emerging Players: Kuwait City logistics corridors offer the most penetrable geography for integrated vehicle-energy-service bundles given underdeveloped charging infrastructure and absence of incumbent network anchors. Target Bahrain's Muharraq industrial zone for light commercial vehicle electrification pilots, leveraging compact urban geography to minimize range requirements. Pursue energy-service-company partnerships rather than direct OEM sales to compress customer acquisition cycles and share balance-sheet burden. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among charging network operators with guaranteed uptime contracts to municipal authorities, positioning these assets for premium valuation multiples. Long-term viability across the analysis window favors integrated vehicle-energy-service providers over standalone OEMs exposed to cell cost volatility. Acquisition target archetype: regional assembly operations with SASO homologation pathways and existing fleet-service relationships. Monitor solid-state battery pilot outcomes at NEOM as inflection indicator for next-generation thermal management displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term LFP cell offtakes from CATL or BYD lock in cost structure for Saudi fleet operators. |
| Charging Infrastructure Partnership | Collaboration with DEWA or SEC secures grid interconnection priority for highway corridor buildout. |
| Thermal Management Technology Licensing | Desert-rated cooling system IP transfers enable regional assembly without full R&D replication. |
| Platform Standardization | Common 800V architectures reduce technician training burden and parts inventory complexity. |
| Geographic Manufacturing Footprint | Saudi-based assembly satisfies local content requirements for public procurement eligibility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and vehicle registration databases. Primary interviews engaged fleet procurement directors at Saudi logistics operators, charging network engineering leads in Dubai, and homologation specialists at SASO and ECAS certification bodies. Secondary validation drew from Dubai's Roads and Transport Authority electrification mandates, Saudi Standards, Metrology and Quality Organization technical regulations, and IHS Markit vehicle production data. Bottom-up fleet deployment modeling triangulated against top-down market sizing from energy infrastructure investment disclosures.
Forecast inputs incorporate vehicle class segmentation, battery chemistry adoption curves, charging infrastructure deployment schedules, and regulatory mandate timelines. Modeled dimensions span passenger cars, commercial vehicles, and buses across lithium-ion and solid-state technology pathways, with end-user splits between fleet operators, individual consumers, and government agencies. CAGRs derived from regression analysis of historical procurement cycles against policy acceleration signals. Industry-specific inputs include desert thermal degradation curves for battery cycle-life estimation and grid interconnection lag assumptions for secondary Saudi cities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese cell manufacturers or accelerated solid-state commercialization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Electric Vehicle Insulation Market