
 Electric Tricycle Market | 2026-2036
Electric Tricycle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Tricycle Market Analysis
The EU Green Deal's urban mobility decarbonization targets are restructuring procurement criteria for municipal vehicle fleets across member states. Jinpeng Electric Vehicle leverages its integrated battery-pack manufacturing to anchor pricing power in European distribution channels. Bajaj Auto competes through dense service networks across South Asian cities where after-sales density determines fleet operator loyalty. Yadea specializes in high-torque hub motor designs that differentiate its cargo variants on steep terrain routes.
An electric tricycle is a three-wheeled vehicle propelled by one or more electric motors, typically drawing from lithium-ion battery packs mounted beneath the cargo deck or behind the rider seat, with power outputs ranging from 250W to 2,000W depending on payload class. Its primary commercial purpose centers on short-haul urban logistics, passenger ferrying, and agricultural material transport where maneuverability and low operating costs outweigh speed requirements. The local delivery segment leads volume adoption as e-commerce fulfillment networks prioritize narrow-street accessibility over van-based distribution. Smart features technology represents the fastest-expanding category as fleet operators demand telematics integration for route optimization and theft prevention. Personal use applications remain mature in retirement communities and disability-access markets where regulatory carve-outs permit unlicensed operation.
The EPA's Phase 3 greenhouse gas standards for medium-duty vehicles are tightening emissions benchmarks that indirectly elevate electric tricycle competitiveness against small internal-combustion trucks in US urban zones. India's BIS certification requirements for electric vehicle safety and the PLI scheme's battery cell manufacturing incentives are reshaping supplier qualification thresholds for OEMs serving South Asian markets. China's MIIT new energy vehicle catalog determines national subsidy eligibility, filtering market access toward models meeting prescribed range and energy-density benchmarks. Stakeholders must monitor how municipal low-emission zone expansions redefine addressable fleet populations in dense metropolitan cores.
Market Dynamics
Fleet electrification mandates across municipal logistics networks are compressing replacement cycles for internal-combustion three-wheelers, forcing manufacturers to reconfigure powertrain architectures around standardized battery interfaces rather than proprietary designs.
Growth Catalysts
- India's FAME-II subsidy extension:The PLI scheme's battery cell manufacturing incentives reduce landed powertrain costs for domestic OEMs serving commercial fleet operators.
- Last-mile delivery densification:E-commerce fulfillment networks in Vietnam's urban logistics corridors prioritize narrow-street accessibility over van-based distribution.
- EU Green Deal urban mobility targets:Municipal procurement criteria across member states now mandate zero-emission vehicle shares in contracted service fleets.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing capacity clusters in China, exposing non-Chinese OEMs to input cost volatility and qualification delays.
- Hub motor torque limitations:Existing 2,000W designs struggle on sustained gradients above 12%, restricting cargo viability in hilly South Asian terrain.
- BIS certification timelines:India's safety testing protocols for electric vehicle battery packs extend product launch windows by 8-14 months versus unregulated imports.
Strategic Opportunities
- Telematics-integrated fleet management:Route optimization and theft-prevention software layers are expanding into the fastest-expanding category as operators demand connected asset visibility.
- Philippines archipelago logistics:Island-hopping cargo networks favor compact three-wheeled haulers with modular battery swapping over fixed-charge van alternatives.
- China's MIIT catalog alignment:Models meeting prescribed range and energy-density benchmarks unlock national subsidy eligibility, filtering market access toward qualified suppliers.
Industry Challenges
- Battery thermal management engineering:Southeast Asian ambient temperatures degrade lithium-ion cycle life, requiring liquid-cooled pack designs that inflate BOM costs.
- Service network density requirements:Fleet operators in South Asian cities demand sub-24-hour repair turnaround, forcing OEMs to pre-position technicians and spare hubs in dense urban clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Tricycle Market |
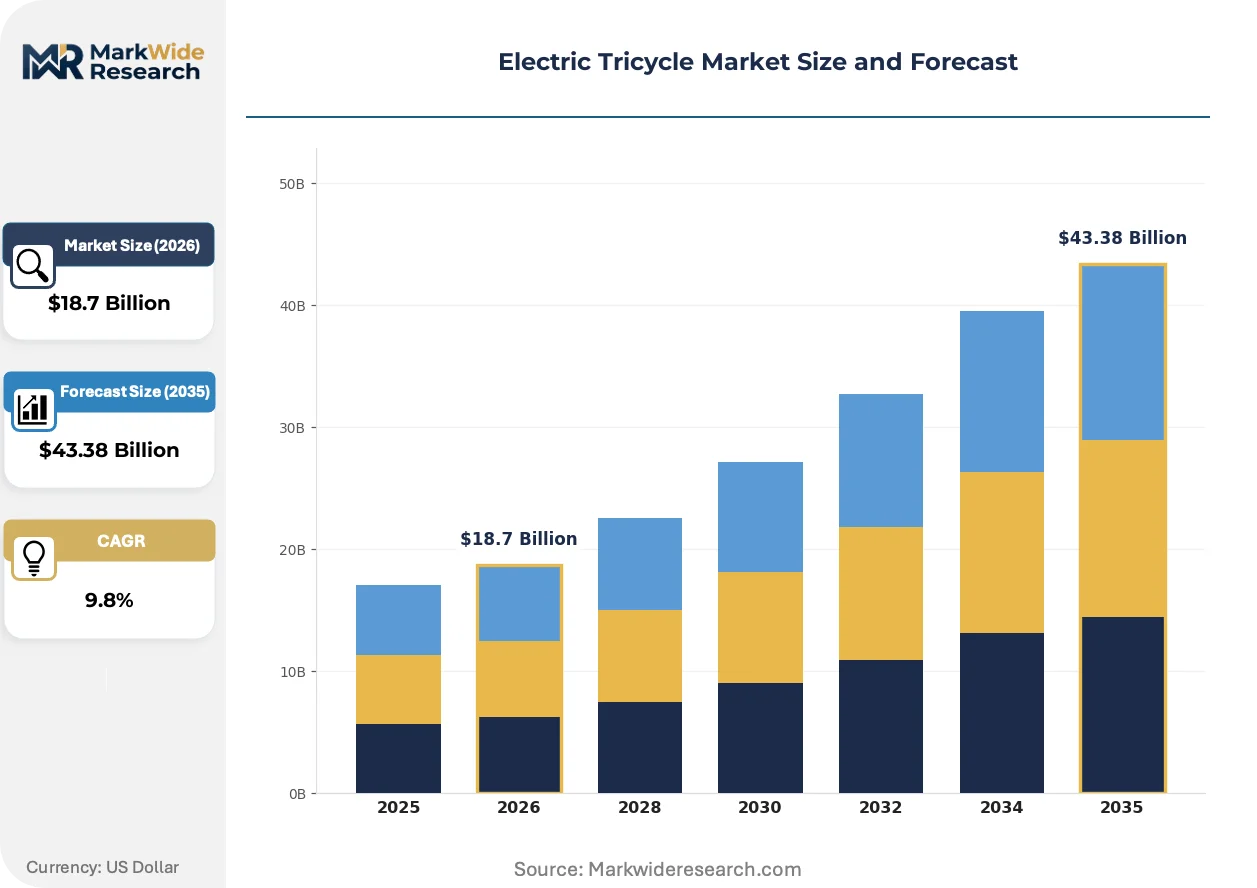
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Local Delivery, Personal Use, Utility Transport, Agricultural Use End User: Individuals, Municipalities, Enterprises, Delivery Services Power Source: Batteries, Fuel Cells, Hybrid Systems, Solar Power Technology: Automatic, Manual, Smart Features, Connectivity Solutions |
| Companies Covered | Terra Motors, Jinpeng Electric Vehicle, Bajaj Auto, eBikeGo, BEMAC Corporation, Yadea, Piaggio Vehicles, Rad Power Bikes, Mahindra Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Tricycle Market Emerging Trajectories
Smart feature integration is redefining asset valuation models as fleet operators shift procurement criteria from unit price to total cost of ownership metrics incorporating connectivity and predictive maintenance capabilities.
Swappable battery architectures are expanding into commercial tricycle platforms, enabling operators to eliminate dwell time at charging stations. Logistics providers in Vietnam's urban corridors adopt subscription-based energy models where battery ownership remains with third-party infrastructure providers. This decoupling of vehicle and energy assets is compressing upfront capital requirements and accelerating fleet turnover rates among small-scale operators.
The EPA's Phase 3 greenhouse gas standards for medium-duty vehicles tighten emissions benchmarks that indirectly elevate electric tricycle competitiveness against small internal-combustion trucks in US urban zones. California's Advanced Clean Trucks regulation extends these pressures to last-mile delivery segments previously exempt from passenger-car zero-emission mandates. Fleet operators in Los Angeles and New York logistics hubs now face compliance-driven procurement timelines that favor electric three-wheelers for sub-500-pound payload routes.
After-sales service unbundling is disrupting traditional OEM-dealer relationships as fleet operators negotiate direct contracts with third-party maintenance networks. Independent service providers in India's Tier-2 cities now offer hub motor rebuilds and battery pack refurbishment at 40% below authorized channel rates. This channel fragmentation pressures incumbent manufacturers to defend parts margin through proprietary diagnostic tools and encrypted battery management systems.
Electric Tricycle Market Segmentation
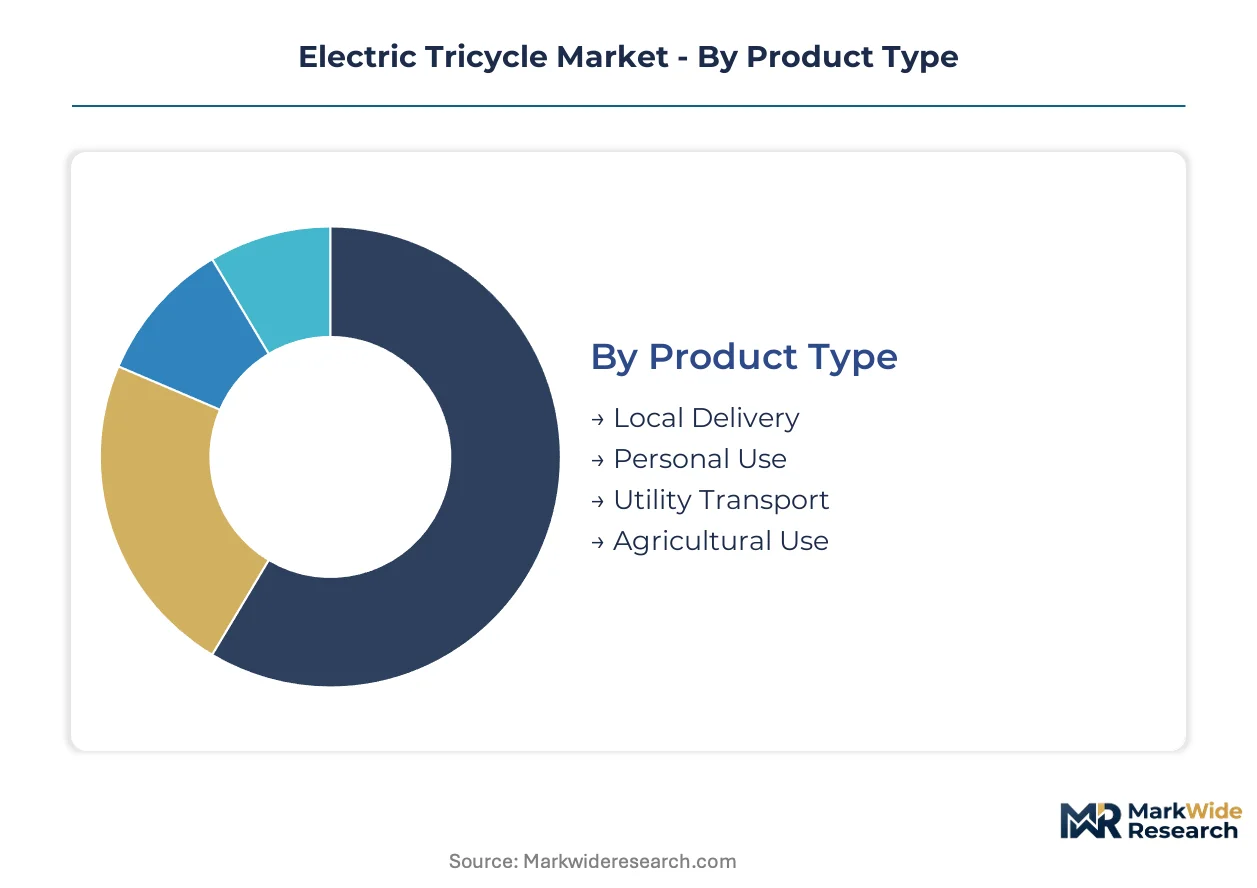
Electric tricycle procurement patterns diverge sharply across buyer archetypes, with fleet operators prioritizing standardized battery interfaces and telematics integration while individual buyers emphasize purchase price and local service availability. Understanding these segment boundaries clarifies why product configurations and distribution channels cluster around distinct customer profiles rather than converging on universal designs.
Product Type:
Commercial operators prioritize payload capacity and route efficiency over rider comfort, while personal buyers emphasize maneuverability and regulatory exemptions.
- Local Delivery:Cargo-optimized frames with 500kg+ payload ratings and swappable battery architectures dominate procurement from e-commerce fulfillment networks. Vietnam's urban logistics corridors favor compact three-wheeled haulers with sub-2.5m turning radius for narrow-street accessibility.
- Personal Use:Low-speed variants with 250W hub motors and step-through frames target retirement communities and disability-access markets where regulatory carve-outs permit unlicensed operation. Demand concentrates in European municipal programs subsidizing mobility aids for elderly populations.
- Utility Transport:Reinforced chassis with 1,500W+ powertrains serve municipal maintenance crews and small-scale construction material hauling.
- Agricultural Use:All-terrain configurations with knobby tires and extended-range battery packs support farm-to-market produce transport in Southeast Asian rural corridors.
Volume sits with Local Delivery; growth tilts toward Agricultural Use.
End User:
Procurement scale and decision speed separate these buyer classes, with Enterprises negotiating multi-year fleet contracts while Individuals transact through retail channels.
- Enterprises:Logistics providers and industrial facilities demand telematics-integrated assets with predictive maintenance capabilities and sub-24-hour repair turnaround guarantees. India's FAME-II subsidy extension accelerates fleet conversions among commercial operators seeking fuel cost reduction.
- Delivery Services:Last-mile specialists prioritize narrow-street accessibility and subscription-based energy models where battery ownership remains with infrastructure providers.
- Individuals:Price-sensitive buyers in personal mobility segments respond to purchase subsidies and local service network density.
- Municipalities:EU Green Deal procurement criteria now mandate zero-emission vehicle shares in contracted service fleets across member states.
Enterprises command the largest order volumes; Delivery Services are expanding most quickly.
Power Source:
Energy asset ownership models—purchase versus subscription—determine total cost of ownership calculations more than unit efficiency metrics.
- Batteries:Lithium-ion packs with 2-4kWh capacity dominate commercial applications, though Southeast Asian ambient temperatures degrade cycle life and require liquid-cooled designs.
- Fuel Cells:Hydrogen proton-exchange membrane systems target long-haul agricultural routes where battery weight compromises payload efficiency.
- Hybrid Systems:Range-extender architectures combining small battery packs with combustion generators address charging infrastructure gaps in Philippines archipelago logistics.
- Solar Power:Roof-integrated photovoltaic panels supplement charging for low-speed personal use variants in sun-intensive climates.
Batteries retain volume leadership; Hybrid Systems show the steepest expansion trajectory in island-hopping networks.
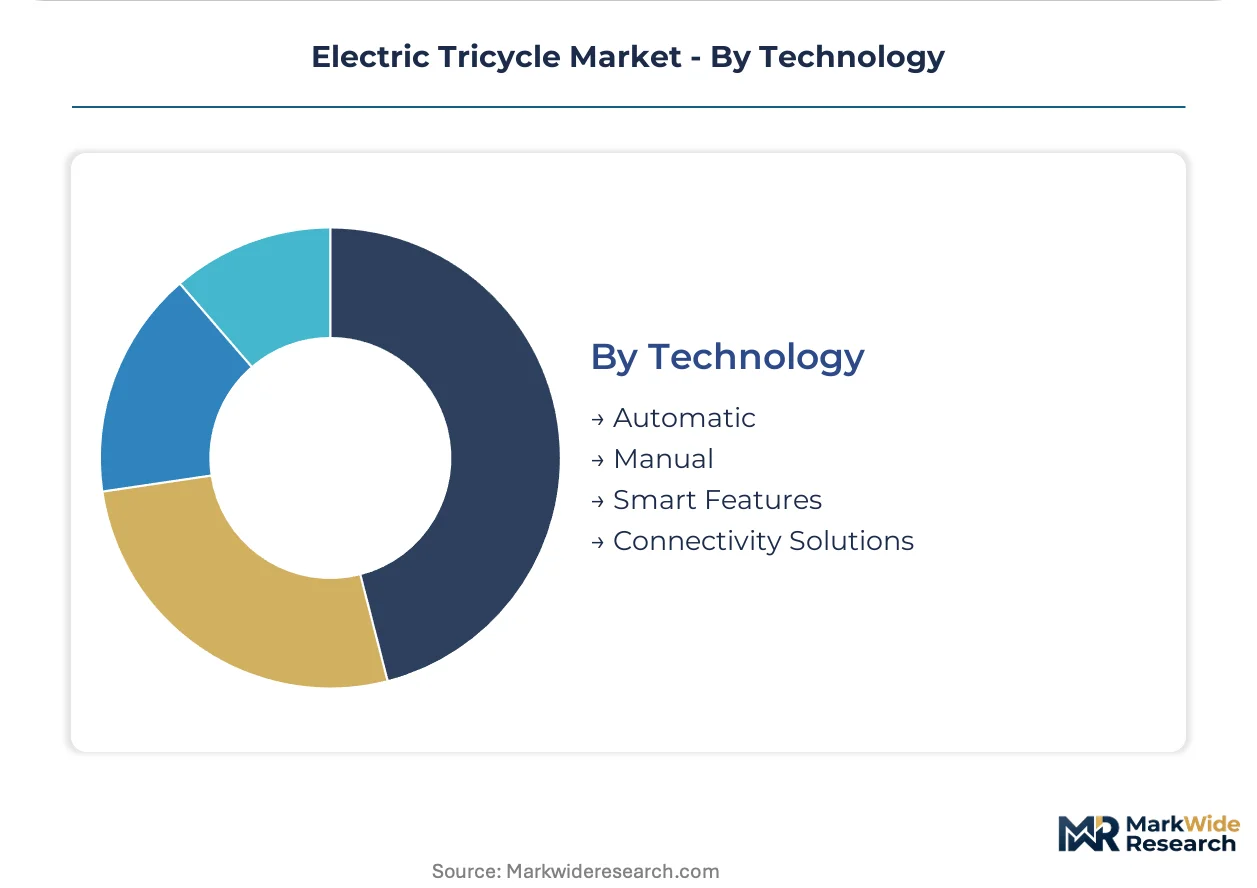
Technology:
Connectivity integration separates premium configurations from commodity hardware, with fleet operators valuing asset visibility over incremental motor performance.
- Smart Features:GPS tracking, geofencing, and remote diagnostics command pricing premiums from fleet managers seeking theft prevention and route optimization. This category is gaining share fastest as procurement criteria shift from unit price to total cost of ownership metrics.
- Connectivity Solutions:Cellular-enabled battery management systems enable over-the-air firmware updates and usage-based insurance pricing.
- Automatic:Single-speed hub motor drives with regenerative braking dominate low-maintenance commercial deployments.
- Manual:Pedal-assist configurations with selectable power levels persist in regulatory jurisdictions requiring human propulsion capability.
Automatic systems hold current volume; Smart Features capture incremental growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ho Chi Minh City logistics corridors anchor electric tricycle deployment density, where narrow street grids and e-commerce fulfillment networks compress delivery timelines and favor compact three-wheeled cargo haulers over van-based distribution.
India
Commercial fleet operators in Delhi-NCR and Mumbai accelerate conversions from internal-combustion three-wheelers under the FAME-II subsidy extension and PLI scheme battery manufacturing incentives. The BIS certification requirements for electric vehicle safety extend product launch windows but reshape supplier qualification thresholds for domestic OEMs. Karnataka's Bengaluru-Tumkur industrial corridor concentrates assembly operations serving South Asian urban logistics networks.
China
The MIIT new energy vehicle catalog filters market access toward models meeting prescribed range and energy-density benchmarks, determining national subsidy eligibility for manufacturers. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou integrate battery-pack production with vehicle assembly. Shenzhen's technology zones pioneer telematics-integrated fleet management systems for commercial operators.
United States
EPA Phase 3 greenhouse gas standards for medium-duty vehicles tighten emissions benchmarks that elevate electric tricycle competitiveness against small internal-combustion trucks in Los Angeles and New York logistics hubs. California's Advanced Clean Trucks regulation extends zero-emission mandates to last-mile delivery segments. Fleet operators in dense metropolitan cores face compliance-driven procurement timelines favoring electric three-wheelers for sub-500-pound payload routes.
Philippines
Island-hopping cargo networks favor compact three-wheeled haulers with modular battery swapping over fixed-charge van alternatives across the archipelago. Metro Manila's urban logistics corridors prioritize narrow-street accessibility for e-commerce fulfillment. Cebu and Davao distribution hubs adopt hybrid range-extender architectures addressing charging infrastructure gaps between islands.
Germany
The EU Green Deal's urban mobility decarbonization targets restructure municipal procurement criteria for zero-emission vehicle shares in contracted service fleets. North Rhine-Westphalia's logistics clusters test cargo-optimized electric tricycles for last-mile distribution in Cologne and Düsseldorf city centers. Bavaria's industrial zones develop liquid-cooled battery thermal management systems for Southeast Asian ambient temperature applications.
Electric Tricycle Market Vendor Landscape
The competitive structure tilts toward integrated battery-pack manufacturers with captive powertrain supply. Player density concentrates around three strategic archetypes: Chinese OEMs with upstream cell manufacturing control, South Asian assemblers leveraging dense service networks, and European specialists in telematics-integrated fleet solutions. Dominant competitive moves include backward integration into cathode material processing and geographic expansion through third-party maintenance network licensing.
Among Asia-Pacific-based manufacturers, Jinpeng Electric Vehicle, Bajaj Auto, and Yadea occupy distinct positioning vectors. Jinpeng exemplifies the integrated battery-pack archetype with manufacturing concentration in Chinese industrial zones. Bajaj Auto represents the service-network-dense model prevalent across South Asian urban markets. Yadea anchors the high-torque hub motor specialization for steep terrain cargo applications. These three entities collectively illustrate how geographic origin and structural configuration shape competitive differentiation in procurement-intensive fleet segments.
| Leading Market Players |
|---|
| Terra Motors |
| Jinpeng Electric Vehicle |
| Bajaj Auto |
| eBikeGo |
| BEMAC Corporation |
| Yadea |
| Piaggio Vehicles |
| Rad Power Bikes |
| Mahindra Electric |
| Others |
Supply Flow & Price Mechanics
Swappable battery architectures are compressing upfront capital requirements for fleet operators while simultaneously concentrating manufacturing leverage among integrated cell producers in Chinese industrial zones. This dual shift redraws cost economics around energy-as-a-service models and rewards OEMs with captive cathode processing capabilities.
Pricing Analysis
Total cost of ownership metrics anchored to uptime guarantees and route throughput now command premium positioning over unit sticker prices in enterprise procurement. Three-tier pricing structure across premium telematics-integrated, standard connected, and economy basic tiers reflects divergence in fleet management sophistication. Cost compression in economy segments intensifies as Indian and Vietnamese assemblers localize hub motor production. Individual buyers in personal mobility segments exhibit highest price sensitivity, while logistics providers negotiating multi-year fleet contracts prioritize reliability metrics over acquisition cost.
Supply Chain Analysis
Freight cost volatility across Southeast Asian maritime corridors and overland routes from Chinese manufacturing clusters is reshaping regional assembly location decisions. Cathode material processing concentrates in China, South Korea, and Japan, with lithium carbonate and nickel sulfate drawing from Australian and Chilean extraction. Single-source vulnerability in semiconductor-based battery management systems creates qualification bottlenecks for non-Chinese OEMs. Distribution runs through authorized dealer networks in South Asian cities and direct fleet contracts in European municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as integrated battery-pack manufacturers with upstream cell control squeeze margin from modular assemblers lacking captive cathode supply.
For Market Incumbents: To counter margin erosion from Chinese cell producers with backward integration into lithium processing, Jinpeng-class manufacturers should deepen captive supply of cathode materials and pre-position certified service technicians within 50-kilometer radius of Vietnam's Ho Chi Minh City logistics corridors. India's BIS certification timelines represent a defensive moat worth extending through encrypted battery management systems that block independent refurbishment channels. For New Entrants and Emerging Players: California's Advanced Clean Trucks regulation opens a window for compliance-focused electric tricycle deployment in Los Angeles and New York logistics hubs previously served by small internal-combustion trucks. Agricultural use segments in Southeast Asian rural corridors remain underpenetrated by telematics-integrated platforms. A subscription-based energy model decoupling vehicle from battery ownership offers the most penetrable go-to-market angle for capital-constrained operators. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated battery manufacturers seeking geographic footprint expansion. The five-to-ten year viability window favors targets with MIIT catalog alignment and established service network density in South Asian Tier-2 cities. Watch for inflection when municipal low-emission zone expansions in European core cities trigger compliance-driven fleet replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Yangtze River Delta producers for Vietnam fleet deployments. |
| Backward Integration into Cathode Processing | Reduces input cost volatility for OEMs serving Indian markets under PLI scheme incentives. |
| Telematics Platform Integration | Enables predictive maintenance contracts with Delhi-NCR logistics operators demanding sub-24-hour turnaround. |
| Geographic Manufacturing Footprint | Positions assembly near Bengaluru-Tumkur corridor to compress BIS certification timelines for domestic OEMs. |
| Charging Infrastructure Partnership | Supports battery swapping networks across Philippines archipelago logistics replacing fixed-charge alternatives. |
Methodological Framework
Multi-period observation of fleet conversion rates, subsidy uptake patterns, and municipal procurement award flows anchored the trend analysis, supplemented by interviews with commercial fleet operators, battery pack procurement managers, OEM platform engineers, and aftermarket service heads. Secondary validation drew from MIIT new energy vehicle catalog updates, EPA Phase 3 regulatory filings, India's FAME-II disbursement records, and EU Green Deal procurement directive implementations. Bottom-up triangulation across vehicle registration databases and top-down reconciliation against national subsidy budgets ensured cross-verification.
Input-output matrices modeled unit shipments and value flows across product type, end user archetype, power source configuration, and technology tier dimensions throughout the forecast period. CAGRs were derived from logistic diffusion curves fitted to observed fleet replacement cycles and projected regulatory compliance deadlines. Industry-specific forecast inputs incorporated lithium-ion cell price trajectories and thermal management engineering cost curves for Southeast Asian ambient temperature applications.
The model assumes a particular technology adoption path favoring swappable battery architectures; alternative pathways for hydrogen fuel cell range extenders would alter the outlook for agricultural use segments in island-hopping networks. Forecasts reflect assumptions regarding subsidy extension continuity and low-emission zone expansion timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market