
 Electric Vehicle (EV) Fluids Market | 2026-2036
Electric Vehicle (EV) Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Fluids Market Analysis
Fleet operator procurement is rebalancing from fragmented aftermarket purchases toward consolidated long-term supply contracts with fluid manufacturers. ExxonMobil Corporation leverages its synthetic base stock infrastructure to serve high-volume thermal management contracts. Shell plc anchors European supply through integrated lubricant and coolant distribution networks.
Electric vehicle fluids encompass coolants, brake fluids, transmission fluids, and battery electrolytes formulated with low conductivity, dielectric stability, and thermal transfer coefficients tailored for electrified powertrains. These fluids manage battery cell temperatures, lubricate single-speed reduction gearboxes, and enable regenerative braking hydraulic systems in vehicles operating at voltages exceeding 400V. Coolants dominate value pools given their direct contact with battery thermal management systems, while synthetic fluid formulations capture premium positioning due to extended service intervals and compatibility with advanced polymer seals. Brake fluids for regenerative braking applications represent the fastest-growing application segment as blended friction-electric systems proliferate across OEM platforms.
EPA regulations in the United States mandate reduced toxicity profiles for coolant formulations, while REACH in Europe restricts certain glycol ether chemistries used in conventional thermal transfer fluids. China's SAMR enforces GB standards for dielectric coolant properties in domestic EV production, creating compliance thresholds for imported formulations. Stakeholders must monitor evolving battery chemistry transitions—solid-state architectures will redefine thermal management requirements and fluid specification priorities.
Market Dynamics
Fleet electrification is compressing fluid procurement timelines as commercial operators consolidate thermal management contracts around standardized dielectric coolant specifications. Battery chemistry transitions toward solid-state architectures are forcing reformulation cycles that outpace traditional automotive fluid development schedules.
Growth Catalysts
- China's dual carbon goals:NMPA thermal management standards mandate dielectric coolant upgrades across domestic EV production lines, accelerating specification harmonization.
- High-voltage platform proliferation:800V architectures require low-conductivity formulations with enhanced dielectric stability, expanding addressable formulation complexity.
- Commercial fleet electrification:Logistics operators in Germany's Stuttgart-Wolfsburg corridor are bundling coolant procurement with battery lease agreements.
Market Restraints
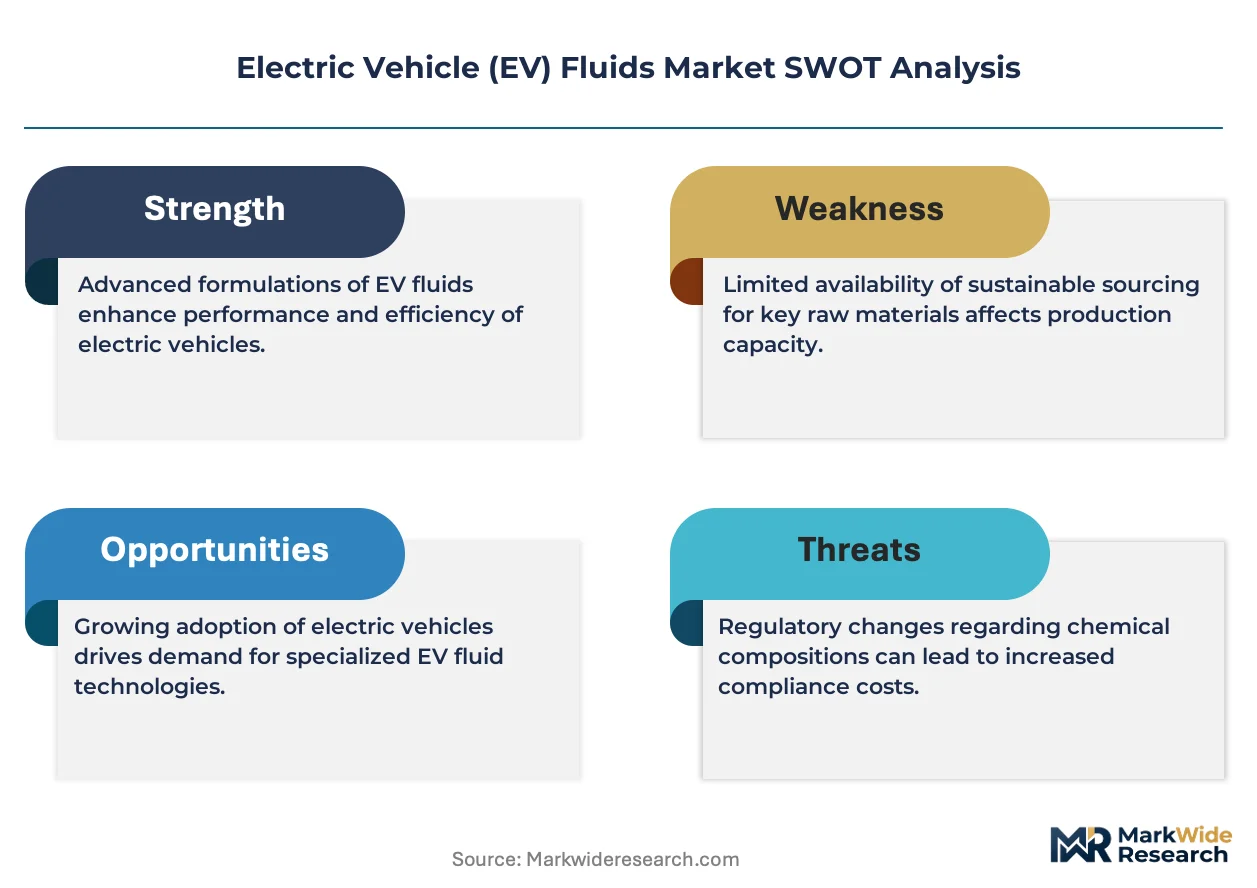
- Base stock supply concentration:Synthetic polyalphaolefin production clusters in US Gulf Coast refineries create geographic vulnerability for premium formulations.
- REACH glycol ether restrictions:ECHA limitations on conventional thermal transfer chemistries force costly reformulation of legacy coolant portfolios.
- Fluid-battery interface uncertainty:Solid-state cell architectures may eliminate direct liquid cooling, threatening long-term coolant demand assumptions.
Strategic Opportunities
- Second-life battery thermal management:Stationary energy storage deployments in India require adapted coolant specifications for degraded cell chemistries.
- Service-interval extension:Synthetic formulations with 150,000+ kilometer lifespans command premium positioning in European aftermarket channels.
- Closed-loop recycling mandates:EU F-Gas Regulation alignment creates service-contract bundling opportunities for coolant recovery and reprocessing.
Industry Challenges
- Formulation-chemistry talent scarcity:Dielectric fluid engineering expertise concentrates at specialty chemical divisions, constraining R&D scaling.
- GB standard compliance timelines:China's SAMR certification processes for imported coolant formulations extend market entry cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Fluids Market |
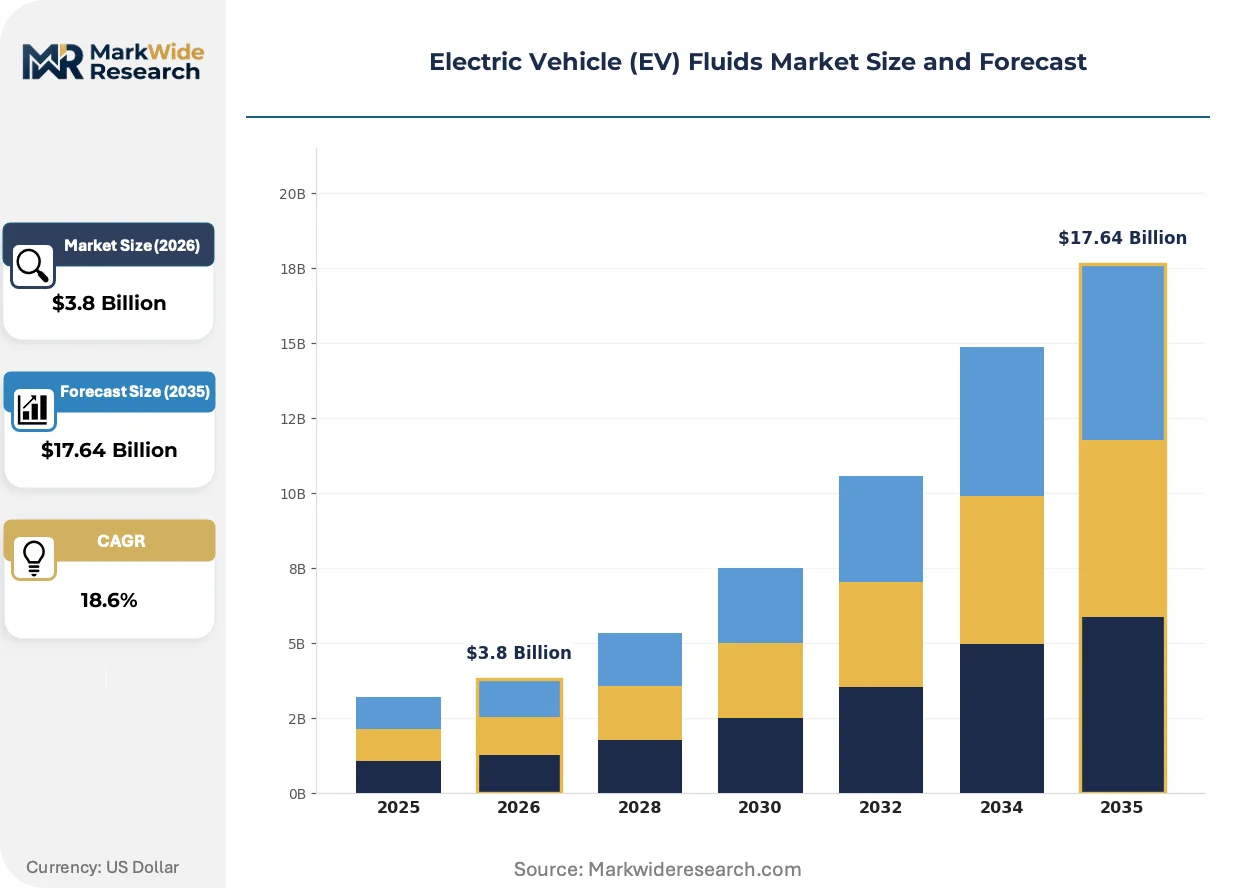
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolants, Brake Fluids, Transmission Fluids, Battery Electrolytes Application: EV Powertrain, Thermal Management, Battery Management, Regenerative Braking End User: OEMs, Aftermarket Service Providers, Fleet Operators, Consumers Material: Synthetic Fluids, Biodegradable Fluids, Water-Based Fluids, Mineral Oils |
| Companies Covered | ExxonMobil Corporation, Shell plc, BP plc, TotalEnergies SE, FUCHS SE, Valvoline Inc., Petroliam Nasional Berhad (PETRONAS), Saudi Arabian Oil Company (Saudi Aramco), ENEOS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Fluids Market Emerging Trajectories
Dielectric coolant architecture is fragmenting into application-specific modules as battery thermal management diverges across cell formats and voltage classes. Formulators are abandoning universal chemistries in favor of tailored conductivity and viscosity profiles.
Modular battery pack designs are driving fluid compartmentalization. OEMs adopting cell-to-pack architectures specify zonal coolant circuits with localized flow control. ExxonMobil's synthetic base stock infrastructure is modularizing around these discrete thermal zones, enabling faster specification matching without full platform redesigns.
REACH authorization requirements are tightening traceability for glycol ether derivatives used in conventional coolants. ECHA's sunset clause timeline is forcing reformulators to submit alternative chemistries for authorization by 2026. German OEMs are accelerating validation of polyol ester alternatives to secure supply continuity.
Fleet operators are unbundling fluid procurement from vehicle acquisition. Commercial buyers in China's Yangtze River Delta now contract coolant supply separately through third-party thermal management service providers. This disintermediation compresses margins for integrated lubricant-coolant distributors while opening direct formulation relationships.
Electric Vehicle (EV) Fluids Market Segmentation
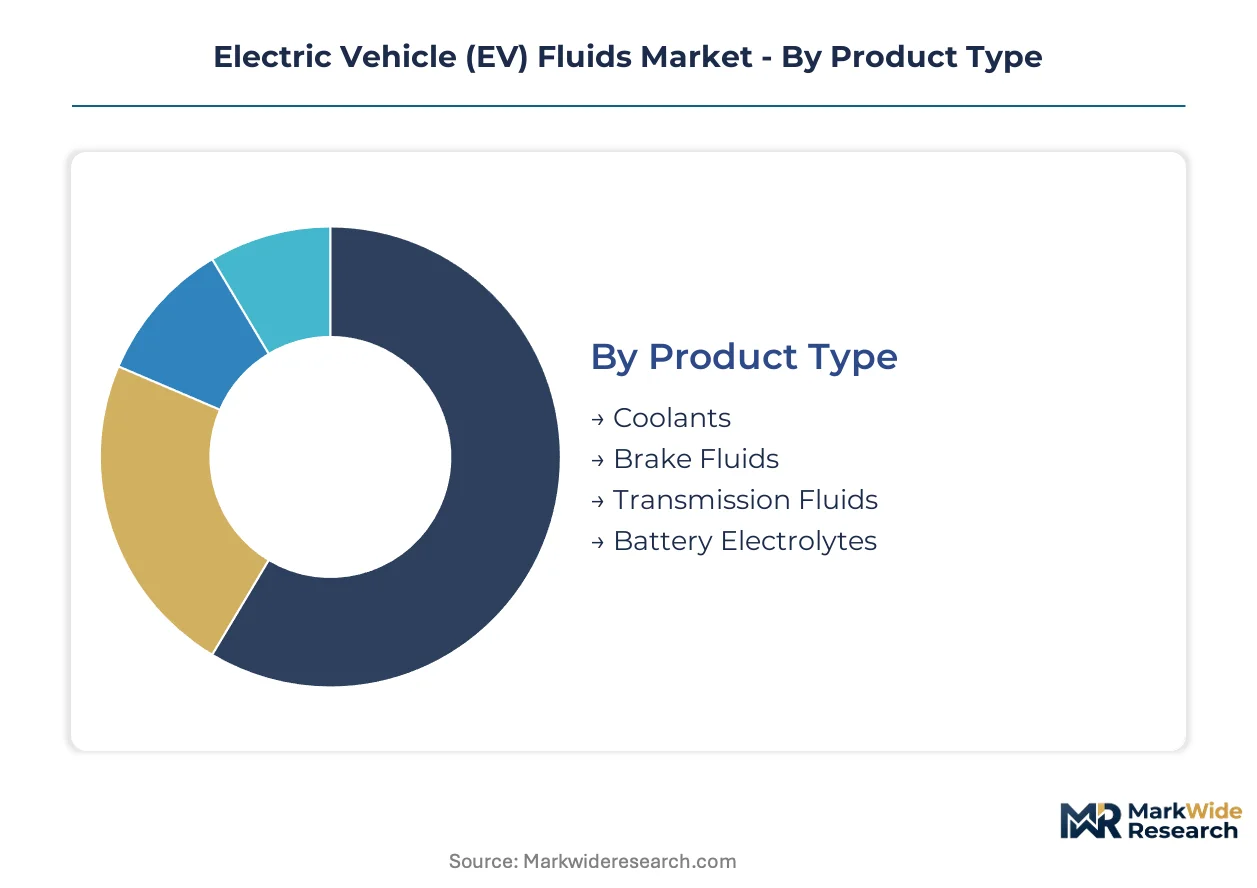
EV fluid procurement patterns diverge sharply across product categories and customer types. Fleet operators negotiate dielectric coolant contracts separately from vehicle acquisition, while OEMs bundle thermal management fluids with battery platform sourcing. Understanding these segmentation fault lines reveals where margin pools concentrate and where specification power resides.
Product Type:
Cost tier differentiation separates high-specification synthetic formulations from commodity thermal transfer fluids. Premium positioning correlates directly with voltage class and service interval requirements.
- Coolants:Dielectric thermal transfer fluids with low electrical conductivity and high specific heat capacity manage battery cell temperatures in 400V and 800V architectures. Demand concentrates in China's Yangtze River Delta manufacturing cluster, where NMPA thermal management standards mandate upgraded formulations across domestic EV production lines.
- Brake Fluids:Synthetic polyglycol-ether formulations with elevated dry and wet boiling points enable regenerative braking hydraulic systems in blended friction-electric platforms. Germany's Stuttgart-Wolfsburg automotive corridor drives specification development as KBA-type approval requirements tighten for electrified commercial vehicles.
- Transmission Fluids:Single-speed reduction gearbox lubricants with tailored viscosity profiles and polymer seal compatibility.
- Battery Electrolytes:Ion-conducting salt solutions enabling lithium-ion cell electrochemistry.
Volume sits with coolants; growth tilts toward brake fluids as blended braking systems proliferate.
Application:
Application scope determines fluid specification complexity and regulatory exposure. Direct battery contact applications face stricter dielectric property mandates than auxiliary systems.
- EV Powertrain:Combined lubrication and thermal management fluids serving electric motor bearings, inverters, and reduction gearboxes in integrated e-axle designs. Germany's commercial vehicle OEMs in Baden-Württemberg are consolidating powertrain fluid specifications across 800V platform generations.
- Thermal Management:Battery pack coolants with zonal flow control for cell-to-pack architectures. China's SAMR enforces GB standard compliance timelines that extend market entry cycles for imported formulations.
- Battery Management:Auxiliary fluids for battery state estimation and thermal runaway prevention systems.
- Regenerative Braking:Hydraulic fluids enabling kinetic energy recovery in friction-electric blended systems.
Thermal management commands the largest volume position; regenerative braking applications are climbing the fastest as electrified platforms scale.
End User:
Procurement authority fragmentation creates divergent channel economics. Direct OEM relationships favor long-term formulation partnerships, while aftermarket channels reward service-interval extension claims.
- OEMs:Original equipment manufacturers specifying fluids at platform design stage with multi-year supply agreements. China's domestic EV producers in Shenzhen and Shanghai are integrating coolant procurement with battery lease structures.
- Aftermarket Service Providers:Independent maintenance networks sourcing fluids for vehicle servicing and thermal system refurbishment. European channels prioritize synthetic formulations with 150,000+ kilometer service intervals to differentiate against mineral oil alternatives.
- Fleet Operators:Commercial buyers unbundling fluid procurement from vehicle acquisition through third-party thermal management contracts.
- Consumers:Individual vehicle owners purchasing replacement fluids through retail and authorized service channels.
OEMs anchor current volume; fleet operators are gaining share fastest as commercial electrification accelerates contract consolidation.
Material:
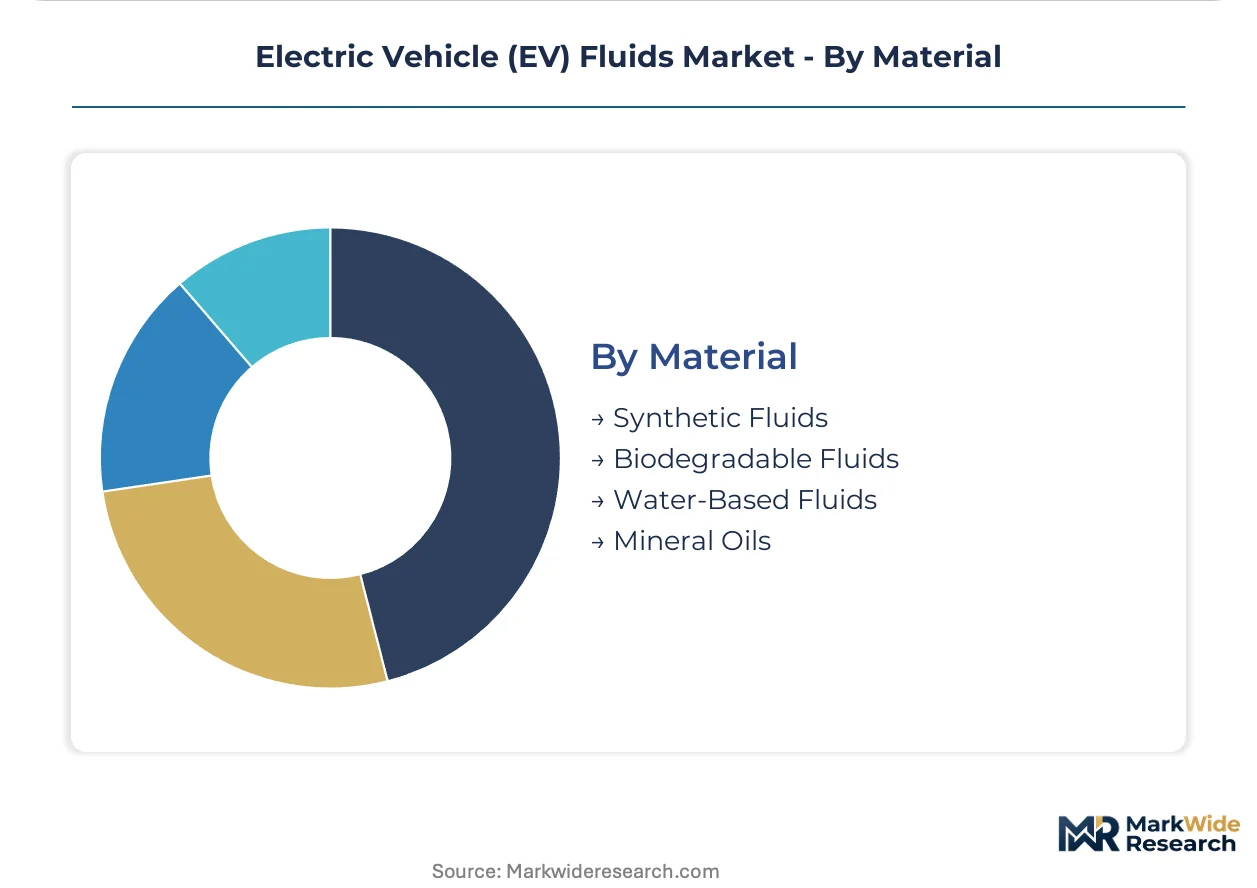
Base stock chemistry determines performance ceiling and regulatory compliance pathway. Synthetic routes command premium positioning against constrained mineral oil and emerging biodegradable alternatives.
- Synthetic Fluids:Polyalphaolefin and polyol ester base stocks engineered for dielectric stability, thermal oxidative resistance, and extended drain intervals. US Gulf Coast refineries concentrate polyalphaolefin production, creating geographic supply vulnerability for premium formulations.
- Biodegradable Fluids:Ester-based formulations meeting OECD 301 biodegradability criteria for environmentally sensitive applications. EU F-Gas Regulation alignment in Germany and France is creating service-contract bundling opportunities for coolant recovery and reprocessing.
- Water-Based Fluids:Glycol-water mixtures for cost-sensitive thermal management applications with moderate dielectric requirements.
- Mineral Oils:Petroleum-derived base stocks constrained by conductivity limitations in high-voltage applications.
Synthetics dominate value capture; biodegradable alternatives are expanding most quickly under tightening EU environmental mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyalphaolefin base stock production concentrates along the US Gulf Coast, anchoring supply security calculations for premium synthetic formulations. Battery thermal management demand clusters in three manufacturing corridors where OEMs and regulators are accelerating specification upgrades.
United States
EPA toxicity mandates for coolant formulations are tightening as 800V platform deployment accelerates across Michigan and Ohio assembly plants. Gulf Coast refineries supply synthetic base stocks to formulators serving Detroit's electrified truck programs. Thermal management contracts for commercial fleets are consolidating around dielectric specifications validated by the Department of Energy's national laboratories.
Germany
KBA-type approval requirements for electrified commercial vehicles are driving brake fluid specification upgrades in Baden-Württemberg. Stuttgart-Wolfsburg OEM corridors are bundling coolant procurement with battery lease structures for logistics operators. REACH authorization timelines for glycol ether alternatives are compressing reformulation cycles at specialty chemical divisions.
China
NMPA thermal management standards and dual carbon goals are mandating dielectric coolant upgrades across Shenzhen and Shanghai production lines. SAMR enforces GB standard compliance timelines that extend market entry cycles for imported formulations by 18-24 months. Yangtze River Delta manufacturing clusters are integrating fluid procurement with domestic battery platform sourcing.
Japan
METI guidelines for high-voltage vehicle safety are shaping thermal management fluid specifications for Tokyo-based OEMs. ENEOS Corporation's synthetic base stock infrastructure serves domestic 800V platform development programs. Kanto region battery manufacturers are validating coolant formulations for solid-state cell architectures.
India
CEA technical standards for stationary energy storage are creating adapted coolant specifications for second-life battery deployments in Gujarat and Maharashtra. BIS certification processes for thermal management fluids are aligning with automotive electrification targets under the PLI scheme. Tamil Nadu manufacturing corridors are attracting formulators serving export-oriented EV component production.
Electric Vehicle (EV) Fluids Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable and service-interval extension specializations. The vendor base stratifies across integrated petroleum majors, independent lubricant specialists, and regional chemical formulators. Three archetypes dominate: synthetic base stock owners with refining integration, formulation specialists with OEM approval relationships, and regional distributors with fleet service contracts. Competitive moves concentrate on backward integration into base stock production and technology licensing for solid-state-compatible chemistries.
Among petroleum majors with integrated refining positions, ExxonMobil Corporation and Shell plc exemplify the synthetic infrastructure archetype, while BP plc occupies a position within the energy-transition pivot tier. These entities anchor supply relationships through captive base stock production and established OEM validation pathways rather than through formulation novelty alone.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BP plc |
| TotalEnergies SE |
| FUCHS SE |
| Valvoline Inc. |
| Petroliam Nasional Berhad (PETRONAS) |
| Saudi Arabian Oil Company (Saudi Aramco) |
| ENEOS Corporation |
| Others |
Supply Flow & Price Mechanics
Synthetic-commodity fluid bifurcation separates dielectric coolants validated for 800V architectures from mineral-oil thermal transfer fluids, with that performance gap manifesting in OEM contract premiums and Gulf Coast base stock allocation priorities. Price differentiation reflects dielectric stability certification tiers under China's GB standards and EPA toxicity mandates, while procurement consolidation by fleet operators compresses margins on unbundled aftermarket sales.
Pricing Analysis
Warranty-bundled coolant supply contracts now dominate OEM channel economics, while unbundled aftermarket purchases concentrate price competition. Three-tier pricing structure across premium synthetic, mid-grade polyol ester, and economy mineral oil levels correlates with voltage class and service interval claims. Cost compression in the economy tier stems from REACH-driven glycol ether reformulation expenses passed to formulators. Fleet operators exhibit highest price sensitivity due to volume procurement leverage, while OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Polyalphaolefin base stock supply rests on US Gulf Coast refineries, South Korean petrochemical complexes, and Japanese synthetic lubricant producers. Formulators draw from specialty chemical feedstocks including ethylene oxide derivatives, fluorinated compounds, and high-purity glycol ethers. Single-source vulnerability concentrates in US polyalphaolefin capacity given hurricane exposure and export logistics constraints. Distribution runs through integrated lubricant-coolant distributors serving OEM assembly plants and third-party thermal management service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic base stock capacity constraints prop pricing power for integrated producers, with polyalphaolefin production bottlenecks at Gulf Coast refineries limiting supply elasticity against accelerating 800V platform demand.
For Market Incumbents: Anticipate solid-state battery thermal management obsolescence risk by diversifying into second-life stationary storage coolant specifications and service-interval extension formulations. Secure backward integration into biodegradable ester base stocks ahead of EU F-Gas Regulation enforcement. Channel control through direct fleet operator relationships offers defensive positioning against disintermediation. For New Entrants and Emerging Players: Direct digital procurement platforms targeting India's second-life battery thermal management segment offer lowest competitive density. India's CEA technical standards for stationary energy storage create specification entry points without incumbent OEM validation barriers. Biodegradable fluid formulations for European aftermarket channels provide the most penetrable white space given REACH authorization timelines forcing incumbent reformulation. For Investors and Strategic Acquirers: Re-rating potential sits with specialty chemical formulators holding SAMR GB standard pre-approvals given China's 18-24 month certification bottlenecks. Long-term viability over a multi-year window favors entities with synthetic base stock ownership and solid-state-compatible chemistry pipelines. The signal to watch is OEM announcements of cell-to-pack architecture adoption eliminating direct liquid cooling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Stocks | Captive polyalphaolefin supply secures margin control against Gulf Coast concentration risk. |
| GB Standard Pre-Certification Investment | SAMR compliance timelines create 18-24 month moats for approved imported formulations. |
| Second-Life Battery Coolant Development | CEA technical standards for stationary storage open adapted specification revenue streams. |
| Biodegradable Formulation Transition | EU F-Gas Regulation alignment enables service-contract bundling for recovery and reprocessing. |
| Fleet Operator Direct Contracting | Unbundled procurement trends favor bypassing integrated distributor margin capture. |
Methodological Framework
Multi-period observation of NMPA thermal management standard implementations, REACH authorization timelines, and fleet procurement contract structures anchored the trend analysis, supplemented by interviews with synthetic base stock procurement leads at Gulf Coast refineries, thermal management fluid R&D directors at specialty chemical divisions, OEM platform engineers specifying 800V architectures, and aftermarket service network procurement managers. Secondary validation drew from EPA toxicity mandate filings, ECHA sunset clause documentation, SAMR GB standard publications, and customs trade data on polyalphaolefin imports. Bottom-up volume builds across product categories triangulated against top-down market sizing from automotive production forecasts.
Segment-weighting approaches distributed value across coolant, brake fluid, transmission fluid, and battery electrolyte categories proportional to thermal management system content per vehicle and service interval frequency. Modeled dimensions included voltage class architecture, base stock chemistry tier, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating fleet electrification penetration rates and solid-state battery commercialization scenarios across the projection horizon. Industry-specific inputs captured dielectric conductivity specification evolution and reformulation cycle compression under REACH authorization pressure.
The model holds under continued liquid cooling dominance in battery thermal management; deviation in solid-state commercialization timelines or direct cooling elimination would shift coolant demand assumptions materially. Forecasts embed assumptions regarding NMPA enforcement consistency, ECHA authorization grant rates, and Gulf Coast base stock capacity expansion plans. A small set of named triggers—solid-state OEM platform announcements, SAMR import certification backlog changes, and REACH alternative chemistry authorization decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Used EV Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Automotive Electric Vehicle Power System Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market