
 United States Electric Pick-Up Trucks Market | 2026-2036
United States Electric Pick-Up Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Pick-Up Trucks Market Analytics
A capital-intensity divergence between legacy automakers and EV-native startups is redrawing competitive boundaries in the United States electric pick-up trucks landscape. Ford Motor Company leverages its Dearborn manufacturing complex and F-150 Lightning platform to sustain volume production at scale. Rivian Automotive Inc. anchors its position through proprietary drive-unit architecture and direct-to-consumer distribution. Tesla competes via its integrated battery cell format and Supercharger network access.
United States electric pick-up trucks are heavy-duty vehicles propelled by battery-electric, plug-in hybrid, or fuel cell powertrains, typically offering payload capacities exceeding 1,500 pounds and tow ratings above 7,500 pounds, designed for commercial hauling and personal utility applications. Battery electric configurations currently dominate segment revenue due to declining lithium-ion cell costs and expanding DC fast charging corridors along interstate corridors. Commercial fleets represent the fastest-growing end user category as total cost of ownership advantages materialize across high-mileage duty cycles. Vehicle-to-grid technology sits at an emerging margin pool, enabling fleet operators to monetize bidirectional power discharge during peak grid demand periods.
The EPA enforces Corporate Average Fuel Economy standards that ratchet down allowable fleet emissions, while NHTSA administers Federal Motor Vehicle Safety Standards governing crashworthiness and battery enclosure integrity for electrified platforms. The Inflation Reduction Act's commercial clean vehicle tax credits directly alter procurement economics for fleet buyers qualifying under domestic content assembly requirements. Stakeholders must monitor how NHTSA's evolving autonomous vehicle framework intersects with state-level deployment permissions, as hands-free highway operation becomes a decisive specification differentiator in commercial fleet tenders.
Market Dynamics
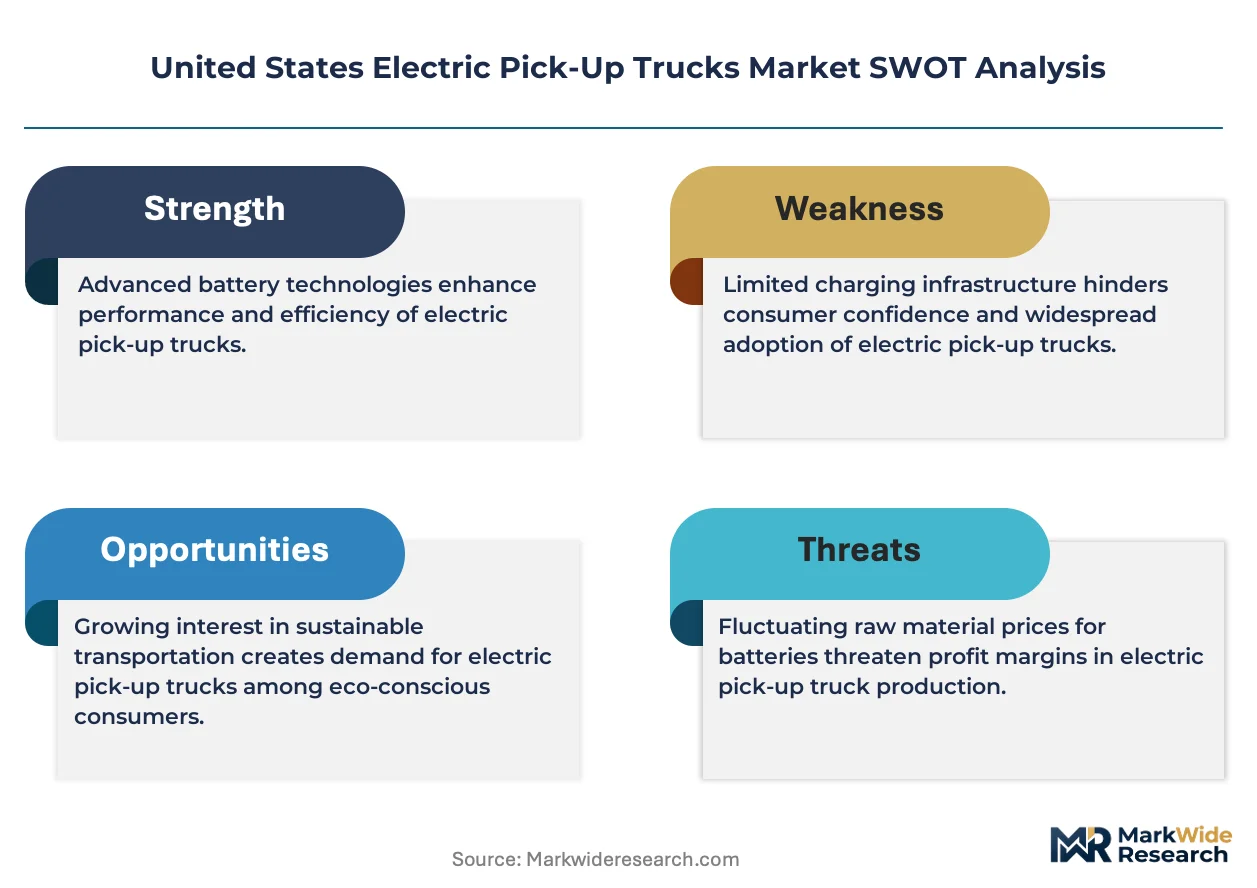
California's Advanced Clean Trucks regulation is compressing electrification timelines for legacy manufacturers, forcing platform redesigns and battery supply reconfiguration before the 2035 model-year cutoff.
Growth Catalysts
- EPA tailpipe standards:The Environmental Protection Agency's tightening Corporate Average Fuel Economy mandates eliminate compliance pathways for internal combustion engines in light-duty segments. Fleet operators face penalties that accelerate battery-electric procurement.
- Texas energy sector demand:Oilfield services and utility maintenance fleets in the Permian Basin and Gulf Coast corridor are replacing diesel work trucks with electric equivalents to meet corporate decarbonization commitments and access state infrastructure incentives.
- Lithium iron phosphate chemistry:Cell format migration from nickel-cobalt-manganese to LFP architectures is reducing pack costs and thermal runaway risk, enabling OEMs to offer base-model electric trucks at price parity with combustion equivalents.
Market Restraints
- Charging infrastructure gaps:Rural interstate corridors and worksite locations lack 350kW DC fast charging density, constraining fleet deployment outside urban freight hubs and limiting range confidence for commercial buyers.
- Domestic battery supply concentration:Cell and pack assembly capacity clusters in Nevada, Michigan, and Tennessee, creating geographic mismatch with Texas and Florida demand centers and inflating logistics costs for eastern seaboard deliveries.
- Grid interconnection queues:Utility-scale fleet depot charging installations face 18-36 month interconnection delays in PJM and ERCOT territories, deferring operational cost savings and complicating total cost of ownership calculations.
Strategic Opportunities
- Vehicle-to-grid monetization:Bidirectional charging protocols enable fleet operators to discharge stored energy during ISO-New England and CAISO peak demand events, generating ancillary revenue streams that improve payback periods.
- Last-mile delivery electrification:E-commerce fulfillment centers in Ohio, Pennsylvania, and Georgia are specifying electric light-duty trucks for urban route density, opening volume contracts absent from traditional construction and agriculture segments.
- Inflation Reduction Act commercial credits:The Treasury Department's domestic content assembly requirements alter procurement economics for municipal and corporate fleets, favoring trucks assembled in Michigan, Tennessee, and Texas over imported alternatives.
Industry Challenges
- High-voltage technician shortage:Fleet maintenance departments lack certified electricians capable of battery pack diagnostics and inverter repair, forcing reliance on OEM service networks and extending vehicle downtime.
- NHTSA battery enclosure certification:Crashworthiness testing for electrified platforms requires 18-24 month validation cycles, compressing model-year launch windows and limiting mid-cycle powertrain updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Pick-Up Trucks Market |
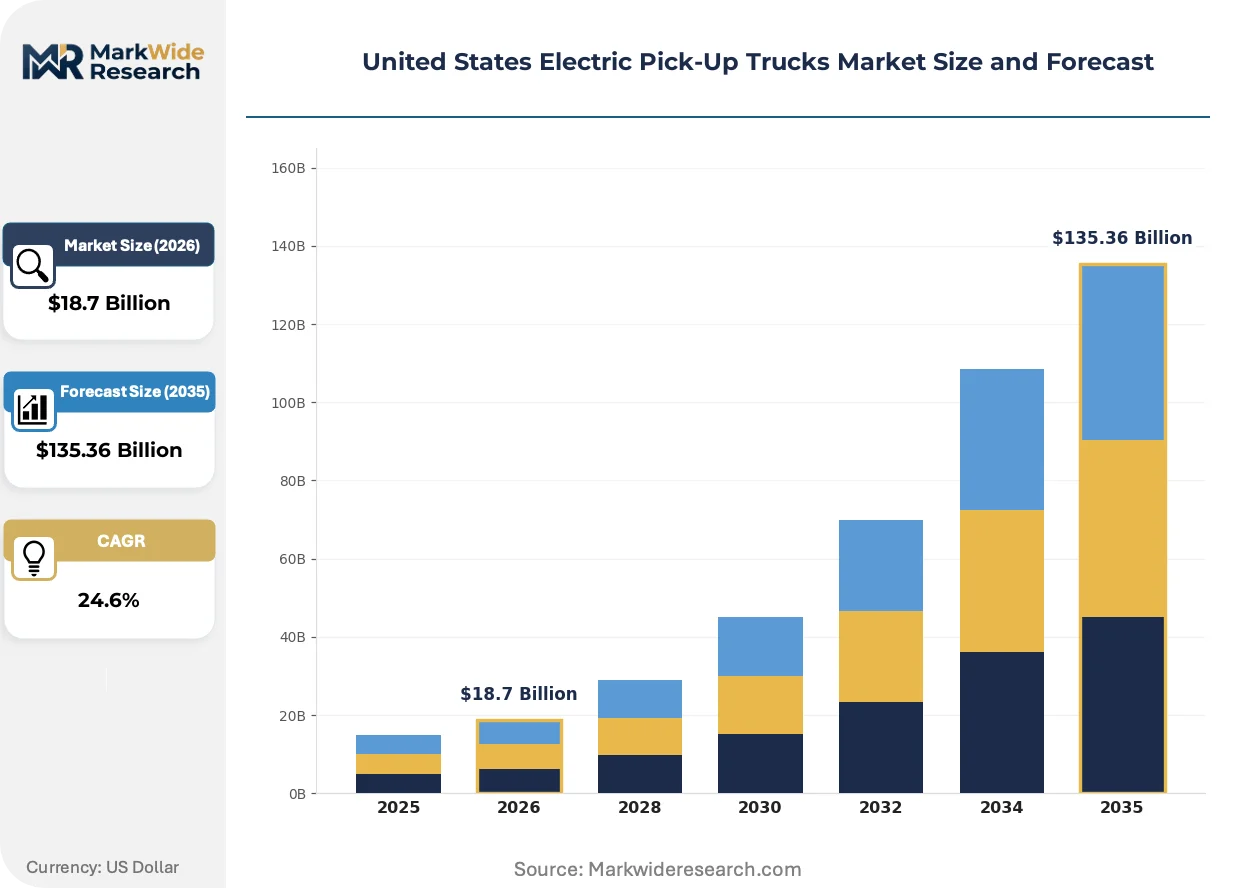
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric, Plug-in Hybrid, Fuel Cell, Extended Range End User: Commercial Fleets, Personal Users, Government Agencies, Construction Firms Technology: Fast Charging, Regenerative Braking, Vehicle-to-Grid, Autonomous Driving Distribution Channel: Direct Sales, Online Retail, Dealerships, Auctions |
| Companies Covered | Ford Motor Company, General Motors Company, Rivian Automotive Inc., Tesla, Canoo Inc., GMC, Chevrolet, Toyota Motor Corporation, Mercedes Benz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Pick-Up Trucks Market Evolving Landscape
Powertrain architecture convergence and charging protocol standardization are compressing development cycles for electric work trucks, while procurement models shift from unit sales to total-cost contracting.
800-volt electrical architectures are displacing 400-volt systems as the baseline for next-generation electric trucks. Fleet operators operating high-mileage duty cycles in Arizona and Nevada are specifying 800-volt platforms to enable 350kW charging rates that compress midday recharging windows. This voltage migration is compressing the competitive window for first-generation electric truck platforms that launched on 400-volt topologies.
The Inflation Reduction Act's domestic content bonus credit is restructuring supply chain geography. Battery cell and module assembly must occur in North America to qualify for the full commercial clean vehicle credit, compelling OEMs to reconfigure procurement contracts with Korean and Japanese cell suppliers. Michigan and Tennessee assembly plants are capturing disproportionate allocation as manufacturers race to satisfy Treasury Department traceability requirements before the 2024 tax year.
Fleet procurement departments are consolidating vendor relationships around full-service mobility contracts. Large logistics operators in California and Texas are unbundling vehicle acquisition from charging infrastructure, maintenance, and energy management, awarding integrated contracts to OEM-affiliated service entities. This bundling is marginalizing independent dealerships and compressing aftermarket parts margins for traditional service networks.
United States Electric Pick-Up Trucks Market Segmentation
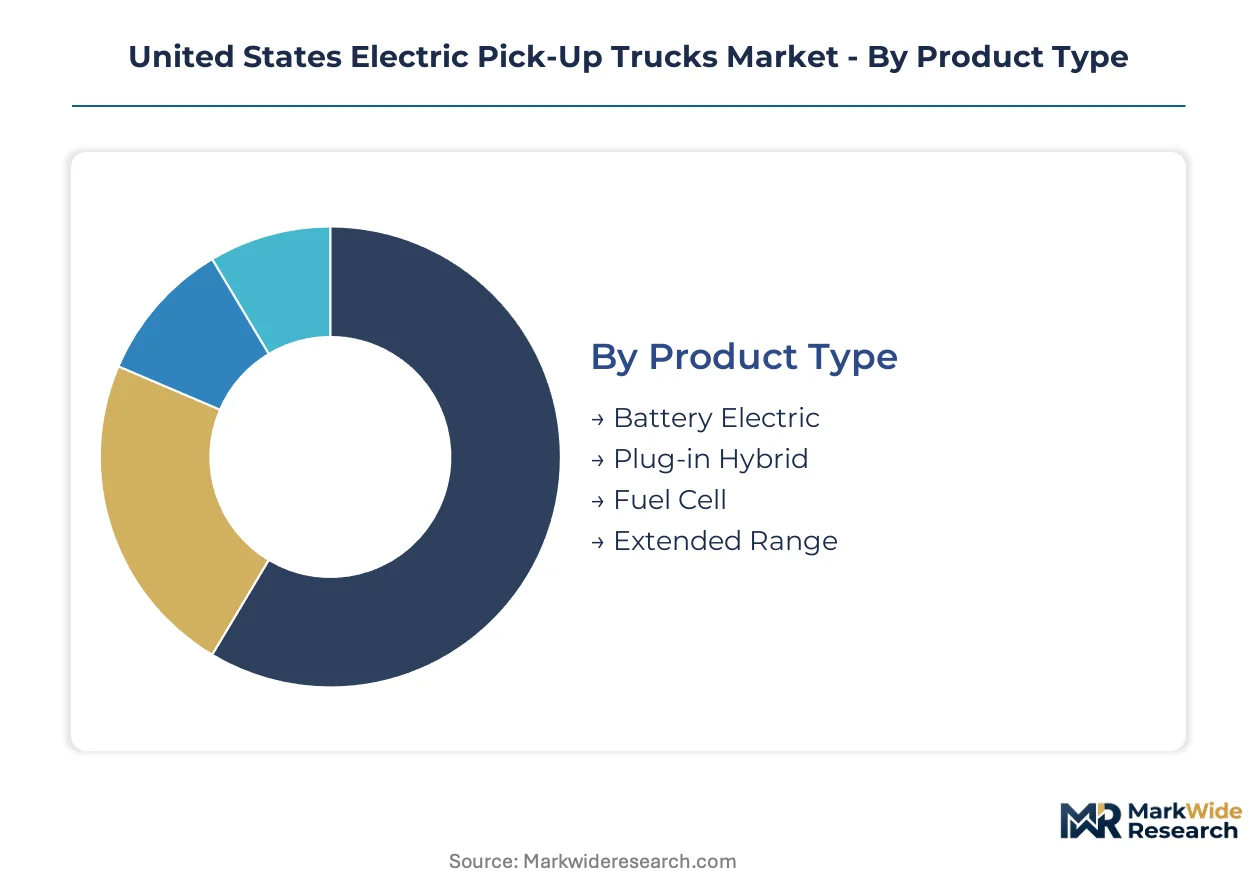
Segmentation in the United States electric pick-up trucks market reveals divergent procurement patterns across powertrain architectures and buyer categories. Fleet operators prioritize total cost of ownership metrics while personal buyers emphasize range confidence and charging access. Technology adoption curves vary sharply between commercial and consumer segments.
Product Type:
Battery electric configurations dominate domestic assembly lines serving fleet renewal programs, while plug-in hybrid variants retain export relevance for markets with sparse charging infrastructure.
- Battery Electric:Lithium-ion cell packs deliver zero tailpipe emissions and qualify for the full Inflation Reduction Act commercial credit. Texas energy-sector fleets in the Permian Basin are accelerating procurement to meet corporate decarbonization timelines and access state infrastructure incentives.
- Plug-in Hybrid:Combustion-electric dual powertrains offer range-extended operation for rural contractors lacking depot charging. Demand concentrates in Montana and Wyoming where 350kW corridor density remains insufficient for pure battery operation.
- Fuel Cell:Hydrogen fuel cell stacks target heavy towing applications in California's Central Valley agricultural corridors.
- Extended Range:Onboard gasoline generators eliminate range anxiety for cross-state haulers in the Mountain West.
Battery Electric holds the largest share; momentum sits with Extended Range configurations bridging infrastructure gaps.
End User:
Procurement scale separates volume buyers from fragmented retail demand, with tax credit eligibility reshaping customer mix.
- Commercial Fleets:High-mileage logistics and utility operators achieve payback through reduced fuel and maintenance expenditures. E-commerce fulfillment centers in Ohio and Pennsylvania are specifying electric light-duty trucks for urban route density.
- Personal Users:Individual buyers in suburban Texas and Florida markets respond to state-level EV rebates and home charging installation subsidies.
- Government Agencies:Municipal procurement in California and New York follows state fleet electrification mandates.
- Construction Firms:Site contractors in Arizona and Nevada demand vehicle-to-grid capability for equipment power take-off.
Commercial Fleets anchor volume; Personal Users are climbing the fastest as price parity with combustion equivalents materializes.
Technology:
Feature bundling separates premium configurations from base models, with fleet tenders specifying bidirectional power protocols.
- Fast Charging:800-volt architectures enable 350kW DC replenishment compressing midday downtime for Arizona and Nevada high-mileage operators.
- Regenerative Braking:Kinetic energy recovery systems extend urban range for last-mile delivery routes in Atlanta and Dallas metropolitan zones.
- Vehicle-to-Grid:Bidirectional discharge protocols allow ISO-New England and CAISO grid participation generating ancillary revenue.
- Autonomous Driving:Hands-free highway operation features differentiate commercial fleet tenders as NHTSA frameworks evolve.
Fast Charging commands specification priority; Vehicle-to-Grid delivers the steepest expansion trajectory as grid interconnection queues lengthen.
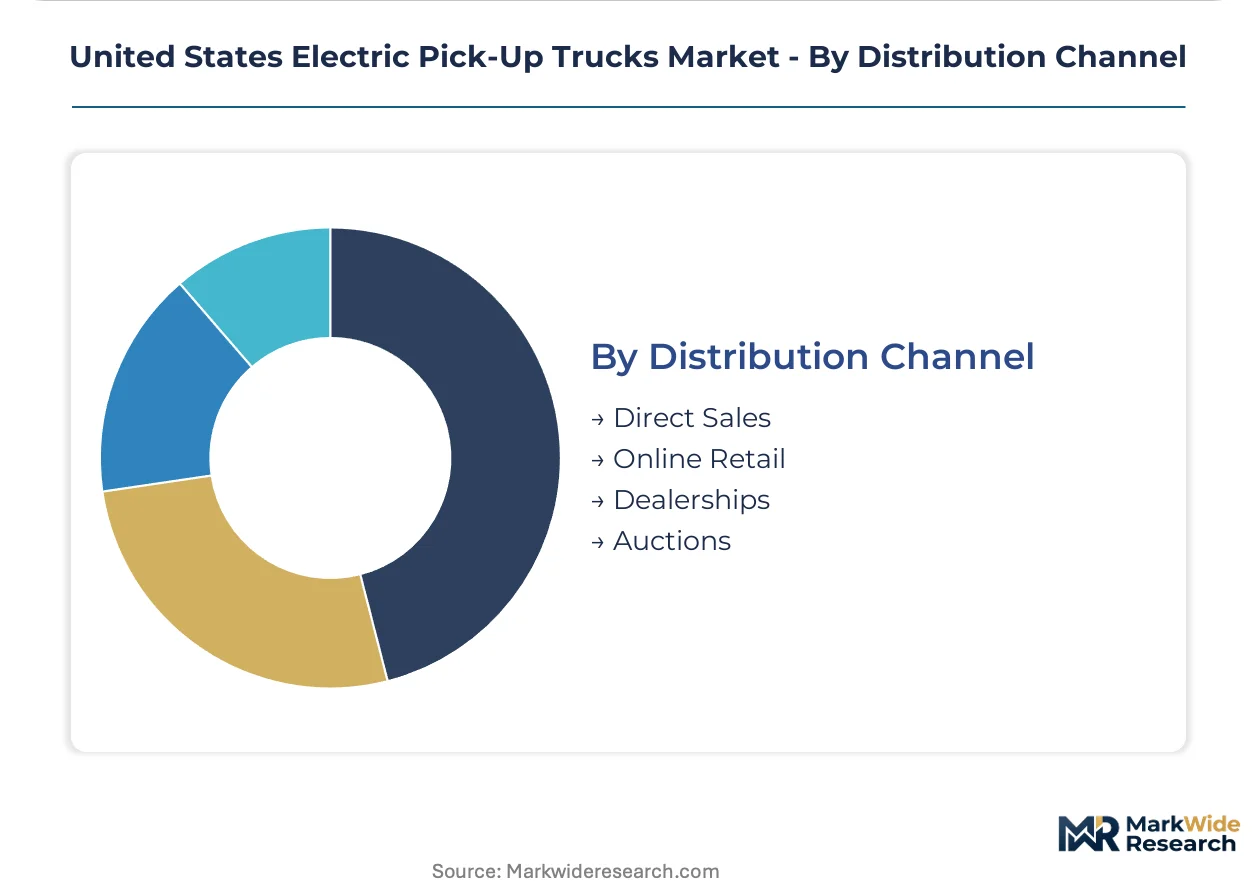
Distribution Channel:
Channel selection reflects buyer scale and service integration requirements, with integrated mobility contracts displacing traditional retail.
- Direct Sales:Manufacturer-owned channels capture fleet procurement departments consolidating vendor relationships around full-service contracts. California and Texas logistics operators unbundle vehicle acquisition from charging infrastructure and maintenance.
- Dealerships:Franchise networks retain personal buyer traffic in suburban markets requiring localized service access.
- Online Retail:Digital configurators serve tech-forward consumers in Seattle and Austin metropolitan areas.
- Auctions:Secondary market disposal channels manage fleet rotation for municipal and corporate vehicle pools.
Direct Sales holds the largest share; Online Retail is gaining share fastest among younger demographic cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands premium pricing leverage over Michigan due to concentrated energy-sector fleet demand and state infrastructure subsidies, while California's regulatory mandates compress procurement timelines regardless of cost position.
Texas
Oilfield services and utility maintenance fleets in the Permian Basin and Gulf Coast corridor drive replacement of diesel work trucks with electric equivalents. The Texas Commission on Environmental Quality administers grants for zero-emission vehicle infrastructure through the Texas Emissions Reduction Plan. Houston anchors deployment clusters where corporate decarbonization commitments intersect with state-level EV incentives.
California
Municipal procurement departments and logistics operators accelerate electrification to meet fleet mandates ahead of the 2035 model-year cutoff. The California Air Resources Board enforces Advanced Clean Trucks regulation requiring increasing percentages of zero-emission vehicle sales. The Central Valley agricultural corridor concentrates fuel cell pilot programs for heavy towing applications.
Michigan
Assembly plant proximity to battery cell manufacturing in Nevada and domestic content assembly requirements attract fleet procurement from municipal and corporate buyers. The Michigan Department of Transportation coordinates with EPA on corridor charging infrastructure deployment along interstate highways. Detroit metropolitan area facilities capture disproportionate allocation as manufacturers satisfy Treasury Department traceability requirements.
Ohio
E-commerce fulfillment centers in Columbus and Cleveland metropolitan zones specify electric light-duty trucks for urban route density. The Ohio Environmental Protection Agency administers diesel emission reduction grants convertible to electric vehicle procurement. The I-70/I-71 freight corridor concentrates last-mile delivery electrification contracts absent from traditional construction segments.
Florida
Suburban personal buyers respond to state-level EV rebates and home charging installation subsidies in Miami and Tampa metropolitan markets. The Florida Department of Transportation allocates federal infrastructure funds to DC fast charging density along interstate corridors. Orlando anchors tourism-sector fleet trials for hotel and rental car electrification programs.
United States Electric Pick-Up Trucks Market Competitive Landscape
Concentration sits with legacy automakers possessing established manufacturing infrastructure and fleet service networks. The competitive structure divides between Detroit-based volume manufacturers, California-Texas EV-native startups, and premium European entrants testing market viability. Strategic archetypes include platform-scale incumbents leveraging existing dealer relationships, direct-to-consumer specialists controlling distribution economics, and technology-integrated players bundling charging infrastructure. Dominant competitive moves center on backward integration into battery cell supply and geographic consolidation of assembly capacity to satisfy domestic content requirements.
Among Detroit-based volume manufacturers, Ford Motor Company and General Motors Company exemplify platform-scale incumbents with established fleet service networks and multi-state assembly presence. Rivian Automotive Inc. and Tesla occupy positions within the EV-native specialist tier, representing direct-to-consumer distribution models and integrated technology architectures. Toyota Motor Corporation anchors the diversified multinational archetype, bringing hybrid-electric expertise and established dealer infrastructure to segment entry timing decisions.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors Company |
| Rivian Automotive Inc. |
| Tesla |
| Canoo Inc. |
| GMC |
| Chevrolet |
| Toyota Motor Corporation |
| Mercedes Benz |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between cell suppliers and OEMs lock in lithium iron phosphate cathode supply and compress price volatility for fleet buyers qualifying under Treasury Department domestic content rules. These arrangements tether procurement economics to Nevada and Tennessee assembly plant output, binding price visibility to geographic concentration of pack production.
Pricing Analysis
Customization-premium spreads separate configured-to-order fleet specifications from standard retail configurations. Three-tier pricing structure across premium, standard, and economy levels tracks battery chemistry grade and vehicle-to-grid certification tier. Cost compression in base-model LFP configurations is intensifying because Korean and Japanese cell suppliers renegotiate North American assembly contracts. Commercial fleet procurement departments exhibit lowest price sensitivity due to total cost of ownership modeling, while personal buyers in Florida and Texas markets remain most responsive to state rebate thresholds.
Supply Chain Analysis
Nevada-Tennessee battery pack assembly chokepoints constrain eastern seaboard delivery timelines and inflate logistics costs for Ohio and Pennsylvania fleet deployments. Domestic cell production draws from Chilean lithium, Australian spodumene, and Indonesian nickel feedstocks. Single-source vulnerability concentrates in Korean cathode active material supply. Distribution runs through OEM-affiliated service entities consolidating vehicle acquisition with charging infrastructure and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement cycles track energy-sector capital expenditure patterns, positioning the market for cyclical recovery as Permian Basin operators renew work truck inventories. The Inflation Reduction Act commercial credit phase-in provides demand floor visibility through the mid-decade.
For Market Incumbents: Secure captive lithium iron phosphate cell supply through joint venture structures in Nevada and Tennessee to defend against EV-native entrants importing Asian-assembled packs. Lock in fleet service network capacity ahead of NHTSA battery enclosure certification backlogs. Prioritize 800-volt platform standardization to compress development cycles for derivative commercial variants. For New Entrants and Emerging Players: Anchor in last-mile delivery electrification contracts with Ohio and Pennsylvania e-commerce fulfillment centers, the most penetrable segment absent entrenched legacy service relationships. Target construction firm segments in Arizona and Nevada demanding vehicle-to-grid capability for equipment power take-off. Pursue direct-to-fleet distribution bypassing franchise dealership networks. For Investors and Strategic Acquirers: Capital is best deployed toward cell-to-vehicle integrated specialists with Treasury Department traceability compliance and ISO-New England grid interconnection queue positioning. Long-term viability favors archetypes controlling upstream cathode active material refining and downstream fleet energy management contracts. Watch ERCOT and PJM interconnection approval velocity as inflection indicator for depot charging infrastructure deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in LFP cell allocation from Nevada assembly plants for fleet qualification under IRA domestic content rules. |
| Charging Infrastructure Partnership | Accelerates 350kW corridor deployment along Texas interstate highways serving Permian Basin energy-sector fleets. |
| Platform Standardization | Enables 800-volt architecture migration compressing midday recharging windows for Arizona high-mileage operators. |
| Software-Defined Vehicle Investment | Supports NHTSA autonomous vehicle framework compliance for hands-free highway operation in commercial tenders. |
| Geographic Manufacturing Footprint | Consolidates assembly in Michigan and Tennessee to satisfy Treasury Department traceability requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, NHTSA safety standard databases, and Treasury Department credit guidance documents. Interviews with OEM platform engineers, fleet procurement directors, utility interconnection planners, and battery cell manufacturing executives inform demand and supply assumptions. Vehicle production databases and state-level EV registration records provide volume anchors. Bottom-up fleet procurement modeling triangulates against top-down regulatory mandate trajectory analysis.
Segmentation dimensions modeled span propulsion architecture, end-user category, and technology feature bundling across the projection horizon. Powertrain mix shares derive from state-level regulatory compliance pathway analysis. Battery chemistry adoption curves incorporate cathode cost forecasts and thermal runaway risk assessments. CAGRs reflect compounded annual growth across high-mileage fleet replacement cycles and personal buyer price parity thresholds.
Decision-makers should treat outputs as directional under IRA credit continuity and NERC grid reliability assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EPA tailpipe standard stringency and state-level infrastructure incentive durability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
US Electric Bus Battery Pack Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Electric Bicycle Market