
 Electric Transporters Market | 2026-2036
Electric Transporters Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Transporters Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is shifting the cost-of-entry calculus for commercial fleet operators. This regulation compels companies to report on supply chain emissions, which directly impacts logistics choices for last-mile delivery. Segway Ninebot specializes in personal mobility solutions tailored for urban commuters. In contrast, BYD leverages its extensive battery manufacturing capabilities to control costs across its portfolio of electric mopeds and scooters.
Electric transporters are battery-powered vehicles engineered for personal and light commercial transport, often featuring motors ranging from 250W to 4000W. Their core function is to offer a low-emission alternative for short-distance travel in cities, on campuses, and within large commercial facilities. Electric scooters and bicycles represent the largest volume within the personal mobility application. The underlying shift to Lithium-Ion battery technology from legacy lead-acid chemistries defines technical progress and sets new performance standards.
A fragmented regulatory environment shapes market access and product specifications. In the United States, EPA standards indirectly encourage the transition to electric options, while China's dual carbon goals directly accelerate adoption. Concurrently, CE marking in Europe is mandatory for ensuring product safety and environmental compliance. The critical challenge for manufacturers is balancing the development of global vehicle platforms against the need to adapt designs to meet disparate municipal regulations on speed, power, and road access.
Market Dynamics
The central force shaping the market is the conflict between manufacturers' pursuit of standardized global vehicle platforms and the fragmented, often municipal-level, regulations governing speed, power, and road access in key urban centers.
Growth Catalysts
- Policy Acceleration:China's dual carbon goals directly incentivize micro-mobility adoption in dense urban centers, accelerating the replacement of combustion-engine scooters.
- Last-Mile Delivery Growth:E-commerce expansion creates persistent demand for efficient vehicles in final-stage logistics, a core application for electric cargo bikes and scooters.
- Battery Technology Advancement:The shift to Lithium-Ion and solid-state chemistries improves vehicle range and charging speed, unlocking new performance tiers and use cases.
Market Restraints
- Regulatory Fragmentation:A patchwork of municipal rules on speed, motor power, and road access creates high compliance costs and prevents economies of scale from standardized vehicle designs.
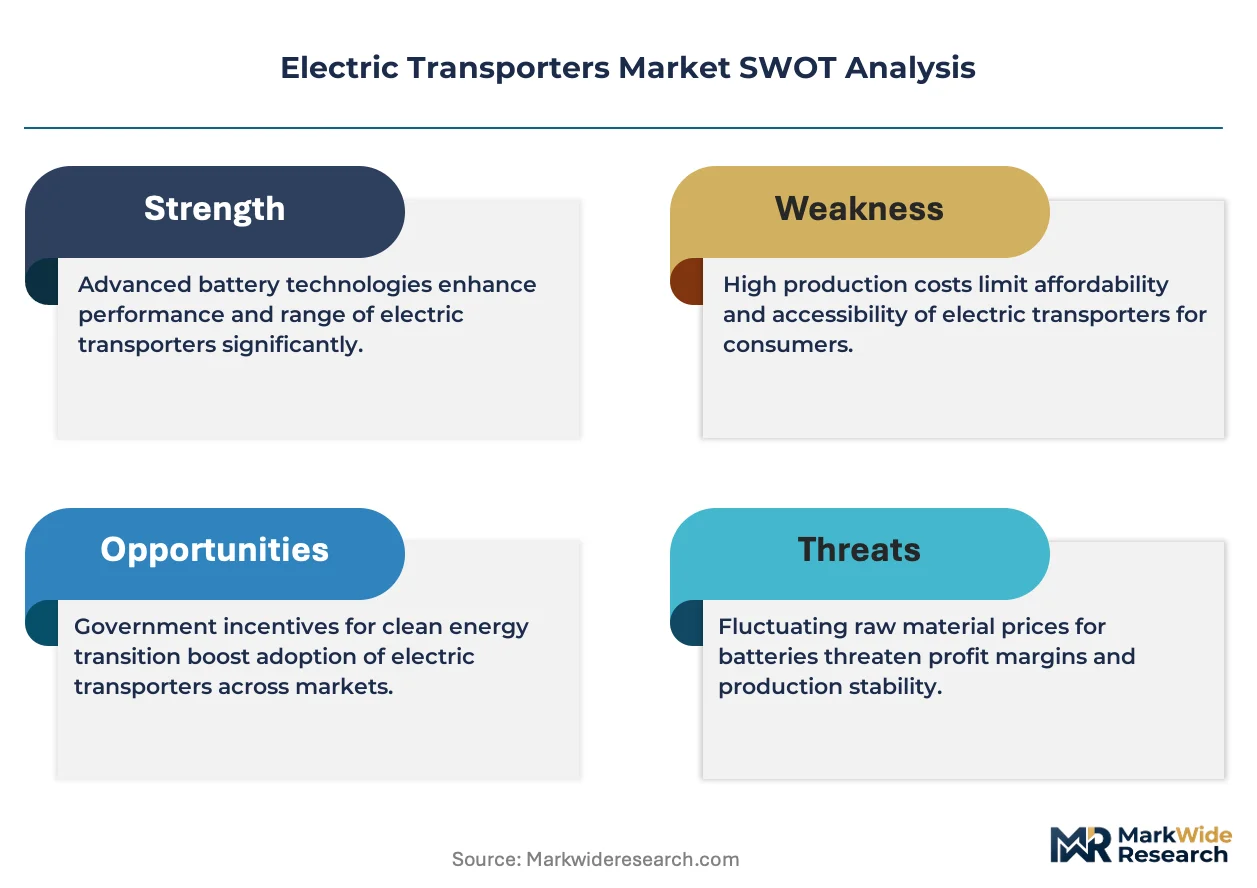
- Input Cost Volatility:Price fluctuations for key battery materials, particularly lithium and cobalt, introduce significant uncertainty into production costs and final vehicle pricing.
- Infrastructure Deficits:The lack of widespread, standardized public charging and secure parking infrastructure for micro-mobility vehicles limits practical appeal for many potential users.
Strategic Opportunities
- B2B Fleet Leasing:Offering subscription-based leasing models for corporate campuses, resorts, and large industrial facilities represents a significant, underpenetrated commercial application.
- Telematics-Enabled Services:Integrating IoT connectivity with fleet management software creates opportunities for value-added services like predictive maintenance, remote diagnostics, and usage-based insurance.
- Sustainability-Driven Procurement:Europe's CSRD incentivizes corporations to adopt electric transporters to reduce and report on their Scope 3 supply chain emissions.
Industry Challenges
- Multi-Jurisdictional Compliance:Engineering products to simultaneously meet Europe's CE marking, US EPA standards, and China's GB standards on a single platform is a major technical hurdle.
- After-Sales Service Scalability:Establishing a cost-effective network for vehicle maintenance, battery swapping, and component repair is a critical operational challenge that lags vehicle sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Transporters Market |
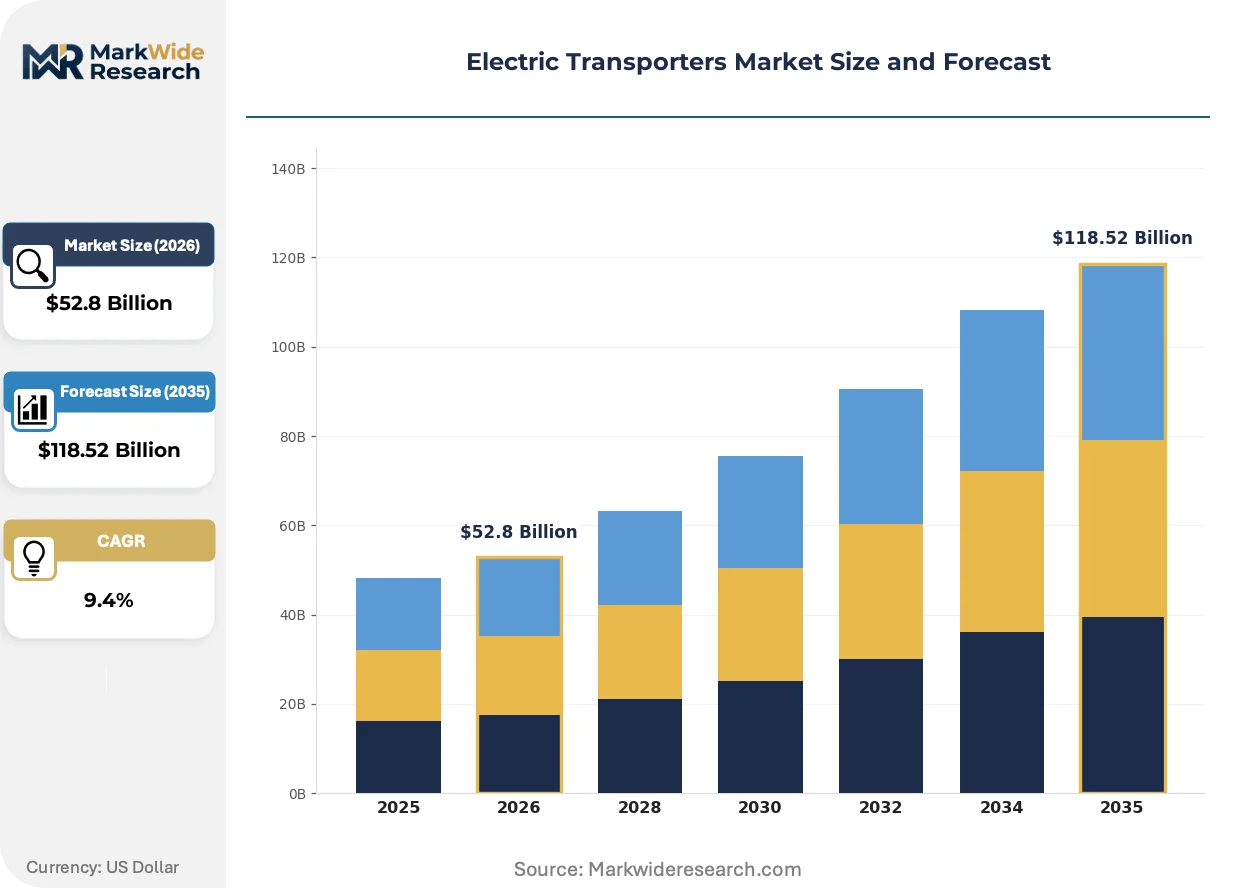
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $118.52 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric Scooters, Electric Bicycles, Electric Skateboards, Electric Mopeds Battery Technology: Lithium-Ion, Nickel-Metal Hydride, Solid State, Lead Acid Application: Personal Mobility, Last-Mile Delivery, Campus Transport, Tourism End User: Commuters, Delivery Services, Educational Institutions, Recreation Providers |
| Companies Covered | BYD, Volkswagen, Ford Motor Company, Mercedes-Benz, AB Volvo, Hyundai Motor Company, BMW Motorrad, Segway Ninebot, Rivian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Transporters Market Strategic Shifts & Innovations
The evolution of electric transporters is driven by a convergence of advanced battery systems and new regulatory frameworks. This dynamic is creating distinct performance tiers and forcing a re-evaluation of traditional vehicle ownership and distribution models.
Solid-state battery technology provides a pathway to higher energy density and improved thermal stability compared to current Lithium-Ion cells. Commercial fleet operators are the primary early adopters, driven by the need for longer operational range and reduced charging downtime. This advanced power source is consolidating the market's focus on high-performance, premium-priced models, creating a wider performance and cost gap from entry-level products.
Europe's Corporate Sustainability Reporting Directive (CSRD) is a pivotal regulatory development impacting commercial fleet choices. The directive compels large companies to disclose detailed information on their supply chain emissions, including last-mile delivery activities. Last-mile logistics providers in the EU are most affected, facing pressure to adopt electric transporters to help their corporate clients meet new compliance and reporting obligations.
A behavioral shift from outright ownership toward flexible subscription and leasing services is becoming more prevalent. This model bypasses traditional dealer networks, favoring direct-to-business fleet management arrangements that bundle vehicles, maintenance, and software. The trend is most visible in dense European urban centers where consumers and businesses alike prioritize access and operational efficiency over capital asset ownership.
Electric Transporters Market Segmentation
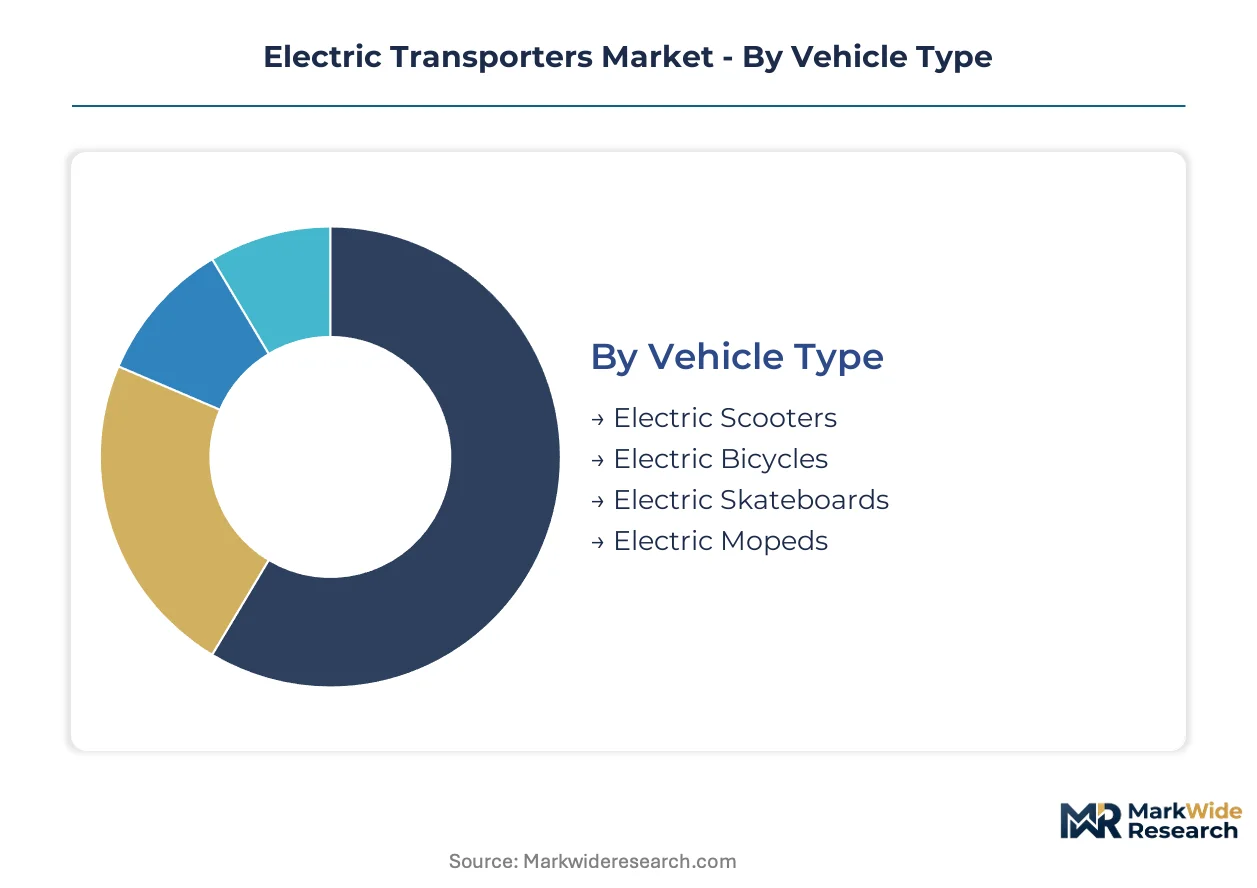
Analyzing the electric transporters market by distinct segments reveals varied investment profiles and operational demands. This granular view highlights where technological advancements and regulatory pressures are most acutely felt, influencing product development and market penetration strategies. Understanding these distinctions is crucial for identifying areas of concentrated value and future growth.
Vehicle Type:
The capital intensity of developing and producing electric transporters varies significantly by vehicle type, reflecting diverse manufacturing complexities and component costs.
- Electric Bicycles:These vehicles integrate an electric motor to assist pedaling, typically with power outputs up to 750W in the US or 250W in Europe, enabling longer commutes and cargo transport. Demand concentrates in European urban centers, driven by robust cycling infrastructure and government incentives for sustainable commuter options.
- Electric Scooters:Characterized by a standing platform and handlebars, these compact vehicles often feature motors ranging from 250W to 2000W, offering agile navigation in congested city environments. Rapid adoption in Chinese mega-cities is fueled by high population density and government support for micro-mobility solutions, easing urban congestion.
- Electric Skateboards:These compact, portable devices utilize electric motors for propulsion, appealing to recreational users and short-distance personal transport.
- Electric Mopeds:These vehicles offer higher speeds and longer ranges than scooters, requiring more robust battery systems and often specialized licensing.
Most installed capacity flows through Electric Bicycles. Expansion is steepest in Electric Scooters.
Battery Technology:
Battery technology segmentation highlights distinct performance tiers and cost structures, directly influencing vehicle pricing and operational capabilities.
- Lithium-Ion:These batteries offer high energy density and a long cycle life, making them the standard power source for most modern electric transporters due to their efficiency and lighter weight. Widespread demand across all vehicle types is driven by their superior performance characteristics and declining manufacturing costs, improving overall vehicle economics.
- Nickel-Metal Hydride:These batteries offer a mature, safer alternative to older chemistries, finding niche applications where cost and moderate performance are prioritized.
- Solid State:Representing a significant advancement, solid-state batteries promise even higher energy density, enhanced safety, and faster charging times by replacing liquid electrolytes with solid materials. Early adoption concentrates in premium electric mopeds and commercial fleets, where extended range and reduced downtime provide substantial operational advantages.
- Lead Acid:This older, heavier chemistry provides a low-cost power solution primarily for entry-level electric scooters and bicycles in price-sensitive markets.
Lithium-Ion technology holds the largest market share. Solid State technology is gaining share fastest.
Application:
The volume of electric transporter deployment varies significantly across different applications, reflecting distinct user needs and operational scales.
- Personal Mobility:Encompasses electric scooters, bicycles, and skateboards used by individuals for daily commutes, errands, and recreational purposes, emphasizing convenience and portability. High population density in cities like Shanghai and Paris fuels demand, as commuters seek alternatives to traditional transport to mitigate traffic and parking issues.
- Last-Mile Delivery:This application involves electric cargo bikes, scooters, and mopeds optimized for efficient, rapid transport of goods over short distances, often within congested urban areas. E-commerce expansion and European CSRD compliance drive demand, pushing logistics providers to electrify fleets for reduced emissions and operational efficiency.
- Campus Transport:This segment includes electric bikes and scooters facilitating movement within large university campuses and corporate parks, promoting efficiency and sustainability.
- Tourism:Electric transporters serve the tourism sector, offering guided tours and rentals in scenic areas, providing eco-friendly and engaging exploration options.
Personal Mobility generates the highest revenue. Last-Mile Delivery exhibits the most significant growth potential.
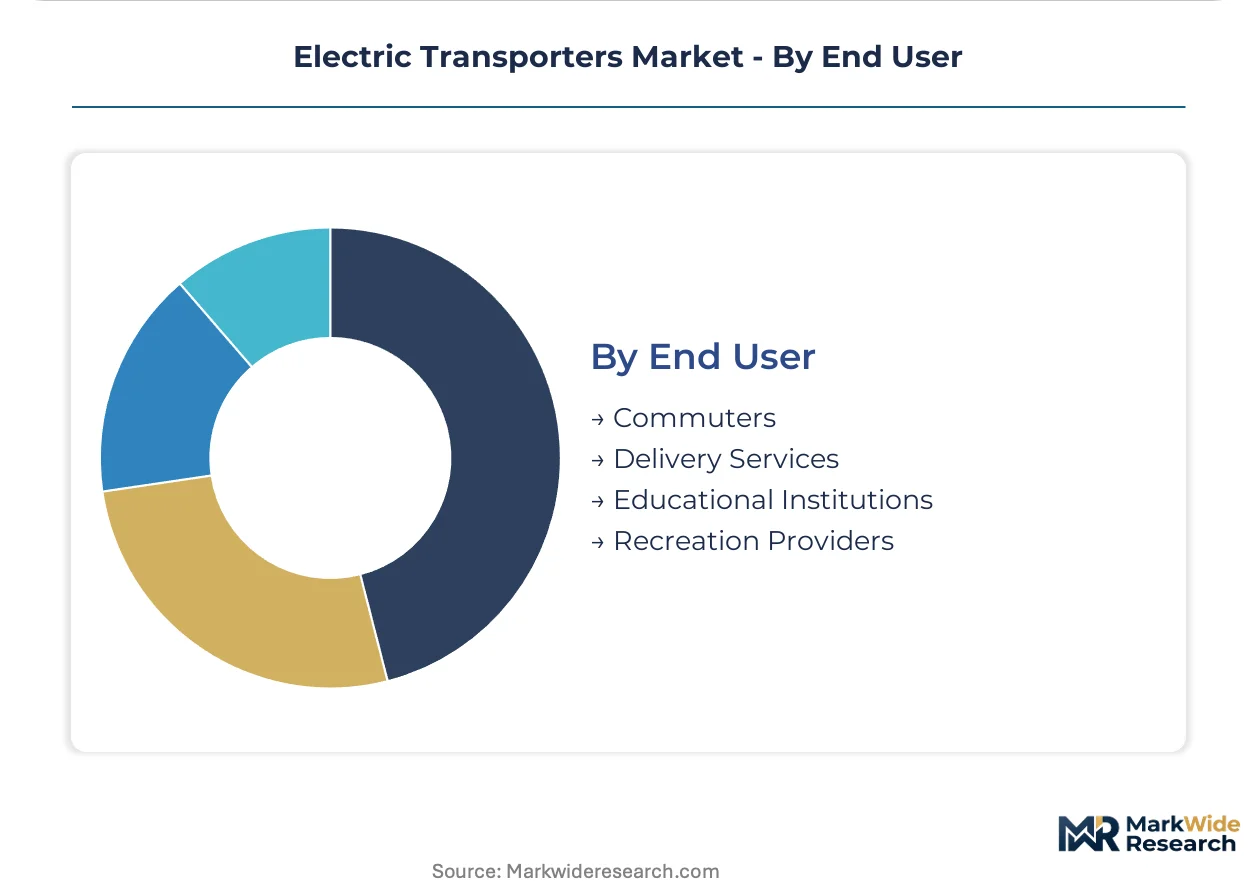
End User:
Segmentation by end user reveals distinct procurement patterns and feature requirements, shaping product development for specific customer bases.
- Commuters:Individuals using electric scooters and bicycles for daily travel to work or school, prioritizing range, portability, and weather resistance for consistent reliability. Urbanization and rising fuel costs in major cities like London and New York drive adoption, seeking cost-effective and environmentally friendly transport alternatives.
- Delivery Services:Businesses like food delivery and parcel services employing electric mopeds and cargo bikes, requiring robust construction, large carrying capacities, and rapid charging capabilities. The expansion of e-commerce platforms globally and the need for efficient urban logistics push these services towards electric fleet integration.
- Educational Institutions:Universities and colleges are adopting electric transporters for campus security, facility maintenance, and student mobility programs, enhancing internal logistics.
- Recreation Providers:These entities, including tour operators and rental companies, offer electric skateboards and bikes for leisure activities, focusing on user experience and durability.
Commuters represent the most penetrated end-user segment. Delivery Services show the most rapid market penetration expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric transporters market initially scaled in Asian urban centers, driven by early adoption of two-wheeled electric vehicles for personal transport. High population densities and a need for efficient, low-emission alternatives characterized these foundational markets. This early development established a global blueprint for micro-mobility growth.
China
Demand for electric scooters and bicycles is immense, driven by urban congestion and government incentives. China's dual carbon goals directly accelerate micro-mobility adoption. Megacities like Shanghai and Shenzhen are seeing widespread deployment of electric vehicles, easing traffic.
Germany
European demand for electric bicycles is strong, supported by cycling infrastructure and sustainability initiatives. CE marking ensures product safety and environmental compliance for market access. Munich and Berlin are hubs for electric bike sharing schemes, integrating electric transporters into daily life.
United States
Personal mobility demand in US cities is increasing, alongside last-mile delivery applications. EPA standards indirectly encourage the transition to electric options. Los Angeles and New York City are experiencing growth in electric scooter and bike usage for short commutes.
Netherlands
Robust cycling culture drives high demand for electric bicycles, particularly for daily commuting. The EU Green Deal promotes sustainable transport solutions across the country. Amsterdam and Utrecht actively integrate electric bikes into their extensive cycle networks, supported by municipal investments.
India
Rapid urbanization and affordability concerns fuel demand for entry-level electric scooters and bicycles. The FAME II scheme provides subsidies for electric vehicle adoption. Major cities like Delhi and Bengaluru are experiencing a surge in electric two-wheeler sales, addressing last-mile connectivity.
Electric Transporters Market Key Industry Players
The competitive structure tilts toward specialized micro-mobility providers and diversified automotive groups. This market exhibits a tiered structure, from high-volume personal mobility solutions to premium commercial fleet offerings. Strategic archetypes include dedicated electric transporter manufacturers, traditional automotive players diversifying into micro-mobility, and battery technology specialists. Dominant competitive moves involve portfolio diversification, strategic partnerships to navigate regulatory complexities, and continuous innovation in battery chemistry to enhance performance.
Within the diversified manufacturing archetype, BYD represents a vertically integrated player leveraging extensive in-house battery capabilities across its electric vehicle portfolio. Segway Ninebot, a Beijing-based company, conversely anchors the personal mobility solution segment, focusing on urban commuter needs with compact designs. Rivian, an American electric vehicle manufacturer, exemplifies a newer entrant pushing into commercial fleet electrification with a premium focus on utility and performance. These companies showcase distinct approaches, from broad-scale integration to niche specialization, shaping the market's evolving competitive dynamics.
| Leading Market Players |
|---|
| BYD |
| Volkswagen |
| Ford Motor Company |
| Mercedes-Benz |
| AB Volvo |
| Hyundai Motor Company |
| BMW Motorrad |
| Segway Ninebot |
| Rivian |
| Others |
Cost & Logistics Intelligence
Commercial fleet operators increasingly drive demand, influencing subscription-based pricing models across the electric transporter market. Their need for operational efficiency directly shapes supply chain choices and cost structures.
Pricing Analysis
Hybrid transactional and subscription models characterize the electric transporters market. Price differentiation stems from advanced battery technology tiers, such as solid-state versus lithium-ion, and comprehensive after-sales service bundles. Pricing pressure stems from input cost volatility for lithium and cobalt, particularly impacting entry-level personal mobility models. Commuters exhibit the highest price sensitivity, while commercial fleet operators prioritize total cost of ownership and operational uptime.
Supply Chain Analysis
Logistics costs significantly impact the final price of electric transporters due to global manufacturing footprints. Geographic supply concentration centers on China for vehicle assembly and battery production, alongside South Korea and Japan for advanced battery components. Raw material dependencies include lithium, cobalt, and nickel, with commodity price volatility introducing structural risk. Distribution runs through a mix of direct-to-consumer sales and B2B fleet management arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric transporters market is evolving into a late-cycle quality story, driven by a demand shift towards premium specifications like solid-state batteries. This trend prioritizes performance and reliability over basic functionality.
For Market Incumbents: Anticipate continued regulatory fragmentation by investing in modular vehicle platforms capable of multi-jurisdictional compliance. Diversify battery sourcing to mitigate input cost volatility, a persistent threat to margin stability. Control after-sales service networks to maintain customer loyalty against emerging competitors.
For New Entrants and Emerging Players: Corporate campus administrators represent an underserved buyer archetype seeking integrated transport solutions. Target B2B fleet leasing for large industrial facilities, a highly penetrable commercial application. Offer telematics-enabled services as a value-added go-to-market angle, providing predictive maintenance and usage analytics.
For Investors and Strategic Acquirers: Diversified automotive groups are the most active acquirers in this space, seeking to expand their micro-mobility portfolios. Long-term viability over the next decade hinges on companies achieving economies of scale in battery production and vehicle assembly. Target specialized micro-mobility software providers as key acquisition archetypes. The signal to watch is the widespread adoption of solid-state battery technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Solid-State Battery R&D | Advances vehicle range and charging speed, crucial for commercial fleet operational efficiency. |
| Expand B2B Leasing Models | Captures corporate campus and last-mile delivery demand, bypassing traditional retail channels. |
| Develop Multi-Jurisdictional Vehicle Platforms | Reduces compliance costs and accelerates market access across diverse municipal regulations. |
| Integrate Telematics for Fleet Management | Offers value-added services like predictive maintenance, enhancing operator efficiency and safety. |
| Secure Lithium and Cobalt Supply Agreements | Mitigates input cost volatility, ensuring stable production costs for electric mopeds and scooters. |
Research Approach
Bottom-up personal mobility modeling reconciled against top-down vehicle manufacturing tracking forms the analytical core of this study. Primary interviews with vehicle engineers, fleet managers, and urban planners provided qualitative insights. Secondary validation drew from government transport agency reports, e-commerce market analyses, and battery patent databases. This triangulation ensures a robust understanding of market dynamics.
Historical trendline analysis informed the projection of market values across the analysis window. This framework segmented the market by vehicle type, battery technology, application, end user, and regional regulatory environment. Compound annual growth rates were derived from historical adoption patterns and projected policy impacts. Key forecast inputs included lithium-ion battery cost trends and urban population density shifts.
Underlying measurement precision varies by segment; electric bicycles and personal mobility carry tighter precision than emerging niche applications. Forecasts reflect assumptions regarding future regulatory changes and raw material supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Busbar for EV Market