
 Compact E-Scooter Market | 2026-2036
Compact E-Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Compact E-Scooter Market Outlook
Chinese lithium-ion pack producers is recalibrating output schedules to match European import certification timelines. Segway-Ninebot leverages its manufacturing scale to dominate the foldable commuter segment across multiple continents. Xiaomi competes aggressively on cost through direct-to-consumer channel control and modular design architectures.
A compact e-scooter is a lightweight, electrically propelled personal mobility device typically weighing under 25 kilograms, powered by rechargeable battery packs with motor outputs ranging from 250 to 750 watts, designed for short-distance urban transit and last-mile connectivity. The foldable product category anchors volume demand among commuters and tourists requiring multimodal transport integration, while solid-state battery technology represents the fastest-growing segment as energy density improvements promise extended range without weight penalties. Fast charging infrastructure compatibility increasingly determines purchasing decisions among delivery personnel operating under time-constrained logistics contracts.
The EU Green Deal and associated F-Gas Regulation frameworks restrict refrigerant and battery chemistry imports, compelling manufacturers to certify under REACH and RoHS standards before European market entry. The US NHTSA and FAA maintain separate oversight tracks for street-legal operation versus air-travel portability, creating compliance complexity for cross-border sellers. Stakeholders must monitor evolving municipal speed-limit ordinances and parking infrastructure investments as these local rules increasingly determine addressable market size in dense urban cores.
Market Dynamics
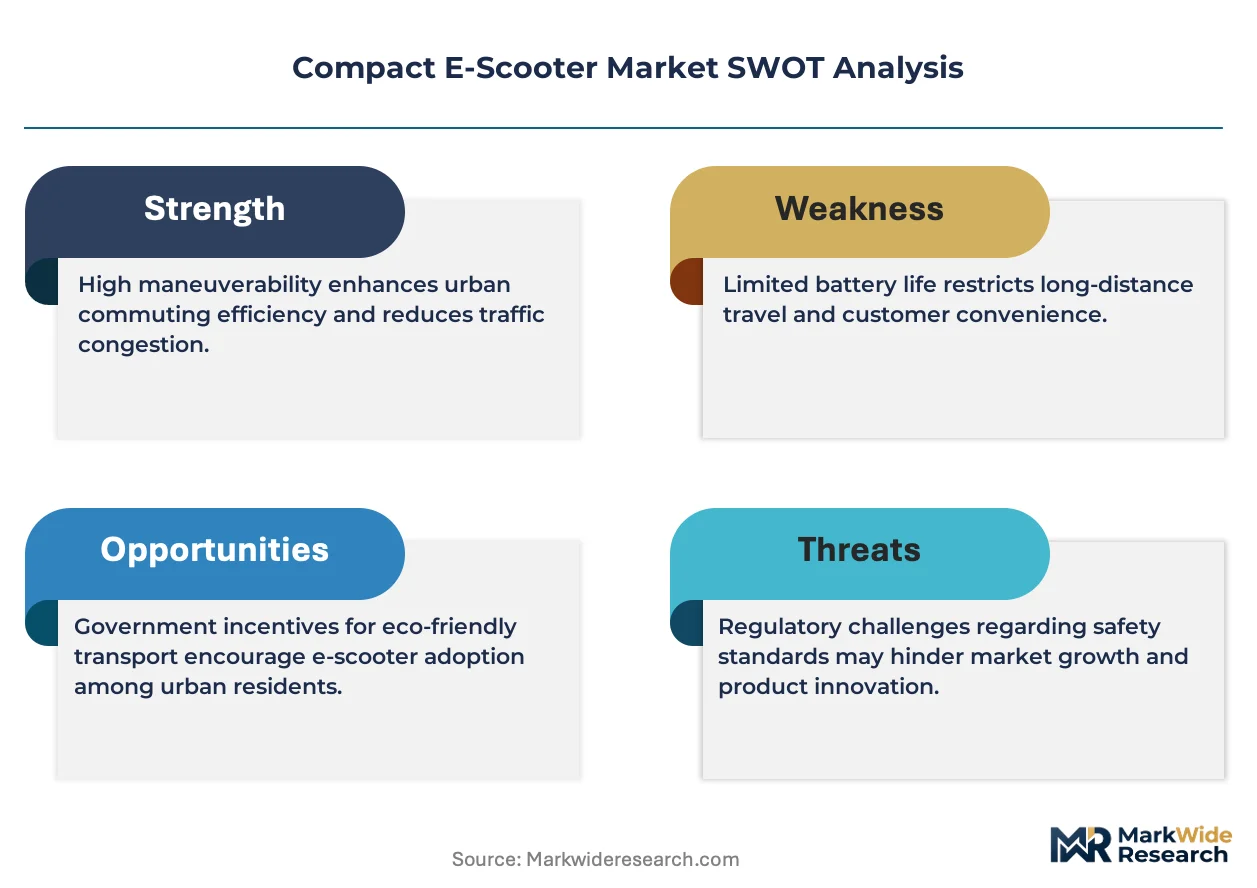
Battery chemistry standardization and municipal speed-limit ordinances are compressing product development cycles while fragmenting addressable markets across urban jurisdictions. Manufacturers must now certify under divergent regulatory frameworks before securing fleet procurement contracts.
Growth Catalysts
- EU Green Deal decarbonization mandates:France, Germany, and Italy have tightened emission standards for micro-mobility, compelling commercial fleets to electrify last-mile delivery operations.
- Integrated battery supply chains:Domestic manufacturers in China benefit from captive lithium-ion cell production and streamlined municipal licensing frameworks.
- Foldable form factor adoption:Urban commuters and tourists require multimodal transport integration, driving volume demand for lightweight, collapsible units.
Market Restraints
- Input cost volatility:Lithium carbonate and nickel prices fluctuate unpredictably, squeezing gross margins for battery pack assemblers.
- Supply concentration risk:Cathode active material production clusters in China, creating single-source dependency for non-integrated brands.
- Technical limitation:Solid-state battery manufacturing yields remain below commercial scale, delaying energy density improvements.
Strategic Opportunities
- Underpenetrated fleet electrification:Courier and food-delivery operators in Spain and Poland still rely heavily on internal combustion mopeds.
- Fast charging infrastructure:Delivery personnel operating under time-constrained logistics contracts prioritize charging speed compatibility in purchasing decisions.
- Technology convergence:Swappable battery architectures combined with IoT telematics enable asset-light fleet management models.
Industry Challenges
- Certification timeline compression:REACH and RoHS compliance for European market entry now requires 14-18 months of pre-certification testing.
- Talent scarcity:Power electronics engineers with motor controller firmware expertise command premium compensation, constraining R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact E-Scooter Market |
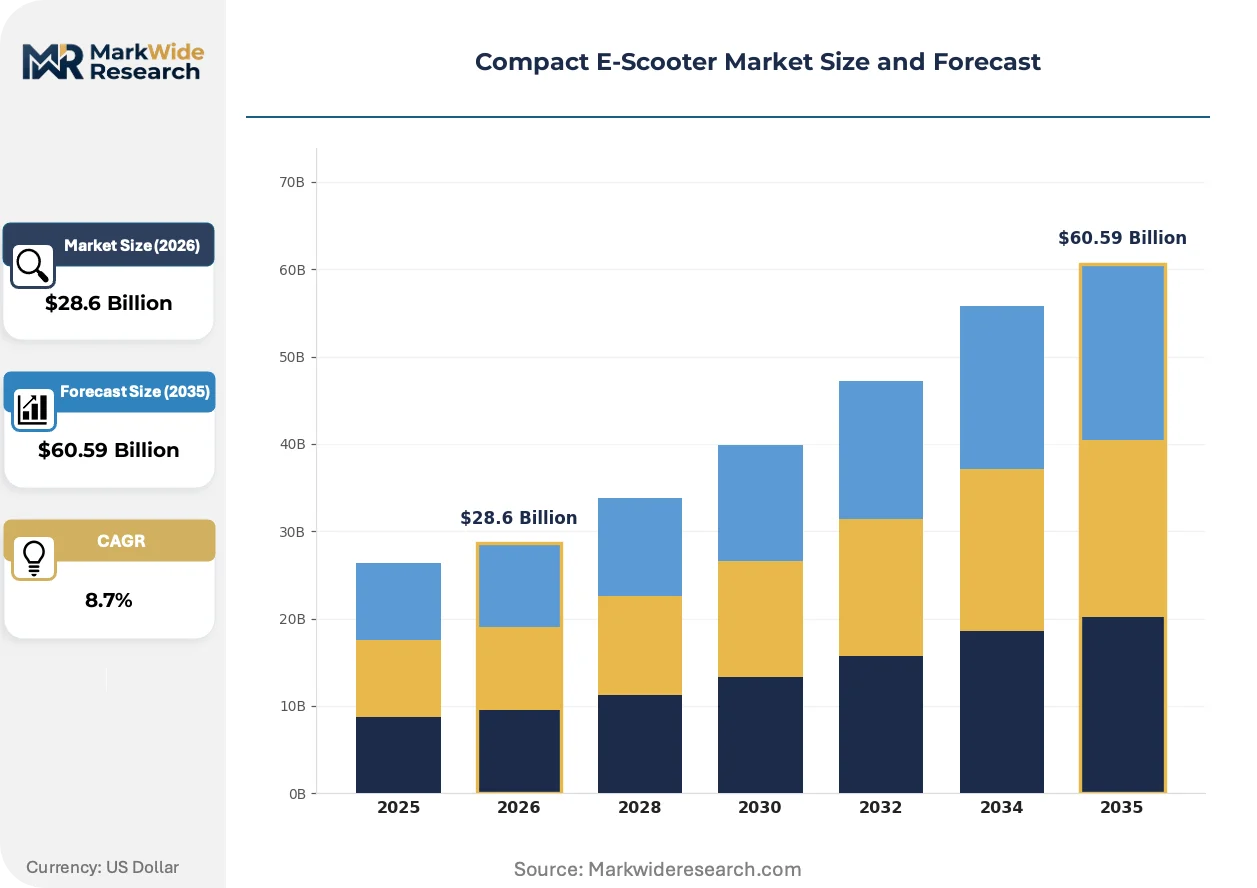
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Non-Foldable, Off-Road, Urban Battery Technology: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Charging Method: Standard Charging, Fast Charging, Solar Charging, Inductive Charging Target User: Commuters, Students, Tourists, Delivery Personnel |
| Companies Covered | Segway-Ninebot, Xiaomi, Honda Motor Company, Niu Technologies, Razor USA, Unagi, Inokim, Ather Energy, Bajaj Auto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact E-Scooter Market Strategic Shifts
Solid-state energy storage and modular hardware architectures are compressing replacement cycles while elevating performance expectations among commercial buyers. Regulatory divergence between street-legal operation and air-travel portability standards is forcing product-line bifurcation.
Solid-state battery technology promises energy density improvements without weight penalties. Fleet operators and premium commuter segments are adopting early-generation cells despite cost premiums. Conventional lithium-ion pouch formats is overtaking cylindrical cell configurations in foldable scooter designs due to packaging efficiency.
The US NHTSA maintains separate oversight tracks for street-legal operation versus FAA air-travel portability requirements. Cross-border sellers face compliance complexity when marketing single SKUs across multiple jurisdictions. Dual-certification product variants now dominate premium positioning in North American and European channels.
Direct-to-consumer channel control is displacing traditional retail distribution in cost-sensitive segments. Modular design architectures enable end-user component upgrades, extending product lifecycles. This pattern is most visible in Chinese domestic e-commerce platforms and German urban commuter markets.
Compact E-Scooter Market Segmentation
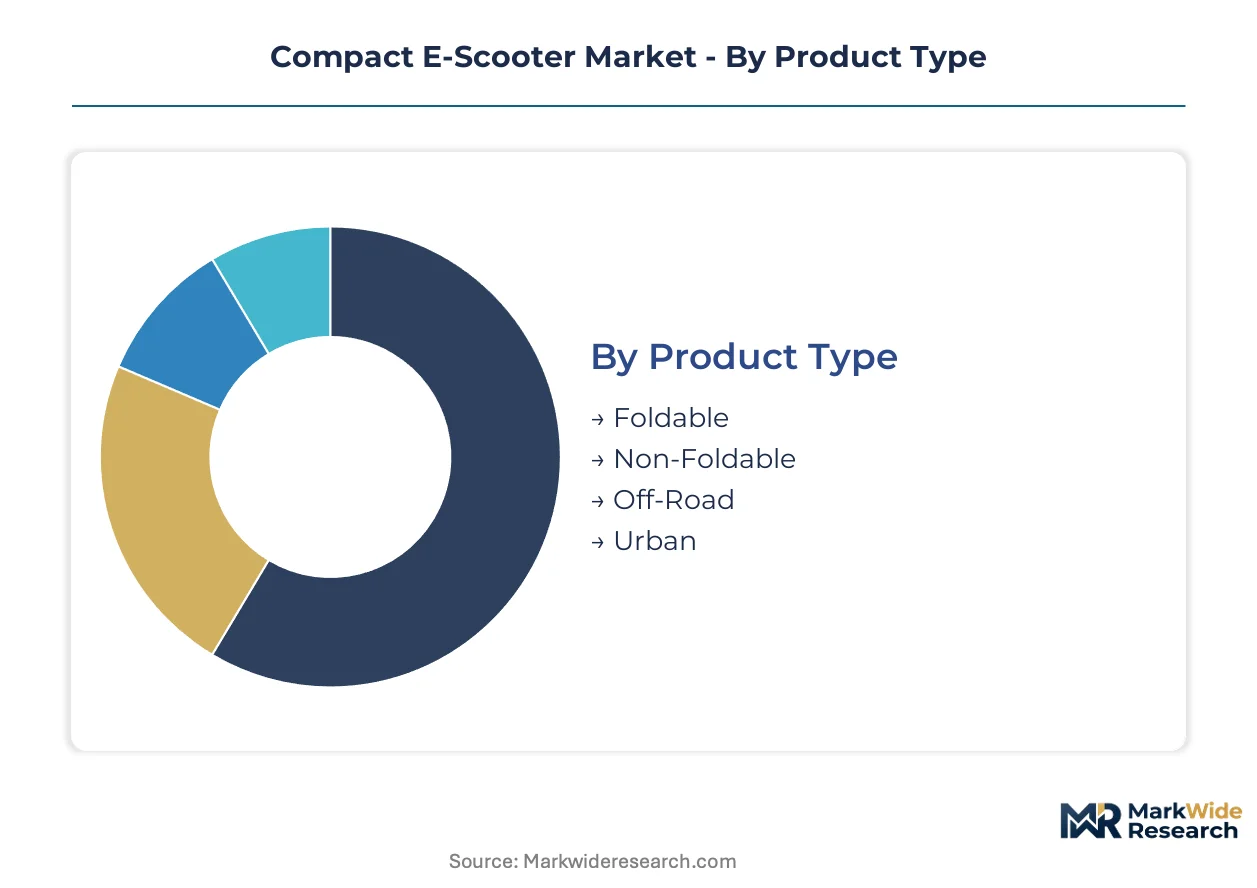
Segmentation in the compact e-scooter market reveals how divergent use cases and technical specifications fragment procurement patterns across consumer and commercial channels. Battery chemistry and form factor choices directly determine regulatory compliance pathways and total cost of ownership calculations for fleet operators.
Product Type:
Supply concentration in foldable frame manufacturing clusters around Shenzhen and Dongguan, where aluminum forging and hinge mechanism suppliers operate within tight logistics radii.
- Foldable:Aluminum alloy frames with patented quick-release mechanisms enable multimodal transit integration. Demand concentrates among urban commuters in Paris, Berlin, and Milan who combine e-scooters with rail networks under EU Green Deal mobility incentives.
- Non-Foldable:Rigid chassis designs prioritize structural rigidity and lower unit costs. Fleet procurement in Chinese municipal bike-share programs and Spanish food-delivery networks favors these units for reduced mechanical failure rates.
- Off-Road:Suspension travel exceeding 80mm and knobby tire configurations address unpaved terrain. Recreational demand in Australian coastal regions and German forest trail networks drives niche volume.
- Urban:Optimized for paved surfaces with puncture-resistant tires and integrated lighting systems. Municipal licensing frameworks in Rome and Madrid explicitly favor this category for sidewalk compatibility.
Today's leader: Foldable. Tomorrow's challenger: Urban.
Battery Technology:
Cost tier differentiation separates premium energy density solutions from commodity cell configurations serving price-sensitive segments.
- Lithium-Ion:NMC and LFP cathode chemistries dominate current production with energy densities of 250-300 Wh/kg. Chinese integrated manufacturers leverage captive cell production to compress pack costs for European export certification timelines under REACH and RoHS frameworks.
- Lead-Acid:Flooded and AGM formats persist in emerging market entry-level units. Price-sensitive student segments in Indian university towns and Southeast Asian urban centers absorb these heavier, shorter-cycle packs.
- Nickel-Metal Hydride:Intermediate energy density with reduced thermal runaway risk. Niche adoption in Japanese domestic market commuter models reflects legacy supplier relationships and conservative safety standards.
- Solid-State:Ceramic electrolyte architectures promise 400+ Wh/kg density without flammable liquid components. Early commercial cells from Samsung SDI and Toyota subsidiaries are gaining share fastest among premium European fleet pilots despite manufacturing yield constraints.
Current procurement centers on Lithium-Ion. Solid-State represents the steepest expansion trajectory as yield improvements compress cost premiums.
Charging Method:
Application urgency determines infrastructure investment, with time-constrained logistics operators driving fast-charging compatibility requirements.
- Standard Charging:4-6 hour full-cycle AC charging via removable battery packs or onboard ports. Residential and workplace parking in German apartment complexes and French corporate campuses accommodates these slower cycles.
- Fast Charging:DC rapid protocols delivering 80% capacity within 45 minutes. Delivery personnel operating under time-constrained contracts in London and Amsterdam prioritize this capability for shift-continuous operations.
- Solar Charging:Integrated photovoltaic panels extend range marginally during daylight exposure. Tourist rental fleets in Mediterranean coastal municipalities leverage this for marketing differentiation despite limited practical range extension.
- Inductive Charging:Wireless power transfer through pavement-embedded coils. Pilot deployments in Swedish smart city infrastructure and Singaporean university campuses test fleet automation integration.
Volume dominance: Standard Charging. Capability migration: Fast Charging.
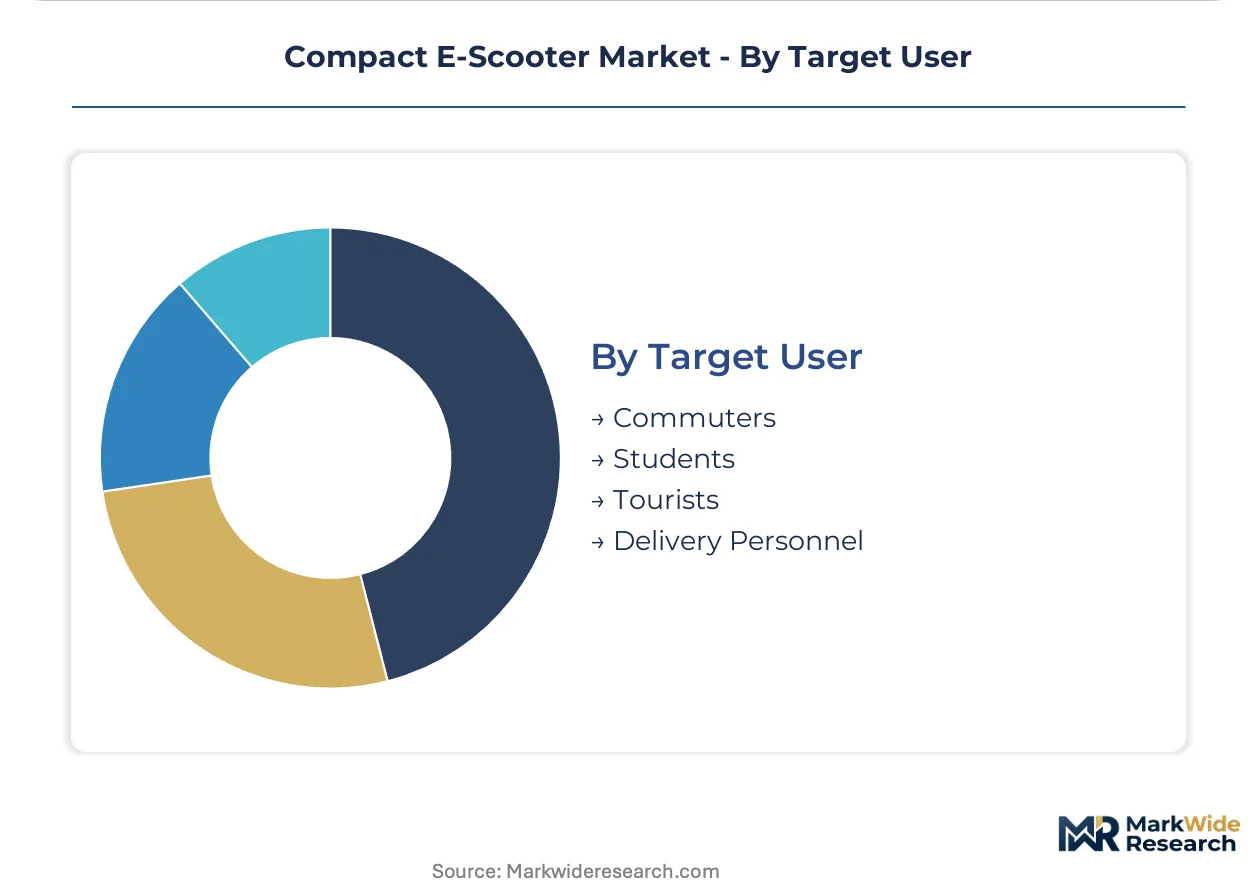
Target User:
Customer type segmentation maps directly to pricing power and replacement cycle frequency, with commercial operators exhibiting superior lifetime value metrics.
- Commuters:Daily urban transit users purchasing personal units for multimodal journeys. Foldable configurations with sub-15kg weights dominate in Paris, Copenhagen, and Vienna where building elevator access constraints apply.
- Students:Price-sensitive demographic prioritizing acquisition cost over performance specifications. Direct-to-consumer channels through Chinese e-commerce platforms and German electronics retailers capture this volume.
- Tourists:Short-term rental demand concentrated in Barcelona, Rome, and Lisbon historic centers. Shared fleet operators deploy ruggedized urban models with geofencing compliance for municipal licensing.
- Delivery Personnel:Commercial users operating under logistics platform contracts with minimum hourly throughput requirements. Fast charging compatibility and swappable battery architectures determine procurement decisions in Madrid and Warsaw food-delivery networks.
Revenue concentration: Delivery Personnel. Volume expansion: Commuters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with streamlined certification timelines and integrated component ecosystems. Cost-of-compliance gaps between REACH-regulated European entry and domestic Chinese licensing create divergent investment incentives.
China
Shenzhen and Dongguan manufacturing clusters absorb the majority of global foldable frame production, leveraging captive lithium-ion cell supply from CATL and BYD subsidiaries. MIIT certification pathways compress pre-market testing to 6-8 months versus 14-18 months for European REACH compliance. Municipal licensing frameworks in Beijing and Shanghai prioritize domestic fleet procurement, anchoring volume demand for non-foldable urban models in bike-share programs.
Germany
Berlin and Munich commuter corridors drive premium foldable adoption under KBA street-legal certification requirements. The EU Green Deal's national decarbonization mandates compel commercial fleets to electrify last-mile operations by 2030. Baden-Württemberg engineering clusters concentrate motor controller firmware development, where talent scarcity elevates compensation premiums for power electronics specialists.
United States
NHTSA street-legal standards and FAA air-travel portability requirements force product-line bifurcation for cross-border sellers. California and New York metro areas dominate personal commuter demand, while Texas logistics corridors anchor delivery fleet procurement. The IRA's clean vehicle incentives apply unevenly to micro-mobility, creating regulatory uncertainty for commercial operators.
France
Parisian multimodal transit integration under EU Green Deal mobility incentives concentrates foldable demand among rail-commuting professionals. ANSM and CNIL oversight extends to IoT telematics data handling in shared fleet deployments. Lyon and Marseille historic centers generate tourist rental volume requiring geofencing compliance for municipal sidewalk compatibility.
India
Bangalore and Delhi-NCR food-delivery networks represent underpenetrated fleet electrification opportunities against internal combustion moped dominance. BIS certification timelines lag European frameworks, creating import friction for premium solid-state configurations. The PLI scheme for advanced chemistry cell manufacturing is recalibrating domestic battery pack assembly capacity toward captive supply.
Compact E-Scooter Market Competitive Environment
Chinese producers anchor the scale-driven tier; European and North American specialists hold premium positioning through certification depth and design differentiation. Market structure exhibits moderate concentration at the top, with Segway-Ninebot leveraging manufacturing scale across multiple continents while Xiaomi competes through direct-to-consumer channel control. Three archetypes dominate: integrated battery manufacturers with captive cell supply, design-centric brands emphasizing multimodal portability, and fleet-focused operators optimizing for total cost of ownership. Competitive moves center on backward integration into cathode active material production and strategic partnerships for fast-charging infrastructure deployment.
Within the integrated manufacturing tier, Segway-Ninebot and Niu Technologies exemplify scale-driven positioning through geographic naming and corporate structure. Xiaomi Corporation occupies a distinct archetype as a direct-to-consumer platform leveraging modular design architectures. Honda Motor Company represents legacy automotive crossover into micro-mobility, sitting within the premium-tier vector where dual-certification product variants dominate North American and European channels. These three anchors illustrate how competitive positioning fragments across production scale, channel control, and brand heritage vectors.
| Leading Market Players |
|---|
| Segway-Ninebot |
| Xiaomi |
| Honda Motor Company |
| Niu Technologies |
| Razor USA |
| Unagi |
| Inokim |
| Ather Energy |
| Bajaj Auto |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate and nickel price volatility feeds directly through battery pack assembler margins into three-tier pricing structure across premium, standard, and economy levels, with Chinese integrated manufacturers compressing mid-tier positioning through captive cathode supply while European certification costs elevate premium entry points.
Pricing Analysis
Distributor margin layers in European channels absorb REACH and RoHS pre-certification testing costs, elevating landed prices against direct-to-consumer Chinese platforms. Price differentiation separates CE-marked fleet configurations from economy-tier student models through battery chemistry grade and after-sales service bundling. Cost compression in the standard tier intensifies because nickel price fluctuations squeeze pack assemblers without captive cell supply. Students in Indian university towns exhibit highest price sensitivity, while delivery fleet operators in Madrid and Warsaw prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from municipal bike-share programs and logistics fleet operators, bypassing retail markup layers. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cell production, with cathode active material processing anchored in Chinese integrated facilities. The supply chain draws from lithium carbonate, nickel sulfate, and aluminum forging inputs. Single-source vulnerability in Chinese cathode material production creates concentration risk for non-integrated brands. Distribution runs through Shenzhen and Dongguan manufacturing clusters for foldable frame assembly, feeding European and North American certification pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on solid-state battery yield improvements compressing cost premiums and fleet operators accepting higher upfront pricing for swappable architectures that reduce downtime.
For Market Incumbents: Deepen backward integration into cathode active material production to defend against nickel price volatility eroding pack margins. Fortify certification depth under dual NHTSA and FAA tracks to maintain premium positioning in North American channels against emerging direct-to-consumer entrants. Prioritize fast-charging infrastructure partnerships to lock in delivery fleet procurement decisions in Amsterdam and London. For New Entrants and Emerging Players: The gap between premium solid-state configurations and economy-tier lead-acid units offers white-space targeting for intermediate lithium-ion pouch formats with modular upgrade paths. Spanish and Polish courier networks remain underpenetrated against internal combustion moped dominance, presenting fleet electrification entry points. Pursue direct-to-consumer channel control through Chinese e-commerce platforms and German electronics retailer partnerships to bypass incumbent distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where talent scarcity for power electronics engineers with motor controller firmware expertise constrains R&D expansion at mid-cap specialists. Long-term viability favors integrated battery manufacturers with captive cell supply and established European certification timelines over design-centric brands dependent on outsourced pack assembly. Watch solid-state battery manufacturing yield improvements as the inflection signal for premium tier cost compression and mainstream adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Production | Captive nickel sulfate processing insulates margins from commodity volatility affecting non-integrated assemblers. |
| Dual Certification Investment | Simultaneous NHTSA street-legal and FAA air-travel compliance unlocks premium positioning in cross-border channels. |
| Fast Charging Infrastructure Partnership | DC rapid protocol compatibility secures delivery fleet procurement in time-constrained logistics contracts. |
| Swappable Battery Architecture Development | Asset-light fleet management models reduce downtime and elevate lifetime value metrics for commercial operators. |
| Direct-to-Consumer Channel Expansion | Platform control through Chinese e-commerce and German retail bypasses distributor margins in price-sensitive segments. |
Study Parameters
Multiple input streams — regulatory filing analysis, customs and trade databases, and supply chain documentation — were reconciled across primary interviews with battery pack engineering directors, fleet procurement managers at logistics operators, municipal licensing officials, and power electronics firmware specialists, combined with secondary validation from MIIT certification records, REACH pre-registration databases, ECHA substance tracking, and SEC filings of listed micro-mobility manufacturers, employing bottom-up unit shipment modeling and top-down market value reconciliation.
Historical volume trajectories were cross-referenced against expert panel assessments of solid-state battery yield improvement timelines and municipal speed-limit ordinance expansion patterns across the projection horizon. Segmentation dimensions modeled include product type, battery technology, charging method, and target user archetype, with CAGRs derived from curve-fitting across disclosed production capacity announcements and fleet procurement contract values. Forecast inputs incorporate cathode material price indices and certification timeline compression effects.
Caveats apply where lithium carbonate price spikes, REACH testing backlog extensions, or solid-state manufacturing yield stagnation could materially shift the outlook beyond modeled ranges. Periodic stress-testing of base assumptions against cathode active material supply disruptions and municipal parking infrastructure investment delays is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
E-SUV Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Europe Electric Car Market