
 GCC Artificial Intelligence Market | 2026-2036
GCC Artificial Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Artificial Intelligence Market Intelligence
The shift from outsourced AI infrastructure to in-house sovereign data centers is expanding across Gulf states. Nvidia Corporation leverages its GPU dominance to anchor high-performance computing clusters in the region. Microsoft Corporation sustains cloud AI service delivery through expanded UAE and Saudi data center regions. SAP Middle East & North Africa LLC differentiates through localized enterprise AI applications tailored to Gulf regulatory environments.
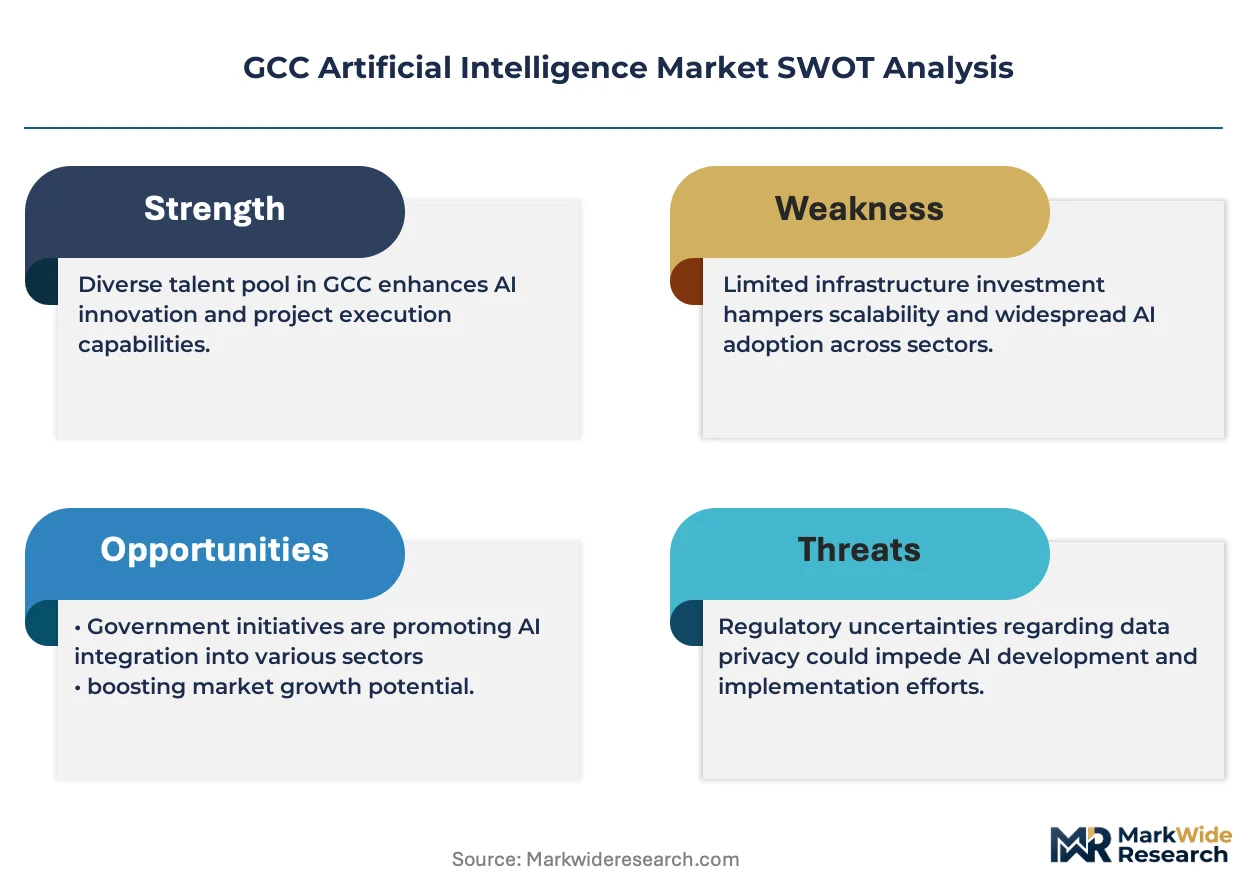
Artificial Intelligence in the GCC denotes computational systems that learn from data inputs to automate decision-making, typically requiring neural network architectures trained on datasets exceeding millions of parameters for commercial deployment. Machine Learning applications currently lead segment value generation across Gulf banking and retail sectors. Deep Learning capabilities within the Technology dimension are capturing expanding margin pools as sovereign AI investments prioritize autonomous systems and predictive analytics infrastructure.
Saudi Arabia's Saudi Data and Artificial Intelligence Authority and the UAE's National Artificial Intelligence Strategy establish compliance frameworks governing data localization and algorithmic transparency for market access. The Kingdom's Personal Data Protection Law and Dubai's AI ethics guidelines shape product standards for cross-border AI service providers. Stakeholders must monitor evolving sovereign data governance requirements as Gulf states tighten control over strategic computational infrastructure.
Market Dynamics
Sovereign data localization mandates across Gulf states are forcing foreign AI providers to establish domestic infrastructure, transforming procurement patterns and vendor selection criteria throughout the region.
Growth Catalysts
- Saudi Data and Artificial Intelligence Authority frameworks:The SDAIA's national AI strategy mandates algorithmic transparency standards that create compliant domestic demand pools for certified solution providers.
- Healthcare diagnostic imaging:Saudi hospital networks deploy computer vision systems for radiology workflow automation, generating specialized procurement for FDA-cleared and SFDA-registered devices.
- Dubai smart city clusters:Government-backed initiatives in healthcare, transportation, and public safety concentrate demand for edge-computing AI deployments with sub-10 millisecond latency requirements.
Market Restraints
- GPU supply concentration:Advanced training hardware availability depends on US Commerce Department export licensing timelines, creating procurement uncertainty for sovereign AI infrastructure projects.
- Personal Data Protection Law compliance costs:Saudi Arabia's PDPL mandates data residency and cross-border transfer assessments that extend vendor onboarding cycles by 6-12 months for foreign providers.
- Neural network training energy intensity:Large language model development requires sustained megawatt-scale power commitments that strain grid capacity in rapidly urbanizing emirates.
Strategic Opportunities
- Abu Dhabi sovereign wealth deployment:Mubadala Investment Company's technology portfolio allocations target domestic AI chip design and fabrication capabilities.
- Arabic natural language processing:Dialectal variation across Gulf states creates whitespace for specialized large language models trained on regional corpora.
- MOHAP medical device AI guidelines:UAE Ministry of Health and Prevention's regulatory sandbox for diagnostic algorithms accelerates market entry for compliant imaging software vendors.
Industry Challenges
- Machine learning operations talent scarcity:MLOps engineering expertise capable of deploying production-grade systems remains concentrated among expatriate professionals with limited long-term retention.
- Legacy banking core integration:Predictive analytics deployments require API connectivity with decades-old mainframe architectures that resist standard data extraction protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Artificial Intelligence Market |
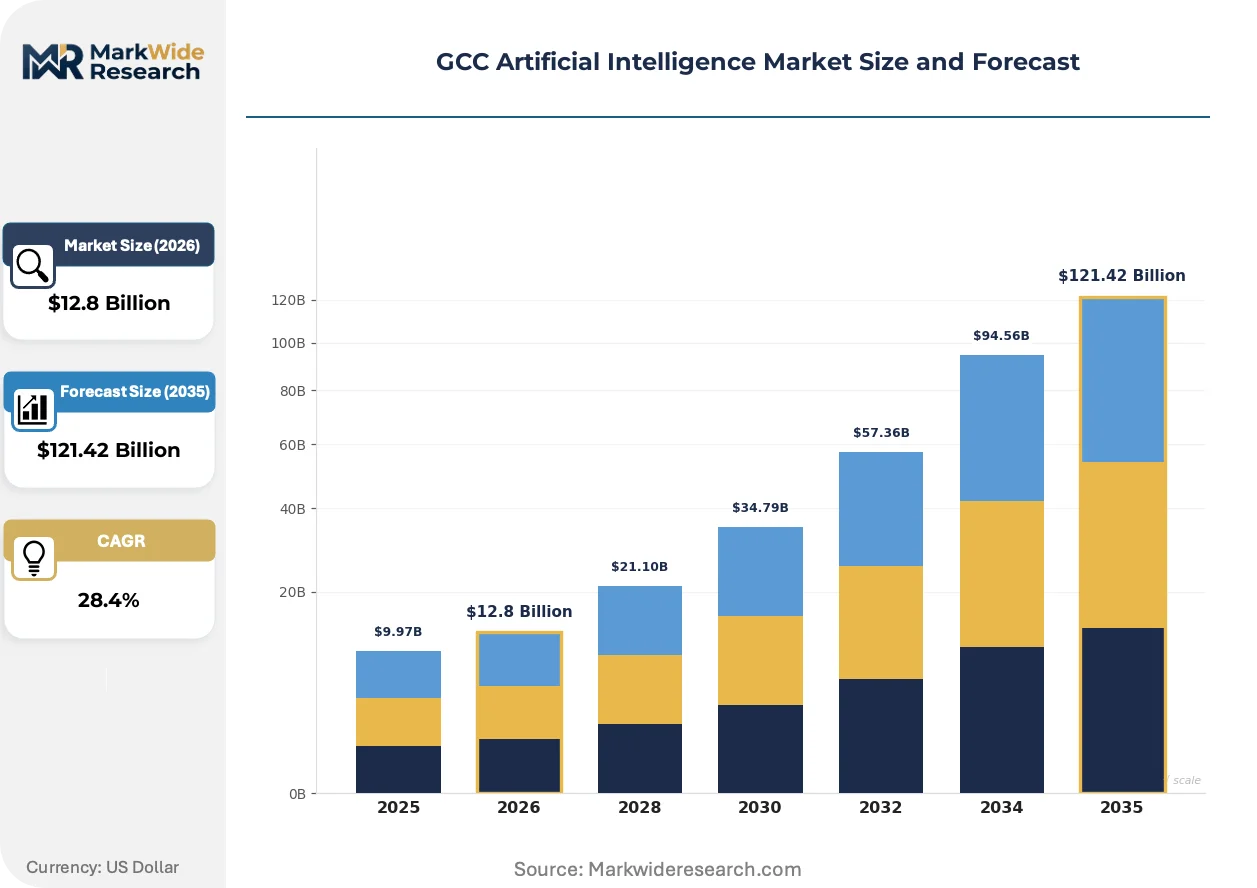
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $121.42 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machine Learning, Natural Language Processing, Image Recognition, Robotics Application: Healthcare, Retail, Banking, Smart Cities End User: Enterprises, Government Agencies, Education, Healthcare Providers Technology: Cloud Computing, Edge Computing, Neural Networks, Deep Learning |
| Companies Covered | Nvidia Corporation, Intel Corporation, Amazon Web Services, Inc., SAP Middle East & North Africa LLC, Samsung Electronics Co. Ltd, Google LLC, Oracle Corporation, Siemens Middle East Limited, Microsoft Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Artificial Intelligence Market Strategic Shifts & Innovations
Federated learning architectures and sovereign cloud infrastructure are converging to enable cross-border AI collaboration without violating data residency requirements. This structural shift redefines how Gulf states balance innovation access with national security imperatives.
Transformer-based large language models optimized for Arabic dialects are rewriting competitive dynamics in customer service automation. Saudi telecom operators and UAE retail banks deploy these systems for call center augmentation, compressing deployment timelines from 18 months to under 6 months for conversational AI projects. The technology is rewriting vendor selection criteria, privileging regional data sovereignty over performance benchmarks established on English-language corpora.
The UAE's National Artificial Intelligence Strategy 2031 mandates algorithmic impact assessments for high-risk applications in healthcare, finance, and transportation. This framework creates compliance differentiation for vendors with established governance documentation, while smaller providers face documentation burdens that extend sales cycles. Dubai's AI ethics guidelines establish product liability precedents that shape insurance and indemnification structures for autonomous system deployments.
Public sector procurement in Riyadh and Abu Dhabi now prioritizes outcome-based contracting for AI-enabled services over perpetual software licenses. Government entities specify operational KPIs—diagnostic accuracy rates, fraud detection precision, traffic flow optimization—rather than technical specifications. This pattern concentrates contract awards among vendors with demonstrated deployment track records in comparable Gulf environments, disadvantaging new market entrants without regional reference implementations.
GCC Artificial Intelligence Market Segmentation
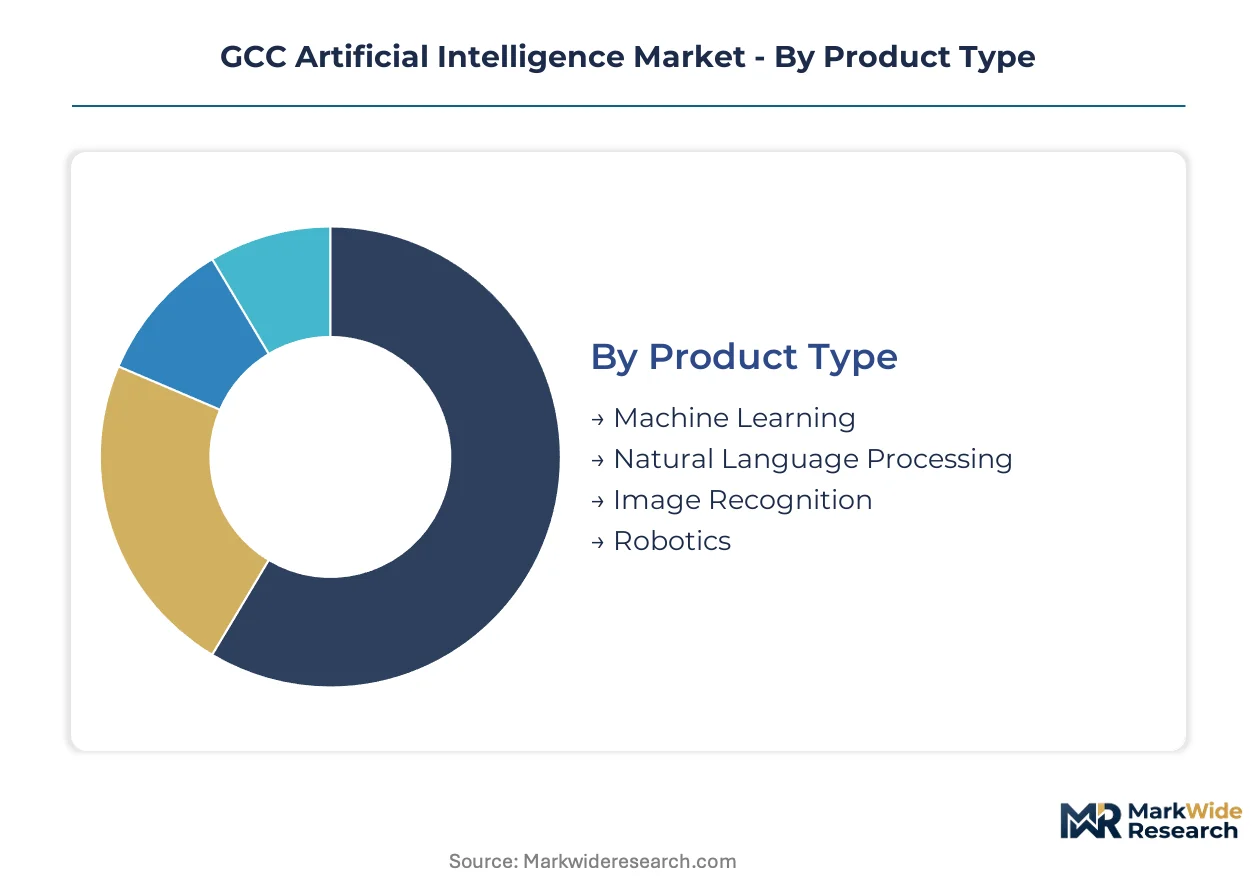
Segmentation in the GCC AI market reveals how sovereign infrastructure investments and regulatory localization reshape vendor positioning. Understanding these divisions exposes where procurement budgets concentrate and which technical capabilities command premium positioning.
Product Type:
Supply concentration in GPU-accelerated training hardware favors vendors with direct Nvidia allocation agreements, concentrating competitive advantage among established cloud providers.
- Machine Learning:Statistical algorithms trained on structured datasets automate credit scoring and fraud detection in Saudi banking networks. Riyadh-based financial institutions drive procurement volumes for supervised learning platforms with explainable output requirements.
- Natural Language Processing:Transformer architectures process Arabic dialect variations for customer service automation. UAE telecom operators deploy these systems for call center augmentation, prioritizing regional data sovereignty over English-language benchmark performance.
- Image Recognition:Computer vision systems automate radiology workflows in SFDA-registered hospital deployments.
- Robotics:Autonomous systems integrate with Dubai smart city infrastructure for logistics and surveillance applications.
Today's leader: Machine Learning. Tomorrow's challenger: Natural Language Processing.
Application:
Cost tier differentiation separates sovereign-funded deployments from commercial self-financed implementations, with government contracts carrying stricter data residency compliance burdens.
- Healthcare:Diagnostic imaging algorithms require dual FDA-SFDA clearance for hospital network procurement. Saudi Arabia's Ministry of Health mandates algorithmic transparency documentation that extends vendor qualification timelines.
- Smart Cities:Edge-computing deployments with sub-10 millisecond latency requirements dominate Dubai and Abu Dhabi government tenders. Transportation and public safety applications specify operational KPIs rather than technical benchmarks.
- Banking:Predictive analytics for fraud detection integrates with legacy mainframe architectures resistant to standard API protocols.
- Retail:Customer behavior analytics platforms process point-of-sale data for inventory optimization in UAE mall networks.
Healthcare commands current procurement volumes. Smart Cities offer the steepest expansion trajectory as sovereign AI infrastructure scales.
End User:
Volume concentration among government agencies shapes vendor pricing structures, with outcome-based contracts replacing perpetual software licenses in Riyadh and Abu Dhabi tenders.
- Government Agencies:Sovereign AI strategies in Saudi Arabia and the UAE mandate domestic data center deployment for national security applications. SDAIA and the UAE's National Artificial Intelligence Strategy establish compliance frameworks that filter market access.
- Enterprises:Banking and retail conglomerates in Dubai and Riyadh deploy customer-facing AI with shorter procurement cycles than public sector counterparts.
- Healthcare Providers:Hospital networks in Jeddah and Abu Dhabi specialize procurement for diagnostic imaging and patient management systems.
- Education:Universities and technical institutes develop Arabic NLP training datasets for regional model development.
Government Agencies dominate contract values. Enterprises represent the fastest-climbing adoption curve as cloud AI services expand.
Technology:
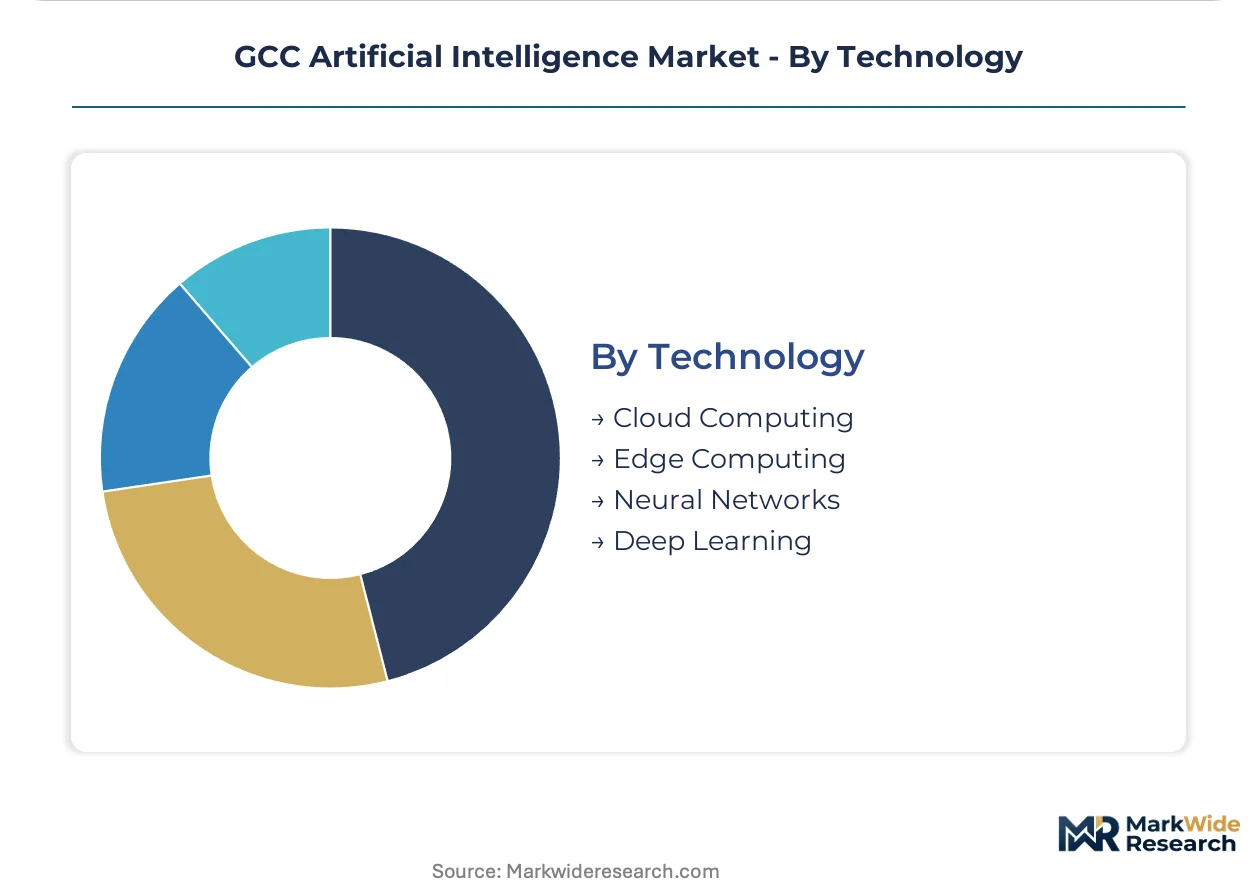
Margin pools concentrate in Deep Learning infrastructure as sovereign investments prioritize autonomous systems and predictive analytics capabilities over commoditized cloud services.
- Deep Learning:Multi-layer neural networks trained on millions of parameters enable autonomous decision-making in high-stakes applications. Mubadala Investment Company's technology allocations target domestic AI chip design to reduce dependency on US export-licensed hardware.
- Cloud Computing:Microsoft and Amazon Web Services operate UAE and Saudi data center regions to satisfy data localization mandates. Sovereign cloud partnerships with local entities satisfy SDAIA and PDPL requirements.
- Edge Computing:Distributed processing architectures meet latency requirements for Dubai smart city transportation and public safety deployments.
- Neural Networks:Foundation model architectures underpin Arabic-language large language model development for regional dialect specialization.
Deep Learning captures premium positioning. Edge Computing is gaining share fastest as latency-sensitive deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors GCC AI infrastructure deployment through SDAIA-backed sovereign data center construction. Government procurement concentrates in Saudi Arabia and the UAE, with Kuwait and Qatar accelerating specialized investments in healthcare and finance automation.
Saudi Arabia
The Saudi Data and Artificial Intelligence Authority drives diagnostic imaging procurement across Ministry of Health hospital networks. The Personal Data Protection Law mandates data residency for all AI service providers, extending vendor onboarding timelines. Riyadh's smart city clusters concentrate edge-computing deployments for transportation and public safety applications.
United Arab Emirates
Dubai's government-backed smart city initiatives generate concentrated demand for sub-10 millisecond latency AI systems. The National Artificial Intelligence Strategy 2031 requires algorithmic impact assessments for healthcare and finance applications. Abu Dhabi hosts Mubadala Investment Company's technology allocations targeting domestic AI chip design capabilities.
Qatar
Qatar's healthcare sector accelerates computer vision adoption for radiology workflow automation in Hamad Medical Corporation facilities. The national data protection framework shapes compliance requirements for foreign AI vendors. Doha's education and research institutes develop Arabic natural language processing training datasets for regional model specialization.
Kuwait
Kuwaiti banking networks deploy machine learning platforms for fraud detection and credit scoring automation. The central bank's technology governance guidelines influence procurement standards for predictive analytics vendors. Kuwait City's financial district concentrates enterprise AI adoption among retail and investment banking conglomerates.
Bahrain
Bahrain's fintech regulatory sandbox attracts AI-enabled financial service providers seeking Gulf market entry. The national cloud-first policy mandates sovereign infrastructure for government AI deployments. Manama's financial services cluster drives demand for compliant customer service automation platforms.
GCC Artificial Intelligence Market Key Industry Players
Established technology conglomerates occupy the standard tier; emerging regional specialists pursue sovereign compliance differentiation. The vendor base stratifies across GPU hardware suppliers, hyperscale cloud operators, and localized enterprise application developers. Three archetypes dominate: US-based semiconductor and cloud providers with direct allocation agreements, European enterprise software vendors with regional localization capabilities, and Gulf-based system integrators with regulatory compliance expertise. Competitive positioning depends on data center region expansion and sovereign partnership formation.
Within the hardware-tier, Nvidia Corporation and Intel Corporation anchor GPU and accelerator supply for sovereign AI infrastructure projects. Microsoft Corporation and Amazon Web Services, Inc. exemplify hyperscale cloud providers operating UAE and Saudi data center regions to satisfy localization mandates. SAP Middle East & North Africa LLC represents the localized enterprise application archetype, with regulatory-tailored positioning across Gulf compliance environments.
| Leading Market Players |
|---|
| Nvidia Corporation |
| Intel Corporation |
| Amazon Web Services, Inc. |
| SAP Middle East & North Africa LLC |
| Samsung Electronics Co. Ltd |
| Google LLC |
| Oracle Corporation |
| Siemens Middle East Limited |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
Captive sovereign data center construction across Saudi Arabia and the UAE anchors supply positioning while compressing pricing power for foreign cloud providers facing SDAIA-mandated localization requirements. This integration pattern concentrates procurement leverage among Gulf government entities specifying outcome-based contracts over perpetual software licenses.
Pricing Analysis
Input-cost pass-through from US Commerce Department GPU export licensing delays intensifies pricing pressure on sovereign AI infrastructure deployments. Three-tier pricing structure across premium certified, standard compliant, and economy non-resident levels separates vendors with SDAIA-approved data centers from those relying on cross-border service delivery. Cost compression in the economy tier reflects extended vendor onboarding cycles under Saudi Arabia's PDPL compliance assessments. Government agencies exhibit lowest price sensitivity due to sovereign budget allocations, while mid-market enterprises in Dubai and Riyadh drive hardest bargain on cloud AI service contracts.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced GPU fabrication, while US-based Nvidia Corporation controls training hardware architecture licensing. Raw material dependencies span high-bandwidth memory modules from SK Hynix and Samsung Electronics, advanced packaging substrates from Japan, and specialized cooling systems from German industrial suppliers. Tariff exposure through US export control classifications on AI accelerators threatens procurement timelines for Saudi sovereign data center builds. Distribution runs through hyperscale cloud operators establishing UAE and Saudi data center regions under sovereign partnership structures with local entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC AI market reads as a late-cycle quality story as procurement shifts from generic cloud services toward SDAIA-certified sovereign infrastructure with algorithmic transparency documentation.
For Market Incumbents: Deploy sovereign partnership formation as the primary defensive lever. Microsoft Corporation and Amazon Web Services should accelerate UAE and Saudi data center region expansion to preempt local competitor entry. Nvidia Corporation must secure direct allocation agreements with SDAIA-backed infrastructure projects before domestic chip design capabilities mature under Mubadala Investment Company allocations. Certification investment in PDPL compliance documentation extends vendor qualification timelines, creating moats against unqualified foreign providers. For New Entrants and Emerging Players: Mid-market healthcare providers in Jeddah and Doha represent an underserved buyer archetype seeking FDA-SFDA dual-cleared diagnostic imaging platforms without hyperscale cloud lock-in. Arabic natural language processing specialization for Gulf dialect variations offers the most penetrable segment, with deployment timelines compressing from 18 months to under 6 months for compliant vendors. A go-to-market angle through Dubai's MOHAP regulatory sandbox accelerates market entry for imaging software vendors lacking regional track records. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with SDAIA compliance expertise because sovereign data localization mandates fragment procurement across six Gulf states with non-harmonized regulatory frameworks. Long-term viability centers on acquisition targets possessing established government reference implementations in Riyadh or Abu Dhabi. The signal to watch is Mubadala Investment Company technology portfolio allocations toward domestic AI chip design, which would displace import-dependent training hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Expansion | Microsoft and AWS UAE-Saudi region buildout satisfies SDAIA data residency mandates for government contracts. |
| Regulatory Sandbox Entry | MOHAP diagnostic algorithm sandbox accelerates FDA-SFDA dual clearance for imaging software vendors. |
| Arabic NLP Model Development | Saudi telecom operators deploy dialect-optimized transformers, compressing conversational AI project timelines. |
| Domestic Chip Design Investment | Mubadala allocations target AI accelerator fabrication to reduce GPU import dependency under US export controls. |
| Outcome-Based Contracting | Riyadh government tenders specify diagnostic accuracy KPIs rather than technical specifications, favoring proven vendors. |
Research Approach
Direct dialogue with SDAIA policy officers, UAE National AI Strategy implementation leads, hospital procurement managers at Saudi Ministry of Health networks, and hyperscale cloud regional directors grounded qualitative findings. Secondary validation drew from SDAIA regulatory filings, PDPL compliance documentation, MOHAP medical device guidelines, hyperscaler capex disclosures, and Gulf sovereign wealth technology portfolio allocations. Bottom-up deployment tracking across Riyadh and Dubai smart city projects triangulated against top-down sovereign budget commitment analysis.
Bottom-up segment modeling across machine learning platforms, natural language processing systems, computer vision deployments, and robotics applications combined with top-down GDP-linked technology spending elasticity estimates. Segmentation dimensions included product type, application vertical, end-user category, and technology layer across the analysis window. CAGRs derived from deployment timeline compression observed in Arabic NLP projects and sovereign data center construction schedules. Forecast inputs incorporated US Commerce Department GPU export licensing queue lengths and Saudi grid capacity expansion plans for megawatt-scale training clusters.
Underlying measurement precision varies by segment; government procurement data carries tighter precision than enterprise cloud spending estimates. Forecasts reflect assumptions around SDAIA framework stability, PDPL enforcement consistency, and US export control policy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Global Enterprise Artificial Intelligence Market
Artificial Intelligence (AI)
North America Chatbot Market