
 AI Orchestration Market | 2026-2036
AI Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
AI Orchestration Market Intelligence
Cloud marketplace channels is reconfiguring how enterprises procure and integrate AI orchestration tools. Microsoft Azure AI leverages its existing enterprise relationships to anchor platform adoption across hybrid environments. Google Cloud Vertex AI competes through deep integration with proprietary infrastructure and custom silicon. Amazon Bedrock extends its parent company's distribution reach by embedding orchestration within broader cloud consumption bundles.
AI orchestration denotes the automated coordination, scheduling, and governance of multiple artificial intelligence models, data pipelines, and compute resources across distributed environments. The discipline employs API abstraction layers, containerized execution frameworks, and policy engines to enforce latency thresholds, cost controls, and failover protocols. Cloud deployment configurations capture the dominant margin pool as organizations prioritize elastic scaling over capital-intensive on-premises infrastructure. Workflow automation applications within the application dimension attract disproportionate investment as enterprises seek to reduce manual handoffs between generative and predictive models. Managed services in the service type category expand fastest where internal MLOps expertise remains scarce.
The EU AI Act imposes risk-tiered compliance obligations on automated systems processing personal or sensitive operational data, directly elevating demand for governance-native orchestration platforms. HIPAA in the United States constrains how healthcare end users chain together diagnostic and administrative models, creating specialized requirements for audit trails and access controls. Stakeholders must evaluate whether their orchestration architectures can absorb emerging jurisdictional fragmentation without fragmenting operational consistency.
Market Dynamics
Multi-model pipeline complexity is forcing enterprises to abandon point solutions in favor of unified orchestration layers that abstract API fragmentation and enforce cross-functional governance.
Growth Catalysts
- EU AI Act compliance mandates:Risk-tiered obligations for automated decision systems are compelling financial services and healthcare enterprises to deploy governance-native orchestration platforms with built-in audit trails.
- Containerized execution frameworks:Kubernetes-native orchestration is accelerating deployment velocity for MLOps teams managing heterogeneous model portfolios across hybrid cloud environments.
- Healthcare diagnostic chaining:HIPAA-constrained institutions require specialized orchestration to link administrative and clinical AI models while preserving patient data segmentation.
Market Restraints
- GPU compute cost volatility:Elastic scaling dependencies on NVIDIA and AMD silicon expose orchestration workloads to input cost swings that compress margin predictability.
- API standardization gaps:Absence of universal model interface protocols forces custom integration layers that extend deployment timelines.
- On-premises infrastructure drag:Capital-intensive legacy data center investments in regulated industries slow cloud-native orchestration migration.
Strategic Opportunities
- India's BIS certification pathway:Emerging data localization requirements create first-mover advantage for orchestration vendors establishing sovereign cloud partnerships.
- Edge-to-cloud model federation:Convergence of 5G low-latency networks with container orchestration enables real-time inference distribution for manufacturing and autonomous systems.
- Cloud marketplace procurement:Hyperscaler distribution channels are displacing direct enterprise sales cycles, reducing customer acquisition friction.
Industry Challenges
- MLOps talent scarcity:Shortage of engineers proficient in both Kubernetes infrastructure and model governance is extending implementation timelines.
- Interoperability with legacy middleware:Integration complexity with existing SOA and ESB investments demands costly bridge architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Orchestration Market |
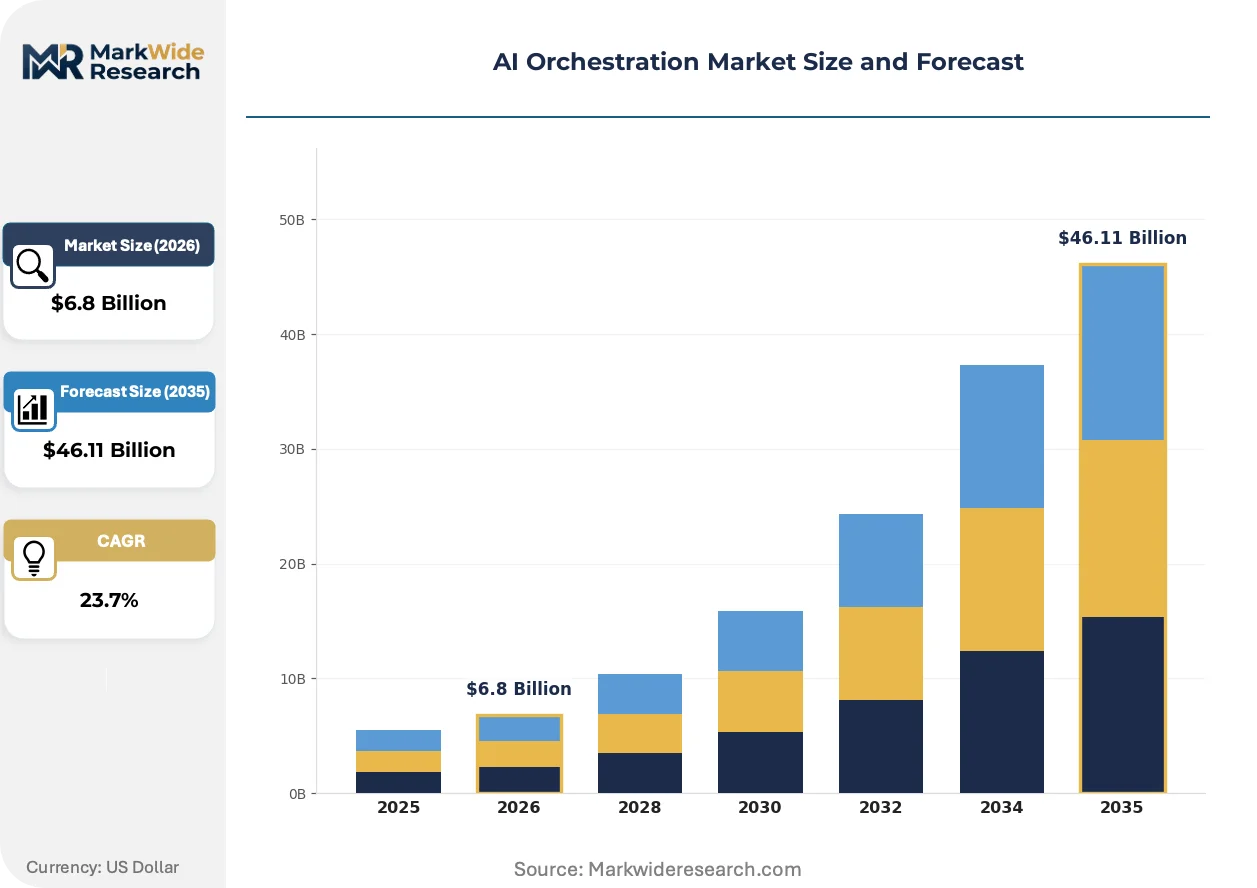
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $46.11 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Multi-Cloud End User: Healthcare, Retail, Financial Services, Telecommunications Service Type: Consulting, Integration, Managed Services, Support Application: IT Operations, Customer Experience, Data Management, Workflow Automation |
| Companies Covered | Amazon Bedrock, VectorShift, Zapier, Microsoft Azure AI, Haystack, LangChain, Flyte, Google Cloud Vertex AI, Prefect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Orchestration Market Strategic Shifts & Innovations
Architectural convergence between generative and predictive AI pipelines is collapsing previously separate tooling categories into unified orchestration stacks.
Agentic workflow engines are hybridizing deterministic automation with probabilistic model outputs. Enterprise IT departments are deploying these systems to coordinate multi-step business processes spanning retrieval-augmented generation and structured prediction. Financial services workflows in the United States and Germany are compressing manual handoff points between model types.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for high-risk automated systems. Deployers must maintain technical documentation and human oversight protocols that elevate demand for governance-embedded orchestration. Healthcare and credit-scoring applications across France, Germany, and the Netherlands are restructuring compliance workflows.
Consumption-based pricing for orchestration services is displacing perpetual license models in enterprise procurement. Hyperscaler marketplaces are capturing preference share from direct vendor relationships. Manufacturing and logistics verticals in Japan and South Korea are piloting usage-metered orchestration for seasonal demand spikes.
AI Orchestration Market Segmentation
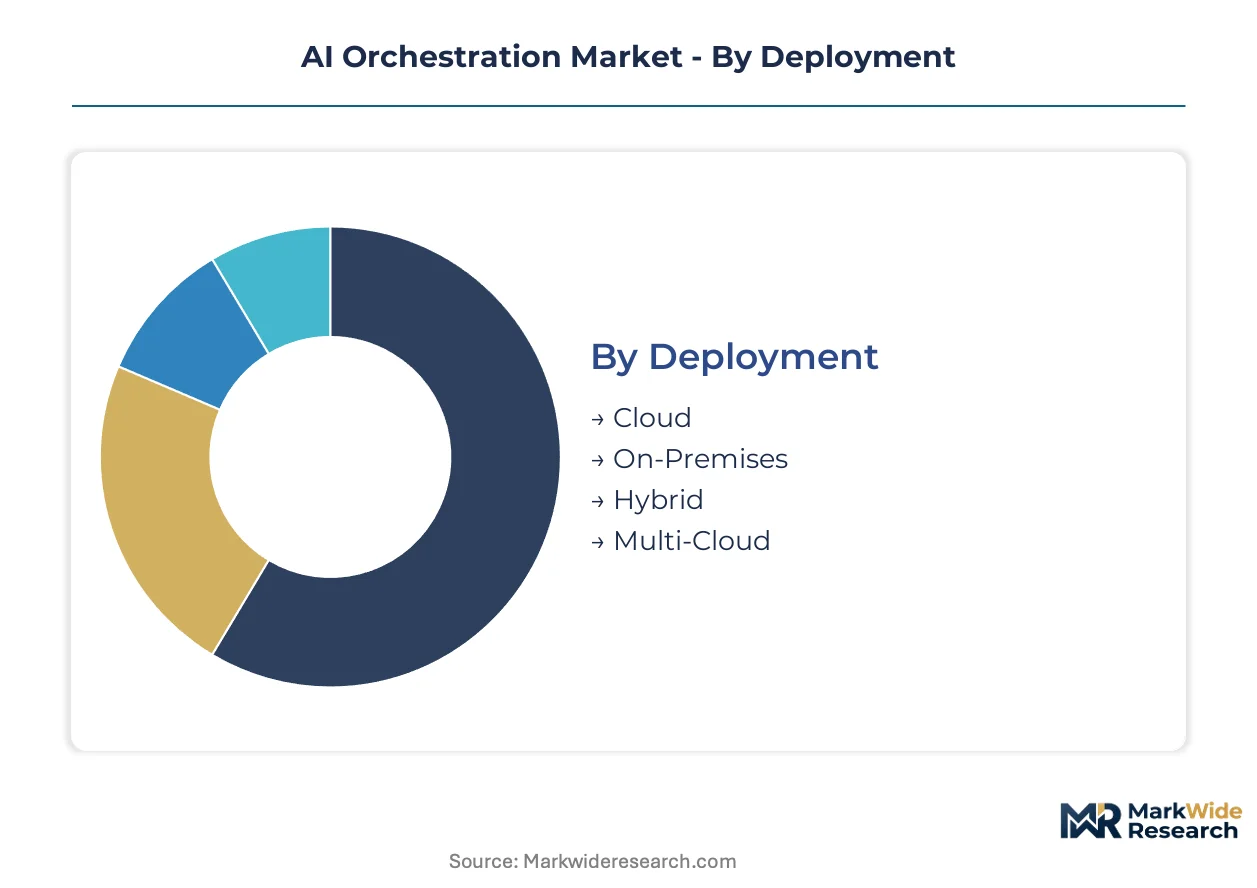
AI orchestration architectures diverge sharply across deployment topologies, end-user compliance regimes, and service delivery models. Understanding these segment boundaries enables vendors to align pricing mechanics with operational constraints and procurement patterns.
Deployment:
Cloud-native configurations dominate elastic workloads, while regulated industries retain hybrid footprints to satisfy data residency mandates.
- Cloud:Hyperscaler-hosted orchestration layers abstract GPU provisioning and API management through containerized execution frameworks. Financial services firms in the United States deploy these configurations to compress model deployment cycles while offloading infrastructure capital to operational expenditure lines.
- On-Premises:Dedicated infrastructure maintains physical control over sensitive training data and inference logs through air-gapped or sovereign data center deployments. Healthcare institutions constrained by HIPAA audit requirements in the United States favor this topology despite higher total cost of ownership.
- Hybrid:Split architectures route non-sensitive preprocessing to cloud elastic pools while retaining patient records or proprietary algorithms in controlled environments.
- Multi-Cloud:Vendor-agnostic orchestration abstracts API differences across AWS, Azure, and Google Cloud to prevent single-provider lock-in and negotiate favorable compute pricing.
Established volume favors Cloud; emerging adoption favors Hybrid.
End User:
Regulatory intensity and model chain complexity create divergent orchestration requirements across vertical sectors.
- Healthcare:Clinical and administrative AI pipelines demand strict segmentation between diagnostic models and operational systems. HIPAA compliance in the United States mandates immutable audit trails for every model invocation affecting patient care decisions.
- Financial Services:Credit-scoring and fraud-detection workflows integrate predictive and generative models across real-time transaction streams. EU AI Act risk-tiered obligations in Germany and France are restructuring procurement specifications for algorithmic impact assessments.
- Retail:Demand forecasting and personalized recommendation engines prioritize latency optimization over governance depth.
- Telecommunications:Network optimization and customer churn prediction models operate at massive scale with standardized API interfaces.
Financial Services commands premium pricing; Healthcare exhibits steepest expansion trajectory as diagnostic chaining matures.
Service Type:
Internal capability gaps determine whether enterprises purchase advisory expertise, integration labor, or fully outsourced operations.
- Consulting:Advisory engagements assess MLOps maturity, design governance frameworks, and map compliance requirements to technical architectures.
- Integration:Implementation services connect orchestration layers to existing data warehouses, model registries, and business intelligence platforms.
- Managed Services:Third-party teams assume responsibility for pipeline monitoring, model retraining schedules, and incident response. Scarcity of Kubernetes-certified MLOps engineers in Japan and South Korea is accelerating procurement of these offerings.
- Support:Tiered response contracts provide escalation paths for production orchestration failures and API deprecation events.
Integration captures near-term project revenue; Managed Services builds recurring margin pools.
Application:
Functional use cases determine which orchestration capabilities receive investment priority and engineering attention.
- Workflow Automation:Agentic engines coordinate multi-step business processes spanning retrieval-augmented generation and structured prediction. Manufacturing and logistics operators in Japan are piloting these systems to compress manual handoffs between generative and predictive model outputs.
- IT Operations:Automated incident response and capacity planning integrate observability data with predictive failure models.
- Customer Experience:Real-time personalization pipelines balance latency constraints against model freshness requirements.
- Data Management:Pipeline orchestration ensures data quality gates, lineage tracking, and regulatory retention policies execute consistently across distributed storage.
IT Operations represents mature spend; Workflow Automation gains share fastest as agentic architectures commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler data center interconnects and subsea cable landings in the United States, Germany, Japan, India, and Singapore create the physical substrate for AI orchestration demand concentration. These infrastructure nodes determine latency baselines, data residency compliance, and cloud marketplace access.
United States
Financial services firms in Manhattan and Chicago deploy multi-model pipelines for real-time fraud detection and algorithmic trading. HIPAA constrains healthcare orchestration in Boston and San Francisco, mandating immutable audit trails for diagnostic AI chains. The SEC's proposed rules on predictive data analytics are reshaping compliance specifications for automated investment advice systems.
Germany
Automotive manufacturers in Stuttgart and Munich chain together generative design models with predictive quality systems. The EU AI Act's risk-tiered obligations are restructuring procurement for credit-scoring and insurance underwriting workflows. Industrial clusters in Bavaria and Baden-Württemberg are piloting sovereign cloud partnerships to satisfy data localization requirements.
Japan
Manufacturing operators in Nagoya and Osaka are deploying agentic workflow engines to compress manual handoffs between predictive maintenance and generative process optimization. METI's guidance on AI governance is elevating demand for embedded audit capabilities. The Kanto region around Tokyo concentrates managed services procurement where Kubernetes-certified MLOps engineers remain scarce.
India
IT services exporters in Bangalore and Hyderabad are building orchestration layers for multinational clients seeking cost-optimized model deployment. BIS certification pathways for AI systems are creating first-mover advantage for vendors establishing sovereign cloud partnerships. Mumbai's financial district is adopting hybrid architectures to route sensitive data through local infrastructure while leveraging elastic cloud pools.
Singapore
Wealth management and trade finance institutions deploy orchestration for cross-border compliance automation. The Monetary Authority of Singapore's framework for responsible AI use is mandating governance-native platform selection. The city-state's subsea cable hub status positions it as a regional inference distribution node for Southeast Asian markets.
AI Orchestration Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the workflow engine and model abstraction layers. The vendor base clusters around three strategic positions: hyperscaler-native stacks, open-source framework providers, and vertical workflow automation platforms. Consolidation pressure is mounting as enterprises favor unified orchestration over point solutions. Competitive moves center on cloud marketplace distribution deals and Kubernetes-native certification programs.
Among hyperscaler-backed platforms, Amazon Bedrock, Microsoft Azure AI, and Google Cloud Vertex AI exemplify the integrated stack archetype, each leveraging parent infrastructure and enterprise relationships to anchor adoption. Open-source framework specialists including LangChain and Haystack occupy positions upstream, supplying abstraction layers that hyperscalers embed or enterprises self-host. Workflow automation incumbents such as Zapier represent a distinct tier, extending existing integration graphs into AI model chaining.
| Leading Market Players |
|---|
| Amazon Bedrock |
| VectorShift |
| Zapier |
| Microsoft Azure AI |
| Haystack |
| LangChain |
| Flyte |
| Google Cloud Vertex AI |
| Prefect |
| Others |
Cost & Logistics Intelligence
GPU export-control chokepoints from the United States determine both the pricing tier spreads between sovereign-cloud and hyperscaler-native deployments and the geographic restructuring of supply chains toward ASEAN assembly nodes.
Pricing Analysis
Volume-discount tiering structures separate enterprise-wide orchestration licenses from pay-per-inference consumption models. Three-tier pricing stratifies across governance-native premium stacks, standard containerized frameworks, and economy API abstraction layers. Price differentiation hinges on compliance certification depth and multi-cloud abstraction sophistication. Pricing pressure stems from hyperscaler marketplace bundling that compresses standalone orchestration margins. Healthcare institutions in the United States exhibit the lowest price sensitivity due to HIPAA-mandated audit requirements, while retail demand forecasting buyers prioritize cost minimization over governance depth.
Supply Chain Analysis
Export-control regimes limiting NVIDIA H100 and AMD MI300 flows to China and Russia fragment GPU supply availability across regional orchestration providers. Supply concentrates in Taiwan for advanced silicon fabrication, the United States for chip design and cloud infrastructure, and South Korea for memory components. Raw material dependencies span high-bandwidth memory modules, custom ASIC wafers, and specialized networking fabrics. Single-source vulnerability in Taiwan Semiconductor Manufacturing exposes orchestration platform providers to capacity allocation disruptions. Distribution runs through hyperscaler direct-procurement channels and sovereign-cloud partnership agreements rather than traditional IT value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in AI orchestration have reached an inflection where Kubernetes-native certification programs and cloud marketplace interoperability determine ecosystem lock-in and procurement gravity.
For Market Incumbents: Insulate core enterprise relationships through embedded governance modules that preempt EU AI Act compliance audits. Deepen backward integration into custom silicon partnerships to offset NVIDIA supply allocation uncertainty. Anchor platform stickiness via MLOps certification programs that create switching costs for Kubernetes-proficient engineering teams. For New Entrants and Emerging Players: Pursue white-space opportunities in India's BIS-certified sovereign cloud partnerships where hyperscaler presence remains underdeveloped. Target workflow automation gaps in Japanese manufacturing clusters where agentic engine adoption outpaces local vendor supply. Lead with consumption-based pricing that undercuts perpetual-license incumbents on total cost of ownership metrics. For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape toward governance-native orchestration platforms with embedded audit capabilities. Long-term viability centers on vendors whose architectures absorb jurisdictional fragmentation without operational inconsistency. Prioritize targets with proven Kubernetes-native deployments across hybrid cloud environments. Watch for hyperscaler marketplace revenue concentration exceeding direct sales as an inflection signal of channel dependency risk.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Marketplace Integration | Hyperscaler distribution embeds orchestration within broader consumption bundles that reduce procurement friction. |
| Governance-Native Certification | EU AI Act compliance modules differentiate platforms in financial services and healthcare procurement evaluations. |
| Kubernetes-Native Deployment | Container orchestration standardization accelerates MLOps velocity across hybrid and multi-cloud environments. |
| Sovereign Cloud Partnership | Data localization requirements in India and Germany create first-mover advantage for regional infrastructure alliances. |
| Agentic Workflow Engine Launch | Multi-step business process automation compresses manual handoffs between generative and predictive model outputs. |
Research Approach
Cross-validation between primary fieldwork with MLOps directors and secondary analysis of hyperscaler capex disclosures anchors the qualitative findings. Interviews with platform engineering leads, IT procurement officers at financial services firms, healthcare compliance officers, and Kubernetes-certified systems integrators informed demand-side segmentation. Secondary sources encompassed SEC 10-K infrastructure investment disclosures, EU AI Act implementation guidance, HIPAA audit protocol documentation, and cloud marketplace revenue recognition patterns. Bottom-up deployment topology sizing and top-down vertical spending allocation were reconciled through iterative triangulation.
Calibration against historical adoption curves for container orchestration and enterprise SaaS procurement patterns shaped the analytical framework. Segmentation dimensions modeled encompass deployment topology, end-user vertical, service delivery model, and application function across the projection horizon. CAGRs were derived from elasticity-adjusted spending trajectories by vertical and deployment configuration. Forecast inputs incorporated GPU supply allocation constraints, regulatory implementation timelines, and MLOps talent availability by geography.
Sensitivities concentrate around export-control expansion, EU AI Act enforcement intensity, and hyperscaler marketplace fee structure revisions. Forecasts reflect documented assumptions regarding cloud migration velocity and compliance-driven procurement specification changes. Material shifts in GPU supply geography or algorithmic accountability rulemaking would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market