
 Brain Machine Interface Market | 2026-2036
Brain Machine Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Machine Interface Market Analysis
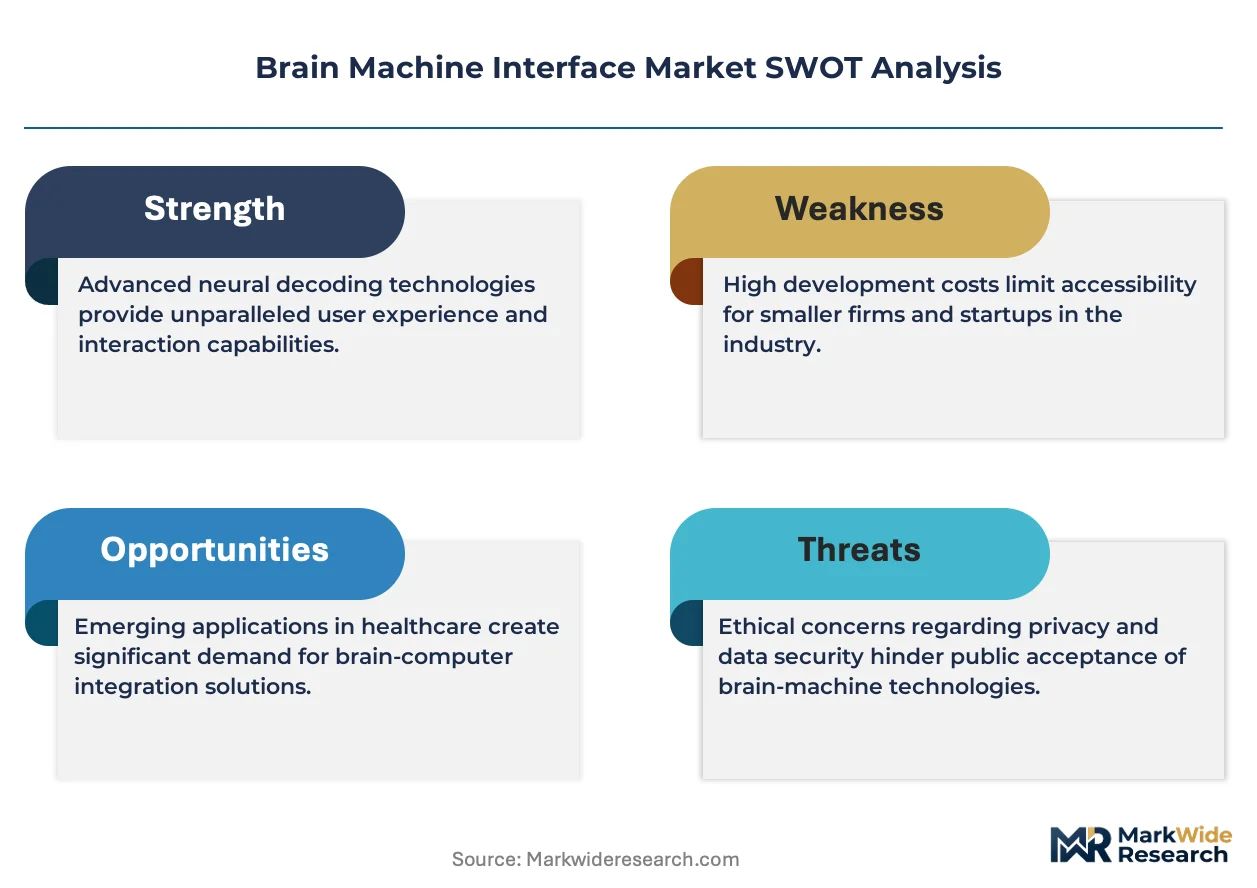
Subscription-based neural data analytics is consolidating recurring revenue models alongside hardware sales in the brain machine interface sector. Neuralink leverages vertical integration from chip fabrication to surgical robotics, sustaining full-stack control over its implant pipeline. Blackrock Neurotech anchors its position through decades of microelectrode array refinement, while Synchron competes via endovascular delivery that eliminates open-brain surgery. Emotiv differentiates through consumer-grade electroencephalography headsets that occupy the non-invasive tier.
Brain machine interfaces constitute direct communication pathways between neural structures and external devices, typically employing microelectrode arrays with electrode counts ranging from dozens to over ten thousand channels to record or stimulate electrical activity. These systems serve primarily to restore lost sensory or motor functions, augment human cognition, or enable control of prosthetic and digital systems through decoded neural signals. Invasive microelectrode arrays capture the deepest signal fidelity and command premium pricing, while non-invasive electroencephalography dominates volume through lower barriers to entry and broader clinical accessibility. Neuroprosthetics applications lead absolute spending due to spinal cord injury and amputation patient populations, yet cognitive restoration segments attract accelerating research investment from defense and longevity-focused commercial enterprises.
The FDA breakthrough device program and HIPAA privacy frameworks shape United States market access timelines and data governance obligations for neural interface developers. The EU AI Act and MDR impose additional conformity requirements on systems employing machine learning for signal decoding or closed-loop stimulation. Stakeholders must monitor evolving regulatory precedents for brain data ownership and algorithmic transparency as jurisdictions establish first-mover frameworks for neurotechnology governance.
Market Dynamics
Neural signal decoding algorithms are compressing the latency gap between thought and device response, forcing hardware manufacturers to synchronize electrode density gains with real-time processing architectures.
Growth Catalysts
- FDA breakthrough device designation:The pathway accelerates pre-market review timelines for implantable neural interfaces, reducing capital lock-up periods for developers pursuing motor restoration indications.
- Neuroprosthetic demand from spinal cord injury populations:Healthcare institutions in the United States are expanding reimbursement coverage for motor restoration applications, creating predictable procurement pipelines.
- Solid-state electrode materials:Transition from thin-film metals to carbon-based conductive polymers is extending device longevity and reducing foreign body response rates.
Market Restraints
- Platinum-iridium alloy supply concentration:Microelectrode fabrication depends on refined precious metal feedstocks concentrated in South African and Russian mining operations, exposing manufacturers to input cost volatility.
- EU MDR conformity assessment bottlenecks:The extended review timelines for active implantable medical devices are delaying commercial launches in European markets by 18-24 months relative to FDA clearance.
- Signal fidelity degradation from glial scarring:Chronic inflammatory responses to penetrating electrodes limit functional lifespan of invasive interfaces to 3-5 years in most patient populations.
Strategic Opportunities
- Endovascular delivery platforms:Synchron's stent-electrode approach eliminates craniotomy requirements, opening addressable markets for patients excluded from open-brain surgical candidacy.
- Defense cognitive augmentation programs:DARPA-funded research into non-invasive attention and memory enhancement is creating dual-use technology transfer pathways to commercial wellness applications.
- Subscription neural data analytics:Recurring revenue models for signal processing and cloud-based decoding are supplementing one-time hardware sales with 40-60% gross margin software services.
Industry Challenges
- Neuroelectrophysiology talent scarcity:The intersection of electrical engineering, neuroscience, and clinical trial design requires specialized expertise concentrated in Boston, San Francisco, and Zurich academic clusters.
- ISO 14155 clinical investigation compliance:Multi-site trials for neural interfaces face protocol harmonization complexity across institutional review boards with divergent risk tolerance for first-in-human brain implant studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Machine Interface Market |
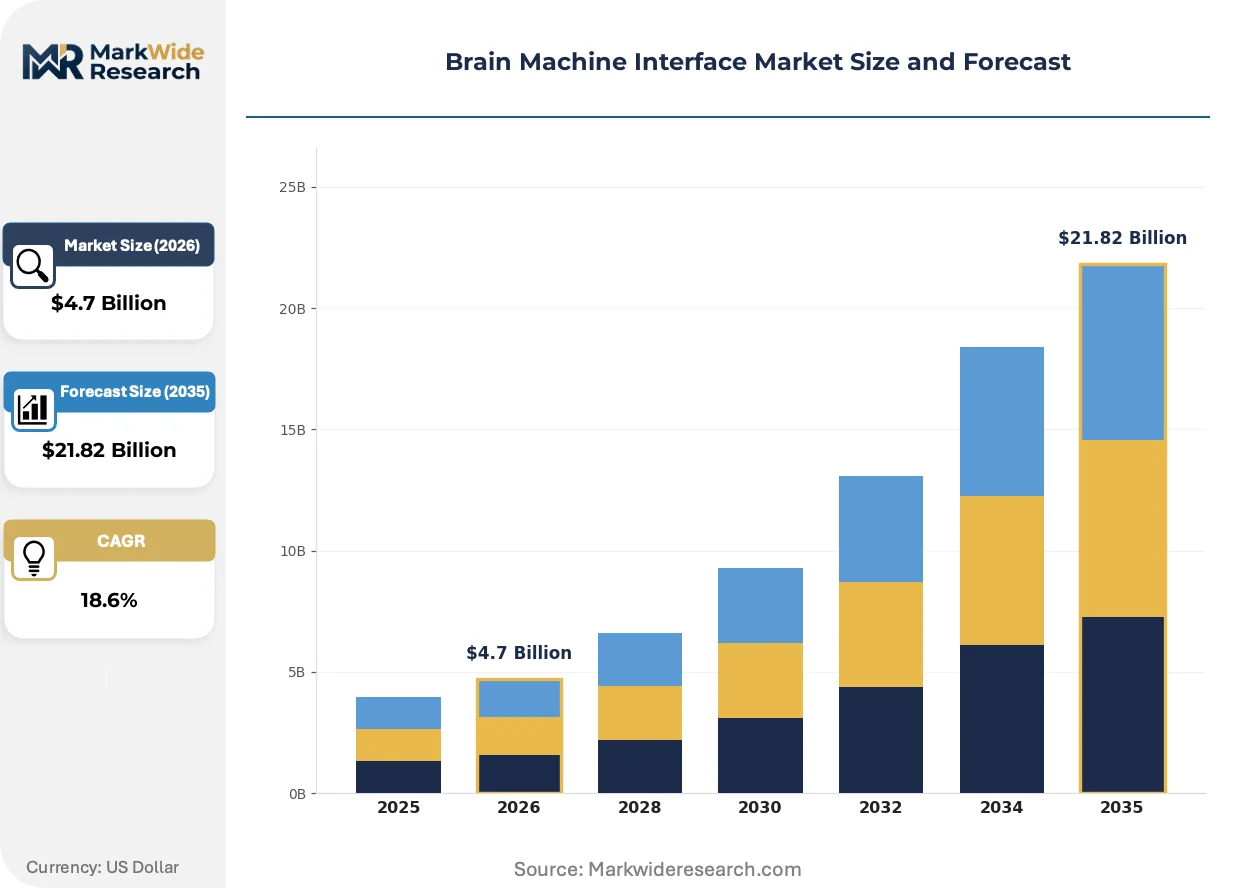
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive, Semi-invasive, Non-invasive, Implantable Devices Application: Assistive Technologies, Cognitive Restoration, Neuroprosthetics, Rehabilitation End User: Healthcare Institutions, Research Laboratories, Military, Commercial Enterprises Technology: Electrocorticography, Electroencephalography, Functional Magnetic Resonance Imaging, Microelectrode Arrays |
| Companies Covered | Neuralink, Synchron, Blackrock Neurotech, Paradromics, g.tec medical engineering GmbH, Emotiv, Advanced Brain Monitoring, Inc., NeuroSky, Kernel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Machine Interface Market Emerging Trajectories
Machine learning inference at the edge is displacing cloud-dependent processing architectures, enabling closed-loop stimulation with sub-10 millisecond response times that match biological reflex speeds.
Neuromorphic computing chips are automating spike sorting and feature extraction directly on implantable devices. Neuroprosthetic developers at Stanford and EPFL are piloting these architectures for real-time motor decoding. The shift is automating the signal processing bottleneck that previously required external compute tethering.
The EU AI Act risk classification framework is imposing conformity obligations on closed-loop neural interfaces employing adaptive algorithms. Systems categorized as high-risk must demonstrate algorithmic transparency and human oversight protocols. European developers are responding by segregating stimulation control logic from learning modules to reduce regulatory exposure.
Hospital procurement committees are consolidating vendor relationships around full-stack neural interface platforms rather than component sourcing. Integrated hardware-software-surgical service bundles are displacing point-solution purchasing at major academic medical centers. The pattern is most visible in the United States, where bundled payment models for spinal cord injury rehabilitation create incentives for single-vendor accountability.
Brain Machine Interface Market Segmentation
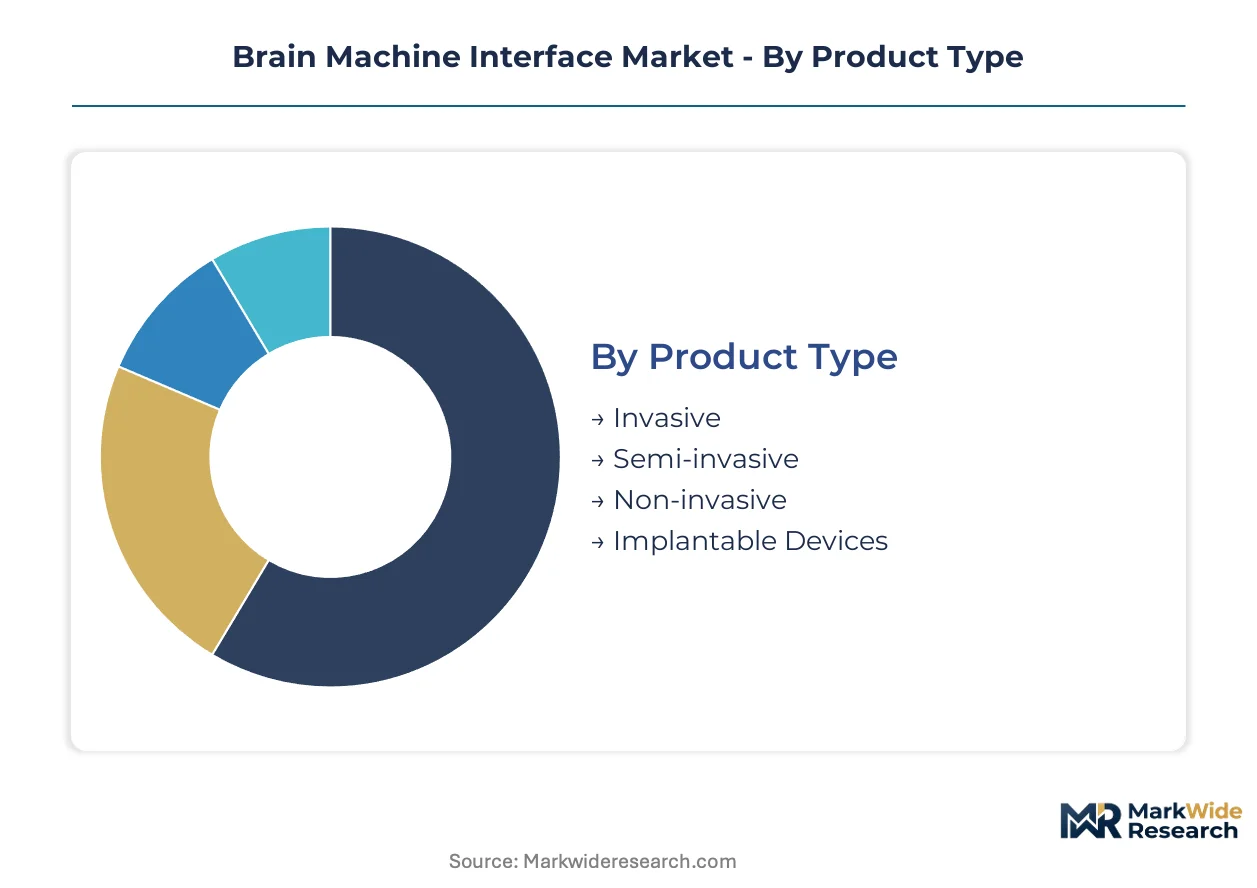
Segmentation in brain machine interfaces reveals how technical risk tolerance, clinical setting, and signal fidelity requirements partition purchasing behavior. Each dimension exposes distinct margin structures and regulatory pathways that shape vendor positioning.
Product Type:
Integration depth varies sharply across this category, with implantable systems demanding full-stack surgical service bundles while non-invasive hardware operates as standalone peripherals.
- Invasive:Penetrating microelectrode arrays achieve single-neuron resolution through cortical implantation. Demand clusters at academic medical centers in Boston and San Francisco pursuing motor restoration for spinal cord injury patients, constrained by the FDA's breakthrough device review timelines and glial scarring limitations on functional lifespan.
- Non-invasive:Electroencephalography headsets capture aggregate cortical activity through scalp electrodes without surgical risk. Volume concentrates in consumer wellness and research laboratory procurement, driven by lower capital barriers and HIPAA-compliant data handling requirements.
- Semi-invasive:Electrocorticography grids sit beneath the skull without penetrating parenchyma, balancing signal fidelity with reduced foreign body response.
- Implantable Devices:Fully embedded systems integrate electrodes, telemetry, and power management for chronic deployment.
Volume placements concentrate in non-invasive systems; the faster expansion belongs to invasive platforms as motor restoration indications mature.
Application:
Clinical utility and reimbursement status create tiered margin profiles across therapeutic categories.
- Neuroprosthetics:Motor restoration for amputation and spinal cord injury constitutes the largest absolute spending segment. Healthcare institutions in the United States are expanding bundled payment coverage for these procedures, creating predictable procurement cycles tied to rehabilitation outcomes.
- Cognitive Restoration:Memory and attention enhancement applications attract defense and longevity-focused investment. DARPA-funded research programs are accelerating technology transfer to commercial wellness markets, though regulatory pathways remain unsettled.
- Assistive Technologies:Communication and environmental control systems for locked-in syndrome patients leverage lower-bandwidth signal decoding.
- Rehabilitation:Stroke recovery and neuroplasticity training applications employ closed-loop feedback protocols.
Revenue concentration sits with neuroprosthetics; cognitive restoration is gaining share fastest through dual-use technology pipelines.
End User:
Purchasing sophistication and risk tolerance diverge across institutional buyer types.
- Healthcare Institutions:Academic medical centers and rehabilitation hospitals dominate invasive system procurement. These buyers demand integrated hardware-software-surgical service bundles with single-vendor accountability under bundled payment models.
- Research Laboratories:University and government labs drive non-invasive and semi-invasive volume through grant-funded acquisition cycles.
- Military:Defense cognitive augmentation programs fund non-invasive attention and memory enhancement research with classified technology transfer restrictions.
- Commercial Enterprises:Wellness and productivity applications represent emerging demand from employer-funded programs and direct-to-consumer channels.
Procurement volume clusters in healthcare institutions; military funding is expanding most quickly for cognitive augmentation.
Technology:
Signal fidelity, spatial resolution, and portability trade-offs define competitive positioning.
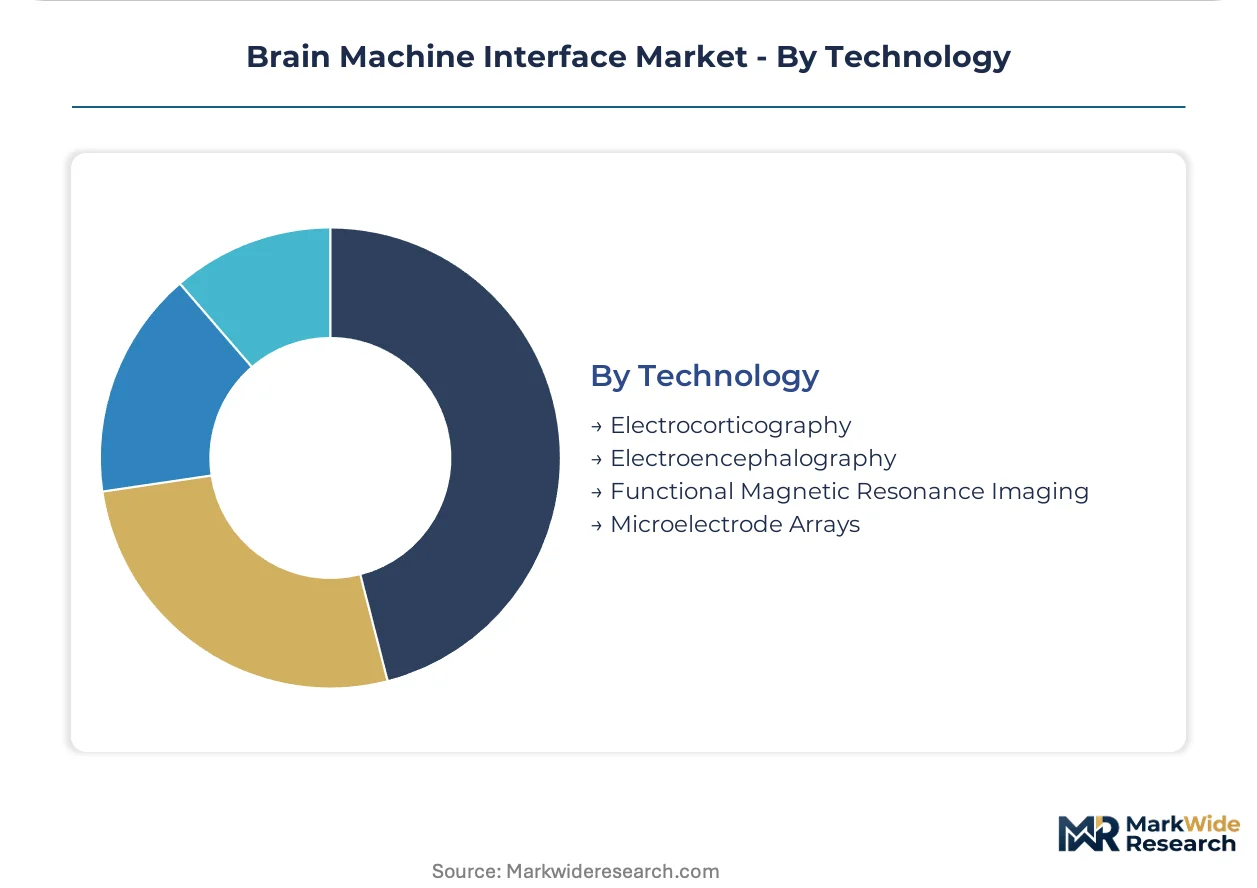
- Microelectrode Arrays:Utah arrays and Neuropixels probes achieve single-unit resolution through penetrating electrodes. Manufacturing depends on platinum-iridium alloy feedstocks concentrated in South African and Russian mining operations, exposing producers to input cost volatility.
- Electroencephalography:Scalp-mounted electrodes dominate volume through dry-contact and gel-based consumer headsets. Emotiv and similar vendors occupy this tier with sub-$500 hardware pricing.
- Electrocorticography:Subdural grids capture local field potentials with intermediate resolution for epilepsy monitoring and research.
- Functional Magnetic Resonance Imaging:Blood-oxygen-level-dependent imaging provides whole-brain coverage at coarse temporal resolution, confined to research and diagnostic settings.
Unit shipments concentrate in electroencephalography; microelectrode arrays command the steepest expansion trajectory as surgical robotics and neuromorphic edge processing mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of microelectrode arrays and surgical robotics concentrates in the United States and Germany, while clinical adoption spreads across healthcare systems with advanced neurosurgical infrastructure and favorable reimbursement frameworks.
United States
The FDA's breakthrough device designation pathway accelerates pre-market review timelines for implantable neural interfaces, reducing capital lock-up periods for developers. Venture funding clusters in Boston and San Francisco drive commercialization pipelines for motor restoration applications. Academic medical centers in these cities expand bundled payment coverage for spinal cord injury rehabilitation.
Germany
The EU MDR imposes extended conformity assessment timelines for active implantable medical devices, delaying commercial launches by 18-24 months relative to FDA clearance. German engineering firms supply precision microfabrication equipment for electrode array production. Research clusters in Munich and Heidelberg advance neuromorphic computing architectures for edge signal processing.
Switzerland
Swissmedic regulates neural interfaces under medical device frameworks with emphasis on algorithmic transparency for closed-loop systems. Swiss precision manufacturing capabilities support microelectrode component supply. The Lake Geneva region hosts neurotechnology research institutes collaborating with clinical partners in Lausanne and Geneva.
China
NMPA medical device registration requirements are evolving for neural interface products as domestic developers advance non-invasive electroencephalography systems. Manufacturing scale advantages in Shenzhen and Shanghai reduce hardware production costs for consumer-grade headsets. Government funding programs target brain-inspired computing and cognitive enhancement research.
United Kingdom
The Medicines and Healthcare products Regulatory Agency coordinates with FDA on parallel review pathways for breakthrough neural technologies. London-based research hospitals pilot endovascular delivery platforms for patients excluded from open-brain surgical candidacy. Oxford and Cambridge academic clusters contribute signal decoding algorithm development.
Brain Machine Interface Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the brain machine interface sector, with integrated surgical service providers commanding premium positioning against component specialists. The vendor base stratifies into three tiers: full-stack platform developers, modular hardware suppliers, and software analytics specialists. Dominant competitive moves include vertical integration from chip fabrication to surgical robotics and strategic partnerships bundling hardware with cloud-based neural data services.
Within the full-stack integration tier, Neuralink exemplifies capital-intensive vertical control spanning electrode manufacturing to surgical automation. Synchron occupies a distinct position through endovascular delivery approaches that eliminate craniotomy requirements. Blackrock Neurotech anchors the established specialist segment with decades of microelectrode array refinement heritage.
| Leading Market Players |
|---|
| Neuralink |
| Synchron |
| Blackrock Neurotech |
| Paradromics |
| g.tec medical engineering GmbH |
| Emotiv |
| Advanced Brain Monitoring, Inc. |
| NeuroSky |
| Kernel |
| Others |
Supply Flow & Price Mechanics
Neuroelectrophysiology talent concentration in Boston, San Francisco, and Zurich academic clusters creates labor-cost differentials that widen pricing-tier spreads between invasive implantable systems and consumer-grade non-invasive headsets.
Pricing Analysis
Cost-down pressure on invasive microelectrode arrays accelerates because platinum-iridium alloy feedstock volatility from South African and Russian mining operations compresses hardware margins. Pricing stratifies across premium implantable surgical bundles, standard research laboratory equipment, and economy consumer wellness peripherals. FDA breakthrough device certification commands substantial brand premium for motor restoration applications. Healthcare institutions demonstrate lowest price sensitivity due to bundled reimbursement models, while direct-to-consumer channels face acute price elasticity.
Supply Chain Analysis
Precision microfabrication workforce availability in Germany, the United States, and Switzerland anchors electrode array manufacturing capacity. Microelectrode production draws from refined precious metal feedstocks, carbon-based conductive polymers, and neuromorphic computing chips. Single-source vulnerability concentrates in platinum-iridium alloy supply from geopolitically exposed mining jurisdictions. Distribution runs through academic medical center procurement committees, research laboratory grant-funded acquisition cycles, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA breakthrough device designation pathway functions as a cost-of-compliance moat, elevating capital requirements for pre-market review and consolidating advantage among developers with established regulatory affairs infrastructure.
For Market Incumbents: Anchor market position through backward integration into surgical robotics and neuromorphic chip fabrication, eliminating supplier dependency for latency-critical signal processing components. Defend against endovascular delivery disruption by expanding stent-electrode R&D partnerships or acquisition of vascular access specialists. Prioritize ISO 14155 clinical investigation compliance investment to accelerate multi-site trial harmonization.
For New Entrants and Emerging Players: Begin with non-invasive electroencephalography wellness applications where FDA 510(k) pathways reduce regulatory capital requirements and Emotiv has established consumer price anchors. Target employer-funded cognitive enhancement programs as the most penetrable commercial channel. Pursue cloud-based neural data analytics subscriptions to capture recurring revenue before hardware commoditization.
For Investors and Strategic Acquirers: Re-rating potential sits with full-stack platform developers given FDA breakthrough device designation acceleration and bundled payment model expansion in spinal cord injury rehabilitation. Long-term viability favors vertically integrated players controlling electrode manufacturing through surgical service delivery. Watch DARPA cognitive augmentation program funding trajectories as inflection indicators for dual-use technology transfer velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated pre-market review reduces capital lock-up for motor restoration developers pursuing spinal cord injury indications. |
| Neuromorphic Edge Computing Integration | On-device spike sorting eliminates cloud latency for closed-loop stimulation matching biological reflex speeds. |
| Endovascular Delivery Platform Development | Stent-electrode approaches expand addressable markets to patients excluded from craniotomy surgical candidacy. |
| Subscription Neural Data Analytics Launch | Recurring software services supplement hardware sales with 40-60% gross margins and predictable revenue streams. |
| EU MDR Conformity Assessment Pathway | Algorithmic transparency protocols for closed-loop systems enable European market access despite extended review timelines. |
Methodological Framework
Independent corroboration across neurotechnology development executives, hospital purchasing committee members, biomedical engineering researchers, and GPO contracts managers underwrites the qualitative findings. Primary interviews with FDA regulatory affairs specialists and Swissmedic conformity assessment officers supplemented secondary validation through FDA 510(k) and breakthrough device designation filings, EU MDR technical documentation databases, and hospital procurement contract records. Bottom-up unit shipment estimates across invasive, non-invasive, and semi-invasive product categories triangulated against top-down healthcare expenditure allocation models.
Rate-of-change decomposition across the projection horizon segments volume and value outputs by product type, application, end user, and technology dimensions. CAGRs derive from surgical robotics adoption curves, neuromorphic chip cost reduction trajectories, and bundled payment model penetration in spinal cord injury rehabilitation. Industry-specific forecast inputs incorporate glial scarring functional lifespan limitations on invasive electrode longevity and DARPA cognitive augmentation program funding velocity.
Underlying measurement precision varies by segment; neuroprosthetics motor restoration applications carry tighter precision than emerging cognitive enhancement categories due to established reimbursement coding and procurement data availability. Forecasts reflect documented assumptions regarding FDA review timeline stability, platinum-iridium supply chain continuity, and EU AI Act algorithmic transparency enforcement intensity. Material deviation in breakthrough device designation approval rates or endovascular delivery clinical outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Global Conversational Computing Platform Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market