
 AI in Medical Writing Market | 2026-2036
AI in Medical Writing Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Medical Writing Market Analytics
Pharmaceutical company demand for automated regulatory submission tools is hardening as trial complexity rises. IQVIA leverages its real-world data infrastructure to anchor medical writing automation across Phase II and III study reports. Certara specializes in model-informed drug development content, competing on regulatory science depth rather than template volume. Parexel International controls a global delivery network that extends AI-assisted writing services across multiple therapeutic areas.
AI in medical writing denotes the application of natural language processing and machine learning algorithms to generate, edit, and manage clinical and regulatory documents, typically operating with structured data inputs from electronic data capture systems and requiring validation against ICH E3 guidelines for clinical study reports. The technology serves primarily to compress document development timelines and reduce manual consistency errors in submissions to health authorities. Software solutions dominate current revenue as established vendors embed large language models into legacy document management platforms. Cloud-based applications represent the fastest-expanding deployment category as CROs seek elastic compute for multinational trial programs. Natural language processing underpins most functional differentiation, though data analysis platforms are capturing margin pools where real-world evidence integration commands premium pricing.
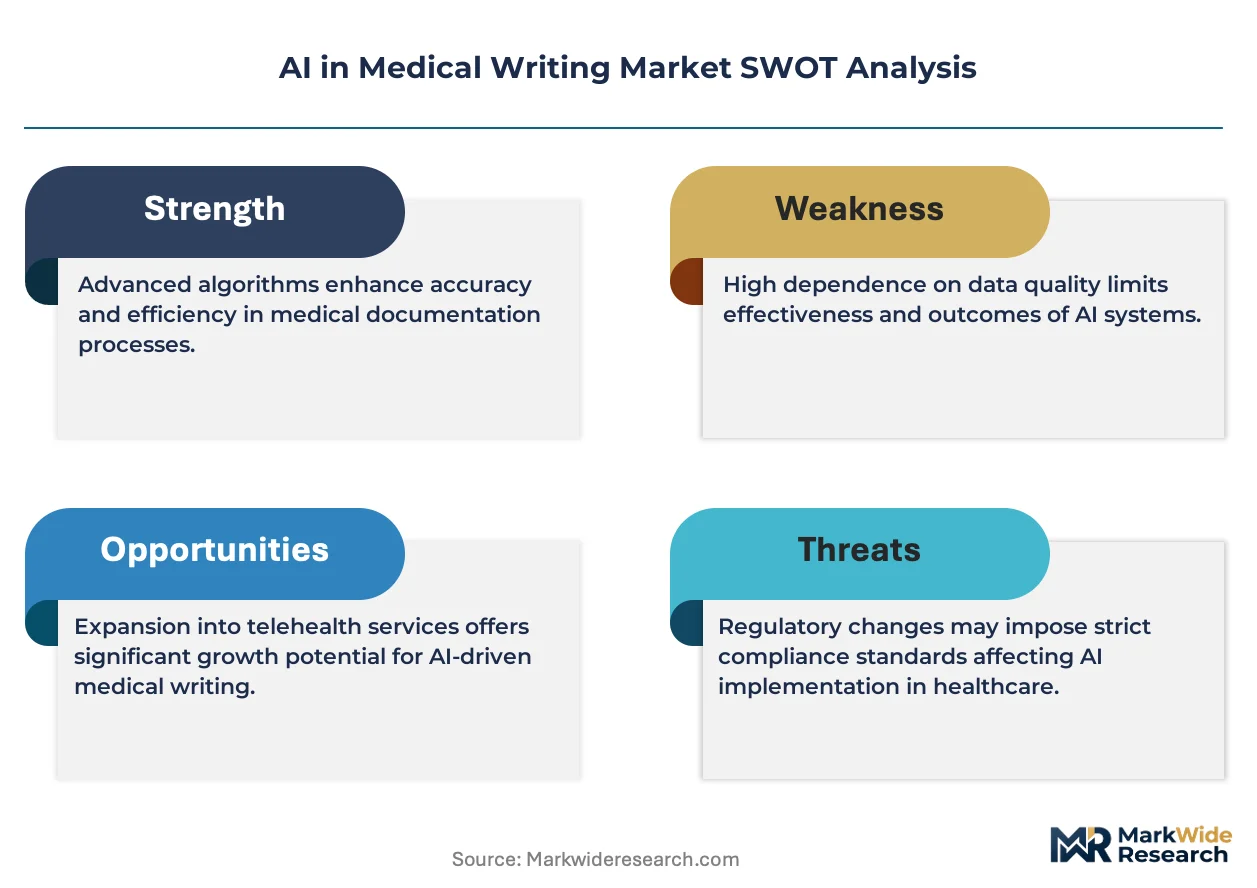
FDA maintains active guidance development for AI-generated content in regulatory submissions, while the EU AI Act imposes conformity assessment obligations on high-risk medical writing automation deployed within European markets. EMA's evolving framework for computerized systems in GxP environments shapes validation requirements that vendors must satisfy for market access. Health Canada and Japan's PMDA are issuing comparable signals, tightening the compliance perimeter for cross-border document automation. Stakeholders must monitor divergence between jurisdiction-specific evidentiary standards for AI-generated text and invest in modular validation architectures that adapt to shifting regulatory baselines without full platform redevelopment.
Market Dynamics
Large language model integration into legacy document management platforms is compressing clinical study report development timelines while FDA and EMA validation requirements harden around automated content generation systems.
Growth Catalysts
- EU AI Act conformity pathways:High-risk medical writing automation systems face mandatory conformity assessments, creating certified vendor differentiation that accelerates enterprise procurement cycles for validated platforms.
- Phase III trial complexity:Adaptive trial designs and decentralized clinical trials multiply document volumes, forcing pharmaceutical sponsors toward automated narrative generation to maintain submission timelines.
- Real-world evidence mandates:FDA's expanding requirements for integrated safety and effectiveness data in post-market submissions pull AI-assisted literature synthesis tools into standard workflows.
Market Restraints
- Validation infrastructure costs:ICH E3 guideline compliance for computerized systems requires extensive IQ/OQ/PQ documentation, elevating total cost of ownership beyond mid-tier CRO budgets.
- Cloud concentration risk:Elastic compute dependencies on hyperscale providers create single-point vulnerabilities for multinational trial programs requiring guaranteed availability during regulatory deadlines.
- Human-in-the-loop requirements:FDA draft guidance on AI-enabled medical devices preserves manual review mandates, limiting full automation potential and sustaining labor cost structures.
Strategic Opportunities
- Japan PMDA harmonization gaps:Divergent computerized systems validation expectations between Japan and ICH regions create demand for modular platforms that adapt to jurisdiction-specific evidentiary standards without redevelopment.
- Cell and gene therapy documentation:Complex manufacturing narrative requirements for ATMP submissions outpace template-based approaches, opening premium positioning for model-informed content generation.
- Health Canada alignment:Accelerated regulatory convergence with FDA AI guidance creates near-term white space for vendors with existing US validation infrastructure to capture Canadian market share.
Industry Challenges
- Regulatory science talent scarcity:Cross-functional expertise spanning natural language processing, ICH guidelines, and quality assurance remains concentrated among senior professionals at established vendors.
- Legacy system integration friction:Electronic data capture and clinical trial management system APIs vary across sponsor environments, requiring costly custom connectors for each enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Medical Writing Market |
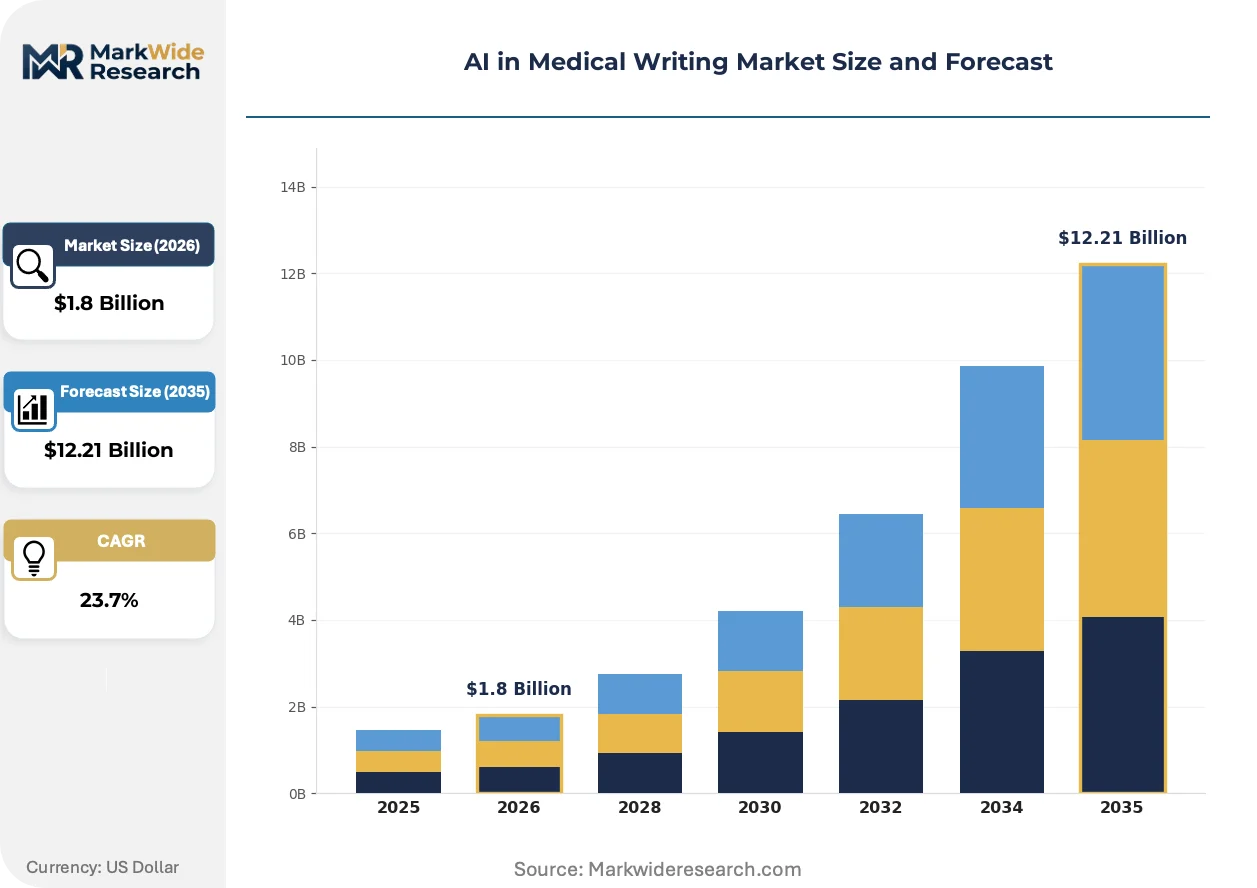
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud-Based Applications, Mobile Applications, Integration Tools End User: Pharmaceutical Companies, Medical Writers, Contract Research Organizations, Healthcare Providers Technology: Natural Language Processing, Machine Learning Algorithms, Content Creation Tools, Data Analysis Platforms Deployment Model: SaaS, On-Premises, Hybrid Solutions, Others |
| Companies Covered | Parexel International, Certara, IQVIA, ICON plc, Syneos Health, Trilogy Writing & Consulting GmbH, Freyr, Cactus Communications, GENINVO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Medical Writing Market Evolving Landscape
Foundation model architectures are displacing rules-based natural language generation in regulatory document workflows, while jurisdictional validation requirements fragment around AI-specific conformity frameworks.
Retrieval-augmented generation is integrating structured electronic data capture outputs with unstructured literature corpora to produce draft clinical study report sections. Mid-size pharmaceutical sponsors are piloting these systems for non-critical narratives before expanding to efficacy and safety summaries. This convergence is integrating real-world evidence streams directly into regulatory submission drafts, collapsing the traditional sequential gap between data lock and document completion.
FDA's evolving guidance on predetermined change control plans for AI-enabled devices is forcing vendors to architect modular validation frameworks. Sponsors must demonstrate ongoing performance monitoring rather than point-in-time qualification. Contract research organizations with US-centric trial portfolios are restructuring quality systems to accommodate continuous learning model updates without triggering full revalidation cycles.
Subscription-based access to AI writing modules is displacing perpetual license models among emerging biotech sponsors. These buyers prioritize operational flexibility over capital expenditure, particularly for single-asset companies with uncertain funding horizons. The shift concentrates in Boston and San Francisco corridor startups where venture-backed financing patterns favor opex-heavy technology procurement over long-term infrastructure commitments.
AI in Medical Writing Market Segmentation
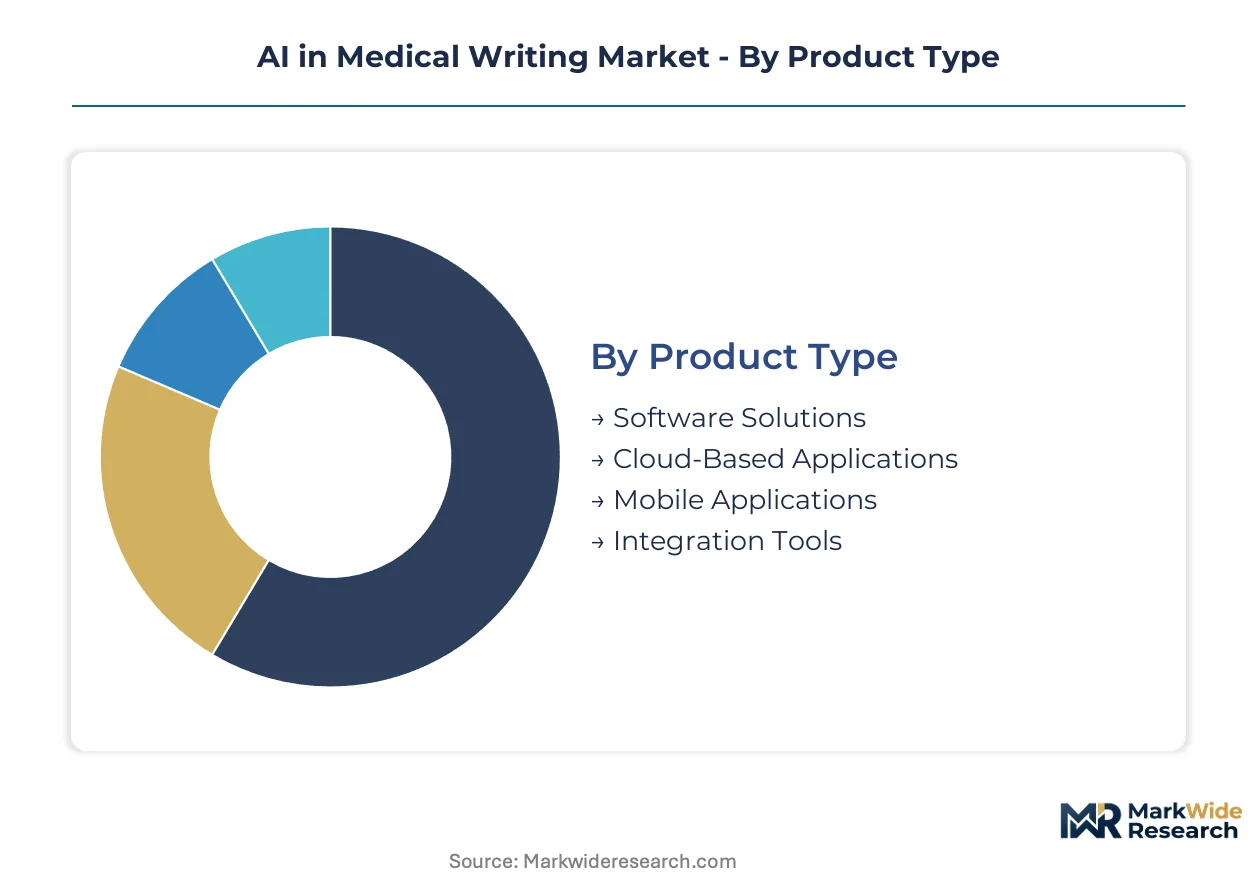
AI in medical writing segments by product architecture, user sophistication, underlying technology, and infrastructure deployment. Each dimension shapes validation requirements, procurement patterns, and margin structures differently across pharmaceutical sponsors and service providers.
Product Type:
Cost tier separates enterprise buyers from emerging biotech sponsors, with validation depth and integration scope as the primary differentiators.
- Software Solutions:Legacy document management platforms embed large language models for structured narrative generation, requiring IQ/OQ/PQ validation against ICH E3 guidelines. Pharmaceutical sponsors in the United States, particularly Massachusetts-based biotechs, prioritize these for Phase III submission timelines where regulatory scrutiny is highest.
- Cloud-Based Applications:Elastic compute architectures support multinational trial programs with variable document volumes, attracting CROs managing decentralized clinical trials. FDA draft guidance on predetermined change control plans creates procurement urgency for sponsors seeking modular validation frameworks that accommodate continuous model updates.
- Mobile Applications:Lightweight review interfaces enable field-based medical writers to annotate draft narratives during site visits. These serve supplementary roles rather than primary generation workflows.
- Integration Tools:API connectors bridge electronic data capture outputs with document management systems, reducing manual data transfer errors.
Volume sits with Software Solutions; growth tilts toward Cloud-Based Applications.
End User:
Application intensity varies by organizational scale, with trial portfolio breadth determining automation depth and regulatory risk tolerance.
- Pharmaceutical Companies:Internal medical writing departments deploy AI for clinical study reports, investigator brochures, and integrated summaries, with validation documentation maintained for FDA inspections. Large sponsors in California's Bay Area corridor invest most heavily, driven by cell and gene therapy pipelines requiring complex manufacturing narratives.
- Medical Writers:Individual practitioners leverage AI for first-draft generation and consistency checking, particularly for non-critical narratives before senior review. Freelance adoption concentrates where sponsor outsourcing budgets tighten.
- Contract Research Organizations:Global delivery networks standardize AI-assisted writing across multiple therapeutic areas, with quality systems restructured for continuous learning model updates.
- Healthcare Providers:Academic medical centers pilot AI for case report generation and publication drafting, though regulatory submission volumes remain limited.
Revenue concentrates with Pharmaceutical Companies; expansion accelerates fastest among Contract Research Organizations.
Technology:
Margin capture follows functional differentiation, with real-world evidence integration commanding premium positioning over template-based approaches.
- Natural Language Processing:Foundation model architectures displace rules-based generation for regulatory document workflows, with retrieval-augmented generation combining structured EDC outputs and unstructured literature corpora. This underpins most current functional differentiation in the market.
- Machine Learning Algorithms:Adaptive systems learn from reviewer feedback to improve draft quality over time, though FDA human-in-the-loop requirements limit full automation potential.
- Content Creation Tools:Template libraries with variable insertion fields serve mid-tier sponsors with standardized trial designs.
- Data Analysis Platforms:Real-world evidence integration and safety signal detection capabilities support post-market submission requirements, capturing margin pools where evidence synthesis complexity is highest.
Adoption depth is greatest for Natural Language Processing; premium pricing accrues to Data Analysis Platforms.
Deployment Model:
Maturity stage separates validated enterprise installations from experimental pilots, with compliance documentation requirements as the dividing line.
- SaaS:Subscription-based access displaces perpetual licenses among Boston and San Francisco corridor startups, with operational flexibility prioritized over capital expenditure for single-asset companies.
- On-Premises:Air-gapped installations satisfy data residency requirements for EU AI Act high-risk system deployments, with conformity assessment documentation maintained for EMA inspections.
- Hybrid Solutions:Sensitive data processing occurs on-premises while model training leverages cloud compute, addressing sponsor concerns about intellectual property exposure.
- Others:Managed service arrangements where vendors assume validation responsibility for sponsor-specific quality systems.
Installed base favors On-Premises; subscription momentum builds fastest in SaaS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States, while regulatory validation demand distributes across Western Europe and East Asia. Consumption patterns track pharmaceutical R&D investment clusters rather than manufacturing geography.
United States
FDA draft guidance on predetermined change control plans drives procurement urgency among Boston and San Francisco corridor biotechs. Sponsors restructure quality systems for continuous learning model updates without triggering full revalidation cycles. Massachusetts-based Phase III sponsors invest most heavily in validated platforms.
Germany
EMA's computerized systems validation framework shapes vendor market access requirements for GxP environments. EU AI Act conformity assessment obligations create certified vendor differentiation that accelerates enterprise procurement. Heidelberg and Munich pharmaceutical clusters standardize AI-assisted writing across multiple therapeutic areas.
United Kingdom
MHRA alignment with FDA AI guidance creates near-term white space for vendors with existing US validation infrastructure. London-based CROs pilot retrieval-augmented generation systems for non-critical narratives before expanding to efficacy summaries. The Cambridge life sciences cluster drives demand for cell and gene therapy documentation tools.
Japan
PMDA divergent computerized systems validation expectations create demand for modular platforms adapting to jurisdiction-specific standards. Tokyo sponsors face complex manufacturing narrative requirements for ATMP submissions. Osaka pharmaceutical companies seek elastic compute architectures for multinational trial programs.
Switzerland
Swissmedic tightening compliance perimeter for cross-border document automation elevates total cost of ownership for mid-tier sponsors. Basel-based global pharma headquarters drive premium positioning for real-world evidence integration capabilities. Geneva CROs extend AI-assisted writing services across decentralized clinical trial networks.
AI in Medical Writing Market Competitive Landscape
Top-tier vendors anchor enterprise validation depth, while mid-tier specialists compete on therapeutic niche coverage. The vendor base stratifies across three layers: global CROs with integrated quality systems, pure-play software vendors with modular architectures, and boutique consultancies with regulatory science specialization. Dominant competitive moves include M&A to capture validation infrastructure and strategic partnerships to bridge electronic data capture API gaps.
Among contract research organizations with global delivery networks, Parexel International, IQVIA, and ICON plc exemplify the scale-driven archetype. These entities represent positions where real-world data infrastructure anchors medical writing automation across Phase II and III study reports. Certara occupies a specialist position in model-informed drug development content, competing on regulatory science depth rather than template volume. Trilogy Writing & Consulting GmbH sits within the European boutique tier, reflecting geography-specific conformity assessment capabilities.
| Leading Market Players |
|---|
| Parexel International |
| Certara |
| IQVIA |
| ICON plc |
| Syneos Health |
| Trilogy Writing & Consulting GmbH |
| Freyr |
| Cactus Communications |
| GENINVO |
| Others |
Value Network & Pricing Analysis
Cloud compute pricing indices from hyperscale providers cascade through AI medical writing supply chains, compressing SaaS subscription tiers while elevating validation documentation costs for on-premises deployments. Pharmaceutical sponsors absorb these trade-offs differently across Boston corridor biotechs and Basel-based global headquarters.
Pricing Analysis
Margin tightening in mid-tier CRO segments reflects elastic compute dependency on AWS and Azure infrastructure. Three-tier pricing structure across enterprise-validated, modular-cloud, and entry-level SaaS levels separates FDA-inspection-ready platforms from pilot-stage tools. Cost-down pressure on perpetual licenses accelerates because emerging biotech sponsors prioritize operational flexibility over capital expenditure. Single-asset companies in San Francisco demonstrate highest price sensitivity; Phase III sponsors in Massachusetts show lowest sensitivity due to regulatory deadline risk.
Supply Chain Analysis
Natural language processing talent scarcity in the United States, Germany, and Switzerland constrains vendor scaling velocity. Foundation model development draws from proprietary clinical trial databases, open-source biomedical corpora, and regulatory submission archives. Single-source vulnerability concentrates around GPT-class API dependencies for retrieval-augmented generation workflows. Distribution runs through direct enterprise sales for validated platforms and self-serve portals for emerging sponsor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model architectures are displacing rules-based natural language generation, compressing legacy vendor margins while opening white space for retrieval-augmented generation specialists. This technology-transition phase rewards modular validation frameworks over monolithic platforms.
For Market Incumbents: Hedge against open-source model commoditization by deepening regulatory science talent pools in ICH guideline interpretation. Acquire boutique consultancies with EMA conformity assessment expertise to defend certification moats. Vertical integration into electronic data capture APIs reduces custom connector costs per enterprise deployment. For New Entrants and Emerging Players: API-first distribution routes penetrate mid-size pharmaceutical sponsors faster than direct sales cycles. Target Health Canada alignment gaps where FDA-validated platforms face lighter adaptation requirements. Pilot retrieval-augmented generation for non-critical narratives before expanding to efficacy summaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular-platform specialists with existing IQ/OQ/PQ documentation libraries in the United States. Long-term viability hinges on continuous learning model update architectures that avoid full revalidation cycles. Watch FDA predetermined change control plan finalization as inflection indicator for procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Science Talent Acquisition | ICH E3 guideline expertise anchors vendor differentiation against template-based competitors. |
| Modular Validation Framework Development | FDA predetermined change control plans require continuous learning architectures without full revalidation. |
| API Integration Partnership | Electronic data capture connectors reduce deployment friction across sponsor-specific clinical trial management systems. |
| EU AI Act Conformity Certification | High-risk system assessments create procurement urgency for validated platforms in Heidelberg and Munich clusters. |
| Real-World Evidence Platform Expansion | Safety signal detection capabilities capture premium pricing in post-market submission workflows. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with medical writing directors, regulatory affairs leads, quality assurance officers, and CRO procurement managers. FDA 483 inspection observations, EMA qualification reports, and ClinicalTrials.gov protocol registries provided validation requirement benchmarks. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure patterns.
Data-stream reconciliation across deployment model adoption curves, end-user procurement cycles, and technology capability maturity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, user sophistication tier, underlying technology type, infrastructure deployment pattern, and regional regulatory cluster. CAGRs derived from elasticity-adjusted penetration curves and sponsor budget allocation surveys. Phase III trial complexity indices and real-world evidence mandate expansion served as industry-specific forecast inputs.
The model holds under stable FDA and EMA guidance interpretation; deviation in EU AI Act enforcement stringency or PMDA harmonization timelines would shift vendor market access costs. Forecasts reflect these assumptions without claiming predictive certainty. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Voice User Interface Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
AI in Retail Market