
 Voice Recognition Market | 2026-2036
Voice Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Recognition Market Analysis
Cloud-based API leasing and pay-per-query consumption models is reconfiguring competitive entry barriers for voice recognition vendors. Amazon.com Inc. leverages its Alexa developer ecosystem to sustain hardware-software bundling across smart home and automotive channels. Microsoft Corporation anchors enterprise demand through Azure Speech Services integration with productivity suites and call center platforms. Alphabet Inc. competes via Google Cloud Speech-to-Text APIs that extend its search infrastructure into vertical transcription workflows.
Voice recognition encompasses acoustic signal processing, natural language understanding, and speech synthesis systems that convert spoken utterances into machine-actionable commands or text output with specified word-error-rate thresholds below five percent in controlled environments. The technology serves industrial and commercial purposes spanning hands-free device control, automated customer service routing, and clinical documentation capture. NLP and acoustic model deployments dominate enterprise budgets as organizations prioritize multilingual intent parsing and noise-robust transcription for call center automation and virtual assistant rollouts. Edge computing architectures represent the fastest-growing deployment category as manufacturers localize inference to reduce latency and satisfy data residency constraints in security systems and automotive cabins.
The FDA regulates voice-enabled clinical decision support software as medical devices under its digital health framework, while the EU AI Act imposes conformity assessments on biometric identification systems including speaker verification. The FCC governs telecommunications accessibility standards that mandate voice interface compatibility for consumer electronics and emergency services. Stakeholders must monitor evolving algorithmic accountability requirements across jurisdictions to determine compliance investment sequencing and market access prioritization.
Market Dynamics
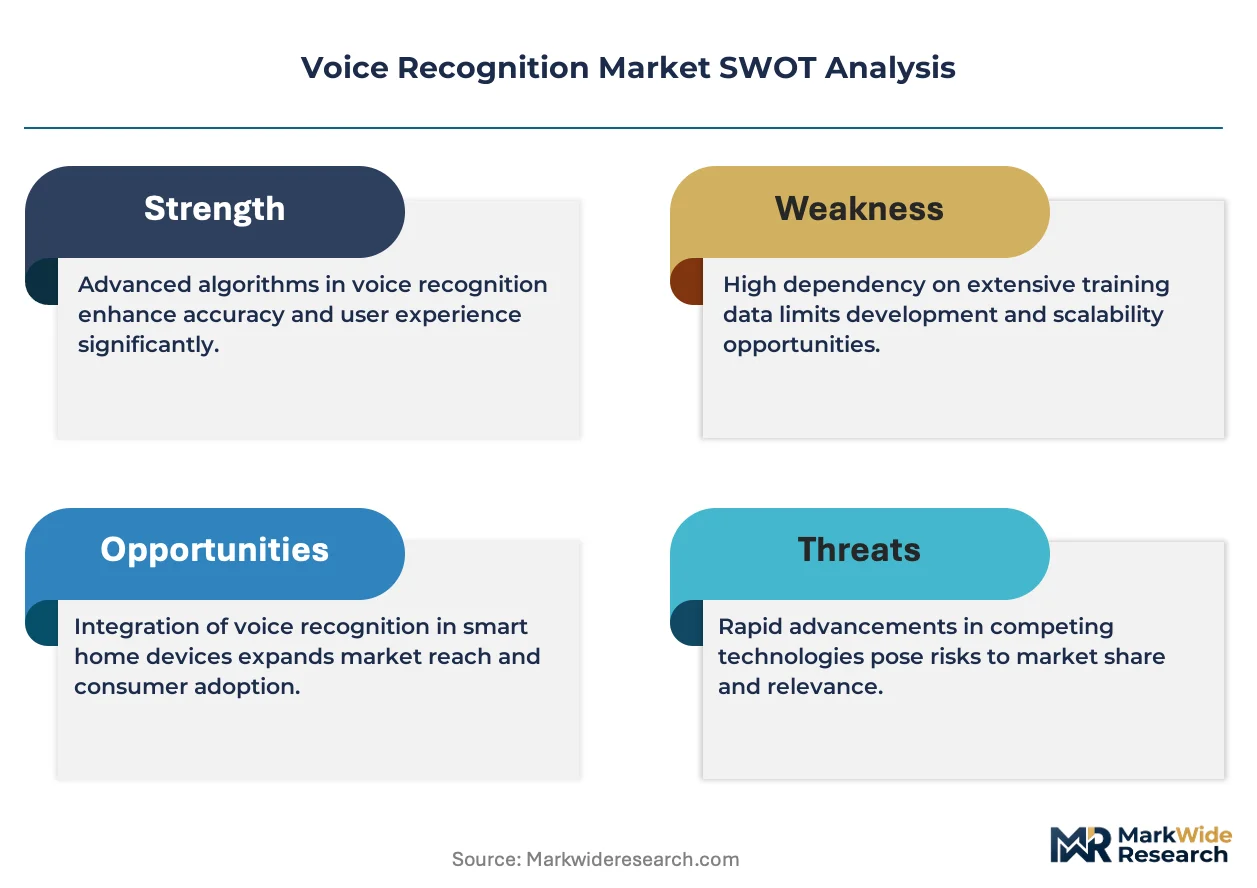
Edge inference architectures are compressing latency requirements below 200 milliseconds for automotive cabin systems and medical dictation workflows, forcing vendors to reconfigure hardware-software stacks around localized acoustic processing rather than cloud dependency.
Growth Catalysts
- EU AI Act conformity pathways:Biometric identification systems face mandatory third-party assessment, creating certified vendor pools that reduce procurement friction for healthcare and financial services buyers seeking compliant speech verification.
- Automotive cabin integration:Hands-free control mandates from NHTSA and equivalent regulators in Germany and Japan are embedding wake-word detection and natural language command parsing into production vehicle lines as standard equipment.
- Transformer-based acoustic modeling:Self-supervised pretraining on multilingual audio corpora is collapsing word-error-rate thresholds for low-resource languages, opening public sector and emerging market procurement previously blocked by accuracy requirements.
Market Restraints
- GPU and NPU silicon concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced node fabrication for inference-optimized chips, exposing voice recognition hardware vendors to single-source geopolitical and capacity risk.
- FDA 510(k) clearance timelines:Clinical decision support software incorporating voice interfaces faces median review periods exceeding 180 days, compressing revenue recognition for healthcare-focused developers.
- Cloud API pricing volatility:Pay-per-query models from hyperscale providers subject enterprise buyers to unpredictable transcription costs at volume, driving internal TCO analyses toward capital-intensive edge deployment.
Strategic Opportunities
- India's BIS certification pipeline:Mandatory safety testing for imported electronics creates first-mover advantage for vendors establishing local acoustic tuning labs and Hindi-English code-switching models ahead of enforcement deadlines.
- Convergence with computer vision:Multimodal systems fusing lip-reading video streams with audio signals are penetrating high-noise industrial environments where pure acoustic methods fail, opening manufacturing and logistics verticals.
- Contact center channel restructuring:Direct enterprise licensing bypassing traditional systems integrators is capturing margin previously allocated to intermediary configuration services, particularly in United States and United Kingdom mid-market accounts.
Industry Challenges
- Phonetic lexicon engineering scarcity:Computational linguists capable of building noise-robust pronunciation dictionaries for domain-specific vocabularies command compensation premiums exceeding 40% above standard machine learning engineering roles.
- EHR integration complexity:Legacy healthcare record systems from Cerner and Epic require custom HL7 FHIR middleware development for voice-generated clinical notes, extending implementation timelines and eroding project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Recognition Market |
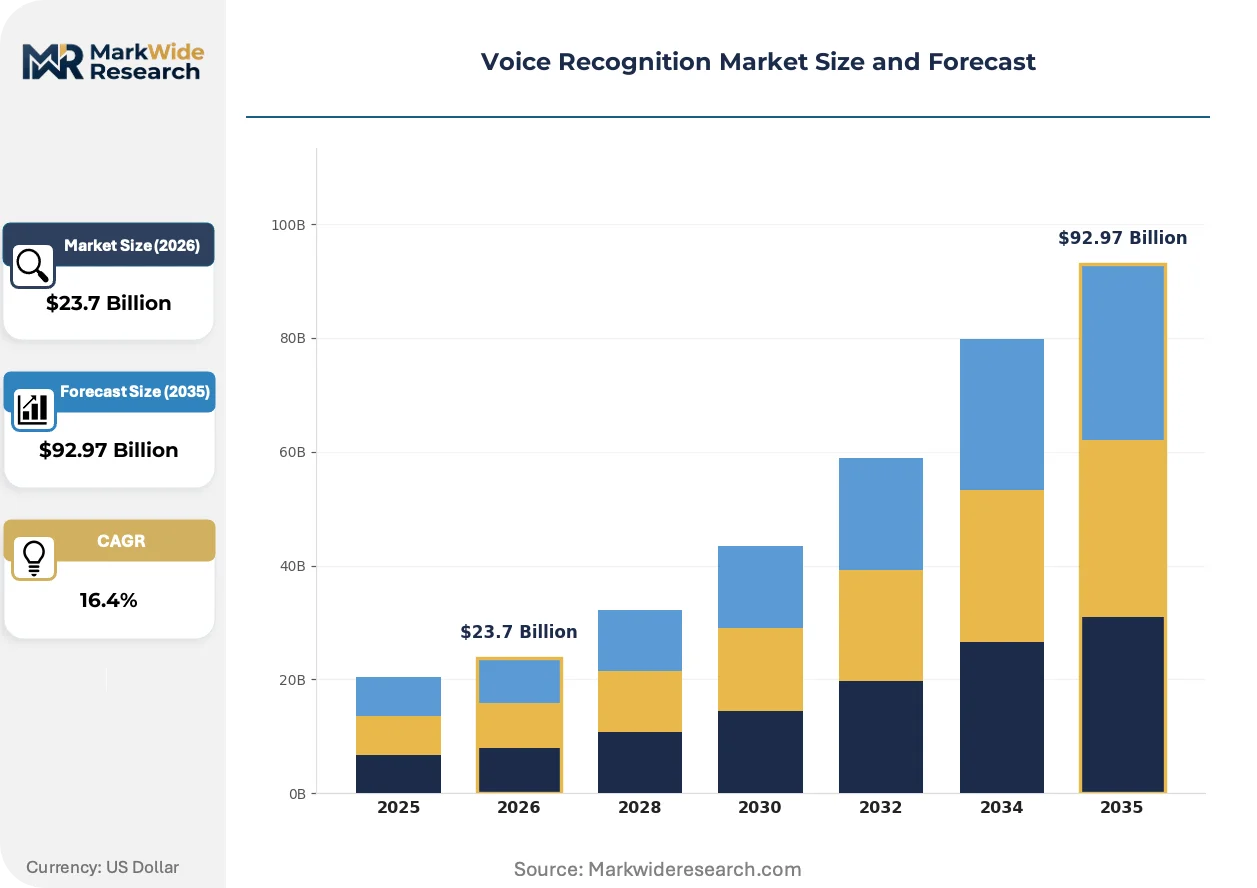
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $92.97 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: NLP, Acoustic Model, Language Model, Speech Synthesis Application: Virtual Assistants, Dictation Software, Voice Command Systems, Call Center Automation End User: Healthcare, Automotive, Consumer Electronics, Security Systems Deployment: Cloud-Based, On-Premises, Edge Computing, Hybrid Solutions |
| Companies Covered | Alphabet Inc., Amazon.com Inc., Microsoft Corporation, Apple Inc., IBM Corporation, Baidu Inc., iFLYTEK Co. Ltd., Nuance Communications Inc., Sensory Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Recognition Market Emerging Trajectories
Neural audio codecs and on-device learning loops are collapsing the boundary between cloud training and edge personalization, enabling acoustic models that adapt to individual speakers without transmitting biometric data off-premises.
Self-supervised wav2vec architectures trained on unlabeled multilingual speech are rendering obsolete supervised pipelines dependent on expensive phonetically transcribed corpora. Automotive OEMs in Germany and Japan are deploying these models for in-cabin assistants that learn driver accent patterns during initial ownership periods. The shift is compressing vendor R&D budgets previously allocated to manual annotation while raising performance floors for second-tier speech recognition providers.
REACH restrictions on persistent organic pollutants are forcing microphone MEMS suppliers to reformulate encapsulant chemistries and acoustic mesh coatings. The EU AI Act's biometric system registration requirements are layering documentation obligations onto hardware component sourcing. Medical device manufacturers seeking CE marking for voice-enabled diagnostic tools face stacked compliance timelines from both chemical safety and algorithmic accountability frameworks.
Enterprise procurement teams are unbundling transcription accuracy guarantees from platform subscription fees, negotiating separate service-level agreements for specific acoustic environments. United States healthcare systems now demand contractual penalties for word-error-rate exceedances in emergency department dictation workflows. The pattern is shifting vendor revenue recognition toward performance-contingent structures and away from flat per-seat licensing that dominated pre-2023 contract templates.
Voice Recognition Market Segmentation
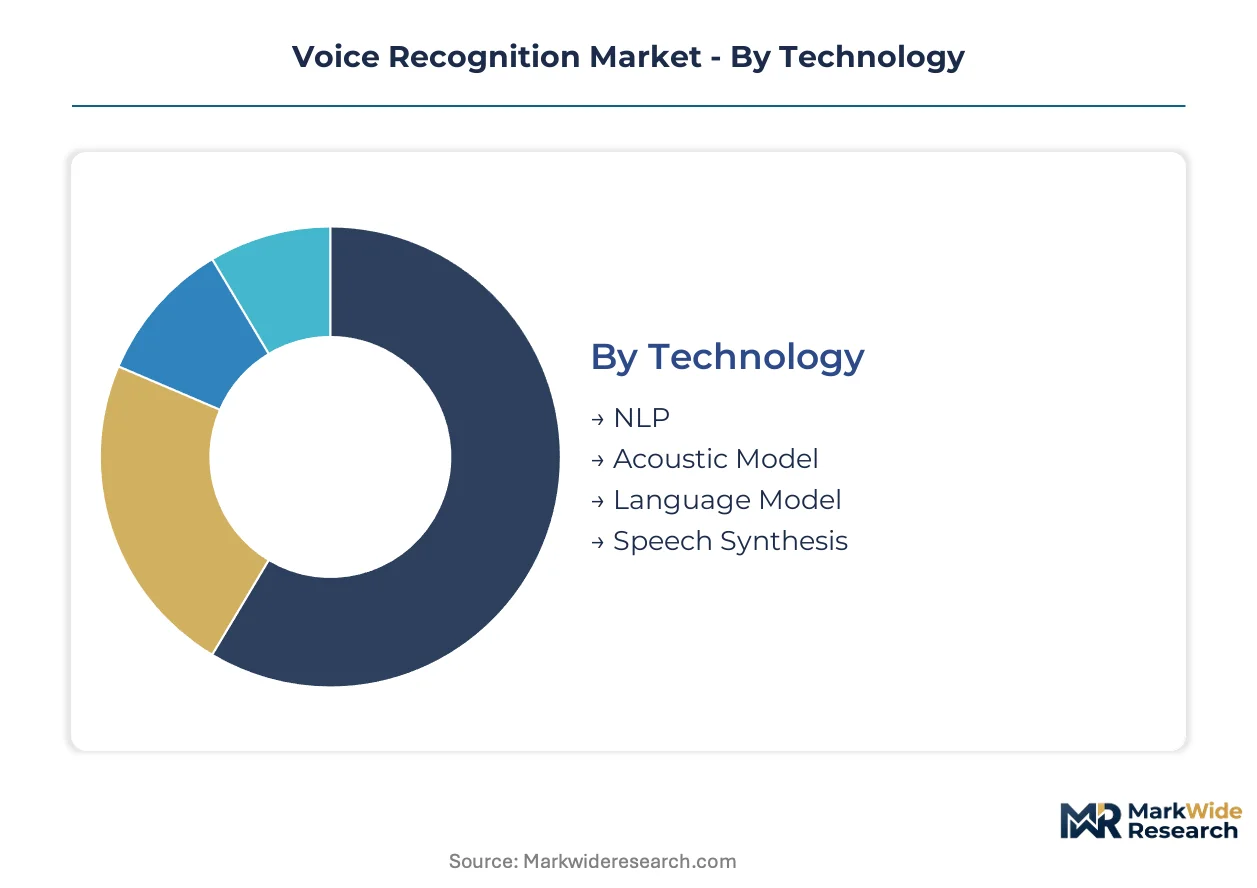
Voice recognition vendors configure product roadmaps around four intersecting dimensions that determine pricing power and implementation complexity. Technology choices dictate R&D burn rates, while deployment architectures shape customer acquisition costs and data governance obligations across regulated industries.
Technology:
NLP and acoustic model refresh cycles run 6-12 months for cloud-hosted systems, whereas language model iterations stretch 18-24 months due to corpus curation demands. Speech synthesis pipelines turn slowest, often locked for 3-5 years in embedded automotive contracts.
- NLP:Intent parsing engines extract semantic meaning from transcribed utterances using transformer architectures trained on multilingual conversational datasets. Healthcare systems in the United States deploy these modules for clinical documentation workflows where FDA software guidance mandates validation protocols. Procurement concentrates among hospital networks seeking HL7 FHIR integration for EHR connectivity.
- Acoustic Model:Deep neural networks map audio spectrograms to phonetic representations, with self-supervised wav2vec pretraining now displacing supervised pipelines. Automotive OEMs in Germany and Japan prioritize noise-robust variants for cabin environments where engine and road interference degrades recognition accuracy. These models require continuous retraining on fleet-collected audio samples.
- Language Model:Statistical and neural architectures predict word sequences to resolve acoustic ambiguities, operating as the final decoding layer in production pipelines. Contact center platforms leverage domain-specific variants fine-tuned on industry vocabularies.
- Speech Synthesis:Text-to-speech systems generate naturalistic voice output for conversational agents and accessibility tools. Smart home device manufacturers specify low-latency neural vocoders that run on constrained embedded silicon.
NLP dominates installed base. Acoustic model innovation is where expansion concentrates.
Application:
Virtual assistants and call center automation command premium pricing due to recurring API consumption, while dictation software licenses trade at lower margins with higher customer lifetime value in professional segments.
- Virtual Assistants:Conversational AI platforms combine wake-word detection, intent classification, and dialogue management for consumer and enterprise use cases. Amazon.com Inc. and Alphabet Inc. anchor consumer demand through smart speaker ecosystems, while Microsoft Corporation targets enterprise productivity integration. These systems monetize through hardware-software bundling and developer marketplace fees.
- Call Center Automation:Interactive voice response and agent-assist tools transcribe customer utterances in real time, routing inquiries and surfacing knowledge base articles. United States financial services and telecommunications buyers drive procurement, with EU AI Act conformity assessments becoming a gating factor for biometric verification features.
- Dictation Software:Speaker-dependent transcription tools capture professional documentation in legal, medical, and journalistic workflows. Dragon Medical and equivalent platforms maintain entrenched positions despite cloud-native challengers.
- Voice Command Systems:Hands-free control interfaces for industrial machinery, automotive infotainment, and smart home devices prioritize low-latency execution over conversational depth. NHTSA mandates are accelerating automotive adoption.
Call center automation captures the steepest expansion trajectory. Dictation software retains the most stable revenue base.
End User:
Healthcare and automotive verticals impose the longest sales cycles due to regulatory validation, while consumer electronics moves fastest with 9-12 month product development timelines.
- Healthcare:Clinical documentation and diagnostic support applications face FDA 510(k) clearance requirements for software-as-medical-device classifications. United States health systems invest in voice interfaces to reduce physician administrative burden, with Epic and Cerner EHR integration consuming substantial implementation resources. The EU AI Act adds layered conformity obligations for biometric identification deployments in European markets.
- Automotive:In-cabin assistants and hands-free control systems integrate with vehicle bus architectures for climate, navigation, and telephony functions. German and Japanese OEMs specify wake-word engines that learn driver accent patterns during initial ownership periods. NHTSA and KBA regulations mandate compatibility with emergency services protocols.
- Consumer Electronics:Smart speakers, wearables, and mobile devices embed voice interfaces as standard features. Price compression is severe, with differentiation shifting to privacy-preserving on-device processing.
- Security Systems:Speaker verification and voice biometrics control physical and logical access in banking and government facilities. Data residency requirements favor edge deployment architectures.
Healthcare dominates contract value. Automotive is climbing the fastest.
Deployment:
Cloud-based APIs deliver fastest time-to-value but expose buyers to pricing volatility, while edge computing requires capital-intensive hardware qualification that extends initial deployment by 6-9 months.
- Cloud-Based:Hyperscale speech APIs from Amazon Web Services, Microsoft Azure, and Google Cloud Platform offer pay-per-query consumption with automatic model updates. Enterprise buyers in the United States favor these for rapid prototyping and variable workloads, though transcription cost unpredictability at volume drives TCO analyses toward alternatives. FCC telecommunications accessibility standards govern compatibility requirements.
- Edge Computing:Localized inference on NPU-equipped silicon eliminates network latency and satisfies data residency constraints. Automotive cabin systems and security applications in Germany and Japan specify sub-200-millisecond response thresholds that mandate edge architectures. Taiwan Semiconductor Manufacturing and Samsung Foundry fabrication dependencies create supply risk.
- On-Premises:Dedicated hardware deployments in regulated data centers address financial services and government confidentiality requirements. Higher upfront capital expenditure is offset by predictable operational costs.
- Hybrid Solutions:Architectures partition workloads between cloud training and edge inference, enabling personalization without biometric data transmission. Medical device manufacturers pursuing CE marking favor these for EU AI Act compliance.
Cloud-based deployment holds the largest installed base. Edge computing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's biometric system conformity assessments are redirecting procurement budgets toward certified vendors in European healthcare and financial services. Cloud infrastructure concentration in the United States sustains hyperscale API rollouts across automotive and contact center verticals. India's BIS certification deadlines for imported electronics are accelerating local acoustic tuning investments ahead of enforcement.
United States
Enterprise IT spending and hyperscale cloud infrastructure sustain platform rollouts across automotive and healthcare verticals. FDA 510(k) clearance timelines for voice-enabled clinical decision support software extend median review periods beyond 180 days. Greater Boston and Silicon Valley clusters concentrate voice AI R&D operations for EHR integration and call center automation.
Germany
Automotive OEM procurement for in-cabin assistants drives wake-word detection and natural language command parsing demand. KBA regulations mandate hands-free control compatibility with emergency services protocols for production vehicle lines. Bavaria and Baden-Württemberg manufacturing corridors anchor acoustic model development for noise-robust cabin environments.
Japan
METI industrial policy supports edge computing localization for automotive and security system deployments. JIS standards govern interoperability requirements for voice interfaces in consumer electronics and industrial machinery. Kansai and Chubu industrial clusters concentrate NPU-equipped silicon integration for sub-200-millisecond response thresholds.
India
BIS mandatory safety testing for imported electronics creates first-mover incentives for Hindi-English code-switching model development. TRAI telecommunications frameworks shape accessibility standards for voice interface compatibility. Karnataka and Telangana technology corridors host acoustic tuning labs serving domestic smart speaker and automotive Tier-1 suppliers.
China
MIIT industrial guidance accelerates on-device learning architectures for privacy-preserving biometric processing. GB standards establish baseline requirements for voice recognition accuracy in consumer electronics and security applications. Yangtze River Delta manufacturing clusters integrate neural audio codecs into smart home and wearable device production lines.
Voice Recognition Market Vendor Landscape
Channel-controlling players compete with product-specialist players across cloud API, embedded silicon, and enterprise software vectors. Hyperscale cloud providers anchor the upper tier through pay-per-query consumption models and developer ecosystem lock-in. Mid-tier specialists concentrate on vertical-specific acoustic tuning for healthcare and automotive certifications. Competitive moves center on edge computing hardware qualification and direct enterprise licensing bypassing systems integrators.
Within the hyperscale cloud tier, Amazon.com Inc., Microsoft Corporation, and Alphabet Inc. occupy positions defined by infrastructure scale and productivity suite integration. Amazon.com Inc. leverages hardware-software bundling across smart home channels. Microsoft Corporation anchors enterprise demand through productivity platform integration. Alphabet Inc. extends search infrastructure into transcription workflows. These three exemplify the channel-control archetype that shapes pricing power and developer ecosystem capture across the market.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Amazon.com Inc. |
| Microsoft Corporation |
| Apple Inc. |
| IBM Corporation |
| Baidu Inc. |
| iFLYTEK Co. Ltd. |
| Nuance Communications Inc. |
| Sensory Inc. |
| Others |
Supply Flow & Price Mechanics
The Trans-Pacific freight corridor's rate volatility feeds directly into edge computing hardware landed costs, compressing margins for voice recognition vendors sourcing NPU-equipped silicon from Taiwan and South Korea while amplifying price spreads between FDA-certified clinical systems and uncertified consumer electronics.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared clinical documentation platforms commanding three-to-five-fold premiums over uncertified call center APIs. Subscription-based SaaS tiers dominate enterprise procurement, though pay-per-query consumption from hyperscale providers subjects high-volume buyers to unpredictable transcription costs. Pricing pressure stems from GPU and NPU silicon concentration at Taiwan Semiconductor Manufacturing and Samsung Foundry, where capacity constraints inflate component costs. Healthcare systems exhibit the lowest price sensitivity due to regulatory compliance requirements, while consumer electronics manufacturers face severe margin compression from smart speaker commoditization.
Supply Chain Analysis
Advanced node silicon feedstock draws from Taiwan, South Korea, and the United States, with Taiwan Semiconductor Manufacturing controlling the majority of inference-optimized NPU fabrication. MEMS microphone components hinge on specialized acoustic mesh coatings and encapsulant chemistries subject to REACH restrictions. Single-source vulnerability concentrates at the foundry level, where geopolitical disruption or capacity allocation shifts would cascade through automotive cabin system and medical device supply chains. Distribution runs through direct enterprise licensing channels that bypass traditional systems integrators, particularly in United States and United Kingdom mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational linguists capable of building noise-robust pronunciation dictionaries command compensation premiums exceeding 40% above standard machine learning engineering roles, constraining vendor R&D scaling and creating acquisition targets for firms with captive phonetic lexicon expertise.
For Market Incumbents: Entrench ecosystem lock-in through deeper Azure Speech Services and Alexa developer platform integration, while acquiring specialized acoustic tuning labs in India ahead of BIS certification enforcement. Cloud API pricing volatility from hyperscale competitors threatens margin stability in the call center automation segment. Certification investment in EU AI Act conformity pathways creates procurement preference with European healthcare and financial services buyers. For New Entrants and Emerging Players: Build out Hindi-English code-switching capabilities and local acoustic tuning infrastructure in Karnataka and Telangana to capture India's BIS-mandated import substitution window. The automotive cabin integration segment in Germany and Japan offers the most penetrable white space for specialized wake-word detection vendors. Go-to-market execution should target direct enterprise licensing to Tier-1 automotive suppliers rather than OEM relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from healthcare IT divisions seeking to monetize EHR-integrated voice documentation assets. Long-term viability rests on edge computing hardware qualification capabilities and regulatory certification velocity rather than pure algorithmic accuracy. Watch for FDA 510(k) clearance timeline compression as an inflection indicator for healthcare-focused developer revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Mandatory third-party assessment creates certified vendor pools that reduce procurement friction for European healthcare buyers. |
| Edge Computing Hardware Qualification | Sub-200-millisecond response thresholds in automotive cabin systems mandate localized NPU-equipped silicon deployment. |
| Multimodal System Development | Lip-reading video fusion with audio signals penetrates high-noise industrial environments where pure acoustic methods fail. |
| Direct Enterprise Licensing | Bypassing systems integrators captures margin previously allocated to intermediary configuration services in mid-market accounts. |
| Self-Supervised wav2vec Pretraining | Training on unlabeled multilingual audio collapses R&D budgets previously allocated to expensive phonetically transcribed corpora. |
Methodological Framework
A spread of perspectives from platform engineering directors, healthcare IT procurement officers, automotive Tier-1 supplier technical leads, and acoustic model researchers converged on the working assumptions. Primary interviews with these stakeholders were combined with secondary validation from SEC filings of hyperscale cloud providers, FDA 510(k) submission databases, EU AI Act conformity assessment registries, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down macroeconomic cross-checks were triangulated to establish consensus estimates.
Demand-supply balance across deployment architectures, end-user verticals, and regional regulatory clusters shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology type, application workflow, end-user industry, and deployment topology. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and forward-looking procurement pipeline visibility. Key inputs included automotive OEM production schedules for in-cabin assistant integration and healthcare system EHR modernization timelines.
Stress conditions across FDA review period extension, EU AI Act enforcement acceleration, and foundry capacity allocation shocks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline stability and silicon supply continuity. Cross-checking against hyperscale cloud provider revenue disclosures and automotive electronics bill-of-materials trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market