
 Europe Decision Intelligence Market | 2026-2036
Europe Decision Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Decision Intelligence Market Insights
Project finance for AI infrastructure and asset-light cloud leasing is narrowing the competitive field in European decision intelligence. Oracle Corporation leverages its established database installed base to anchor enterprise deployments across continental Europe. SAP SE sustains deep integration with ERP workflows, while Pyramid Analytics BV specializes in governed self-service analytics for mid-market manufacturers.
Decision intelligence encompasses platforms that synthesize machine learning, business rules engines, and contextual analytics to automate and augment complex organizational choices, typically processing structured and unstructured data streams with sub-second inference latency for operational decisions. The primary commercial purpose centers on reducing decision cycle times while embedding audit trails for regulatory accountability. Software solutions dominate current revenue as enterprises prioritize packaged platforms over custom builds, though cloud services represent the fastest-expanding deployment mode as German and French firms migrate from legacy on-premise architectures. Among end users, finance and healthcare absorb the majority of spending, with risk analysis and customer insights applications capturing disproportionate margin pools due to their compliance-critical nature.
The EU AI Act and GDPR jointly constrain how automated decision systems handle personal data and explain outputs to affected individuals, directly shaping product roadmaps and procurement criteria across the region. EMA guidelines for algorithmic transparency in pharmaceutical supply chains add sector-specific compliance layers that vendors must embed. France's CNIL and Germany's BfDI enforce divergent interpretations of automated decision rights, creating a fragmented compliance map. Stakeholders must monitor how upcoming harmonized standards under the AI Act's risk-based classification reshape competitive access across member states.
Market Dynamics
The EU AI Act's risk-based classification system is forcing European enterprises to re-architect automated decision systems before enforcement deadlines, compressing vendor sales cycles and privileging established compliance infrastructure over experimental deployments.
Growth Catalysts
- EU AI Act Conformity Requirements:Mandatory algorithmic impact assessments for high-risk applications are creating procurement urgency among banks and insurers seeking audit-ready platforms.
- Frankfurt Financial Cluster Concentration:Germany's banking hub generates concentrated demand for real-time credit risk modeling, pulling specialized vendors into continental headquarters.
- Explainable AI Techniques:SHAP and LIME integration into decision workflows satisfies GDPR Article 22 automated decision rights, opening procurement pathways previously blocked by legal review.
Market Restraints
- GDPR-EU AI Act Regulatory Friction:Overlapping transparency mandates create conflicting technical specifications, forcing dual compliance engineering that extends product development timelines.
- Cloud Infrastructure Concentration:Dependence on hyperscale providers for GPU compute concentrates supply risk, with Frankfurt and Dublin data center capacity constraints limiting deployment scale.
- Legacy ERP Integration Complexity:Technical debt in SAP-dominated manufacturing environments constrains decision intelligence layer deployment without costly middleware development.
Strategic Opportunities
- Polish Manufacturing Belt Expansion:Underpenetrated mid-market factories in Silesia and Łódź present whitespace for governed self-service analytics targeting Industry 4.0 retrofit programs.
- EMA Algorithmic Transparency Guidelines:Pharmaceutical supply chain mandates create sector-specific demand for decision audit trails in batch release and pharmacovigilance workflows.
- Graph Neural Network Convergence:Combining relationship-aware ML with business rules engines enables fraud detection applications previously requiring separate vendor stacks.
Industry Challenges
- MLOps Talent Scarcity:Shortage of engineers capable of deploying production-grade model monitoring in regulated environments extends implementation timelines and inflates service costs.
- CNIL-BfDI Interpretive Divergence:France's data protection authority and Germany's federal commissioner enforce incompatible automated decision rights standards, fragmenting product roadmaps.
- Legacy Mainframe Connectivity:Core banking systems in southern European institutions resist API-based data extraction, forcing expensive custom integration workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Decision Intelligence Market |
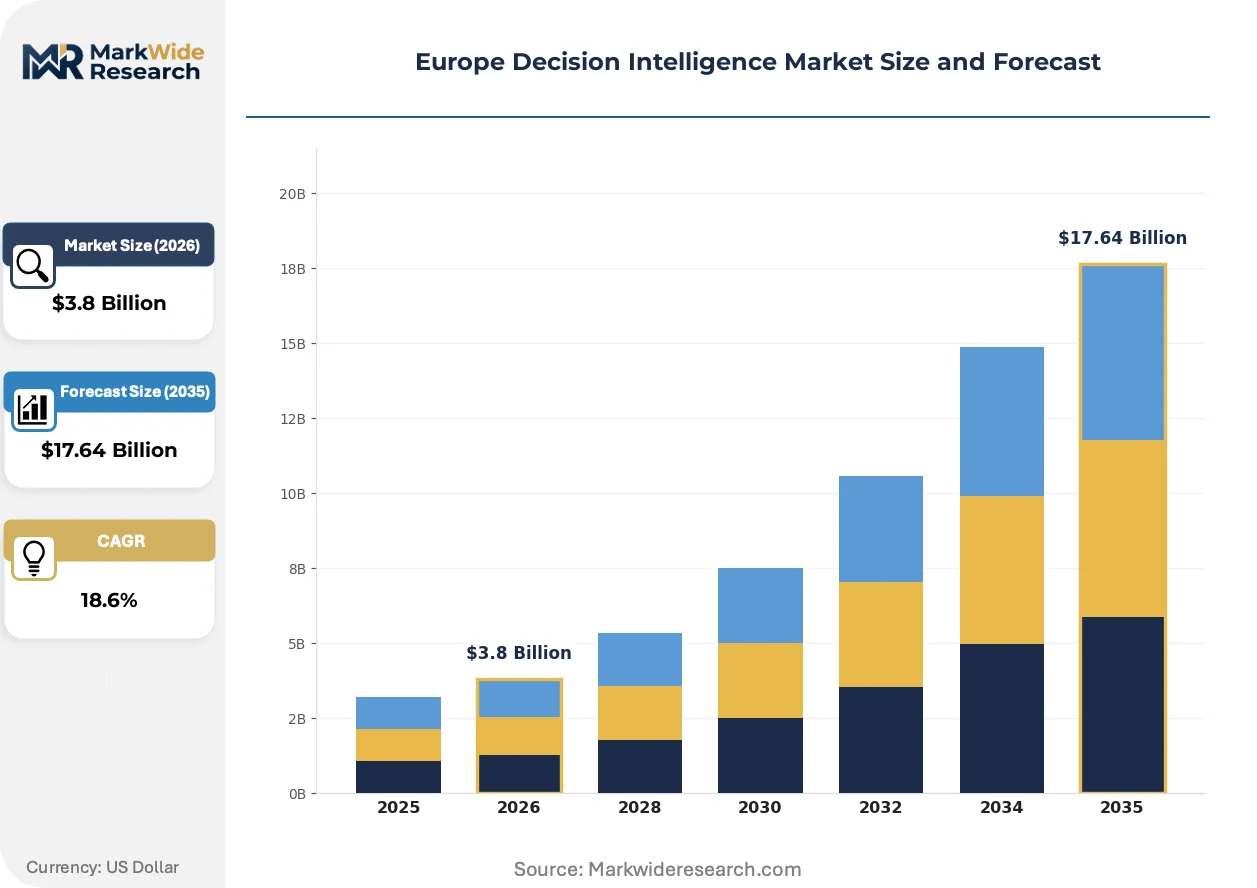
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Services, Analytics Tools, Consulting Services Deployment: On-Premise, Cloud-Based, Hybrid, Open Source End User: Finance, Healthcare, Retail, Manufacturing Application: Supply Chain Management, Risk Analysis, Customer Insights, Market Forecasting |
| Companies Covered | Oracle Corporation, IBM Corporation, Microsoft Corporation, Intel Corporation, Google LLC, Board International S.A., Domo, Inc., Pyramid Analytics BV, SAP SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Decision Intelligence Market Trends and Innovations
Decision intelligence architectures are converging around real-time inference pipelines that compress the gap between analytical insight and operational action, with regulatory pressure accelerating standardization of explainability interfaces.
Neuro-symbolic AI integration is collapsing the traditional separation between statistical pattern recognition and deterministic business rules. German automotive suppliers are deploying hybrid systems for supply chain disruption response, compressing decision latency from hours to seconds while maintaining auditable logic paths required by CSRD due diligence mandates.
The EU AI Act's harmonized standards development is reshaping vendor competitive positioning. ESO and CEN-CENELEC working groups are defining technical specifications for high-risk system conformity assessment, forcing product teams to embed logging and human oversight capabilities from initial design rather than retrofitting compliance.
Buyers in European banking are consolidating vendor relationships around platforms offering integrated model governance. Procurement committees now mandate single-pane observability across decision workflows, displacing point solutions that require separate risk management tooling. This concentration is most visible in Dutch and Nordic institutions where procurement centralization has advanced furthest.
Europe Decision Intelligence Market Segmentation
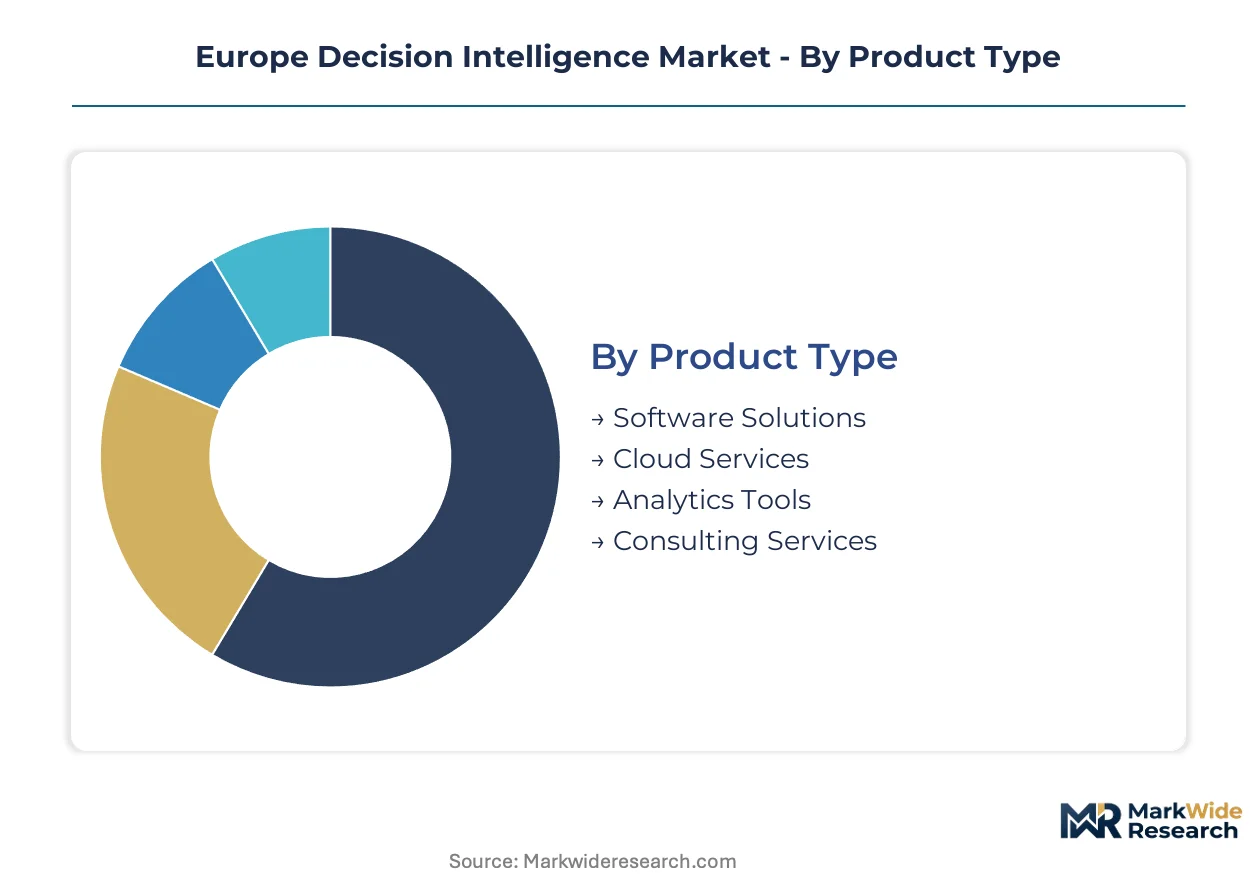
Segmentation reveals how EU AI Act compliance requirements and legacy infrastructure constraints fragment procurement patterns across European enterprises. Vendors must align product architectures with distinct deployment capabilities and sector-specific audit demands.
Product Type:
The use-case spectrum spans packaged platforms for rapid deployment through bespoke advisory engagements for complex regulatory remediation.
- Software Solutions:Packaged platforms integrating machine learning inference engines with deterministic business rules. German banking groups in Frankfurt deploy these for real-time credit scoring workflows that satisfy Bafin audit requirements.
- Cloud Services:GPU-accelerated inference pipelines delivered via Frankfurt and Dublin data center regions. French insurers leverage these for elastic scaling during quarterly solvency reporting cycles without capital-intensive infrastructure commits.
- Analytics Tools:Specialized visualization and model interpretability layers. Polish manufacturers adopt governed self-service variants for Industry 4.0 retrofit programs.
- Consulting Services:Advisory-led implementations addressing GDPR-EU AI Act dual compliance engineering.
The dominant share belongs to Software Solutions, while Cloud Services is closing the gap fastest.
Deployment:
Cost tier differentiation separates capital-intensive on-premise estates from operational-expense cloud models.
- On-Premise:Dedicated hardware installations in regulated data centers. Italian banks maintain these for core banking decision systems requiring air-gapped security postures.
- Cloud-Based:Fully managed SaaS architectures with shared tenancy. Nordic procurement centralization drives standardized cloud-first mandates across banking consortia.
- Hybrid:Split workloads with sensitive inference on-premise and training pipelines in cloud. German automotive suppliers deploy these for CSRD-compliant supply chain disruption response.
- Open Source:Community-supported frameworks requiring internal MLOps capability. Netherlands fintechs favor these for algorithmic transparency customization.
Cloud-Based deployments command the largest addressable base, though Hybrid architectures are expanding most quickly.
End User:
Application maturity varies sharply by sector regulatory exposure and legacy system entrenchment.
- Finance:Risk-weighted asset calculations and automated lending decisions. Frankfurt's banking cluster generates concentrated demand for sub-second inference with full audit trails.
- Healthcare:Clinical decision support and pharmaceutical supply chain optimization. EMA algorithmic transparency guidelines shape procurement specifications for batch release workflows.
- Retail:Dynamic pricing and demand forecasting across multi-channel operations. French retailers integrate CNIL-compliant customer insight platforms.
- Manufacturing:Predictive maintenance and quality control automation. Silesian and Łódź factories present whitespace for mid-market retrofit programs.
Finance retains the deepest penetration, while Manufacturing is gaining share fastest.
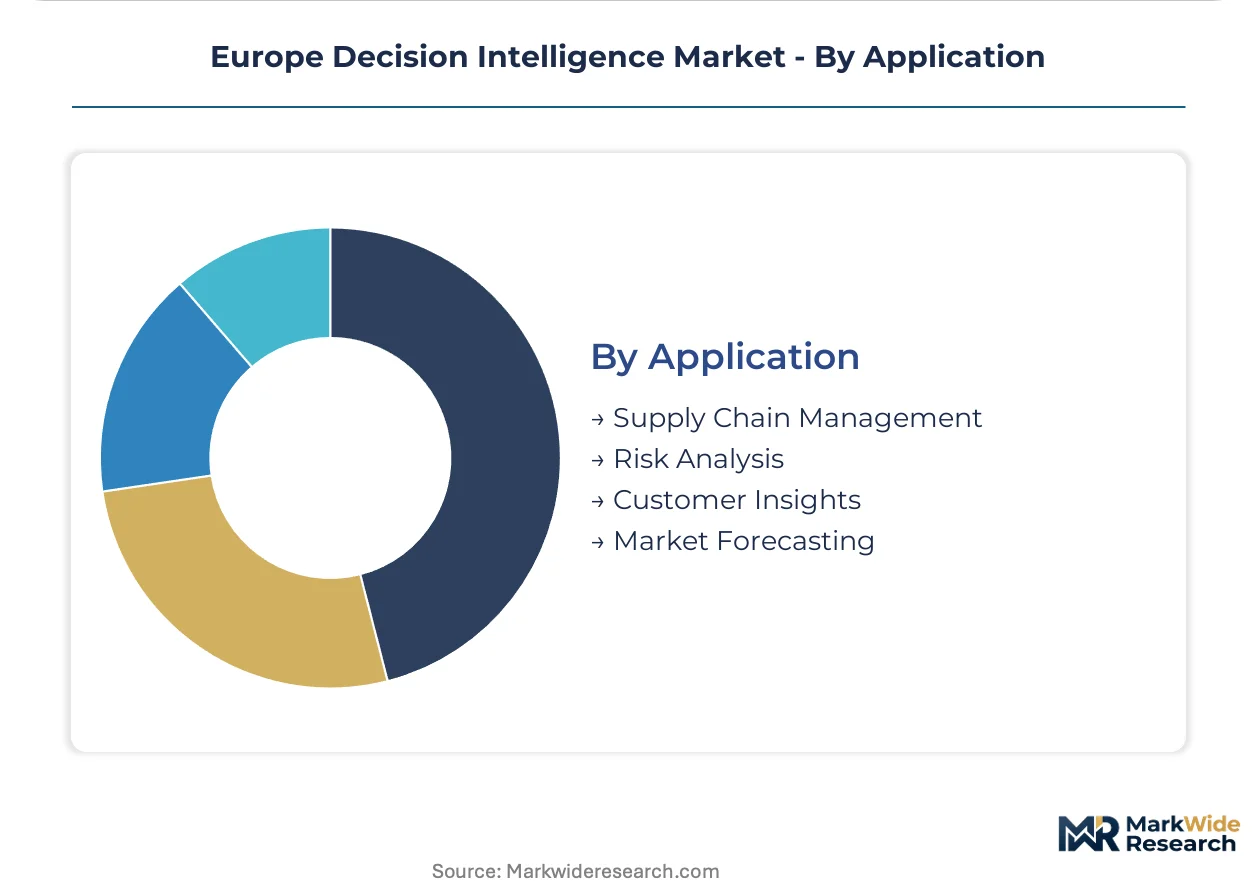
Application:
Margin concentration aligns with compliance-critical use cases requiring embedded governance.
- Supply Chain Management:Multi-tier disruption response and inventory optimization. German automotive suppliers deploy neuro-symbolic systems compressing decision latency to seconds.
- Risk Analysis:Credit scoring, insurance underwriting, and operational risk quantification. EU AI Act high-risk classification mandates algorithmic impact assessments.
- Customer Insights:Segmentation and churn prediction with GDPR Article 22 rights management. SHAP and LIME explainability integration opens procurement pathways.
- Market Forecasting:Demand planning and macroeconomic scenario modeling.
Risk Analysis captures the steepest margin pool, while Customer Insights is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's decision intelligence trade flows reflect a structural deficit in specialized GPU compute infrastructure, with continental enterprises importing cloud inference capacity while exporting governance frameworks and compliance tooling. The region's regulatory leadership on algorithmic accountability creates asymmetric exchange patterns in digital services trade.
Germany
Frankfurt's financial services cluster and Berlin's enterprise software ecosystem concentrate procurement demand for real-time credit risk modeling and ERP-integrated decision systems. Bafin supervisory requirements mandate auditable inference trails for automated lending decisions. The Rhine-Main metropolitan area anchors continental headquarters for vendors serving EU-wide banking compliance mandates.
France
Parisian banking groups and pharmaceutical multinationals drive demand for algorithmic transparency tooling under CNIL enforcement of GDPR Article 22 rights. The country's national data protection authority imposes stricter automated decision notification standards than peer regulators. Île-de-France hosts specialized consultancies addressing dual EU AI Act-GDPR compliance engineering for high-risk system deployments.
United Kingdom
London's fintech corridor and Edinburgh's insurance cluster sustain demand for explainable credit scoring and dynamic pricing platforms despite post-Brexit regulatory divergence. The Financial Conduct Authority's evolving guidance on AI in financial services shapes procurement specifications for model governance tooling. The Thames Valley corridor concentrates vendor development centers targeting Commonwealth market expansion.
Netherlands
Amsterdam's procurement centralization in banking consortia and Rotterdam's logistics hub generate concentrated demand for supply chain disruption response systems. Dutch institutional investors mandate single-pane observability across decision workflows, displacing fragmented point solutions. The Randstad metropolitan region serves as a testbed for EU AI Act conformity assessment pilot programs.
Poland
Silesian and Łódź manufacturing belts present whitespace for governed self-service analytics targeting Industry 4.0 retrofit programs with limited legacy ERP entrenchment. The country's national digital affairs ministry channels cohesion funds toward SME automation adoption. Kraków's enterprise service center cluster attracts vendor delivery operations for Central European market coverage.
Europe Decision Intelligence Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying inference engines and explainability modules. The vendor landscape stratifies between full-stack enterprise suites and modular analytics layers, with procurement centralization in Northern European banking driving consolidation around integrated governance capabilities. Three archetypes dominate: database-origin platforms leveraging installed base relationships, ERP-native suites embedding decision logic in operational workflows, and specialized analytics vendors targeting mid-market manufacturing gaps. Competitive positioning hinges on pre-certified compliance infrastructure and API depth for legacy system integration.
Within the database-platform tier, Oracle Corporation anchors enterprise deployments across continental Europe through its established relational installed base. SAP SE occupies the ERP-native position with deep workflow integration for German manufacturing and financial services environments. Pyramid Analytics BV exemplifies the specialized analytics archetype, targeting governed self-service deployments in underpenetrated industrial segments where compliance requirements outpace internal data science capabilities.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Intel Corporation |
| Google LLC |
| Board International S.A. |
| Domo, Inc. |
| Pyramid Analytics BV |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
EU AI Act compliance certification bottlenecks compress vendor margins while widening pricing spreads between audit-ready platforms and experimental deployments. Frankfurt data center capacity constraints tether GPU compute pricing to hyperscaler availability windows, forcing tiered service levels that reflect infrastructure scarcity rather than software differentiation.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing structures across the European decision intelligence landscape. Three-tier pricing structure across premium, standard, and economy levels separates Bafin-certified banking suites from mid-market manufacturing analytics and open-source frameworks requiring internal MLOps investment. Price differentiation rests on certification depth and legacy ERP integration complexity. Cost compression in the economy tier is intensifying because Polish manufacturing buyers prioritize rapid deployment over governance depth. Healthcare and pharmaceutical procurement committees exhibit lowest price sensitivity due to EMA algorithmic transparency mandates.
Supply Chain Analysis
TSMC and Samsung Foundry concentrate advanced GPU wafer supply for European cloud inference deployments. NVIDIA H100 and AMD MI300X accelerators draw from Taiwan and South Korea fabrication capacity, with assembly and testing distributed across Malaysia and Vietnam. Single-source vulnerability in CoWoS packaging capacity creates supply chain risk for real-time inference hardware. Distribution runs through Frankfurt and Dublin hyperscale regions, with German automotive suppliers and French insurers constituting the dominant downstream buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's decision intelligence market sits in early-cycle expansion, with EU AI Act enforcement deadlines compressing procurement timelines for high-risk system deployments.
For Market Incumbents: Build compliance infrastructure moats through pre-certified algorithmic impact assessment tooling. Oracle and SAP should deepen API penetration into legacy mainframe environments at Italian and Spanish banking groups. Emerging cloud-native entrants threaten ERP-anchored incumbents through faster deployment cycles. Certification investment in ESO and CEN-CENELEC harmonized standards creates switching costs that protect installed base relationships. For New Entrants and Emerging Players: Establish a beachhead in Polish Silesian manufacturing corridors where legacy ERP entrenchment remains shallow. Łódź factory automation programs present whitespace for governed self-service analytics targeting Industry 4.0 retrofits. Graph neural network fraud detection modules offer a differentiated go-to-market angle against rule-engine incumbents. Mid-market pharmaceutical contract manufacturers in Central Europe represent underpenetrated demand for EMA-compliant batch release decision systems. For Investors and Strategic Acquirers: Specialized analytics vendors with embedded explainability tooling represent the most attractive acquisition archetype. These firms command premium positioning as GDPR Article 22 enforcement tightens across French and German jurisdictions. Long-term viability hinges on sustaining R&D velocity through the EU AI Act implementation wave. Monitor BfDI and CNIL interpretive convergence as the critical inflection signal for product roadmap fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding decision intelligence into SAP S/4HANA workflows captures German manufacturing procurement. |
| Regulatory Certification Pathway | ESO pre-certification for EU AI Act high-risk systems accelerates enterprise sales cycles. |
| Strategic Partnership | Hyperscaler alliances with Frankfurt data center operators secure GPU capacity commitments. |
| Geographic Expansion | Kraków delivery centers enable cost-competitive Central European market coverage. |
| Acquisition of Specialist Firm | SHAP and LIME explainability modules address GDPR Article 22 procurement blockers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to calibrate market sizing and growth assumptions. Primary interviews with chief data officers at Frankfurt banking groups, IT procurement leads at German automotive suppliers, regulatory affairs directors at pharmaceutical multinationals, and platform engineers at cloud service providers informed demand patterns. Secondary validation drew from SEC filings of listed software vendors, EU AI Act implementation guidance documents, EMA algorithmic transparency guidelines, and hyperscaler capex disclosures. Bottom-up deployment counts and top-down enterprise IT spending estimates were triangulated to anchor projections.
Calibration against historical adoption curves in adjacent analytics markets refined the analytical framework across the analysis window. Segmentation dimensions modeled include product type, deployment architecture, end-user industry, and application use case, with regulatory risk tier adding an industry-specific layer. CAGRs were derived from fitted growth curves incorporating compliance deadline effects and cloud migration velocity. GPU infrastructure capacity constraints and MLOps talent availability served as industry-specific forecast inputs.
Stress conditions across EU AI Act enforcement timing, hyperscaler data center expansion schedules, and legacy system modernization budgets were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization and enterprise cloud migration propensity. Quarterly review of BfDI-CNIL interpretive divergence and ESO standards publication timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Reinforcement Learning Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market