
 UI Design Software Market | 2026-2036
UI Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
UI Design Software Market Insights
Platform licensing revenue is reshaping how UI design software vendors capture lifetime value from enterprise accounts. Adobe Inc. leverages its Creative Cloud ecosystem to bundle interface design tools with adjacent creative workflows. Figma, Inc. sustains market momentum through real-time collaboration architecture that locks in distributed product teams. Sketch B.V. anchors its position within macOS-native professional design studios seeking offline performance.
UI design software encompasses digital tools for creating, prototyping, and iterating visual interfaces across web and mobile applications, typically supporting vector-based canvas rendering, component libraries, and interactive state management at frame rates exceeding 60fps for preview fidelity. The primary commercial purpose centers on compressing design-to-development handoff cycles while preserving brand consistency across multi-channel product experiences. Prototyping tools command the deepest enterprise budgets as product teams demand clickable simulations before engineering commitment. Collaboration platforms represent the fastest-expanding segment as hybrid work models permanently alter synchronous design review rituals. Wireframing software occupies a mature utility position where price compression limits margin expansion.
FCC guidelines on digital accessibility and the EU AI Act's transparency mandates for automated interface generation are elevating compliance requirements across vendors selling into regulated sectors. ISO 9241 ergonomic standards and WCAG accessibility frameworks increasingly appear as procurement gatekeepers in government and healthcare contracts. Stakeholders must monitor how generative AI feature integration triggers new liability regimes for design output ownership and bias disclosure.
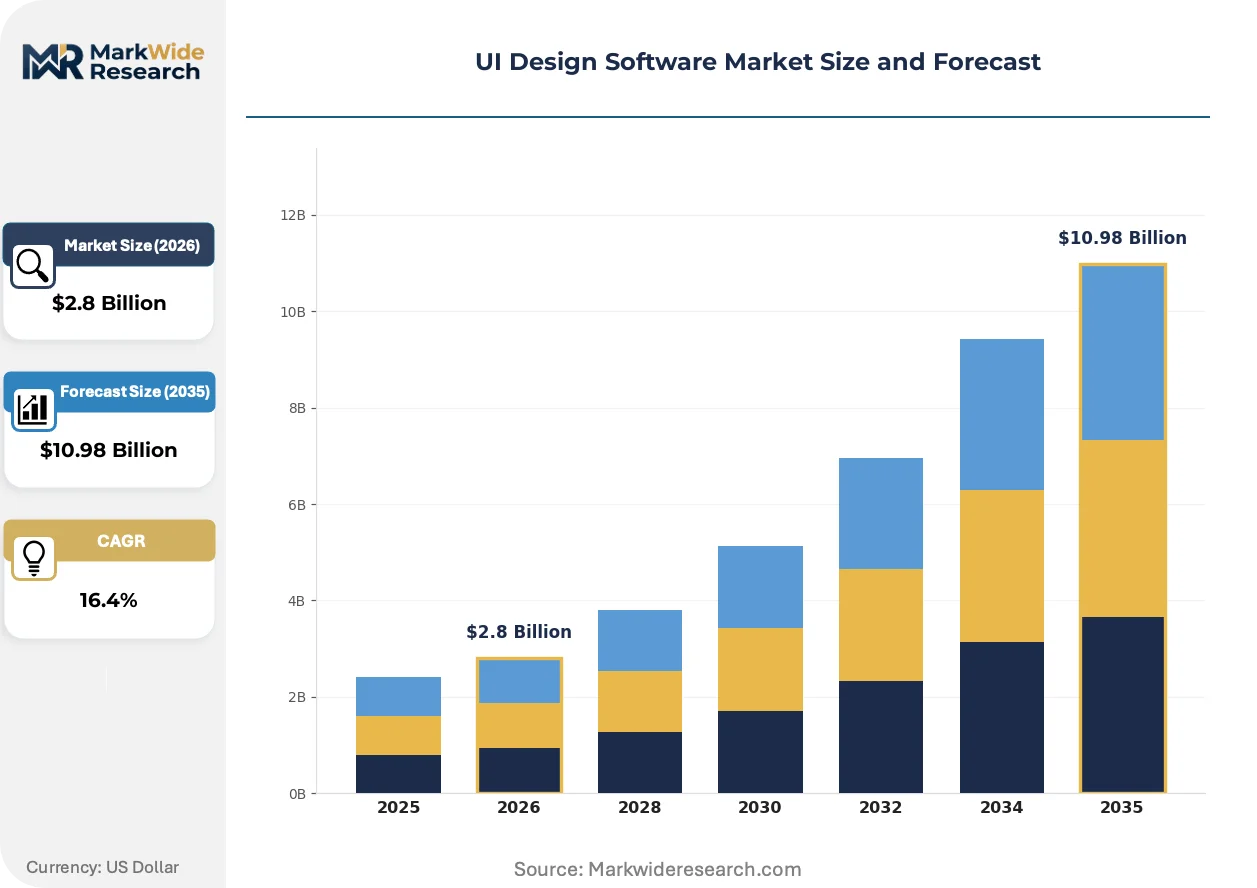
Market Dynamics
Real-time collaborative infrastructure is compressing design-to-development cycles while forcing vendors to rebuild pricing models around seat-based subscriptions rather than perpetual licenses.
Growth Catalysts
- GDPR consent-driven interface mandates:European enterprises must redesign data collection touchpoints, creating recurring procurement cycles for compliance-validated design tools.
- Generative AI code generation:Automated frontend output from design files is collapsing handoff friction for product teams managing multi-platform releases.
- South Korea digital government initiative:Public sector interface modernization is driving institutional demand for accessible, standardized design systems.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominance creates vendor lock-in risk for browser-based design platforms dependent on edge rendering.
- EU AI Act transparency requirements:Automated interface generation features face disclosure obligations that slow feature rollout and increase legal review overhead.
- Vector rendering engine licensing:Core graphics libraries from Skia and Cairo carry royalty structures that compress margins for independent software vendors.
Strategic Opportunities
- India SME design tooling gap:Price-sensitive product studios lack collaborative alternatives to premium Western platforms, creating entry points for localized distribution.
- Figma-API ecosystem expansion:Third-party plugin marketplaces enable vertical specialization without core platform development investment.
- WCAG 2.2 compliance automation:Real-time accessibility checking during design phase addresses procurement requirements in US federal and healthcare contracting.
Industry Challenges
- Design systems engineering talent scarcity:Organizations struggle to hire specialists capable of maintaining component libraries across distributed teams.
- Legacy Adobe workflow migration:Enterprises face retraining costs and file format conversion friction when transitioning from Creative Cloud-native toolchains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UI Design Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prototyping Tools, Wireframing Software, Graphic Design Apps, Collaboration Platforms End User: Freelancers, Startups, Enterprises, Agencies Technology: Web-Based Solutions, Desktop Applications, Mobile Apps, Hybrid Tools Deployment: Cloud-Based, On-Premises, SaaS, Installation |
| Companies Covered | Adobe Inc., Figma, Inc., Sketch B.V., InVision Studio, Webflow, Lucidchart, Balsamiq, Axure, Proto.io, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UI Design Software Market Trends and Innovations
Generative capabilities are embedding directly into canvas interfaces, transforming static design tools into active co-creation environments rather than passive production utilities.
AI-assisted component generation is digitizing the manual work of building design systems from scratch. Enterprise product teams at Fortune 500 technology firms are deploying these features across 60-70% of new projects within eighteen months of platform adoption. The compression of system-build time from weeks to hours is digitizing how organizations scale consistent interfaces across product portfolios.
The EU AI Act's transparency mandates for automated decision-making interfaces are forcing vendors to build audit trails into generative features. Design platforms must now log which AI models contributed to specific interface elements and disclose confidence thresholds for layout recommendations. Healthcare and financial services procurement teams in Germany and France are prioritizing vendors with pre-built compliance documentation.
Seat-based licensing is fragmenting into role-specific tiers as product organizations separate viewer, commenter, and editor permissions. Design operations teams at scaled technology companies are negotiating department-level contracts rather than enterprise-wide agreements. This unbundling is most pronounced in United States SaaS procurement, where finance departments scrutinize per-seat utilization rates quarterly.
UI Design Software Market Segmentation
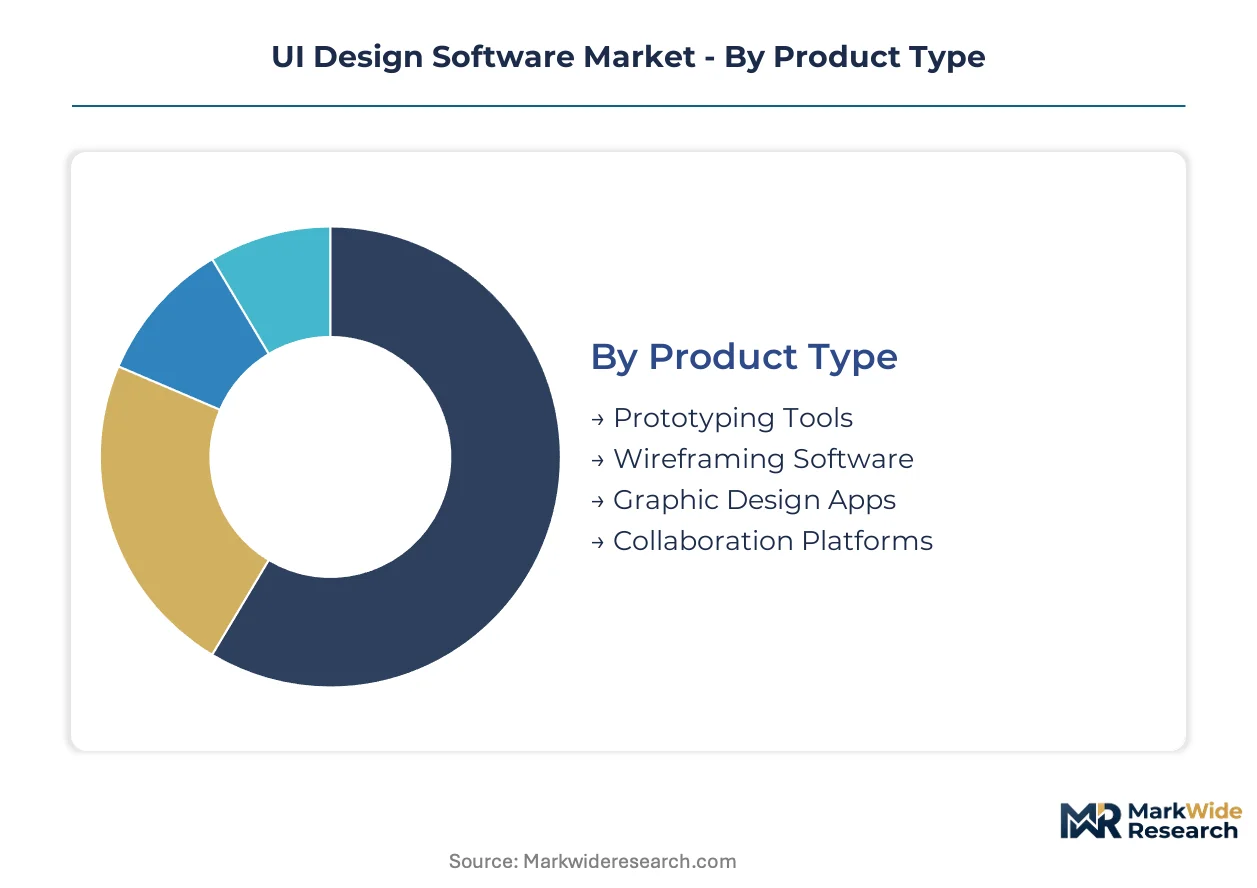
UI design software vendors architect product portfolios around distinct workflow intensities and team collaboration requirements. Segmentation reveals how procurement patterns diverge between rapid prototyping needs and systematic design system governance across organization types.
Product Type:
Tool selection tracks the design process maturity curve from conceptual exploration through production-ready specification.
- Prototyping Tools:Interactive simulation environments supporting clickable state transitions and micro-interaction sequencing at 60fps preview fidelity. Enterprise product teams in Germany and the United States deploy these for stakeholder validation before engineering commitment, driven by compressed release cycles in SaaS verticals.
- Collaboration Platforms:Real-time multiplayer canvas architecture with version branching and component library synchronization across distributed contributors. Hybrid work models in South Korean technology firms and US West Coast product studios sustain demand expansion here.
- Wireframing Software:Low-fidelity layout utilities emphasizing information architecture over visual polish. Freelancers and early-stage startups leverage these for rapid concept validation.
- Graphic Design Apps:Vector and raster manipulation tools for visual asset creation and brand collateral production. Marketing agencies maintain parallel subscriptions alongside dedicated interface tools.
The dominant share belongs to Prototyping Tools, while Collaboration Platforms is closing the gap fastest.
End User:
Organization scale dictates feature requirements and pricing elasticity across the customer base.
- Enterprises:Multi-department deployments requiring SSO integration, audit logging, and design system governance at portfolio scale. Compliance mandates from GDPR and the EU AI Act drive procurement of consent-tracking and transparency features.
- Agencies:Client-facing service operations demanding white-label presentation modes and rapid project templating. Billable hour pressures favor tools with minimal onboarding friction.
- Startups:Resource-constrained product teams prioritizing free-tier scalability and plugin ecosystem breadth over enterprise security certifications.
- Freelancers:Individual practitioners selecting tools based on file format portability and one-time purchase options where available.
Enterprises command the deepest contract values, with Agencies expanding seat counts most aggressively.
Technology:
Runtime architecture determines performance characteristics and integration flexibility for development pipelines.
- Web-Based Solutions:Browser-rendered canvases leveraging WebGL and WASM for near-native vector manipulation. AWS, Azure, and Google Cloud infrastructure dependencies create latency optimization challenges for vendors.
- Desktop Applications:Native OS compilation delivering offline reliability and GPU-accelerated rendering for complex component libraries. macOS-native studios in professional design clusters retain preference here.
- Mobile Apps:Touch-optimized interfaces for tablet-based sketching and presentation review. Field validation workflows in distributed teams sustain niche demand.
- Hybrid Tools:Synchronized local-cloud architectures enabling offline work with automatic conflict resolution. Enterprise procurement teams in regulated sectors prioritize these for business continuity.
Web-Based Solutions capture the broadest addressable market, though Hybrid Tools are gaining traction fastest among compliance-sensitive buyers.
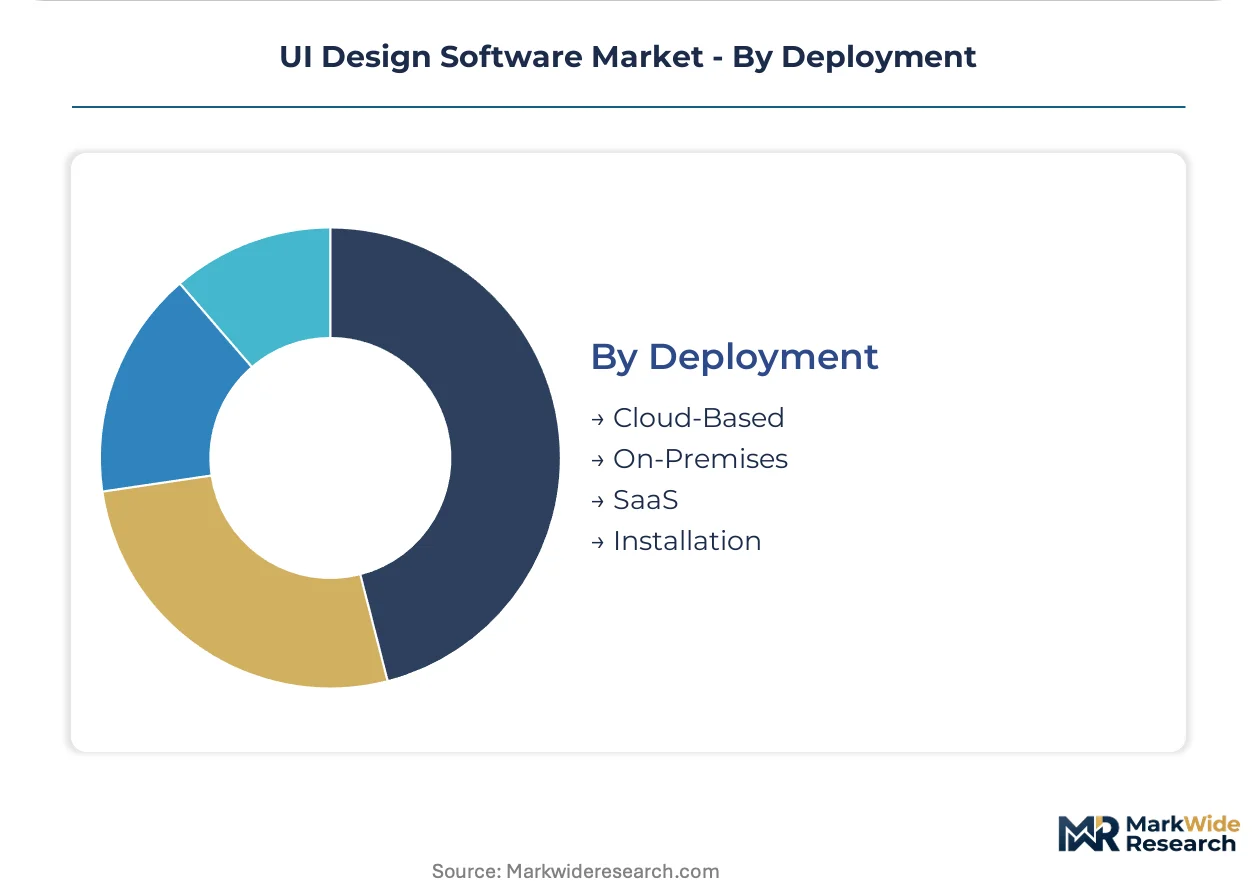
Deployment:
Hosting model selection reflects data sovereignty requirements and IT governance maturity.
- Cloud-Based:Fully managed multi-tenant infrastructure with automatic updates and elastic compute scaling. GDPR Article 44 transfer mechanism compliance dominates European vendor evaluation.
- SaaS:Subscription-metered access with API-first architecture for CI/CD pipeline integration. US federal contractors prioritize FedRAMP-authorized instances.
- On-Premises:Self-hosted installations within customer-controlled data centers. Financial services firms in Germany and healthcare systems in France mandate these for patient data protection.
- Installation:Perpetual license with local execution and manual update cycles. Air-gapped environments in defense and critical infrastructure sectors sustain residual demand.
Cloud-Based deployment holds the installed base majority, while On-Premises is expanding fastest among regulated industry adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States enterprises prioritize real-time collaboration infrastructure for distributed product teams. German procurement teams weight GDPR compliance and audit documentation above feature velocity. South Korean government digitization mandates drive institutional demand for accessible design systems.
United States
Enterprise SaaS procurement dominates demand, with design operations teams negotiating seat-based contracts quarterly. FCC digital accessibility guidelines and Section 508 procurement requirements elevate WCAG 2.2 compliance to contract gatekeeper status. San Francisco Bay Area and Seattle technology clusters concentrate vendor headquarters and beta program participation.
Germany
Industrial design studios and automotive interface teams anchor enterprise adoption, prioritizing offline reliability and data sovereignty. GDPR Article 44 transfer mechanism compliance and EU AI Act transparency mandates dominate vendor evaluation criteria. Berlin and Munich professional design clusters sustain preference for native desktop performance over browser-based alternatives.
South Korea
Public sector digital government initiatives institutionalize demand for standardized, accessible interface components across ministries. MFDS and national digital service standards mandate WCAG-equivalent compliance for government-facing applications. Seoul Capital Area technology corridors concentrate both vendor development centers and enterprise procurement decision-making.
United Kingdom
Agency service models and fintech product studios drive commercial demand, with billable-hour pressures favoring rapid onboarding and white-label presentation modes. UK Information Commissioner's Office guidance on automated decision-making interfaces aligns with emerging EU AI Act disclosure requirements. London creative clusters and Manchester digital agencies sustain dual subscription models for client collaboration.
India
Price-sensitive product studios and startup ecosystems create demand for freemium-tier scalability and plugin ecosystem breadth. BIS standards for software quality and emerging data localization requirements shape procurement for regulated sectors. Bangalore and Hyderabad technology corridors concentrate design talent and offshore service delivery centers serving Western clients.
UI Design Software Market Competitive Landscape
Capability concentration sits with specialized collaborative platforms; scale advantage sits with diversified creative suites. The vendor base organizes into three functional tiers: ecosystem-integrated incumbents, collaboration-native specialists, and component-focused utilities. Consolidation pressure operates through API ecosystem expansion and generative AI feature integration rather than horizontal M&A. Vertical integration into cloud infrastructure and proprietary rendering engines represents the dominant competitive move.
Within the collaboration-native tier, Figma, Inc. and Sketch B.V. exemplify divergent architectural bets—browser-first versus native-desktop—that segment the professional design studio market. Adobe Inc. anchors the ecosystem-integrated incumbent position, leveraging Creative Cloud subscription bundling to capture adjacent workflow value. These three entities collectively represent the competitive poles around which procurement patterns organize: real-time multiplayer infrastructure, offline performance optimization, and creative workflow integration.
| Leading Market Players |
|---|
| Adobe Inc. |
| Figma, Inc. |
| Sketch B.V. |
| InVision Studio |
| Webflow |
| Lucidchart |
| Balsamiq |
| Axure |
| Proto.io |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific submarine cable latency costs compress margins for browser-based platforms serving European enterprises from US West Coast data centers, concentrating pricing power with vendors operating distributed edge infrastructure while forcing tiered subscription models that separate viewer permissions from editor seats.
Pricing Analysis
Long-term enterprise offtake agreements dominate procurement for scaled technology firms, while agencies negotiate project-based monthly subscriptions and freelancers transact through spot-access freemium tiers. Price differentiation rests on SSO integration depth and WCAG 2.2 certification status, with compliance-validated platforms commanding premium positioning. Cost compression in the startup tier intensifies as open-source alternatives erode base-tier willingness-to-pay. Freelancers exhibit highest price sensitivity; regulated healthcare and financial services buyers demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for GPU-accelerated rendering hardware deployed in on-premises installations. Core graphics libraries draw from Skia and Cairo open-source projects with royalty-bearing commercial licenses, while cloud infrastructure concentrates in AWS, Azure, and Google Cloud facilities across the United States, Ireland, and Singapore. Single-source vulnerability in WebGL browser engines creates downstream dependency. Distribution runs through direct self-service portals for individual users and solution-selling partnerships for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent capable of bridging design systems engineering with regulatory compliance documentation commands scarcity premiums, creating structural advantage for vendors investing in automated governance tooling.
For Market Incumbents: Build switching-cost moats through deep API ecosystem lock-in and generative AI feature integration that embeds audit trails directly into canvas workflows. Defensive consolidation should prioritize acquiring WCAG 2.2 compliance automation specialists to preempt regulatory procurement gatekeeping. Capacity addition in Frankfurt and Singapore data centers addresses GDPR Article 44 transfer mechanism requirements and MFDS-aligned sovereign data mandates. For New Entrants and Emerging Players: Pursue white-space capture in India's price-sensitive product studio segment through localized freemium distribution and Hindi-language plugin marketplaces. The most penetrable geography sits in Bangalore and Hyderabad corridors where offshore service delivery centers demand collaborative tooling without Western premium pricing. Go-to-market execution should anchor in design education partnerships that seed trial adoption before enterprise procurement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified creative suite parents where UI design software represents non-core revenue dilution. Long-term viability favors collaboration-native architectures over legacy desktop codebases given permanent hybrid work normalization. Watch for inflection signals in South Korean public sector RFP volume, where digital government initiative procurement velocity indicates institutional demand maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding generative AI code generation collapses handoff friction for multi-platform engineering teams. |
| Strategic Partnership | WCAG 2.2 compliance automation alliances unlock US federal and healthcare contracting procurement gates. |
| Acquisition of Specialist Firm | Design systems engineering talent scarcity makes component library automation targets strategically valuable. |
| Geographic Expansion | Localized distribution in India addresses SME tooling gaps left by premium Western platform pricing. |
| Product Launch | Hybrid local-cloud architectures target regulated sectors requiring business continuity and data sovereignty. |
Research Methodology
Cross-validation between primary interviews with design operations executives, platform engineers, IT procurement officers, and regulatory compliance leads anchors the qualitative findings against secondary validation from SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU AI Act implementation guidance documents. Bottom-up triangulation across seat-based subscription metrics and top-down reconciliation against creative software category spend estimates ensures analytical coherence.
Calibration against historical adoption curves for SaaS collaboration tools refines the projection framework across deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster dimensions. CAGRs derive from segmented growth rate assumptions applied to baseline vendor-reported metrics and third-party platform usage analytics. Generative AI feature penetration rates and GDPR-mandated interface redesign cycles constitute primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in enterprise software budget allocations and cloud infrastructure pricing would shift the trajectory materially. Forecasts reflect documented assumptions regarding hybrid work permanence and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Saas Based HRM Market
Software & Services
Optical Design Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
Online Whiteboard Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Relational Database Management System Market
Software & Services
Global Presentation Software Market
Software & Services
Data Compression Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Europe Business Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Global API Management Software Market
Software & Services
Sports League Management Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Global Furniture Manufacturing Software Market