
 Software Testing Company Market | 2026-2036
Software Testing Company Market Size, Share, and Industry Trends Forecast 2026-2036
Software Testing Company Market Insights
The EU AI Act is broadening the cost-of-entry calculus for vendors seeking to certify algorithmic systems in European deployments. Accenture leverages its consulting-to-testing pipeline to anchor large-scale compliance programs. Tata Consultancy Services sustains delivery density through its India-based testing centers. Cognizant competes on regulatory interpretation depth, positioning its risk advisory and QA practices as integrated offerings.
Software testing companies deliver systematic verification, validation, and defect-detection services across application lifecycles, employing scripted test cases, automation frameworks, and synthetic data environments to assure functional correctness, security posture, and performance thresholds. Their primary commercial purpose is to reduce production failures and liability exposure before code reaches operational environments. Automated testing now leads service type revenue as CI/CD pipelines shorten release cycles, while security testing captures expanding margin pools from compliance-driven buyer segments. Cloud-based deployment is displacing on-premise installations among mid-market adopters seeking elastic test infrastructure.
FDA software validation guidelines for medical devices, SEC cybersecurity disclosure requirements for public filers, and EU AI Act conformity assessment obligations collectively elevate testing rigor across regulated industries. These frameworks mandate documented traceability, independent verification, and recurring regression protocols that external testing specialists must execute. Stakeholders should monitor how emerging algorithmic accountability rules in additional jurisdictions expand mandatory third-party audit scopes beyond current geographic coverage.
Market Dynamics
CI/CD pipeline compression is forcing testing vendors to embed quality assurance directly into developer workflows rather than operate as downstream gatekeepers. This structural shift collapses traditional handoff points and rewards tooling that integrates with GitOps environments.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:US public filers must document material cybersecurity incidents and governance procedures, mandating independent security testing and recurring penetration assessments.
- EU AI Act Conformity Assessment:European deployments of high-risk algorithmic systems require documented traceability and third-party verification, expanding audit scopes for testing specialists.
- Automated Test Scripting:Synthetic data generation and self-healing test frameworks reduce maintenance overhead for regression suites in agile release cycles.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers proficient in both domain-specific regulations and automation architecture limits service expansion velocity.
- Cloud Infrastructure Concentration:Dependency on hyperscaler compute pricing for elastic test environments exposes margins to provider rate adjustments.
- Regulatory Fragmentation:Divergent FDA, EMA, and NMPA software validation protocols force redundant testing cycles for multi-jurisdiction medical device deployments.
Strategic Opportunities
- India Delivery Scale:Bengaluru's testing lab density supports cost-competitive automation services for North American enterprise clients seeking offshore capacity.
- Quantum-Resistant Cryptography Testing:NIST post-quantum algorithm migration creates new verification demand for financial services infrastructure.
- Embedded Device Firmware Validation:IoT security mandates from FCC and EU Cybersecurity Act expand hardware-software integration testing requirements.
Industry Challenges
- Legacy System Integration:Mainframe and COBOL environments resist containerized testing tools, forcing hybrid automation architectures.
- ISO 17025 Accreditation Timelines:Laboratory certification for medical device testing extends go-to-market cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Testing Company Market |
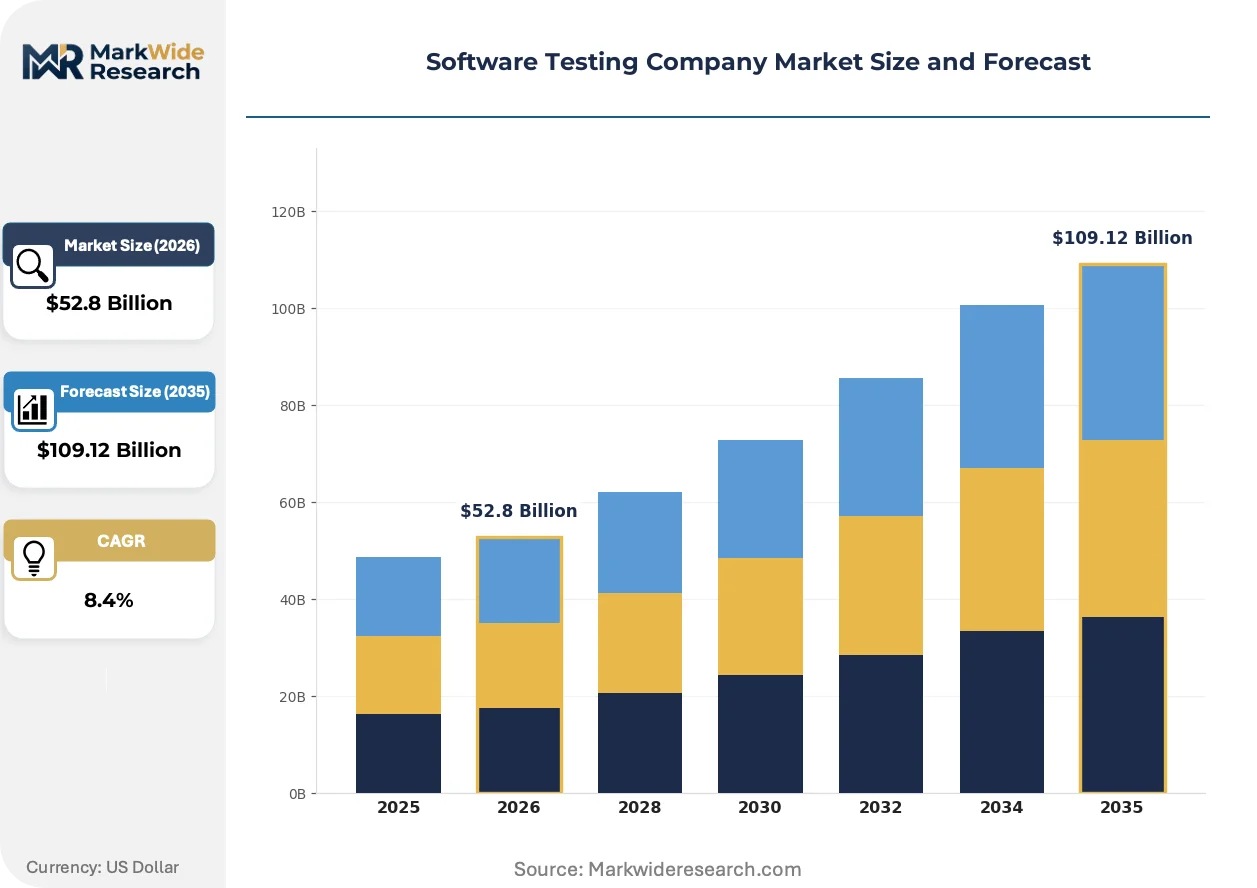
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Manual Testing, Automated Testing, Performance Testing, Security Testing Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: IT Companies, Financial Services, Healthcare Providers, Retailers Test Type: Regression Testing, Unit Testing, Integration Testing, User Acceptance Testing |
| Companies Covered | Accenture, Tata Consultancy Services, Infosys, Cognizant, Wipro, Capgemini, IBM, Cigniti, QA Mentor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Testing Company Market Trends and Innovations
Testing service architecture is fragmenting into composable components that buyers assemble rather than purchase as bundled engagements. This decomposition rewards vendors with API-first platforms and penalizes monolithic service catalogs.
Test automation frameworks are modularizing around containerized execution engines that spin up ephemeral environments per commit. Financial services firms with compressed release windows adopt these micro-test architectures to parallelize validation. The structural consequence is collapsing the distinction between unit testing and system testing into continuous verification layers.
The EU AI Act's risk-based classification system mandates independent conformity assessment for high-risk algorithmic systems before market placement. Medical device manufacturers and credit scoring platforms face expanded documentation requirements for training data provenance and model drift monitoring. German and French notified bodies are building specialized AI audit capacities to handle assessment volume.
Enterprise buyers now unbundle testing contracts from development engagements, sourcing specialized security and performance validation through separate RFP processes. This disintermediation favors pure-play testing vendors over full-service consultancies. The pattern is most pronounced among US healthcare payers subject to HIPAA security rule enforcement and state-level breach notification laws.
Software Testing Company Market Segmentation
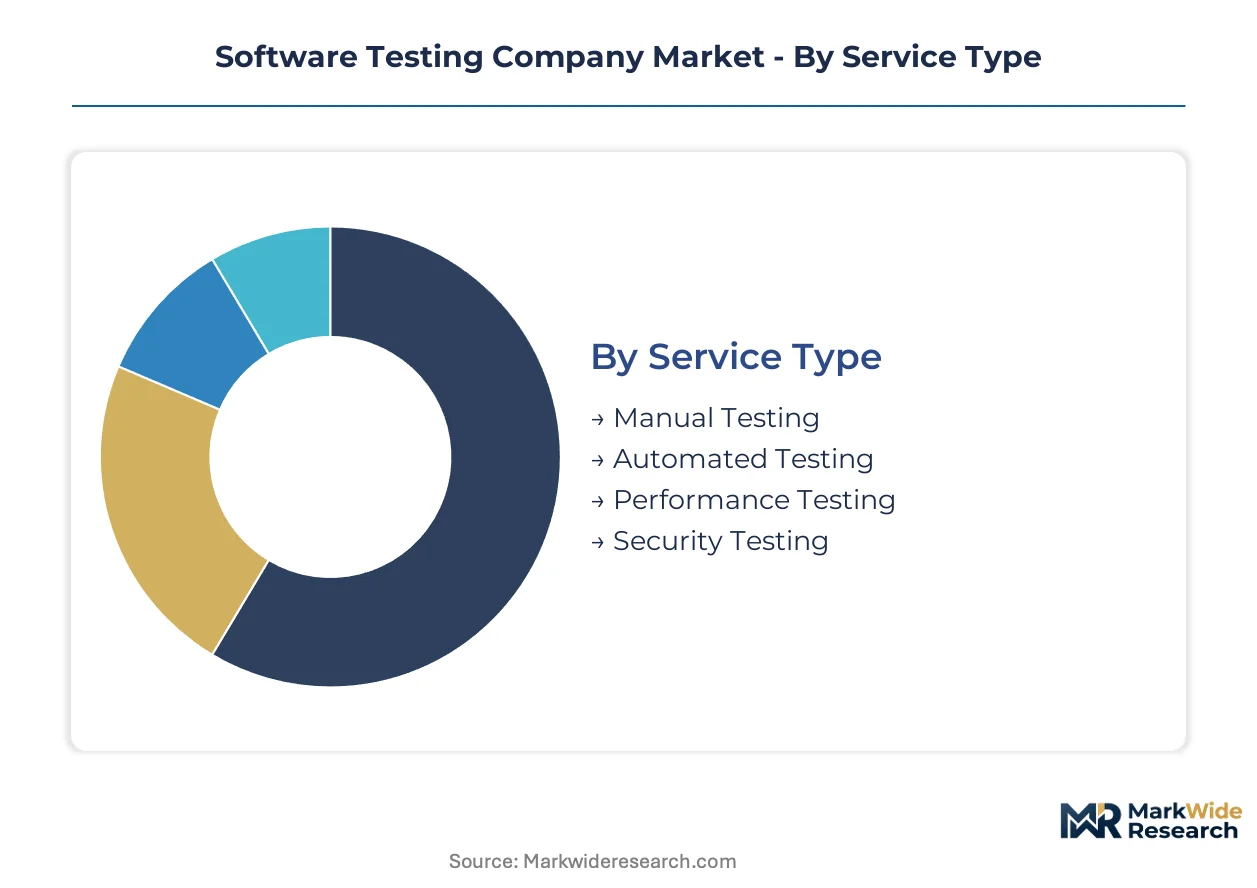
Segmentation reveals how testing demand fragments across technical architectures, delivery modes, and regulatory exposure profiles. Buyers select service tiers based on release velocity requirements and compliance burden severity.
Service Type:
Upgrade cycles in CI/CD tooling are compressing testing windows and forcing buyers to rebalance manual against automated capacity.
- Automated Testing:Self-healing scripts and synthetic data generation reduce maintenance overhead for regression suites in compressed release cycles. Financial services firms in the United States deploy these frameworks to satisfy SEC cybersecurity disclosure mandates for recurring penetration assessments.
- Security Testing:Independent verification of application posture and infrastructure hardening captures expanding margin pools from compliance-driven segments. Healthcare providers subject to HIPAA enforcement prioritize this tier for breach liability reduction.
- Manual Testing:Exploratory validation of user experience edge cases persists where human judgment outperforms script coverage.
- Performance Testing:Load and stress validation for cloud-native architectures ensures elasticity thresholds under traffic spikes.
Automated Testing sits at the top of the volume ranking, with Security Testing climbing the fastest.
Deployment Model:
Cost tier differentiation separates enterprise buyers seeking capital control from mid-market adopters prioritizing operational flexibility.
- Cloud-Based:Elastic compute provisioning for ephemeral test environments aligns with agile sprint cadences and reduces fixed infrastructure commitment. Mid-market software vendors in India leverage Bengaluru lab density to deliver these services cost-competitively to North American clients.
- SaaS:Subscription access to pre-configured automation frameworks eliminates setup latency and accelerates time-to-first-test for lean development teams.
- Hybrid:Split architectures retain sensitive data on-premise while pushing compute-intensive validation to cloud instances.
- On-Premise:Air-gapped installations persist in defense and classified government contracts with data sovereignty requirements.
Cloud-Based commands the largest share of new contract value, with SaaS expanding most quickly among venture-backed software startups.
End User:
Application complexity and regulatory scrutiny intensity vary sharply across buyer verticals, reshaping service packaging requirements.
- Financial Services:Algorithmic trading platforms and credit scoring systems face EU AI Act conformity assessment obligations and SEC cybersecurity disclosure rules. These institutions maintain the highest testing spend per application due to audit documentation requirements.
- Healthcare Providers:Electronic health record systems and connected medical devices trigger FDA software validation guidelines and state-level breach notification laws. HIPAA security rule enforcement drives recurring third-party validation contracts.
- IT Companies:Native digital product firms prioritize velocity-optimized automation over compliance-heavy documentation.
- Retailers:Seasonal traffic spikes and payment card industry standards shape performance and security testing procurement.
Financial Services occupies the peak spending position, with Healthcare Providers gaining share fastest as FDA and EU MDR requirements tighten.
Test Type:
Maturity differentiation separates foundational validation layers from specialized assurance activities demanded by regulated deployments.
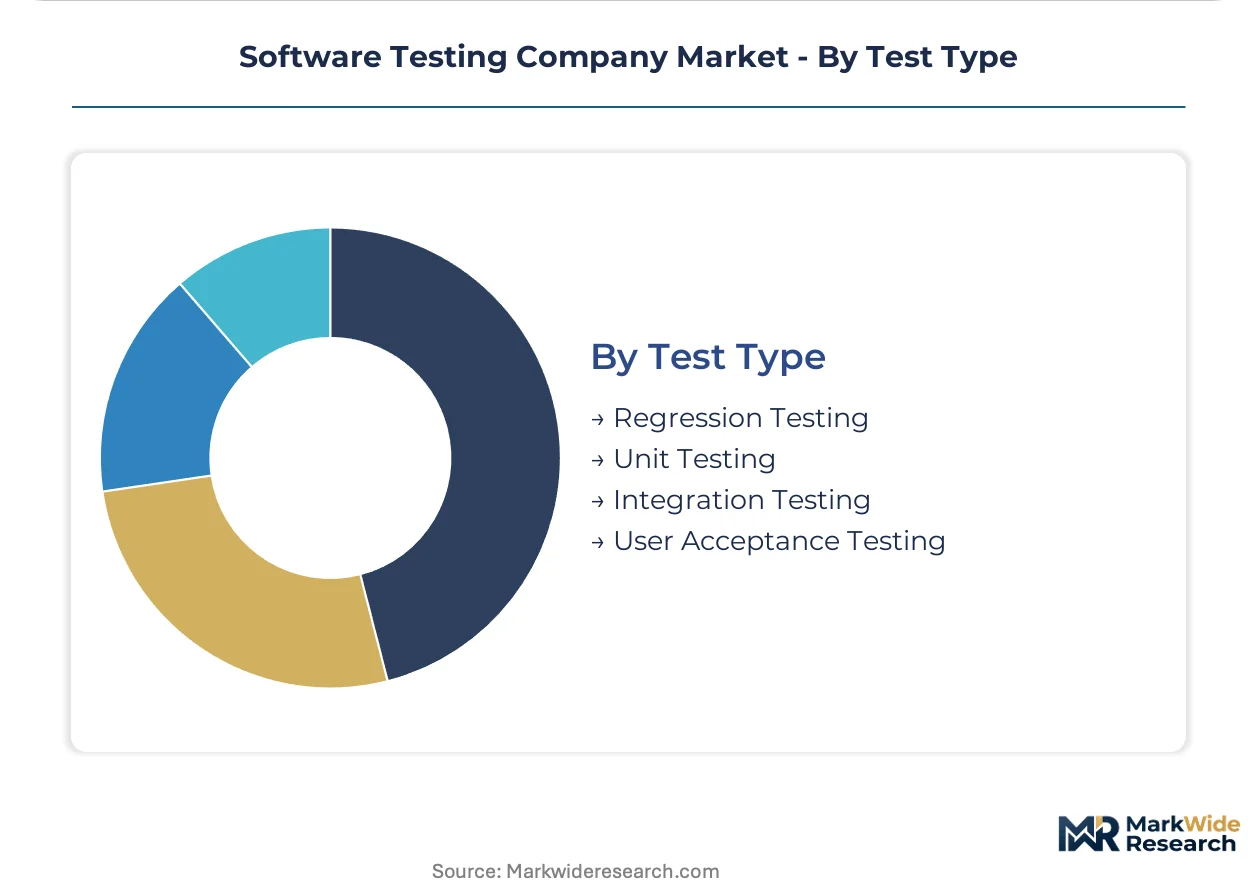
- Regression Testing:Recurring validation of unchanged functionality after code modifications prevents defect injection in iterative development. Automated frameworks dominate this category as release frequency accelerates.
- Integration Testing:Verification of API contract compliance and microservice interoperability addresses distributed architecture complexity. Cloud-native enterprises prioritize this tier to reduce production incident rates.
- Unit Testing:Developer-executed validation of isolated code components remains embedded within integrated development environments.
- User Acceptance Testing:Business stakeholder sign-off protocols persist for workflow-critical enterprise applications.
Regression Testing leads by contract volume, with Integration Testing showing the steepest expansion trajectory as microservice adoption broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software testing services originated in the United States during the 1970s as mainframe quality assurance departments, then scaled through India's 1990s outsourcing boom before fragmenting into specialized regional delivery models.
United States
Financial services firms in New York and San Francisco drive premium testing spend under SEC cybersecurity disclosure mandates. FDA software validation guidelines for medical devices create additional compliance demand from Boston's biotech corridor. Silicon Valley maintains the densest concentration of CI/CD-native automation vendors serving enterprise technology clients.
India
Bengaluru's testing lab ecosystem processes the majority of North American offshore automation contracts through TCS, Wipro, and Infosys delivery centers. RBI's cybersecurity framework for banks and SEBI's IT audit requirements expand domestic regulatory testing demand. Hyderabad and Pune have emerged as secondary hubs for security testing specialization.
Germany
Automotive OEMs in Stuttgart and Munich require ISO 26262 functional safety testing for autonomous driving software under KBA type-approval processes. EU AI Act conformity assessment obligations target Frankfurt's algorithmic trading platforms and Munich's medical AI developers. Berlin hosts a growing cluster of GDPR compliance testing specialists.
United Kingdom
London's fintech density generates demand for open banking API testing under FCA operational resilience requirements. The Financial Conduct Authority's third-party risk management rules mandate independent validation of cloud-hosted trading infrastructure. Manchester and Edinburgh have developed specialized healthcare testing capacity for NHS digital transformation programs.
China
NMPA medical device software validation requirements tighten testing protocols for Shanghai and Beijing's health technology developers. MIIT cybersecurity review processes for critical information infrastructure create state-mandated testing demand. Shenzhen's hardware-software integration ecosystem drives embedded firmware validation for IoT export markets.
Software Testing Company Market Competitive Landscape
The competitive structure tilts toward diversified technology consultancies with embedded testing practices. Tier-one players combine regulatory interpretation depth with automation platform investments. Tier-two specialists compete on vertical-specific compliance expertise. Dominant competitive moves include strategic partnerships with hyperscaler cloud providers and geographic expansion through India-based delivery centers.
Within the diversified consultancy tier, Accenture and Tata Consultancy Services exemplify scale-driven positioning. Accenture occupies a position anchoring large-scale compliance programs through its consulting-to-testing pipeline. Tata Consultancy Services represents delivery density optimization through India-based testing center networks. Cognizant sits within the regulatory interpretation specialist archetype, integrating risk advisory with quality assurance practices.
| Leading Market Players |
|---|
| Accenture |
| Tata Consultancy Services |
| Infosys |
| Cognizant |
| Wipro |
| Capgemini |
| IBM |
| Cigniti |
| QA Mentor |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO 17025-accredited laboratories and non-accredited automation shops bifurcates pricing power across delivery tiers, with accredited providers commanding premium positioning while commodity script maintenance compresses margins in Bengaluru's dense testing corridor.
Pricing Analysis
Bundled compliance-plus-automation engagements carry 40-60% premiums over unbundled script-only contracts, with FDA validation tiers and EU AI Act conformity assessments driving the widest spreads. Price differentiation hinges on regulatory interpretation depth and synthetic data infrastructure maturity. Cost compression in offshore automation pools intensifies as Indian delivery centers add capacity. Mid-market software vendors exhibit highest price sensitivity, while financial services filers under SEC mandates show lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for integrated compliance programs, while partner-mediated distribution serves mid-market adopters through SaaS marketplaces. Supply concentrates in India, the United States, and Germany. Talent pipelines draw from computer science institutes, domain-specific regulatory training programs, and hyperscaler certification ecosystems. Single-source vulnerability in specialized AI audit talent pools concentrates risk. Distribution runs through consulting-to-testing pipelines, independent pure-play vendors, and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in security testing and AI conformity assessment tiers, where regulatory complexity creates sustainable pricing power against automation commoditization pressures.
For Market Incumbents: Extend platform integration depth to capture unbundled testing demand from healthcare payers and financial services firms. Deepen ISO 17025 accreditation coverage to defend positioning against emerging AI audit specialists. Build captive synthetic data generation capabilities to reduce third-party licensing exposure.
For New Entrants and Emerging Players: Cloud marketplace partnerships offer lowest-friction customer acquisition for CI/CD-native automation tools targeting venture-backed software startups. Quantum-resistant cryptography testing for financial services infrastructure represents the most penetrable white-space segment. Lead with API-first architectures to bypass incumbent consulting relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory interpretation expertise concentrates in founder-led boutiques lacking automation platform scale. Long-term viability favors vertically integrated players combining India delivery density with European regulatory proximity. Watch NIST post-quantum algorithm migration timelines as inflection indicator for cryptography testing demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | Medical device manufacturers require documented laboratory certification under FDA software validation guidelines. |
| AI Conformity Assessment Partnership | EU AI Act mandates independent verification for high-risk algorithmic systems before European market placement. |
| Synthetic Data Infrastructure Buildout | Self-healing test frameworks reduce maintenance overhead for financial services regression suites under SEC mandates. |
| Quantum-Resistant Testing Capability | NIST algorithm migration creates verification demand for cryptographic infrastructure in banking and payments. |
| Embedded Firmware Validation Service | FCC and EU Cybersecurity Act IoT mandates expand hardware-software integration testing requirements. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down service provider capacity tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners informed demand-side validation. Secondary sources include SEC cybersecurity disclosure filings, FDA software validation guidance documents, EU AI Act conformity assessment procedures, and hyperscaler capex disclosures. Triangulation across these inputs ensures segmentation integrity.
Historical trendline analysis of CI/CD adoption curves and regulatory enforcement patterns anchors projection logic across the analysis window. Segmentation dimensions span service type, deployment model, end-user vertical, and test architecture complexity. CAGRs derive from regression analysis of release velocity compression and compliance burden expansion. Forecast inputs incorporate RBI cybersecurity framework evolution and SEBI IT audit requirement tightening.
Revisions become necessary when regulatory enforcement intensity shifts, hyperscaler pricing structures adjust, or quantum computing timelines accelerate beyond current NIST migration assumptions. Forecasts reflect documented assumptions about talent pipeline expansion and accreditation timeline stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Machine Translation Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Productivity Management Software Market
Software & Services
School Timetable Software Market
Software & Services
Software As a Service (Saas) Market
Software & Services
Global Test Data Management Market
Software & Services
Automotive Design Software Market
Software & Services
Global Customer Service Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Communication Software Market
Software & Services
Software Testing Tools Market
Software & Services
Quality Management Software Market
Software & Services
Auto Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Global Custom Software Development Services Market
Software & Services
Client Virtualization Software Market