
 Connectivity Constraint Computing Market | 2026-2036
Connectivity Constraint Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Connectivity Constraint Computing Market Analysis
Autonomous vehicle deployment is hardening demand for low-latency constraint optimization at the network edge. NVIDIA dominates GPU-accelerated inference for vehicular path planning under bandwidth restrictions. IBM leverages its Watson IoT platform to anchor enterprise contracts in smart manufacturing environments. Microsoft competes through Azure Edge Zones, extending cloud-native constraint programming into disconnected or intermittently connected operational settings.
Connectivity constraint computing refers to distributed optimization architectures that execute satisfiability and constraint logic programming across nodes with intermittent, bandwidth-limited, or high-latency network links, typically requiring sub-100 millisecond response thresholds for real-time decision loops. Edge Computing leads deployment topology due to its affinity with latency-critical industrial control systems, while Quantum Computing represents the fastest-growing technology segment as hardware maturity enables hybrid classical-quantum approaches to combinatorial optimization. Fog Computing occupies a mature middle ground in smart city infrastructure, whereas Cloud Computing retains the deepest margin pools through hybrid orchestration software licensing.
The EU AI Act imposes conformity assessment requirements on autonomous decision systems, directly shaping product validation pipelines for European deployments. FDA software validation standards for connected medical devices constrain how Healthcare Monitoring use cases integrate real-time constraint solvers, while ISO 27001 and IEC 62443 frameworks govern cross-border data integrity in Energy sector deployments. Stakeholders must monitor the divergence between regional AI safety certifications and sector-specific operational technology cybersecurity mandates when architecting multi-jurisdictional constraint networks.
Market Dynamics
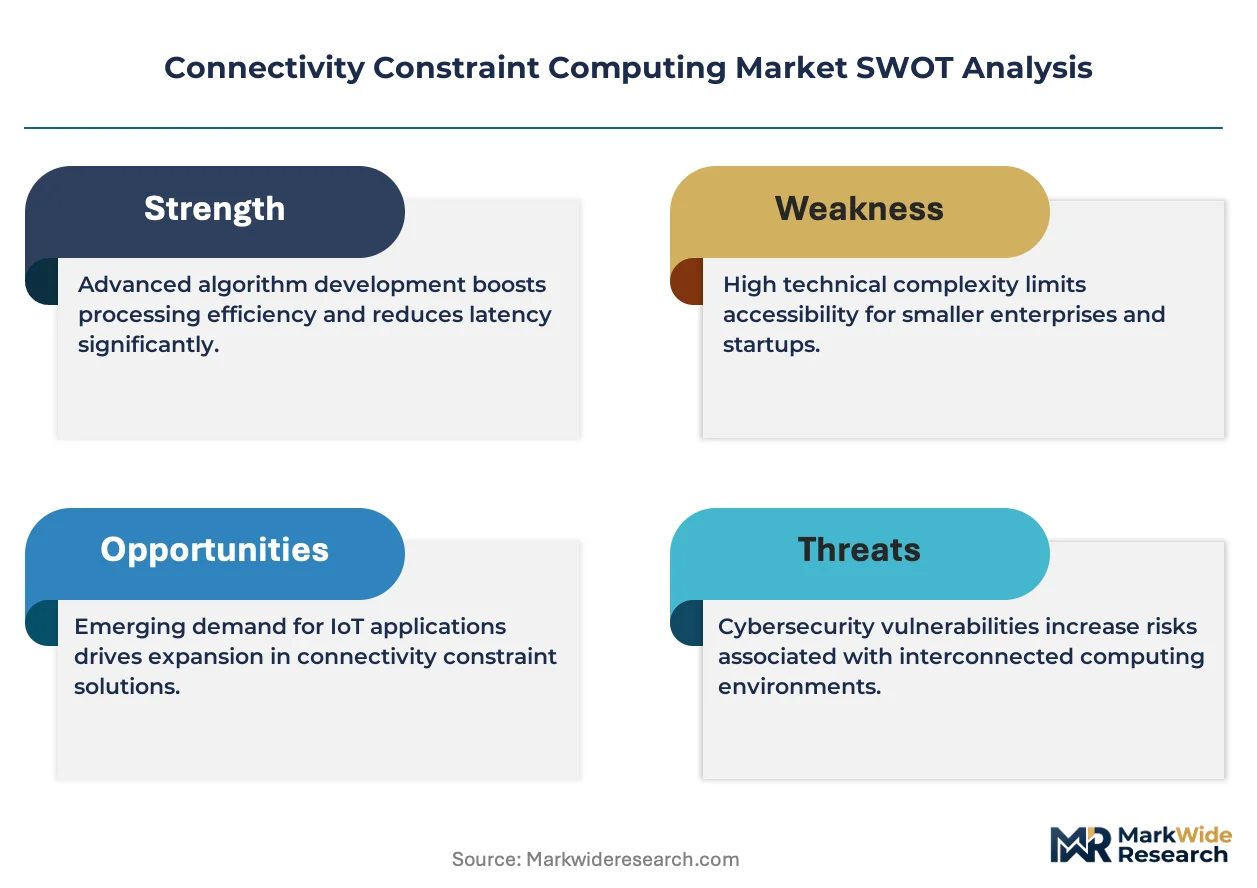
Edge-based constraint solvers are hardening latency requirements across autonomous vehicle manufacturing, while EU AI Act conformity assessments and FDA software validation standards compress deployment timelines for real-time distributed systems in healthcare and automotive verticals.
Growth Catalysts
- EU AI Act Conformity Mandates:European autonomous vehicle manufacturers must integrate auditable constraint logic into safety-critical path planning systems, accelerating procurement of edge-validated solver architectures.
- Germany's Automotive Corridor:Stuttgart and Munich host concentrated R&D facilities from major OEMs deploying sub-100 millisecond constraint optimization for vehicular decision loops.
- Hybrid Classical-Quantum Approaches:Hardware maturity in quantum annealing is enabling combinatorial optimization for bandwidth-constrained logistics networks in smart manufacturing environments.
Market Restraints
- GPU Supply Concentration:Accelerated inference hardware for vehicular path planning depends on concentrated semiconductor fabrication capacity in East Asian foundry networks.
- FDA Validation Timelines:Connected medical devices integrating real-time constraint solvers face 18-36 month software validation cycles that delay healthcare monitoring deployments.
- Specialized Talent Scarcity:Constraint logic programming expertise intersects with embedded systems engineering and cybersecurity, creating acute hiring friction in European automotive clusters.
Strategic Opportunities
- Energy Sector Cybersecurity Integration:IEC 62443 framework adoption in German and French grid infrastructure creates demand for constraint solvers with cross-border data integrity certification.
- Smart City Fog Computing Refresh:Mature smart city installations in Barcelona and Amsterdam require middleware upgrades that embed constraint optimization into legacy sensor networks.
- Performance-Based Licensing Models:Azure Edge Zones and comparable platforms enable outcome-contingent pricing for disconnected operational settings in remote industrial facilities.
Industry Challenges
- ISO 27001 Certification Complexity:Multi-jurisdictional constraint networks must reconcile divergent regional AI safety certifications with sector-specific operational technology cybersecurity mandates.
- Legacy Industrial Control Integration:Brownfield manufacturing environments require protocol translation layers that introduce latency overhead incompatible with sub-100 millisecond response thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connectivity Constraint Computing Market |
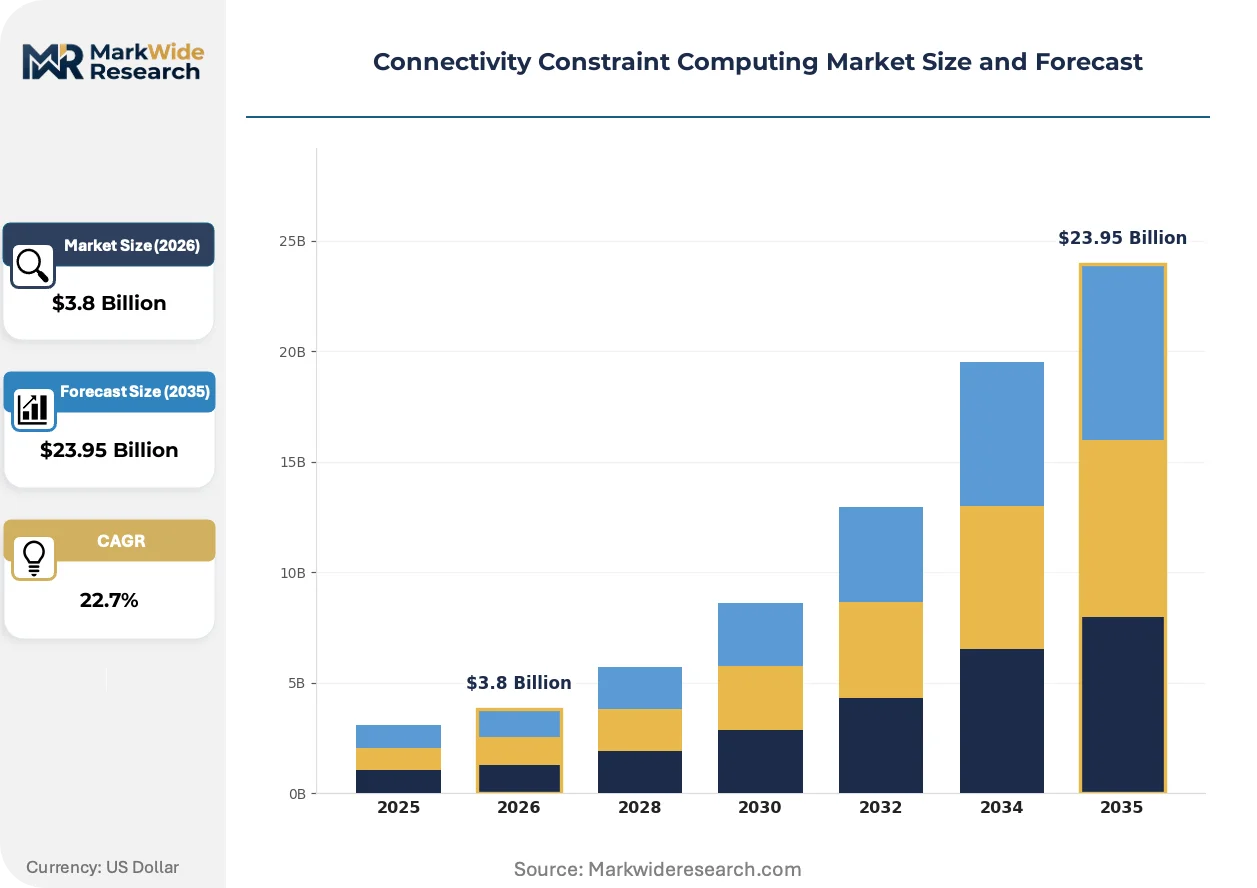
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Edge Computing, Cloud Computing, Quantum Computing, Fog Computing Use Case: Smart Cities, Industrial Automation, Autonomous Vehicles, Healthcare Monitoring End User: Telecommunications, Transportation, Healthcare, Energy Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | IBM, Microsoft, Oracle, SAP, Google, Amazon, Intel, Salesforce, NVIDIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connectivity Constraint Computing Market Emerging Trajectories
Distributed optimization architectures are fragmenting traditional cloud-centric deployment models as latency-critical applications migrate toward heterogeneous edge-fog-cloud hierarchies with specialized hardware acceleration.
Constraint logic programming at the network edge is decentralizing vehicular path planning computation away from centralized data centers. Autonomous vehicle manufacturers in Germany's Stuttgart corridor are deploying GPU-accelerated inference nodes within 50 kilometers of test fleets. This topology is decentralizing safety-critical decision authority while compressing redundant bandwidth consumption across 5G vehicle-to-infrastructure links.
The EU AI Act imposes conformity assessment requirements on autonomous decision systems with direct bearing on European automotive and healthcare deployments. Manufacturers must maintain auditable constraint satisfaction traces for regulatory inspection. German automotive suppliers and Dutch medical device developers are restructuring validation pipelines to embed real-time logging without breaching sub-100 millisecond response thresholds.
Buyers in industrial automation are consolidating vendor relationships around platform-agnostic constraint solver APIs that abstract hardware-specific implementations. Systems integrators in smart manufacturing are displacing point-solution procurement with multi-year framework agreements spanning edge, fog, and cloud orchestration. This pattern is most visible in Bavarian automotive supplier networks where procurement teams prioritize interoperability certification over single-vendor performance benchmarks.
Connectivity Constraint Computing Market Segmentation
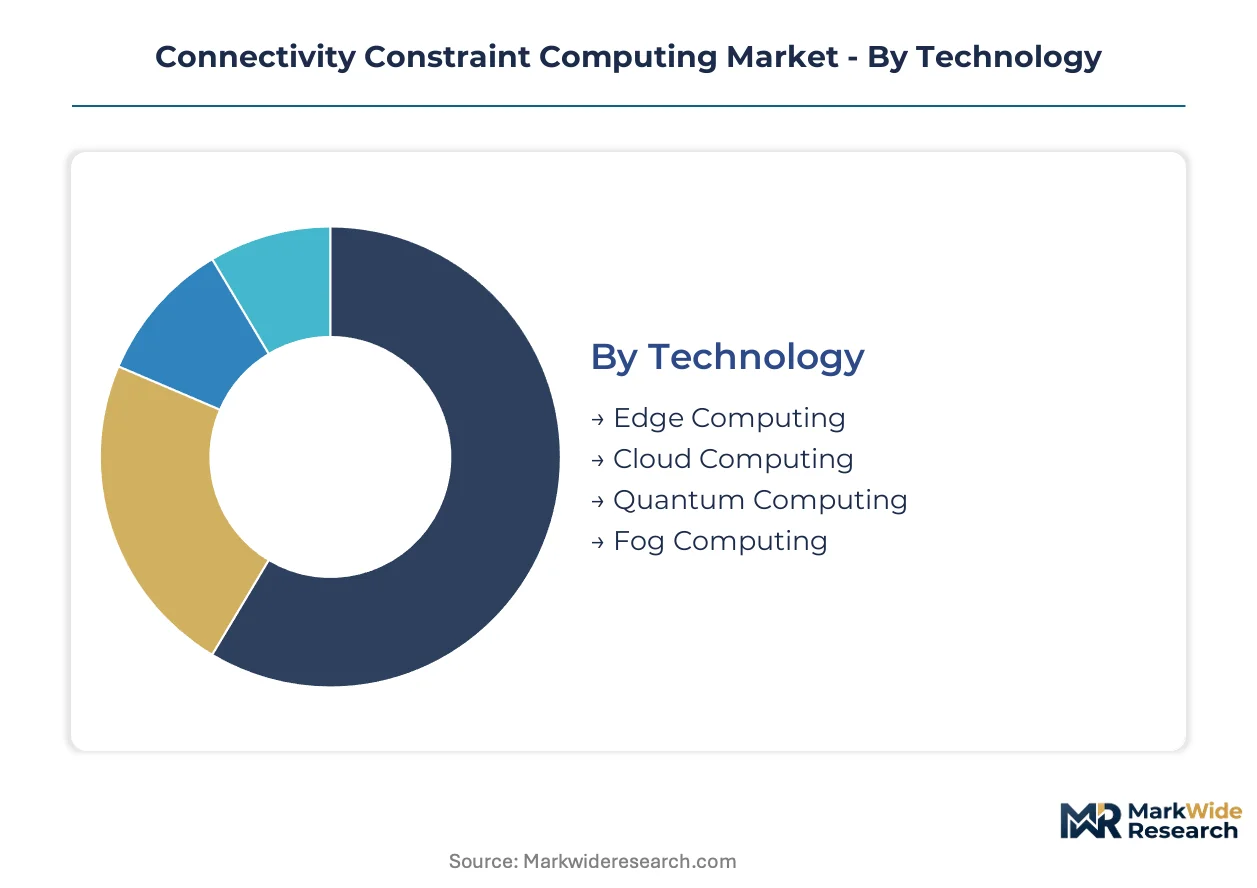
Segmentation in connectivity constraint computing reveals how deployment topology, computational paradigm, and end-use criticality interact to determine hardware specifications and integration complexity. Buyers select technology layers based on latency tolerance, regulatory exposure, and legacy infrastructure constraints.
Technology:
Integration depth varies sharply: Edge Computing and Quantum Computing demand tight coupling with physical infrastructure, while Cloud and Fog layers operate as more loosely federated resources.
- Edge Computing:Distributed nodes execute constraint logic within 50 kilometers of data sources, processing vehicular path planning and industrial control loops under sub-100 millisecond thresholds. Stuttgart automotive suppliers deploy GPU-accelerated inference clusters directly adjacent to test fleets, hardening latency compliance for EU AI Act conformity assessments.
- Quantum Computing:Hybrid classical-quantum architectures address combinatorial optimization problems exceeding classical solver capacity for bandwidth-constrained logistics networks. Hardware maturity in quantum annealing is accelerating procurement for smart manufacturing environments where fog-layer orchestration cannot resolve scheduling complexity.
- Cloud Computing:Centralized orchestration platforms retain deepest margin pools through hybrid software licensing models.
- Fog Computing:Intermediate aggregation layer in mature smart city installations, now requiring middleware refresh cycles.
Volume placements concentrate in Edge Computing; the faster expansion belongs to Quantum Computing.
Use Case:
Application criticality determines validation rigor, with autonomous systems and medical devices facing the most stringent certification timelines.
- Autonomous Vehicles:Safety-critical path planning systems require auditable constraint satisfaction traces under EU AI Act mandates without breaching real-time response thresholds. German OEMs in Munich and Stuttgart corridors are restructuring validation pipelines to embed logging infrastructure within edge-validated solver architectures.
- Healthcare Monitoring:Connected medical devices integrating real-time constraint solvers face 18-36 month FDA software validation cycles. Dutch developers are compressing deployment timelines by pre-certifying edge-based decision modules against ISO 27001 and IEC 62443 frameworks.
- Smart Cities:Barcelona and Amsterdam installations drive middleware upgrade demand for legacy sensor network integration.
- Industrial Automation:Bavarian supplier networks prioritize platform-agnostic constraint solver APIs over single-vendor performance benchmarks.
Revenue concentration sits with Industrial Automation; Healthcare Monitoring climbs the fastest as FDA validation bottlenecks ease.
End User:
Customer type shapes procurement scale and contract structure, from framework agreements to outcome-contingent pricing.
- Transportation:Autonomous vehicle manufacturers consolidate multi-year solver procurement around interoperability certification, with Germany's automotive corridor anchoring concentrated demand.
- Energy:German and French grid infrastructure operators mandate IEC 62443 cross-border data integrity certification for constraint networks spanning generation and distribution systems.
- Healthcare:Medical device developers face divergent regional AI safety certifications requiring multi-jurisdictional compliance architecture.
- Telecommunications:5G vehicle-to-infrastructure link operators consume bandwidth-optimized constraint optimization for network slice management.
Contract value peaks in Transportation; Energy sector cybersecurity integration offers the steepest expansion trajectory.
Deployment:
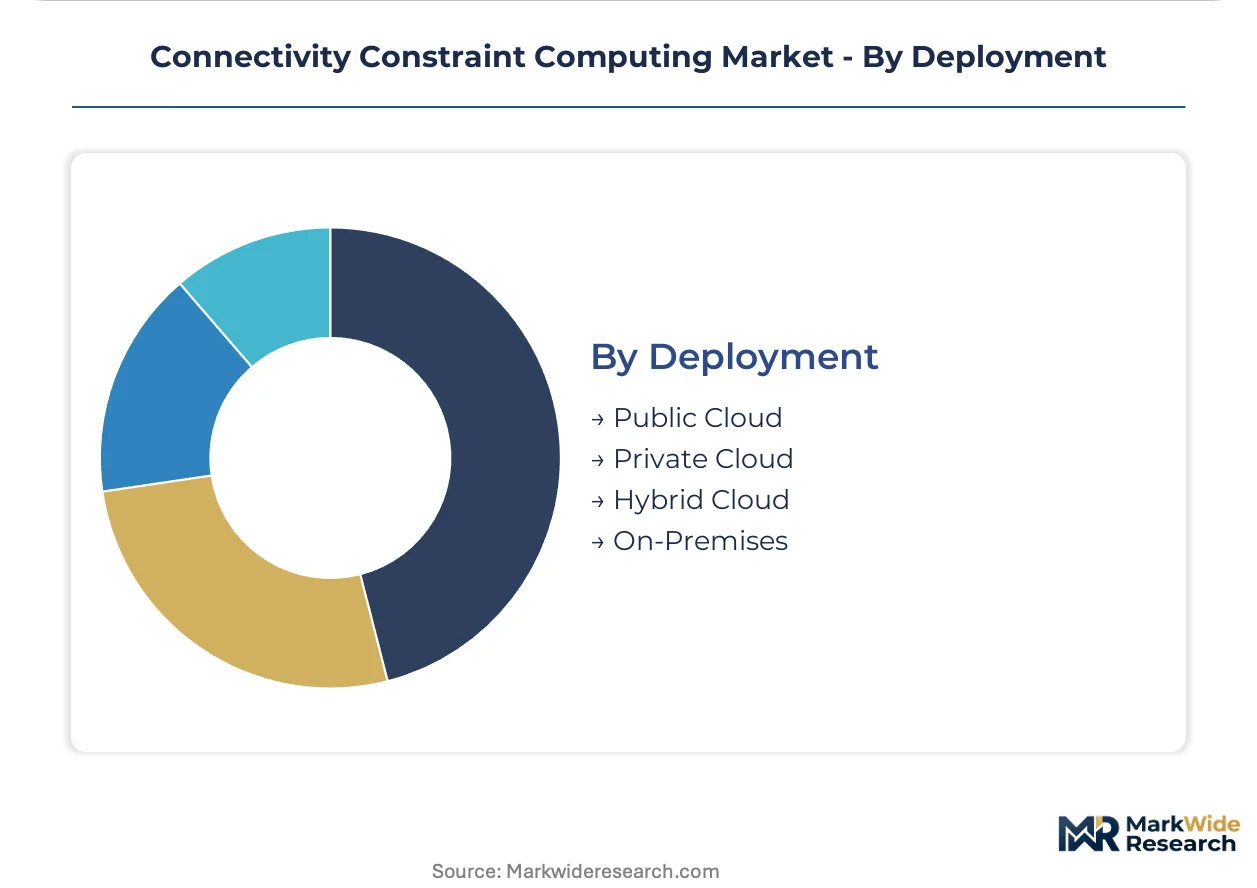
Infrastructure ownership models determine capital intensity and operational control, with hybrid configurations gaining preference for latency-critical workloads.
- Hybrid Cloud:Combines public orchestration with private edge nodes to satisfy disconnected operational settings in remote industrial facilities. Azure Edge Zones and comparable platforms enable performance-based licensing for intermittently connected environments.
- On-Premises:Captive infrastructure retains full operational technology cybersecurity governance for energy sector and defense-adjacent deployments.
- Private Cloud:Single-tenant constraint solver farms serve automotive R&D facilities with proprietary path planning algorithms.
- Public Cloud:Shared infrastructure supports non-latency-sensitive optimization workloads in smart city analytics.
Deployment share shifts toward Hybrid Cloud; On-Premises retains premium pricing for certified-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart-Munich automotive corridor operates as a special economic zone for edge computing R&D, concentrating constraint solver procurement from autonomous vehicle manufacturers seeking EU AI Act conformity.
United States
FDA software validation requirements for connected medical devices drive demand for real-time distributed systems in healthcare monitoring. NHTSA guidelines for autonomous vehicle safety systems accelerate edge-based constraint solver deployment. Silicon Valley and Detroit anchor concentrated R&D facilities for vehicular path planning optimization.
Germany
EU AI Act conformity assessments mandate auditable constraint logic in safety-critical automotive systems. KBA type-approval processes for autonomous driving functions compress validation timelines for edge-validated solver architectures. Stuttgart and Munich host OEM facilities deploying sub-100 millisecond optimization clusters adjacent to test fleets.
China
MIIT standards for intelligent connected vehicles establish domestic certification requirements for real-time decision systems. Dual carbon goals accelerate quantum annealing adoption for bandwidth-constrained logistics optimization. Yangtze River Delta manufacturing hubs integrate hybrid classical-quantum approaches into smart factory orchestration.
Japan
METI industrial digitization programs subsidize edge computing infrastructure for precision manufacturing. JIS standards for autonomous systems guide constraint solver integration in robotics and vehicular applications. Kansai and Chubu regions concentrate supplier networks for industrial automation middleware.
United Kingdom
UK Research and Innovation funding streams support quantum-classical hybrid computing for logistics optimization. MHRA software as medical device regulations constrain real-time solver deployment in healthcare monitoring. London and Cambridge clusters focus on fintech applications of distributed constraint programming.
Connectivity Constraint Computing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platform providers commanding premium pricing in hybrid orchestration while semiconductor fabricators capture margin from accelerated inference hardware. The vendor base concentrates around three strategic archetypes: hyperscale cloud operators extending edge zones, GPU-accelerated hardware specialists, and enterprise software incumbents with IoT platform integration. Dominant competitive moves include strategic partnerships between automotive OEMs and solver developers, plus geographic expansion through localized edge node deployment.
Within the hyperscale tier, Microsoft and Amazon exemplify platform-agnostic orchestration strategies, while NVIDIA occupies a position as the hardware acceleration anchor for vehicular path planning applications. IBM represents the enterprise software archetype, leveraging Watson IoT integration to secure multi-year framework agreements in smart manufacturing environments.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Oracle |
| SAP |
| Amazon |
| Intel |
| Salesforce |
| NVIDIA |
| Others |
Supply Flow & Price Mechanics
Constraint logic programming expertise concentrated in Germany's Stuttgart-Munich automotive corridor drives labor-cost premiums that widen pricing-tier spreads between EU-validated and non-certified solver implementations.
Pricing Analysis
Short-lead-time deployments command premium pricing as automotive OEMs compress EU AI Act validation timelines for edge-validated solver architectures. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Pricing pressure stems from GPU supply concentration in East Asian foundry networks. Healthcare monitoring buyers exhibit highest price sensitivity due to extended FDA validation cycles, while energy sector procurement shows lowest sensitivity given IEC 62443 cybersecurity mandates.
Supply Chain Analysis
Dual-sourcing requirements now govern automotive OEM procurement as buyers mandate multi-supplier qualification for GPU-accelerated inference hardware. Semiconductor fabrication concentrates in Taiwan, South Korea, and China. Raw material dependencies span advanced node silicon wafers, high-bandwidth memory modules, and specialized packaging substrates. Single-source vulnerability in East Asian foundry networks represents the dominant structural risk. Distribution runs through Tier 1 systems integrators with embedded software certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Connectivity Constraint Computing Market operates as a cost-of-compliance story where EU AI Act conformity assessments erect barrier-to-entry moats favoring pre-certified incumbents with validated edge architectures.
For Market Incumbents: Lock in multi-year framework agreements with Stuttgart and Munich automotive suppliers before validation pipeline standardization commoditizes edge solver procurement. Invest in ISO 27001 and IEC 62443 certification infrastructure to capture energy sector cybersecurity integration demand. Threat: Quantum annealing hardware maturation displaces classical constraint solvers in bandwidth-constrained logistics networks. Lever: Backward integration into GPU-accelerated inference node assembly within 50 kilometers of European test fleets. For New Entrants and Emerging Players: Systems integrators with smart city middleware expertise represent the most accessible channel partner type for penetrating Barcelona and Amsterdam fog computing refresh cycles. Target healthcare monitoring white space where Dutch developers compress FDA validation timelines through pre-certified edge modules. Go-to-market: Outcome-contingent pricing models for disconnected operational settings in remote industrial facilities. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid classical-quantum computing specialists given hardware maturity in quantum annealing. Long-term viability favors platform-agnostic constraint solver API providers over single-vendor performance benchmark players. Acquisition target: Edge-validated solver developers with EU AI Act conformity assessment documentation. Signal to watch: KBA type-approval process acceleration for autonomous driving functions in Germany.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | KBA type-approval processes in Germany compress validation timelines for edge architectures. |
| Hybrid Cloud Platform Integration | Azure Edge Zones enable performance-based licensing for intermittently connected industrial environments. |
| Quantum Annealing Partnership | Hardware maturity accelerates procurement for bandwidth-constrained smart manufacturing logistics. |
| Smart City Middleware Refresh | Barcelona and Amsterdam installations drive constraint optimization integration into legacy sensor networks. |
| IEC 62443 Certification Pathway | German and French grid infrastructure mandates cross-border data integrity for energy sector deployments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with edge computing platform engineers, automotive OEM procurement leads, regulatory affairs specialists at medical device developers, and smart city systems integrators. Secondary sources included EU AI Act conformity assessment documentation, FDA software validation guidance, KBA type-approval records, and hyperscaler edge zone deployment disclosures. Bottom-up solver deployment tallies triangulated against top-down infrastructure investment estimates.
Data-stream reconciliation across technology deployment topology, use case criticality, and end-user procurement scale enabled segmentation-level modeling across the projection horizon. Segmentation dimensions spanned edge-fog-cloud-quantum computational paradigms, autonomous vehicle-healthcare-industrial automation application verticals, and hybrid-on-premises-public cloud deployment models. CAGRs derived from fitted growth curves against hardware maturity timelines and regulatory compliance deadline clustering. Industry-specific inputs included GPU supply lead times and EU AI Act implementation phase transitions.
Caveats apply where semiconductor fabrication capacity constraints or EU AI Act enforcement variance could materially shift the outlook. Deviation in quantum annealing hardware commercialization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Cognitive Computing Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations Platform Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market