
 Churg Strauss Syndrome Market | 2026-2036
Churg Strauss Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Churg Strauss Syndrome Market Outlook
ISO 14155 clinical investigation standards for medical products is reorganizing competitive entry into the Churg Strauss syndrome therapeutic space, favoring sponsors with established quality management systems. GlaxoSmithKline leverages its respiratory-immunology crossover portfolio to anchor development programs. Novartis AG sustains biologics manufacturing scale that competes across autoimmune indications. F. Hoffmann-La Roche Ltd differentiates through diagnostic-therapeutic integration in eosinophilic disorders.
Churg Strauss syndrome, also termed eosinophilic granulomatosis with polyangiitis, constitutes a rare systemic necrotizing vasculitis characterized by asthma, eosinophilia, and extravascular granulomas, with diagnosis requiring biopsy-confirmed eosinophilic tissue infiltration plus positive antineutrophil cytoplasmic antibody serology in approximately forty percent of cases. Its primary clinical purpose centers on controlling eosinophilic inflammation, preventing irreversible organ damage, and maintaining remission through immunomodulatory intervention. Biologics command the highest margin pools among product types, reflecting precision-targeted mechanisms and orphan pricing structures. Injectable delivery modes lead in hospital settings, while oral corticosteroids sustain volume share in maintenance protocols across specialty clinics.
FDA orphan drug incentives and EMA's priority medicines scheme shape development economics, compressing regulatory timelines and extending market exclusivity for qualified sponsors. The EU MDR and FDA Good Manufacturing Practice standards enforce batch consistency and pharmacovigilance rigor that determine manufacturing qualification. Stakeholders must monitor evolving payer evidence requirements for biologic therapies and position clinical trial investments against shifting competitive entry timelines.
Market Dynamics
FDA orphan drug incentives are compressing development timelines for eosinophilic granulomatosis with polyangiitis therapeutics, while specialty clinics concentrate demand in tertiary care corridors. This regulatory pull reshapes competitive entry economics across biologics and small-molecule portfolios.
Growth Catalysts
- EMA Priority Medicines Scheme:The European Medicines Agency's PRIME designation accelerates assessment timelines for severe autoimmune indications, compressing sponsor investment horizons.
- Tertiary Care Clustering:United States academic medical centers concentrate diagnostic expertise and clinical trial access, pulling biopharma investment toward established investigator networks.
- Eosinophil-Targeted Biologics:Precision mechanisms against interleukin-5 and its receptor expand addressable patient populations beyond corticosteroid-dependent cohorts.
Market Restraints
- Plasma-Derived Input Volatility:Immunoglobulin manufacturing depends on fractionation facility throughput and donor pool stability, creating batch-to-batch supply uncertainty.
- Biopsy-Dependent Diagnosis:Tissue confirmation requirements delay treatment initiation and restrict addressable populations to specialist-accessible geographies.
- Corticosteroid Substitution:Low-cost oral prednisone protocols retain volume share in maintenance phases, pressuring biologic pricing power.
Strategic Opportunities
- Japan's Rare Disease Framework:PMDA's Sakigake designation offers expedited review for eosinophilic vasculitis candidates with unmet need positioning.
- Diagnostic-Therapeutic Bundling:ANCA serology and eosinophil count monitoring integrated with biologic delivery creates sticky patient relationships.
- Subcutaneous Formulation Migration:Self-administration shifts site-of-care from infusion centers to home settings, expanding addressable geography.
Industry Challenges
- Vasculitis Specialist Scarcity:Fellowship-trained clinicians cluster in academic hubs, creating patient access bottlenecks outside major metropolitan corridors.
- Pharmacovigilance Infrastructure:Long-term safety monitoring for biologics in rare indications demands dedicated registries that strain sponsor resource allocation.
- Legacy Corticosteroid Protocols:Established tapering regimens in community rheumatology resist rapid substitution despite biologic efficacy advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Churg Strauss Syndrome Market |
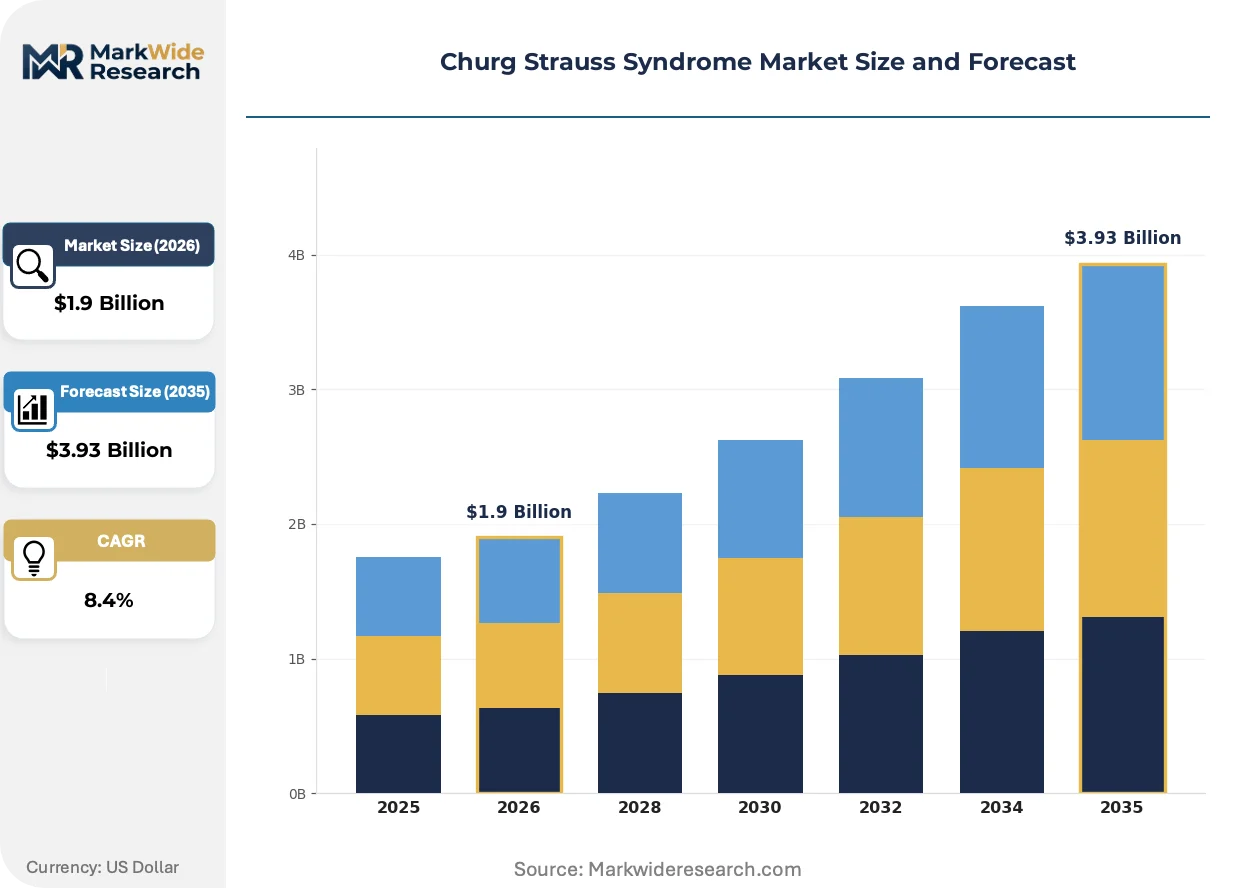
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Immunosuppressants, Corticosteroids, Antioxidants Therapy Area: Immune Disorders, Respiratory Conditions, Vascular Diseases, Autoimmune Disorders Delivery Mode: Oral, Injectable, Inhalation, Infusion End User: Hospitals, Specialty Clinics, Home Healthcare, Research Laboratories |
| Companies Covered | GlaxoSmithKline, Novartis AG, AstraZeneca, F. Hoffmann-La Roche Ltd, Sanofi, Pfizer Inc., Bristol-Myers Squibb Company, Merck & Co. Inc., Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Churg Strauss Syndrome Market Strategic Shifts
Precision immunology platforms are fragmenting the eosinophilic granulomatosis with polyangiitis treatment algorithm, displacing empirical corticosteroid dominance with mechanism-driven selection. This shift reconfigures development priorities and commercial architecture simultaneously.
Anti-interleukin-5 receptor antagonists are fragmenting first-line biologic positioning in severe eosinophilic asthma overlap populations. Specialty pulmonology clinics adopt these agents ahead of formal vasculitis indications, compressing the window for competitor mechanism differentiation. The technology is fragmenting prescriber loyalty across respiratory-immunology boundaries.
EU MDR's strengthened clinical evidence requirements for high-risk devices are extending qualification timelines for companion diagnostic platforms. Manufacturers must demonstrate analytical validity against biopsy gold standards, increasing development burn rates. European reference laboratories are consolidating validation partnerships to spread compliance costs.
Hospital purchasing coalitions are consolidating biologic procurement authority, displacing individual physician preference with formulary committee control. United States integrated delivery networks now centralize eosinophil-targeted therapy selection through pharmacy and therapeutics committees. This concentration shifts commercial investment toward health economics evidence and real-world data generation.
Churg Strauss Syndrome Market Segmentation
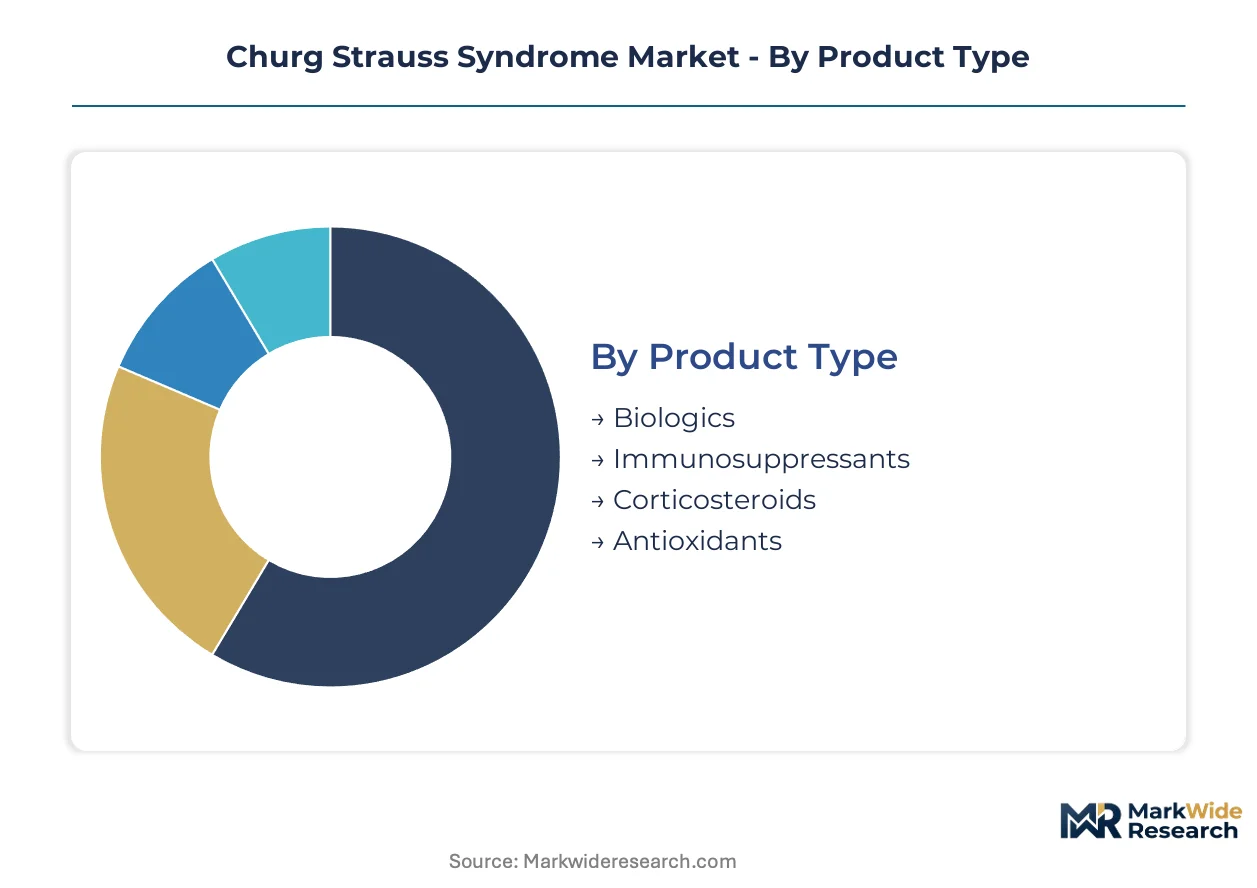
Churg Strauss syndrome treatment selection hinges on disease severity, organ involvement patterns, and patient access to specialized care. Segmentation reveals how corticosteroid substitution pressures and biologic premium positioning reshape prescribing economics across delivery modes and care settings.
Product Type:
Corticosteroids face the most intense substitution pressure from mechanism-targeted alternatives, yet retain volume dominance through protocol familiarity and access advantages.
- Biologics:Precision-targeted monoclonal antibodies against interleukin-5 and its receptor command premium positioning in corticosteroid-refractory eosinophilic vasculitis. Demand concentrates in United States academic medical centers with infusion infrastructure and prior authorization expertise.
- Immunosuppressants:Azathioprine, mycophenolate mofetil, and cyclophosphamide serve as steroid-sparing bridge therapies in maintenance protocols. European reference laboratories favor these agents where biologic reimbursement remains restricted.
- Corticosteroids:Oral prednisone protocols sustain the largest patient volumes through community rheumatology access and established tapering regimens despite long-term toxicity burdens.
- Antioxidants:Adjunctive therapies targeting oxidative stress in eosinophilic tissue damage occupy niche positioning within integrative medicine networks.
Corticosteroids anchor the volume base while biologics gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates acute intervention from chronic maintenance, with vascular involvement commanding the highest resource intensity per patient.
- Immune Disorders:Systemic immunomodulation targeting eosinophil-driven inflammation constitutes the core therapeutic objective across all disease phases. United States tertiary care corridors concentrate demand for advanced biologic intervention.
- Respiratory Conditions:Severe asthma overlap populations in specialty pulmonology clinics drive early biologic adoption ahead of formal vasculitis indications.
- Vascular Diseases:Necrotizing vasculitis with organ-threatening involvement requires intensive immunosuppression and carries the highest per-patient treatment costs.
- Autoimmune Disorders:ANCA-positive subsets access rituximab protocols through rheumatology-dermatology crossover networks.
Respiratory overlap indications expand the addressable patient pool while vascular involvement segments concentrate the highest-margin therapeutic investment.
Delivery Mode:
Patient autonomy preferences and site-of-care economics drive migration from facility-based administration toward self-managed alternatives.
- Injectable:Subcutaneous biologics enable home administration and reduce infusion center dependency. Japan's Sakigake-designated candidates prioritize this modality for patient convenience differentiation.
- Oral:Corticosteroid and immunosuppressant maintenance protocols sustain the largest prescription volumes through community pharmacy distribution.
- Inhalation:Respiratory symptom management in asthma-predominant phenotypes leverages existing pulmonology infrastructure.
- Infusion:Hospital-based administration of cyclophosphamide and biologic loading doses concentrates in academic medical centers with vasculitis specialist availability.
Oral delivery anchors the volume base while injectable formulations gain share at the steepest rate.
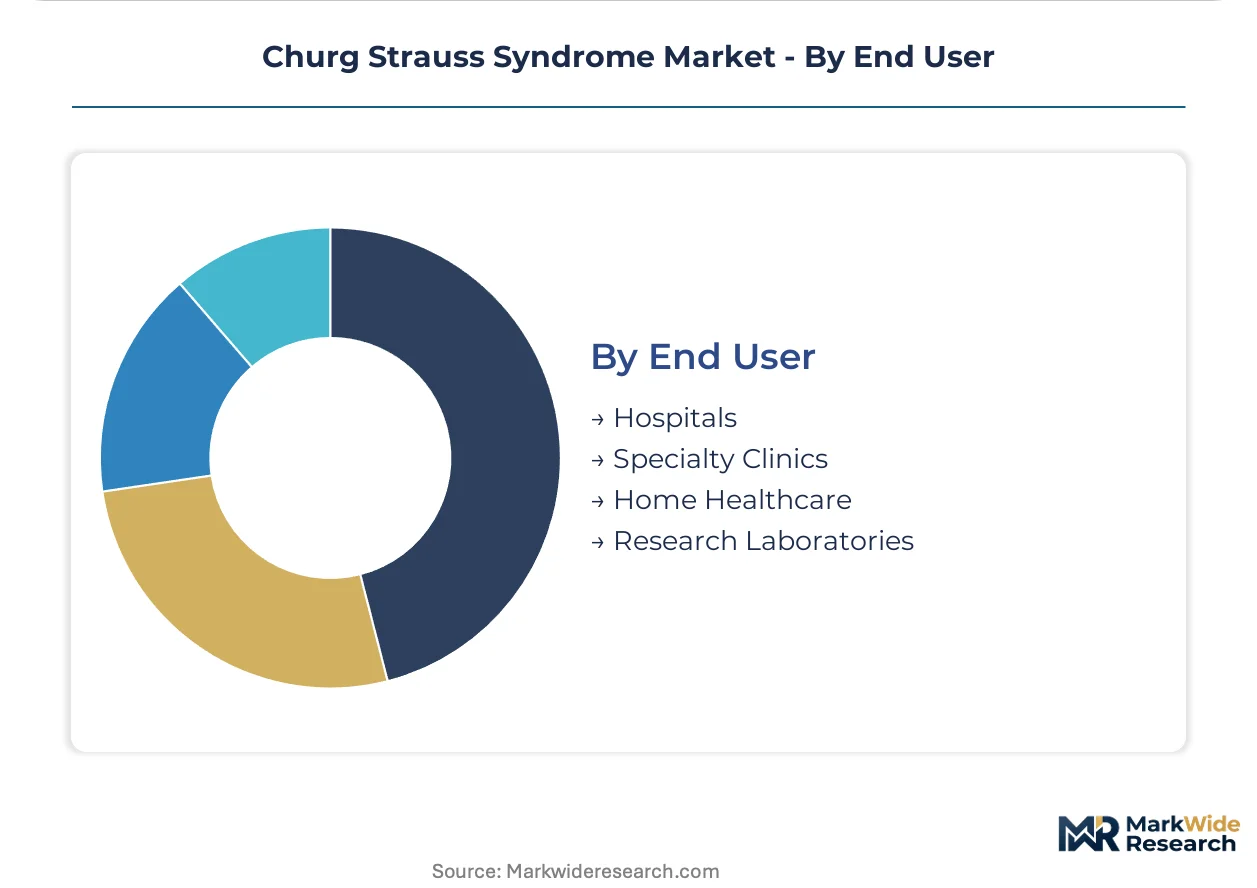
End User:
Customer type stratification reflects diagnostic complexity requirements and therapy intensity, with specialist concentration determining biologic access patterns.
- Specialty Clinics:Fellowship-trained vasculitis centers concentrate diagnostic expertise and clinical trial access for biologic-eligible patients. United States metropolitan corridors sustain the densest specialist networks.
- Hospitals:Acute organ involvement requiring intensive immunosuppression and monitoring pulls high-resource patients into inpatient settings.
- Home Healthcare:Subcutaneous biologic self-administration and remote monitoring expand geographic access beyond specialist hub locations.
- Research Laboratories:ANCA serology and eosinophil count validation supports diagnostic-therapeutic integration in reference laboratory networks.
Hospitals anchor the volume base while specialty clinics gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives pull development investment toward the United States, while EMA's PRIME designation and Japan's Sakigake framework create parallel regulatory gravity across three distinct national jurisdictions. Tertiary care clustering and diagnostic infrastructure density determine where biologic adoption concentrates.
United States
Academic medical centers in Boston, New York, and Philadelphia concentrate vasculitis fellowship programs and clinical trial networks. FDA's orphan drug designation pathway compresses sponsor timelines and extends market exclusivity for qualified candidates. The Northeast Corridor sustains the densest specialist referral networks for eosinophilic granulomatosis with polyangiitis diagnosis.
Germany
Reference laboratories in Berlin and Heidelberg anchor EU-wide ANCA serology validation and eosinophil count standardization. EU MDR's strengthened clinical evidence requirements extend qualification timelines for companion diagnostic platforms. The Baden-Württemberg cluster houses centralized biologics manufacturing facilities serving continental distribution.
Japan
PMDA's Sakigake designation offers expedited review for eosinophilic vasculitis candidates with unmet need positioning. Subcutaneous formulation development prioritizes patient convenience differentiation in Tokyo and Osaka metropolitan corridors. The Kanto region concentrates respiratory-immunology crossover expertise in specialty pulmonology clinics.
United Kingdom
NHS England's specialized commissioning frameworks concentrate biologic access through designated vasculitis centers in London and Manchester. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for rare disease therapeutics. The Oxford-Cambridge-London triangle sustains investigator-initiated trial infrastructure.
Switzerland
Swissmedic's streamlined orphan drug procedures attract sponsor headquarters and clinical operations to Basel and Zurich. The country's reference laboratory networks support diagnostic-therapeutic integration in eosinophilic disorders. Geneva-based immunology research institutes collaborate on mechanistic biomarker development.
Churg Strauss Syndrome Market Competitive Environment
Listed leaders compete with private specialists across respiratory-immunology crossover portfolios, creating a tiered structure where scale-driven pharmaceutical conglomerates anchor premium biologic positioning. The competitive field fragments across three strategic archetypes: respiratory-immunology integrators, biologics manufacturing specialists, and diagnostic-therapeutic bundlers. Dominant competitive moves include portfolio diversification into eosinophil-targeted mechanisms and strategic partnerships with reference laboratory networks for diagnostic co-development.
Within the respiratory-immunology integrator tier, GlaxoSmithKline and AstraZeneca exemplify archetypes leveraging established asthma franchise infrastructure to anchor vasculitis expansion. Novartis AG occupies a position representing biologics manufacturing scale that competes across autoimmune indications. F. Hoffmann-La Roche Ltd sits within the diagnostic-therapeutic bundler archetype, with its positioning in eosinophilic disorder integration reflecting a broader pattern of laboratory-clinical convergence among Swiss-origin conglomerates.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Novartis AG |
| AstraZeneca |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Merck & Co. Inc. |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Plasma-derived immunoglobulin substitution for synthetic biologics simultaneously reshapes supply geography toward fractionation hubs in the United States and Germany while compressing pricing power in maintenance-phase protocols. Corticosteroid retention in community rheumatology practices anchors volume tiers at lower price points, forcing biologic sponsors to justify premium positioning through outcome differentiation.
Pricing Analysis
Orphan drug designation tier creates the primary spread between corticosteroid-dependent maintenance and precision biologic intervention. Three-tier pricing structure separates FDA-designated orphan therapies from standard immunosuppressants and generic prednisone protocols. Cost compression in the oral corticosteroid tier intensifies because of established tapering regimen familiarity among community prescribers. Community rheumatology practices exhibit the highest price sensitivity, while academic medical centers with prior authorization infrastructure demonstrate greater willingness to absorb biologic premiums.
Supply Chain Analysis
Plasma collection network density in the United States, Germany, and Austria underwrites immunoglobulin manufacturing capacity for eosinophilic vasculitis indications. Active pharmaceutical ingredient production draws from Swiss biologics facilities, Irish fill-finish operations, and Singaporean sterile manufacturing sites. Single-source vulnerability concentrates in plasma fractionation where donor pool fluctuations create batch-to-batch variability. Distribution runs through hospital purchasing coalitions and specialty pharmacy networks that centralize biologic procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
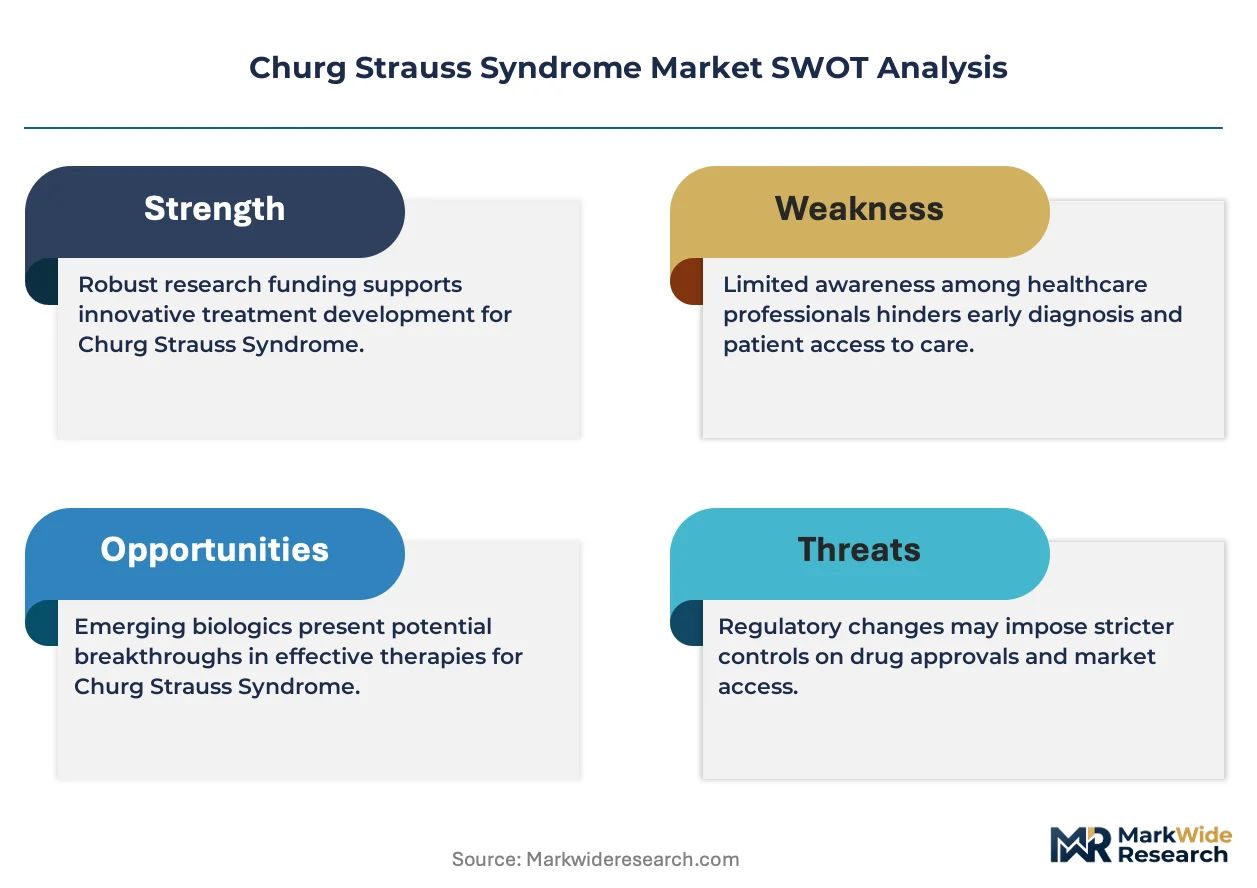
The Churg Strauss syndrome market operates as a defensive-moat story where FDA orphan drug exclusivity creates regulatory entrenchment that extends market protection for qualified sponsors. Switching costs between mechanism classes limit rapid therapeutic substitution despite efficacy advantages.
For Market Incumbents: Secure diagnostic-therapeutic integration partnerships with reference laboratory networks to lock in patient identification upstream of prescribing decisions. Deepen vertical control over eosinophil count validation infrastructure to preempt competitor mechanism differentiation. Corticosteroid substitution pressure from interleukin-5 antagonists threatens maintenance-phase revenue; counter through real-world evidence generation demonstrating organ damage prevention. For New Entrants and Emerging Players: Lead with subcutaneous formulation development targeting Japan's Sakigake pathway and home healthcare settings outside metropolitan specialist corridors. The most penetrable white space sits in community pulmonology clinics managing severe asthma overlap populations ahead of formal vasculitis diagnosis. Position through diagnostic co-development with ANCA serology platforms to capture patients at biopsy stage. For Investors and Strategic Acquirers: Secondary-cycle assets sit with respiratory-immunology crossover specialists holding orphan-designated biologics in Phase II development. Long-term viability hinges on demonstrating steroid-sparing capacity in organ-threatening vascular involvement subsets. Watch FDA breakthrough therapy designation grants to eosinophil-targeted mechanisms as the inflection signal for competitive entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA exclusivity extension compresses competitor entry timelines for qualified sponsors. |
| Diagnostic-Therapeutic Bundling | ANCA serology integration with biologic delivery creates sticky patient relationships in specialty clinics. |
| Subcutaneous Formulation Migration | Self-administration shifts site-of-care from infusion centers to home settings in Japan and United States. |
| Reference Laboratory Partnership | EU MDR-compliant validation spreads compliance costs across European diagnostic networks. |
| Real-World Evidence Generation | Long-term safety registries support payer negotiations for biologic maintenance protocols. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the Churg Strauss syndrome therapeutic landscape. Primary interviews captured perspectives from vasculitis fellowship directors, specialty pharmacy procurement managers, payer access specialists, and regulatory affairs leads at biologics sponsors. Secondary validation drew from FDA orphan drug designations, EMA PRIME submissions, ClinicalTrials.gov entries, and hospital formulary databases. Bottom-up patient population estimates triangulated against top-down biologic revenue disclosures.
Across the analysis window, the forecasting framework modeled treatment line progression, delivery mode migration, and regional regulatory clustering. Segmentation dimensions included product type, therapy area intensity, administration route, and end-user setting. CAGRs were derived from mechanism adoption curves and corticosteroid substitution elasticities. Forecast inputs incorporated orphan drug exclusivity timelines, plasma supply volatility indices, and specialist workforce density by metropolitan corridor.
The analysis sits within stated boundaries; outcomes outside maintained FDA orphan incentives and stable plasma collection economics would require recalibration. Forecasts reflect documented assumptions regarding biologic reimbursement persistence and diagnostic infrastructure expansion. Practitioners should keep alternative scenarios live as payer evidence requirements and corticosteroid tapering protocol evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market