
 Leigh Syndrome Treatment Market | 2026-2036
Leigh Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Leigh Syndrome Treatment Market Insights
The FDA's Rare Pediatric Disease designation is hardening the commercial pathway for mitochondrial therapeutics. Abliva AB leverages its KL1333 program to target NAD+ modulation in Leigh syndrome patients. PTC Therapeutics anchors its position through sustained investment in small-molecule approaches for inherited mitochondrial disorders. Khondrion BV differentiates via its KH176 candidate, which navigates oxidative stress pathways in complex I deficiencies.
Leigh syndrome treatment encompasses therapeutic interventions targeting mitochondrial dysfunction arising from nuclear or mitochondrial DNA mutations, primarily affecting the central nervous system of infants and young children. These interventions aim to restore cellular energy metabolism, with gene therapies employing adeno-associated viral vectors to deliver functional mitochondrial genes directly to affected tissues. Gene therapy segments command premium development investment due to curative potential, while symptomatic treatment remains the clinical standard of care where disease-modifying options remain unavailable. Hospital-based pediatric care dominates the application landscape, though home health care segments are gaining structural relevance as oral and subcutaneous delivery modes reduce inpatient dependency.
The FDA's Orphan Drug Act and EMA's orphan designation framework jointly shape trial design incentives and extended market exclusivity for developers in this space. Reimbursement authorities in Germany and France apply distinct health technology assessment criteria to ultra-rare neurological interventions, creating fragmented market access conditions across major European markets. Stakeholders must monitor evolving gene therapy manufacturing scale-up capabilities and payer willingness to absorb single-administration curative pricing models.
Market Dynamics
The FDA's Rare Pediatric Disease Priority Review Voucher program is restructuring competitive incentives for mitochondrial therapeutic developers, accelerating capital allocation toward single-administration curative modalities that command premium reimbursement positioning.
Growth Catalysts
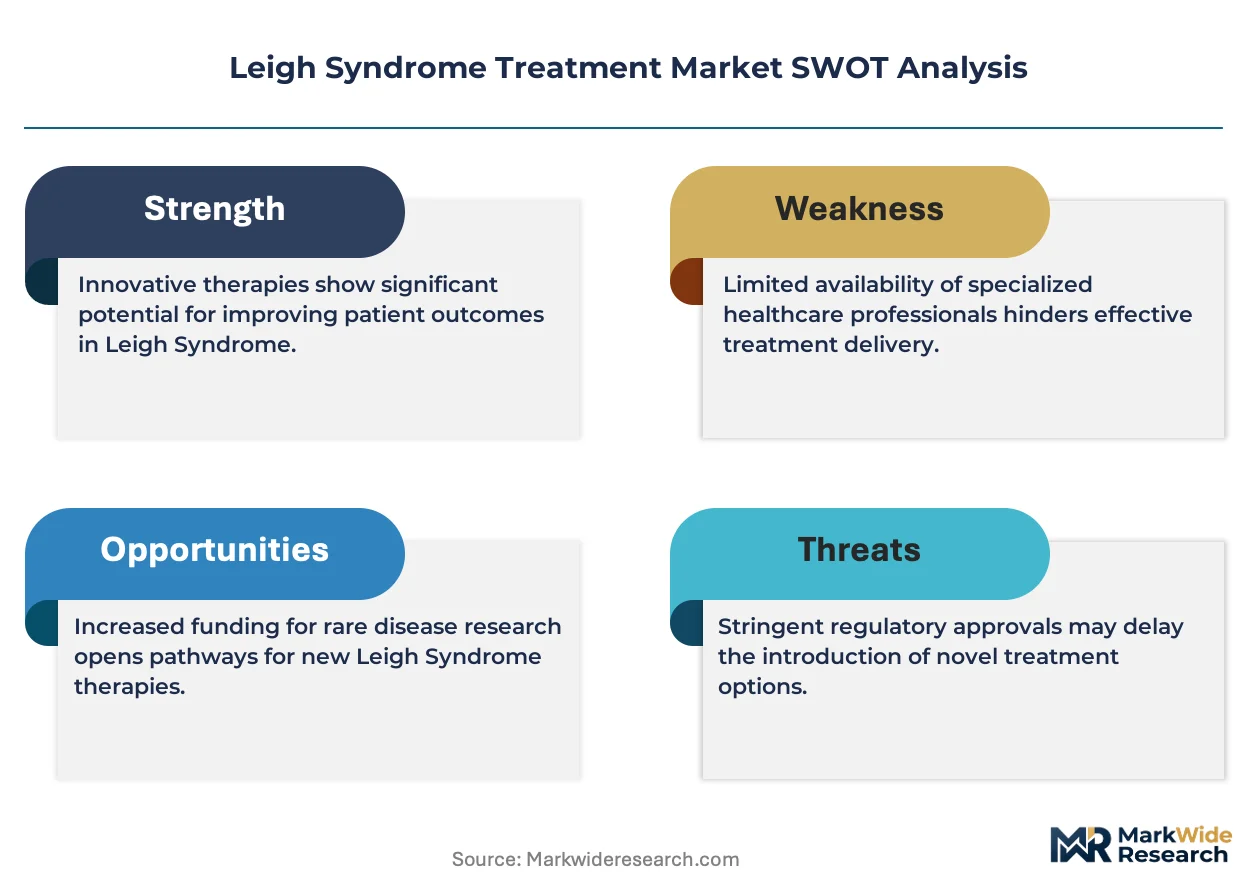
- EMA Orphan Designation Framework:Extended market exclusivity provisions in Europe are pulling late-stage assets toward commercialization readiness, with Germany and France applying distinct health technology assessment criteria that reward first-mover gene therapy entrants.
- Pediatric Academic Medical Center Expansion:Specialized mitochondrial disease clinics clustering around Boston, San Diego, and Houston are generating concentrated patient access infrastructure that streamlines trial recruitment and post-market surveillance.
- Adeno-Associated Viral Vector Manufacturing:Contract development and manufacturing organizations are scaling GMP-compliant production capacity for direct-to-tissue gene delivery, reducing batch-to-batch variability that previously constrained clinical supply.
Market Restraints
- Ultra-Rare Disease Epidemiology:Patient pool fragmentation across heterogeneous nuclear and mitochondrial DNA mutations complicates trial design and statistical powering, extending development timelines beyond typical rare disease benchmarks.
- Single-Administration Curative Pricing Compression:Payer willingness to absorb multi-million-dollar gene therapy costs remains constrained by budget impact thresholds, particularly in European markets with centralized health technology assessment processes.
- Central Nervous System Delivery Barriers:Blood-brain penetration limitations for systemic biologics necessitate invasive administration routes that restrict addressable patient populations and complicate home health care transitions.
Strategic Opportunities
- Home Health Care Channel Development:Oral and subcutaneous delivery formulations are creating infrastructure for outpatient chronic management, reducing inpatient dependency and expanding addressable caregiver support markets.
- NAD+ Modulation Platform Extension:Small-molecule metabolic regulators validated in Leigh syndrome are being repositioned toward broader mitochondrial disease indications with shared complex I deficiency pathophysiology.
- US Rare Pediatric Disease Voucher Monetization:Transferable priority review vouchers awarded upon approval are generating secondary market liquidity that offsets development risk for early-stage mitochondrial therapeutic platforms.
Industry Challenges
- Gene Therapy Manufacturing Scale-Up:GMP-compliant viral vector production capacity remains concentrated among limited contract manufacturers, creating supply bottlenecks that constrain multi-indication program expansion.
- Biomarker-Endpoint Alignment:Regulatory acceptance of surrogate endpoints for central nervous system mitochondrial disorders lags behind peripheral tissue indications, prolonging pivotal trial duration and increasing capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leigh Syndrome Treatment Market |
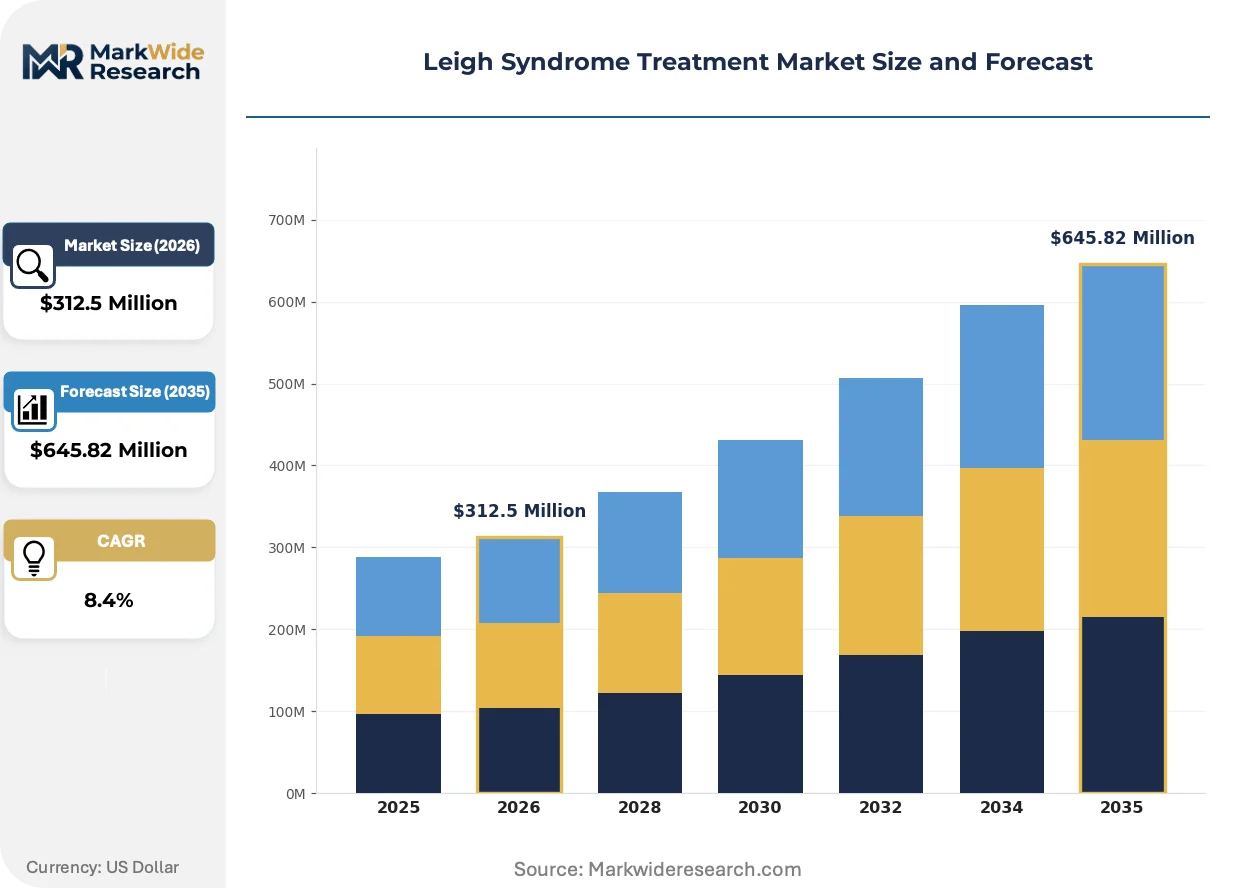
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Symptomatic Treatment, Nutritional Support Application: Pediatric Care, Adult Care, Home Care, Hospital Care Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Rehabilitation Centers, Home Health Care |
| Companies Covered | Abliva AB, PTC Therapeutics, Khondrion BV, Santhera Pharmaceuticals, Stealth BioTherapeutics, Edison Pharmaceuticals, VAKS Pharma, OMEICOS Therapeutics, Taysha Gene Therapies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leigh Syndrome Treatment Market Trends and Innovations
Gene therapy manufacturing scale-up capabilities are intersecting with evolving payer contracting frameworks to reshape commercialization pathways for curative mitochondrial interventions, compressing traditional timelines between regulatory approval and patient access.
Adeno-associated viral vector platforms are expanding into central nervous system mitochondrial disorders through direct intrathecal delivery protocols. Pediatric neurology departments at academic medical centers are adopting these modalities ahead of adult mitochondrial disease programs, driven by the severity of early-onset Leigh syndrome phenotypes. This delivery innovation is compressing the addressable patient timeline toward pre-symptomatic genetic diagnosis windows.
The FDA's Rare Pediatric Disease Priority Review Voucher program is extending market exclusivity incentives beyond orphan drug provisions alone, creating stacked regulatory benefits for mitochondrial therapeutic developers who achieve breakthrough therapy designation. Biotechnology firms are restructuring clinical development timelines to prioritize pediatric indications that qualify for voucher eligibility, even when adult-onset variants present larger commercial pools. Gene therapy segments are responding most aggressively to this incentive stacking.
Caregiver-driven demand for home-based administration is displacing traditional hospital-centric infusion models for chronic metabolic support therapies. Specialty pharmacy distributors are building cold-chain infrastructure for temperature-sensitive biologics that previously required inpatient handling, with the United States leading this channel reconfiguration due to fragmented payer structures that reward site-of-care flexibility. Oral small-molecule programs are capturing structural preference from families managing complex travel logistics for multi-specialty pediatric care.
Leigh Syndrome Treatment Market Segmentation
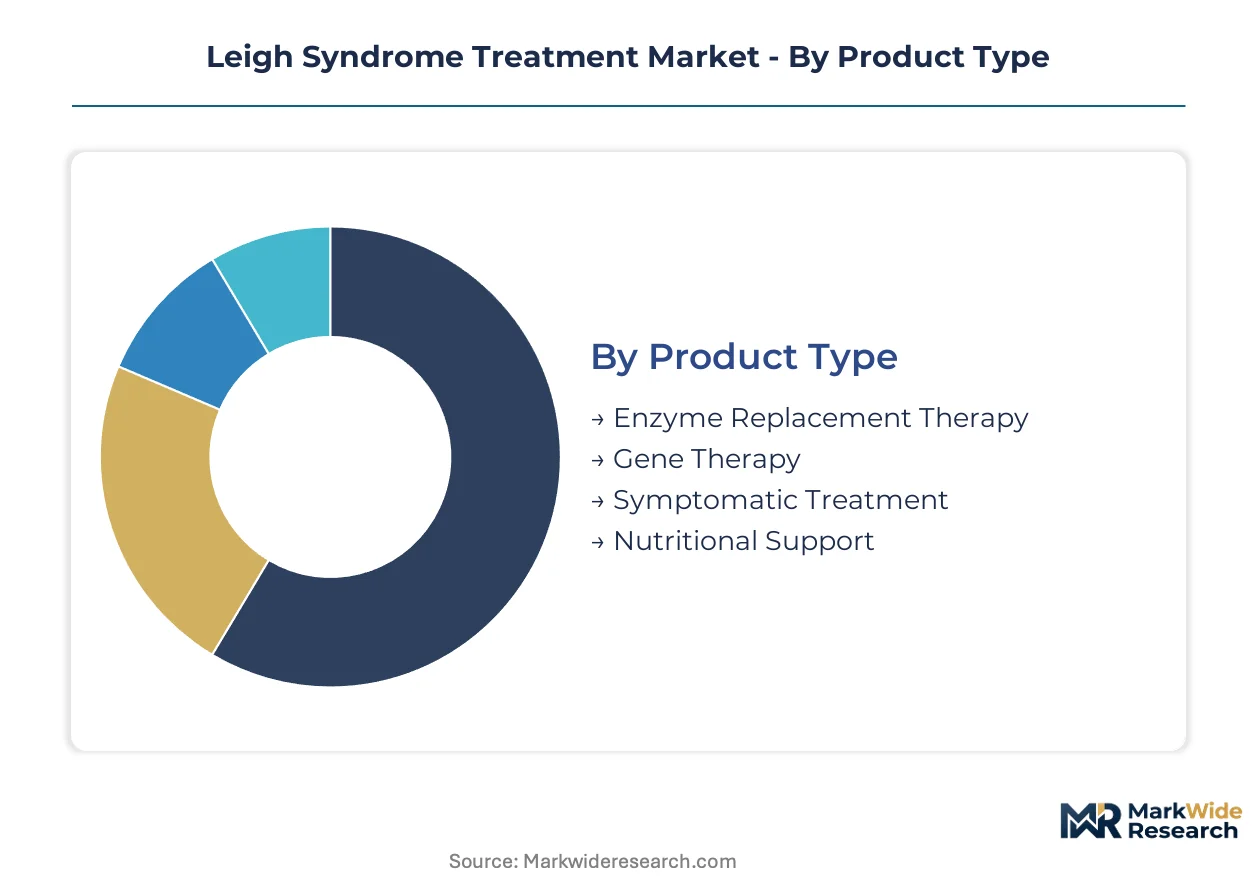
Leigh syndrome treatment segmentation reflects divergent regulatory pathways and reimbursement complexity across curative versus chronic modalities. Each category captures distinct certification burdens from FDA, EMA, and national health technology assessment bodies that shape commercial viability timelines.
Product Type:
FDA breakthrough therapy designation and EMA orphan drug status impose tiered evidentiary requirements across these segments, with gene therapies facing the steepest manufacturing validation hurdles.
- Gene Therapy:Adeno-associated viral vectors deliver functional mitochondrial genes directly to affected tissues, requiring GMP-compliant manufacturing scale-up and extended pharmacovigilance protocols. Demand concentrates at academic medical centers in Boston and San Diego, driven by the FDA's Rare Pediatric Disease Priority Review Voucher program that accelerates capital commitment toward single-administration curative candidates.
- Symptomatic Treatment:Pharmacological management of seizures, movement disorders, and respiratory dysfunction constitutes the current clinical standard where disease-modifying options remain unavailable. Hospital-based pediatric neurology departments in Houston anchor demand, constrained by payer willingness to absorb chronic therapy costs against budget impact thresholds.
- Enzyme Replacement Therapy:Protein-based supplementation targeting specific mitochondrial enzyme deficiencies.
- Nutritional Support:Metabolic cofactor and vitamin supplementation protocols administered through enteral or parenteral routes.
Symptomatic treatment sits at the top of the volume ranking, with gene therapy climbing the fastest.
Application:
Patient age and care setting determine reimbursement coding complexity, with pediatric indications unlocking stacked regulatory incentives unavailable to adult-onset programs.
- Pediatric Care:Early-onset Leigh syndrome phenotypes drive intervention urgency through specialized mitochondrial disease clinics. Academic medical centers in the United States cluster pediatric neurology expertise around pre-symptomatic genetic diagnosis windows, supported by the FDA's Rare Pediatric Disease designation framework.
- Home Care:Oral and subcutaneous delivery formulations reduce inpatient dependency for chronic metabolic support. Caregiver demand in Germany and France is expanding addressable markets through specialty pharmacy cold-chain infrastructure, though centralized health technology assessment processes constrain pricing flexibility.
- Adult Care:Later-onset mitochondrial disorder variants with milder phenotypic progression.
- Hospital Care:Acute intervention settings for respiratory decompensation and metabolic crisis management.
Hospital care retains the highest procedure density, while home care gains share fastest among chronic management segments.
Delivery Mode:
Route of administration shapes manufacturing investment requirements and distribution infrastructure, with invasive CNS delivery commanding premium handling protocols.
- Intravenous:Systemic biologic delivery for enzyme replacement and gene therapy candidates, requiring temperature-controlled logistics and infusion center capacity. Contract development and manufacturing organizations in the United States are scaling GMP-compliant production to reduce batch-to-batch variability that previously constrained clinical supply.
- Oral:Small-molecule metabolic regulators including NAD+ modulation platforms enable outpatient chronic management. Formulation development in France and Germany targets caregiver preference for reduced travel burden to multi-specialty pediatric centers.
- Subcutaneous:Depot formulations and continuous infusion systems for sustained drug exposure.
- Topical:Localized delivery for dermatological manifestations of mitochondrial dysfunction.
Intravenous administration dominates current revenue, with oral formulations expanding most quickly through specialty pharmacy channel development.
End User:
Site-of-care economics and staffing specialization create divergent margin profiles across institutional settings versus distributed care models.
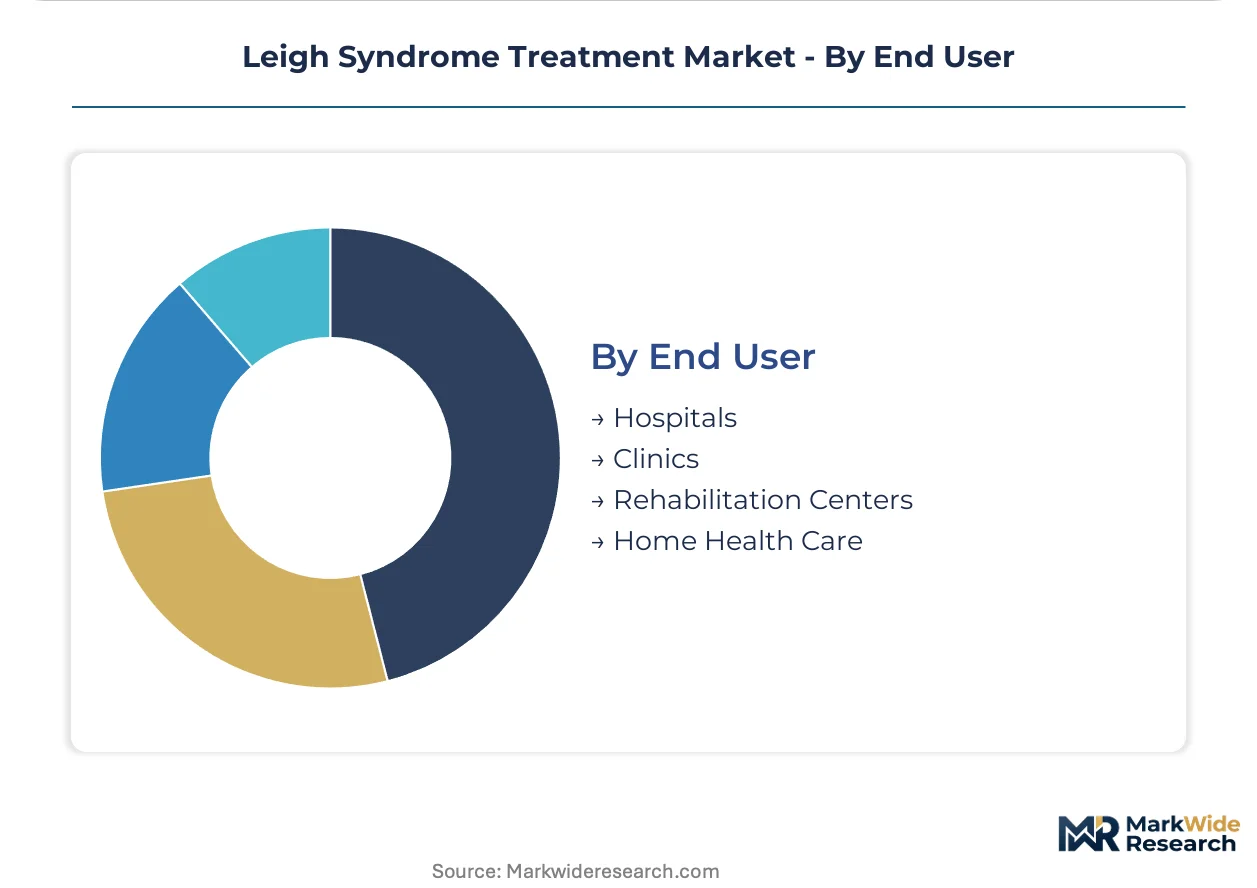
- Hospitals:Tertiary pediatric centers with integrated mitochondrial disease programs capture complex case referrals. Concentrated demand in Boston, San Diego, and Houston generates streamlined trial recruitment infrastructure and post-market surveillance capabilities.
- Home Health Care:Distributed nursing and pharmacy services enable chronic therapy administration outside institutional settings. United States market fragmentation rewards site-of-care flexibility, with specialty distributors building cold-chain capabilities for temperature-sensitive biologics.
- Clinics:Outpatient neurology and metabolic specialty practices for stable patient monitoring.
- Rehabilitation Centers:Physical and occupational therapy focused on neurodevelopmental support.
Hospitals command the highest acuity case mix, with home health care showing the steepest expansion trajectory as oral formulations displace infusion dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leigh syndrome therapeutics originated in the academic medical centers of the United States and Western Europe, where mitochondrial disease research programs first established the clinical infrastructure for ultra-rare neurological intervention. These founding clusters continue to concentrate specialized expertise, patient access networks, and regulatory navigation capabilities that shape commercial pathways today.
United States
Pediatric neurology departments at academic medical centers in Boston, San Diego, and Houston generate concentrated patient access infrastructure that streamlines trial recruitment. The FDA's Rare Pediatric Disease Priority Review Voucher program accelerates capital commitment toward single-administration curative candidates. Specialized mitochondrial disease clinics in these metropolitan clusters anchor post-market surveillance capabilities and physician education networks.
Germany
The country's national pharmaceutical regulator applies distinct health technology assessment criteria that reward first-mover gene therapy entrants with favorable reimbursement positioning. Extended market exclusivity provisions under the EMA orphan designation framework pull late-stage assets toward commercialization readiness. Industrial concentration in Bavaria and North Rhine-Westphalia hosts contract development and manufacturing organizations scaling GMP-compliant viral vector production.
France
Centralized health technology assessment processes constrain pricing flexibility for multi-million-dollar gene therapies, particularly in pediatric neurological indications. ANSM oversees accelerated approval pathways for ultra-rare diseases that align with EMA orphan drug incentives. The Île-de-France region concentrates metabolic disease expertise at Parisian academic hospitals that coordinate multi-national clinical trials.
United Kingdom
The NHS specialized commissioning framework creates distinct access pathways for mitochondrial therapeutics that differ from standard NICE technology appraisal routes. MHRA post-Brexit regulatory autonomy enables tailored trial designs for pediatric rare diseases that maintain alignment with FDA breakthrough therapy standards. London and Cambridge host gene therapy manufacturing scale-up initiatives that serve European market demand.
Japan
PMDA's sakigake designation system accelerates regulatory review for innovative mitochondrial therapeutics addressing unmet pediatric needs. National health insurance price-setting mechanisms for ultra-rare diseases differ materially from standard pharmaceutical reimbursement calculations. The Kanto region around Tokyo concentrates academic medical center capacity for mitochondrial disease diagnosis and management.
Leigh Syndrome Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory incentive capture and manufacturing sophistication, with gene therapy developers commanding valuation multiples that reflect curative potential rather than chronic revenue streams. The competitive structure fragments across three tiers: platform-technology biotechnology firms with viral vector capabilities, metabolic disease specialists with small-molecule portfolios, and emerging gene therapy entrants targeting priority review voucher eligibility. Dominant competitive moves include strategic partnerships with contract development and manufacturing organizations for GMP-compliant viral vector supply, and portfolio diversification into broader mitochondrial disease indications that leverage validated NAD+ modulation platforms.
Within the platform-technology tier, Abliva AB and PTC Therapeutics exemplify divergent strategic positioning around metabolic pathway intervention versus gene delivery infrastructure. Khondrion BV occupies a position among European biotechnology specialists targeting oxidative stress modulation in complex I deficiencies. These three companies represent distinct archetypes—NAD+ platform extension, small-molecule metabolic regulation, and mitochondrial-targeted antioxidant development—that collectively illustrate the competitive segmentation curating capital allocation in ultra-rare neurological therapeutics.
| Leading Market Players |
|---|
| Abliva AB |
| PTC Therapeutics |
| Khondrion BV |
| Santhera Pharmaceuticals |
| Stealth BioTherapeutics |
| Edison Pharmaceuticals |
| VAKS Pharma |
| OMEICOS Therapeutics |
| Taysha Gene Therapies |
| Others |
Pricing and Supply Chain Analysis
Viral vector manufacturing costs cascade through three distinct pricing tiers for Leigh syndrome therapeutics, with GMP-compliant batch production expenses in the United States and Germany determining premium positioning for single-administration gene therapies while metabolic cofactor sourcing from Indian and Chinese API suppliers anchors standard-tier symptomatic treatments.
Pricing Analysis
Curative-disease-modifying-chronic pricing stratification separates gene therapy candidates commanding multi-million-dollar single-administration reimbursement from chronic metabolic support protocols reimbursed through recurring pharmacy benefit structures. Price differentiation hinges on FDA breakthrough therapy designation status and manufacturing complexity tier, with premium gene therapy segments facing pricing compression from European health technology assessment budget impact thresholds while oral small-molecule chronic management retains pricing stability through caregiver-driven demand for home administration convenience.
Supply Chain Analysis
Adeno-associated viral vector supply rests on contract manufacturing organizations concentrated in the United States, Germany, and the United Kingdom, with GMP-compliant production capacity for direct-to-tissue gene delivery drawing from specialized bioreactor equipment and plasmid DNA sourcing. Single-source vulnerability permeates viral vector manufacturing where limited qualified suppliers create supply bottlenecks for multi-indication program expansion, while distribution runs through hospital-based specialty pharmacy channels for temperature-sensitive biologics and expanding cold-chain infrastructure for outpatient oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Leigh syndrome treatment market functions as a regulatory compounder where FDA Rare Pediatric Disease Priority Review Voucher eligibility accelerates capital commitment toward single-administration curative candidates.
For Market Incumbents: Deepen manufacturing scale-up partnerships with contract development organizations in Bavaria and North Rhine-Westphalia to secure GMP-compliant viral vector capacity ahead of competitor pipeline advancement. Anchor post-market surveillance capabilities through academic medical center clusters in Boston and San Diego to defend against emerging gene therapy entrants targeting priority review voucher eligibility. For New Entrants and Emerging Players: Specialty pharmacy distributors present the most penetrable channel for oral and subcutaneous metabolic regulator formulations displacing hospital-centric infusion models. Target caregiver-driven home health care segments in the United States where fragmented payer structures reward site-of-care flexibility, leveraging formulation development partnerships to reduce travel burden for multi-specialty pediatric care. For Investors and Strategic Acquirers: Consolidation pressure builds where gene therapy manufacturing scale-up capabilities lag pipeline advancement timelines across the analysis window. Platform-technology biotechnology firms with validated NAD+ modulation or mitochondrial-targeted antioxidant development represent priority acquisition archetypes; watch FDA breakthrough therapy designation grants as inflection indicators for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | GMP-compliant viral vector production expansion in Germany reduces batch-to-batch variability constraining clinical supply. |
| Rare Pediatric Disease Voucher Monetization | Transferable FDA priority review vouchers generate secondary market liquidity offsetting mitochondrial therapeutic development risk. |
| Home Health Care Channel Development | Specialty pharmacy cold-chain infrastructure in the United States enables outpatient chronic management reducing inpatient dependency. |
| NAD+ Modulation Platform Extension | Small-molecule metabolic regulators validated in Leigh syndrome reposition toward broader complex I deficiency indications. |
| Academic Medical Center Partnership | Pediatric neurology department alliances in Boston and San Diego streamline trial recruitment and post-market surveillance. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads at FDA and EMA, hospital formulary directors, and payer access specialists grounded qualitative insights, cross-referenced against FDA orphan drug designations, EMA submissions, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up patient population estimates and top-down market sizing approaches triangulated value outputs.
Bottom-up modeling anchored forecasts across the projection horizon through segmentation by treatment modality, administration route, patient age cohort, and regional regulatory cluster. CAGRs derived from epidemiological prevalence modeling, pricing trajectory assumptions, and therapy adoption curve analysis incorporating gene therapy manufacturing capacity expansion timelines and health technology assessment reimbursement decisions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy clinical trial readouts and payer willingness to absorb single-administration curative pricing. Forecasts reflect documented assumptions about regulatory pathway timelines and manufacturing scale-up execution. A small set of triggers—FDA breakthrough therapy designations, EMA accelerated approval grants, and major payer coverage determinations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Batten Disease Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Skeletal Dysplasia Market