
 Canavan Disease Treatment Market | 2026-2036
Canavan Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Canavan Disease Treatment Market Outlook
Subscription-based patient monitoring and long-term follow-up services is expanding the addressable value per treated patient beyond the initial intervention. Sarepta Therapeutics, Inc. leverages its neuromuscular gene therapy infrastructure to extend capabilities into rare leukodystrophies. Abeona Therapeutics LLC anchors its position through AAV vector manufacturing scale and internal plasmid supply. Orchard Therapeutics plc competes on the strength of its autologous ex vivo gene therapy platform and European clinical footprint.
Canavan disease treatment encompasses interventions targeting the ASPA gene mutation that disrupts N-acetylaspartate metabolism in oligodendrocytes, causing progressive demyelination and spongiform degeneration of cerebral white matter. Gene therapy using AAV9 vectors to deliver functional ASPA transgenes directly to the central nervous system represents the most technically advanced modality in development. Intravenous delivery dominates current clinical protocols, though intraosseous administration to the skull base is gaining traction for improved CNS biodistribution. Hospitals and specialty clinics capture the majority of procedure volumes, while homecare settings remain limited by infusion complexity and monitoring requirements.
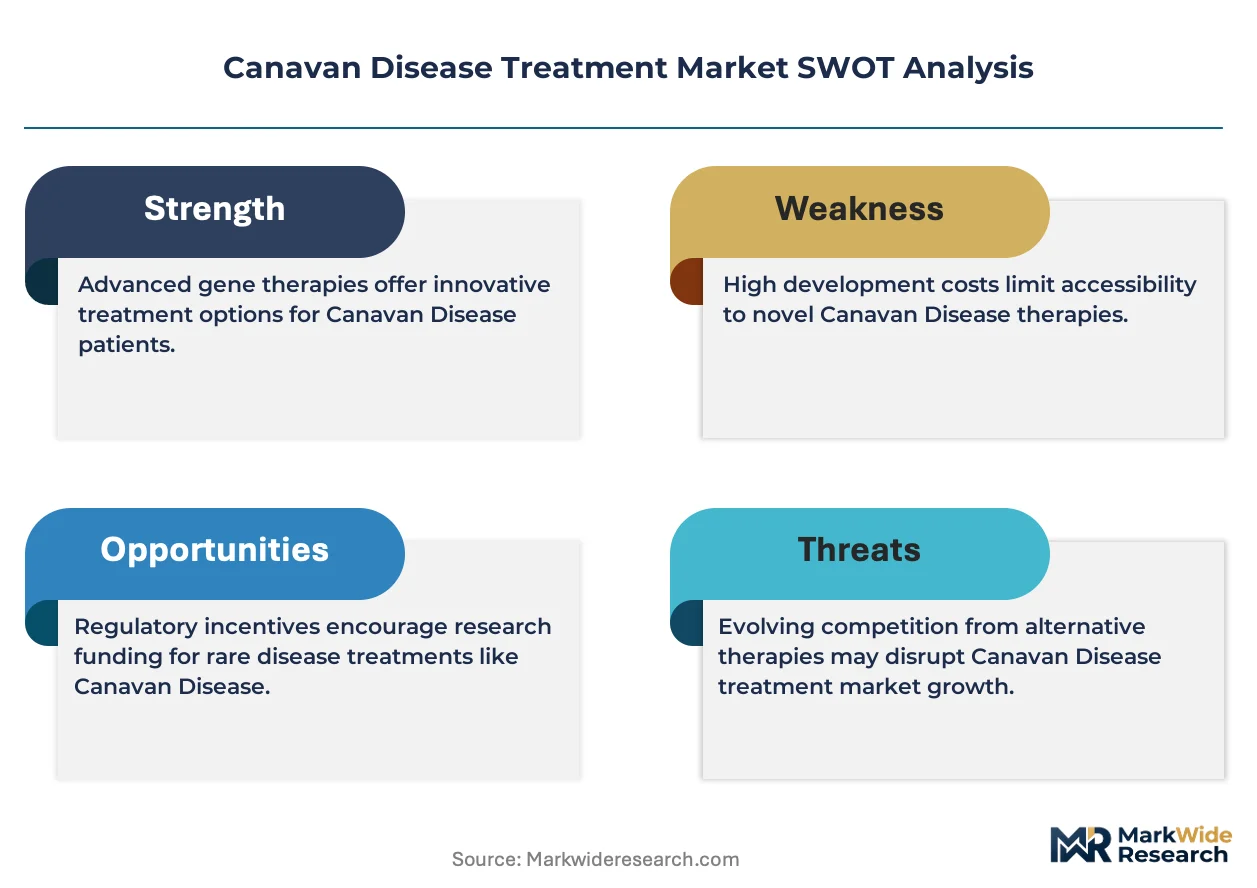
FDA orphan drug incentives and the EU's EMA priority medicines scheme accelerate development timelines and extend market exclusivity protections for Canavan therapies. The EU AI Act and GDPR impose stringent requirements on algorithmic patient stratification tools and cross-border genomic data transfers, complicating multinational trial execution. Stakeholders must track evolving reimbursement frameworks for one-time gene therapies, as payers experiment with outcomes-based installment models and novel risk-sharing arrangements.
Market Dynamics
The Canavan disease treatment landscape pivots on FDA's accelerated approval pathway for gene therapies, which compresses development timelines while intensifying pressure on post-market confirmatory evidence generation for AAV-based interventions.
Growth Catalysts
- Orphan Drug Exclusivity:The FDA grants seven-year market exclusivity and tax credits for qualified rare disease therapies, incentivizing biopharma investment in ASPA-targeted programs.
- Pediatric Neurology Infrastructure:Specialized leukodystrophy centers in the United States concentrate diagnostic expertise and patient access, creating referral density for clinical trial recruitment.
- AAV Manufacturing Scale-Up:Internal plasmid supply chains and suspension bioreactor platforms reduce per-dose production costs for CNS-directed gene therapies.
Market Restraints
- Vector Immunogenicity:Pre-existing neutralizing antibodies against AAV9 capsids exclude a measurable subset of pediatric candidates from receiving intravenous gene therapy.
- Single-Site Production Concentration:GMP-grade AAV manufacturing clusters in the Northeastern United States, creating geographic vulnerability to regional supply disruptions.
- Reimbursement Uncertainty:CMS and private payers lack standardized frameworks for one-time gene therapy pricing, delaying formulary placement decisions.
Strategic Opportunities
- Intraosseous Delivery Innovation:Skull-base administration protocols improve CNS biodistribution compared to intravenous infusion, potentially expanding addressable patient populations.
- Subscription Monitoring Models:Long-term follow-up services capture recurring revenue streams beyond the index procedure, anchoring patient relationships.
- European Clinical Expansion:EMA's priority medicines scheme offers accelerated assessment timelines for rare disease therapies, complementing FDA pathways.
Industry Challenges
- Neurointerventional Skill Scarcity:Intraosseous delivery requires specialized surgical expertise in pediatric skull-base access, limiting site activation for advanced protocols.
- Post-Market Evidence Burden:FDA accelerated approval mandates confirmatory trials, forcing sponsors to maintain expensive long-term natural history cohorts.
- Cross-Border Data Friction:GDPR restrictions on genomic data transfers complicate multinational patient registries and pooled safety analyses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canavan Disease Treatment Market |
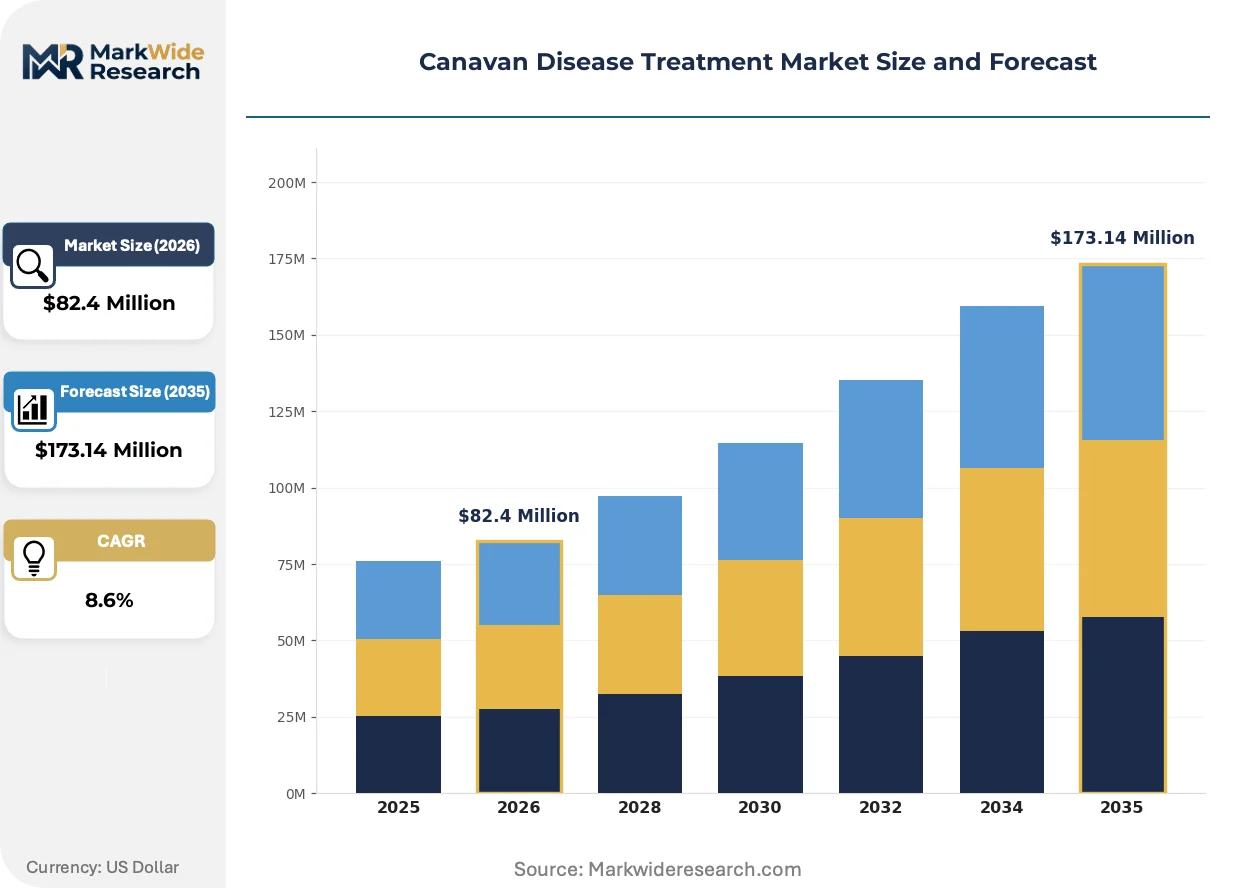
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $173.14 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Enzyme Replacement Therapy, Symptomatic Treatment, Supportive Care Delivery Mode: Intravenous, Subcutaneous, Oral, Intraosseous End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Care Setting: Pediatric Care, Neurology Units, Rehabilitation Centers, Outpatient Facilities |
| Companies Covered | Sarepta Therapeutics, Inc., PTC Therapeutics, Inc., Abeona Therapeutics LLC, Passage Bio, Inc., Neurogene Inc., Anjarium Biosciences AG, Orchard Therapeutics plc, Myrtelle Inc., Axovant Gene Therapies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canavan Disease Treatment Market Strategic Shifts
Gene therapy modalities for Canavan disease are converging around CNS-targeted delivery optimization, while regulatory frameworks and care delivery models undergo parallel recalibration to accommodate one-time curative interventions.
AAV9-mediated ASPA gene delivery is consolidating as the dominant technical platform for Canavan disease intervention. Pediatric neurology units at specialized leukodystrophy centers are adopting intravenous protocols as standard of care, with intraosseous administration emerging as a next-generation alternative. This technology shift is consolidating competitive advantage around sponsors with captive vector manufacturing and neurointerventional surgical networks.
FDA's accelerated approval pathway for gene therapies is reshaping evidence requirements for rare neurological conditions. Sponsors must now design confirmatory trials at the time of initial approval, embedding long-term follow-up into commercial infrastructure. Pediatric neurology programs in the United States are responding by building dedicated gene therapy outcome assessment capabilities.
Care delivery is fragmenting across site-of-service boundaries as hospitals and specialty clinics compete for gene therapy procedure volumes. Homecare settings remain constrained by infusion complexity, but remote patient monitoring technologies are beginning to displace inpatient observation for stable post-infusion periods. This channel evolution is most visible in the Northeastern United States, where leukodystrophy center density supports decentralized follow-up models.
Canavan Disease Treatment Market Segmentation
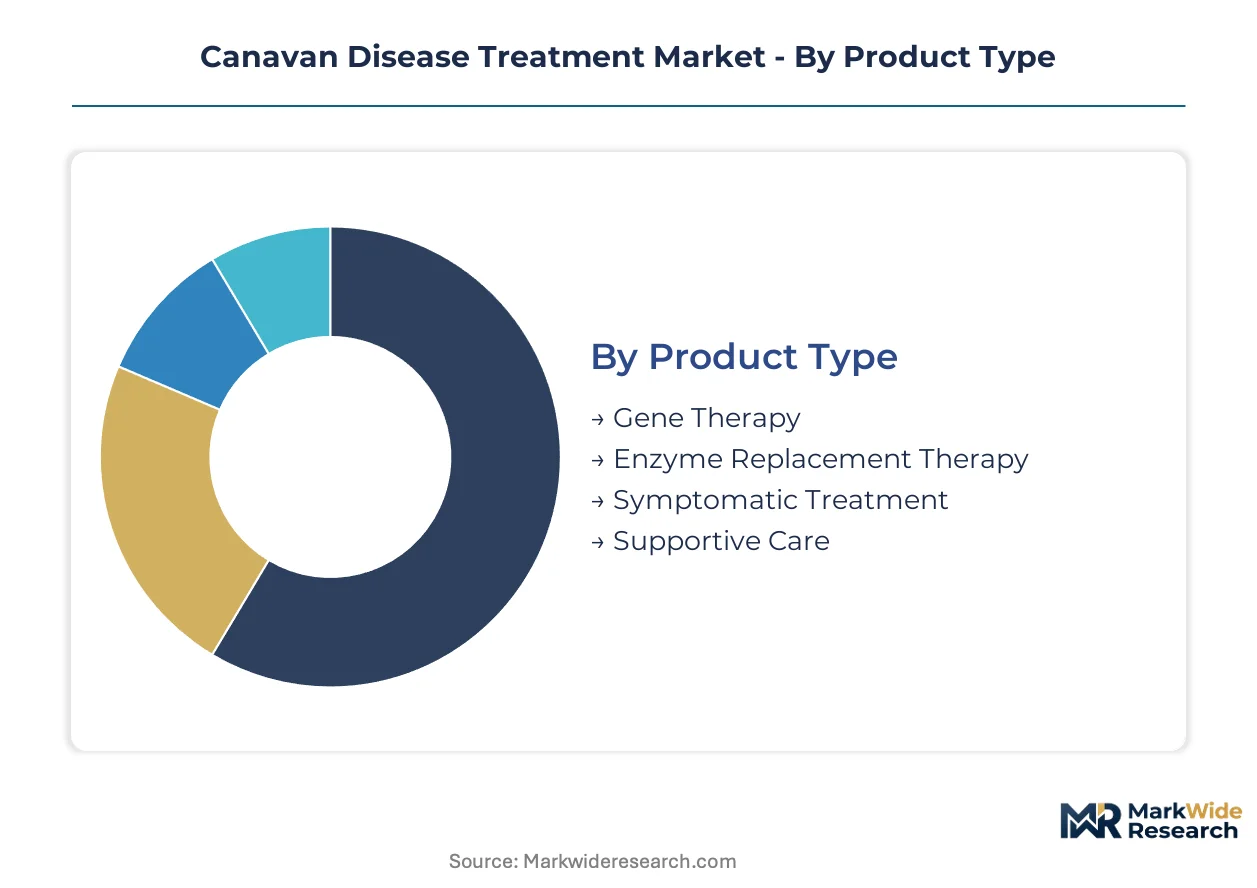
Canavan disease treatment segments reflect the tension between curative gene therapy interventions and chronic symptom management protocols. Treatment modality selection depends on disease stage, vector eligibility, and institutional access to specialized neurointerventional capabilities.
Product Type:
Gene therapy operates as a standalone curative platform requiring discrete manufacturing and delivery infrastructure, while enzyme replacement and symptomatic modalities embed into broader leukodystrophy management protocols.
- Gene Therapy:AAV9-mediated ASPA transgene delivery directly to the central nervous system. Demand concentrates at specialized leukodystrophy centers in Boston and Philadelphia, driven by FDA accelerated approval pathways and seven-year orphan drug exclusivity incentives.
- Enzyme Replacement Therapy:Exogenous aspartoacylase enzyme administration to partially restore N-acetylaspartate metabolism. Adoption clusters among patients with pre-existing AAV9 neutralizing antibodies who are excluded from gene therapy protocols.
- Symptomatic Treatment:Anticonvulsants, antispasmodics, and gastrostomy support for disease manifestations. Embedded within standard pediatric neurology practice across community hospital settings.
- Supportive Care:Multidisciplinary management of feeding, respiratory, and mobility complications. Delivered through integrated care teams at major academic medical centers.
Volume placements concentrate in Gene Therapy; the faster expansion belongs to Symptomatic Treatment as diagnosis rates improve and presymptomatic intervention windows narrow.
Delivery Mode:
Route selection determines CNS biodistribution efficiency, immunogenicity risk profiles, and site-of-service requirements, creating distinct cost tiers across administration modalities.
- Intravenous:Systemic AAV9 infusion with established pediatric dosing protocols. Captures the majority of current gene therapy volumes at specialized leukodystrophy centers, constrained by pre-existing neutralizing antibody screening requirements.
- Intraosseous:Direct skull-base administration to the sphenoid bone for enhanced CNS vector penetration. Emerging at neurointerventional surgery programs with pediatric skull-base access expertise, offering expanded eligibility for seropositive candidates.
- Subcutaneous:Enzyme replacement delivery with home administration potential. Limited by poor CNS penetration for ASPA-targeted therapies.
- Oral:Symptomatic medication administration for seizure and spasticity control. Dominates chronic management outside gene therapy treatment windows.
Intravenous infusion anchors current revenue; Intraosseous protocols are climbing the fastest as neurointerventional capabilities expand at US pediatric centers.
End User:
Customer type segmentation tracks the shift from inpatient gene therapy delivery toward decentralized follow-up models, with reimbursement complexity favoring institutional over home-based administration.
- Hospitals:Academic medical centers with GMP-compliant vector handling and neurointerventional surgery suites. Capture index gene therapy procedures and acute adverse event management.
- Specialty Clinics:Dedicated leukodystrophy and pediatric neurology centers with longitudinal natural history cohorts. Concentrate patient identification, screening, and post-treatment monitoring.
- Homecare Settings:Limited to stable chronic symptom management and oral medication administration. Constrained by infusion complexity and FDA risk evaluation and mitigation strategy requirements.
- Research Institutions:Natural history study enrollment and expanded access protocols. Bridge preclinical and commercial evidence generation.
Hospitals dominate procedure value; Specialty Clinics are gaining share fastest through subscription-based long-term follow-up service models.
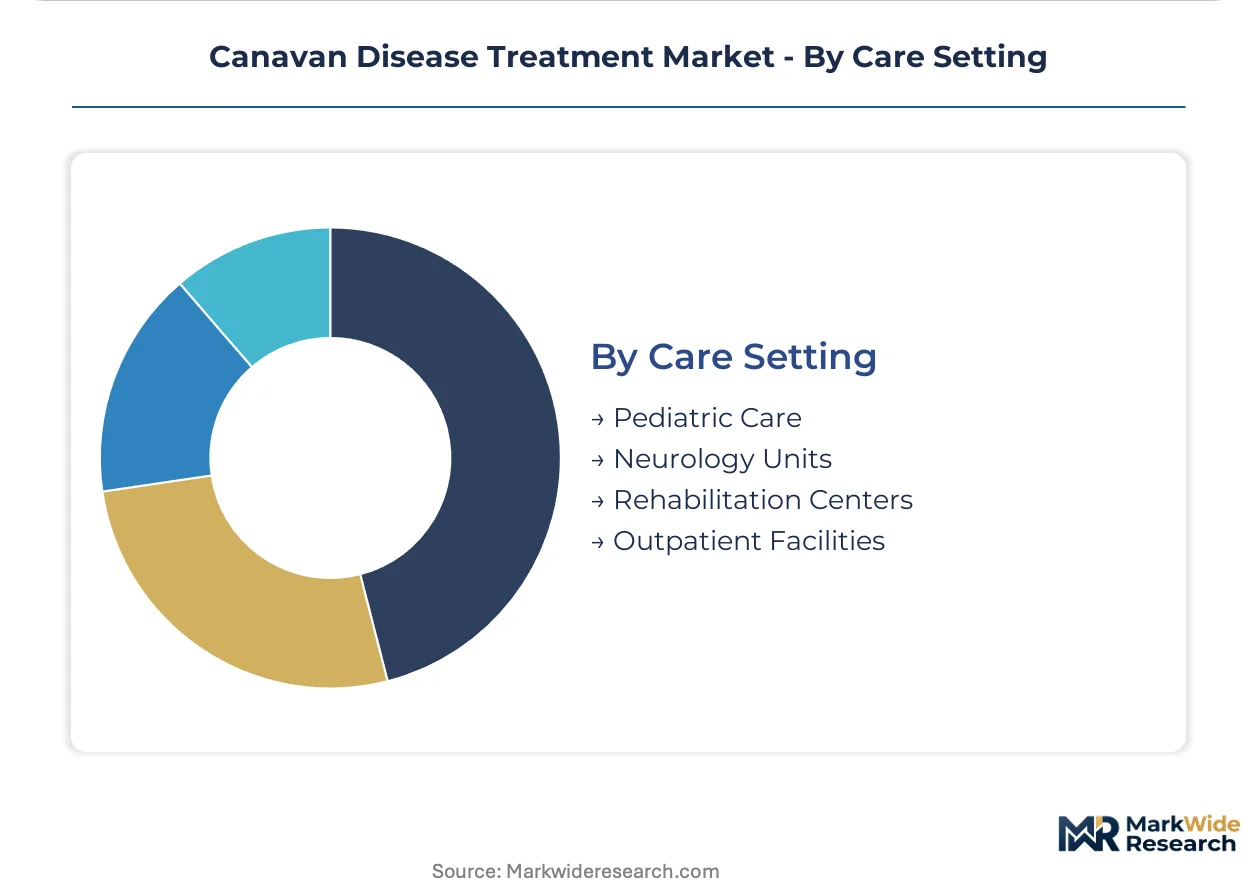
Care Setting:
Site-of-service segmentation reflects the pediatric neurology infrastructure concentration in the Northeastern United States, with rehabilitation and outpatient channels capturing downstream chronic management.
- Pediatric Care:Integrated developmental and neurological assessment for infantile-onset disease. Anchors early diagnosis and treatment initiation windows.
- Neurology Units:Specialized inpatient and outpatient services for leukodystrophy management. House gene therapy administration capabilities and neurocritical care backup.
- Rehabilitation Centers:Physical, occupational, and speech therapy for progressive functional decline. Embedded within chronic disease management protocols.
- Outpatient Facilities:Remote monitoring and routine follow-up for stable post-gene therapy patients. Expanding through telemedicine integration.
Neurology Units concentrate intervention volumes; Outpatient Facilities show the steepest expansion trajectory as remote patient monitoring technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing concentrates in the Northeastern United States, while patient identification and treatment demand spreads across specialized leukodystrophy centers in multiple countries. Production capacity remains geographically narrow, creating supply chain exposure as clinical adoption widens.
United States
Pediatric neurology infrastructure and FDA orphan drug incentives concentrate development activity. The FDA accelerated approval pathway compresses timelines for ASPA-targeted gene therapies. Boston and Philadelphia anchor specialized leukodystrophy centers that capture the majority of clinical trial recruitment and index procedures.
Germany
Academic medical centers in Munich and Heidelberg maintain natural history cohorts that support European regulatory submissions. The EMA priority medicines scheme offers parallel accelerated assessment for rare neurological conditions. Bavarian research hospitals coordinate cross-border patient registries with Austrian and Swiss partners.
United Kingdom
NHS England's specialized commissioning framework creates reimbursement pathways for one-time gene therapies. The MHRA operates a rolling review mechanism for novel genetic medicines. London-based pediatric neurology units participate in multinational trials through the European Reference Network for Rare Neurological Diseases.
France
ANSM's early access programs enable pre-approval treatment use for ultra-rare conditions. The country's national strategy for rare diseases funds reference centers in Paris and Lyon. French academic hospitals contribute to EMA scientific advice procedures for CNS-directed AAV therapies.
Canada
Health Canada's priority review pathway aligns with FDA timelines for orphan neurological therapies. Provincial drug plans experiment with outcomes-based reimbursement for single-administration interventions. Toronto's Hospital for Sick Children anchors pediatric gene therapy expertise and natural history data collection.
Canavan Disease Treatment Market Competitive Environment
Capital-heavy vector manufacturers compete with asset-light gene therapy developers for control of the Canavan treatment value chain. The market structure tilts toward consolidated manufacturing capacity and fragmented clinical-stage development. Three archetypes dominate: integrated vector producers with captive supply chains, neuromuscular gene therapy extenders leveraging existing CNS delivery infrastructure, and European autologous platform specialists. Competitive moves center on manufacturing scale-up investments and neurointerventional surgical network partnerships.
Among US-based integrated developers, Sarepta Therapeutics, Inc. and Abeona Therapeutics LLC exemplify the vector-manufacturing archetype with internal plasmid supply and suspension bioreactor capabilities. Orchard Therapeutics plc represents the European autologous platform specialist, competing through ex vivo gene therapy infrastructure and continental clinical footprint. These three anchors illustrate the geographic and technological segmentation shaping competitive positioning.
| Leading Market Players |
|---|
| Sarepta Therapeutics, Inc. |
| PTC Therapeutics, Inc. |
| Abeona Therapeutics LLC |
| Passage Bio, Inc. |
| Neurogene Inc. |
| Anjarium Biosciences AG |
| Orchard Therapeutics plc |
| Myrtelle Inc. |
| Axovant Gene Therapies Ltd. |
| Others |
Value Chain & Pricing Dynamics
AAV9 plasmid DNA and suspension bioreactor consumables cascade through Northeastern US manufacturing clusters into three-tier pricing structures across premium, standard, and economy levels, with FDA orphan drug exclusivity premiums attaching at the point of pediatric neurology unit procurement.
Pricing Analysis
Margin tightening in gene therapy manufacturing reflects captive vector production scale advantages concentrated among integrated developers with internal plasmid supply chains. Pricing stratifies across premium, standard, and economy tiers based on GMP certification grade and neurointerventional surgical bundling. Cost-down pressure on standard-tier AAV doses accelerates because contract manufacturing organizations compete for sponsor volume. Academic medical centers show highest price sensitivity due to bundled reimbursement constraints, while specialty leukodystrophy clinics absorb premium pricing for intraosseous delivery protocols.
Supply Chain Analysis
Domestic-content mandates for critical biologics manufacturing are reshaping sourcing patterns for GMP-grade AAV production, with Massachusetts and Pennsylvania state-level incentives tethering plasmid suppliers to regional vector finishing facilities. Raw material dependencies center on HEK293 cell lines, baculovirus helper plasmids, and chromatography resins. Single-source vulnerability concentrates in skull-base surgical instrument supply for intraosseous protocols. Distribution runs through hospital pharmacy and specialty clinic channels with cold-chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canavan disease treatment market is consolidating around vector manufacturing scale, with FDA post-market confirmatory evidence burdens forcing capital-constrained developers toward exit or acquisition.
For Market Incumbents: Anticipate reimbursement compression from CMS outcomes-based installment experiments by deepening backward integration into AAV plasmid production and locking multi-year supply agreements with Boston and Philadelphia leukodystrophy centers. Vector immunogenicity screening failures among pediatric candidates threaten addressable patient pools; anchor defensive positioning through intraosseous delivery capability partnerships with pediatric neurointerventional surgery programs. For New Entrants and Emerging Players: Begin with enzyme replacement therapy for AAV9-seropositive patients excluded from gene therapy protocols, a white-space segment with unmet demand and lower regulatory evidence thresholds. European EMA priority medicines pathways offer faster assessment timelines than FDA for first-in-continent sponsors. Target Bavarian and Heidelberg academic medical centers with natural history data partnerships as the go-to-market anchor. For Investors and Strategic Acquirers: FDA confirmatory trial protocol amendments for approved AAV therapies are the leading indicator that post-market evidence generation costs will stratify competitive economics over the five-to-ten year window. Acquisition targets should display captive manufacturing or locked European clinical infrastructure. Watch for EMA rolling review acceptances as the signal that European revenue timelines are compressing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Internal plasmid supply and suspension bioreactor capacity reduce per-dose COGS for CNS-directed AAV9 therapies. |
| Intraosseous Delivery Development | Skull-base administration protocols expand eligibility for seropositive patients beyond intravenous screening exclusions. |
| European Clinical Expansion | EMA priority medicines scheme accelerates assessment timelines and diversifies regulatory risk beyond FDA pathways. |
| Subscription Monitoring Models | Long-term follow-up services capture recurring revenue streams and anchor patient relationships post-index procedure. |
| Neurointerventional Partnerships | Pediatric skull-base surgical networks limit site activation for advanced delivery protocols and concentrate procedure volumes. |
Study Parameters
FDA orphan drug designations, ClinicalTrials.gov registry entries, and EMA scientific advice procedures formed the secondary backbone, cross-referenced against primary interviews with gene therapy development executives, regulatory affairs leads at ASPA-targeted programs, hospital pharmacy directors at specialized leukodystrophy centers, and payer access specialists managing outcomes-based contracts. Bottom-up patient flow modeling and top-down vector manufacturing capacity estimates were triangulated to anchor volume and value projections.
Bottom-up segmentation across treatment modality, delivery route, and care setting was reconciled against top-down orphan drug revenue benchmarks throughout the forecast period. CAGRs were derived from natural history cohort expansion rates and gene therapy adoption curves at US pediatric neurology units. Industry-specific inputs included AAV9 neutralizing antibody prevalence screening data and intraosseous protocol activation timelines at neurointerventional surgery programs.
Regulatory approval reversals, vector immunogenicity safety signals, and reimbursement framework collapses are the dominant revision risks to modeled adoption trajectories. Forecasts reflect documented assumptions on patient identification rates and manufacturing scale realization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Batten Disease Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market