
 Alpha-1 Antitrypsin Deficiency Market | 2026-2036
Alpha-1 Antitrypsin Deficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha-1 Antitrypsin Deficiency Market Outlook
Multi-source plasma collection is realigning supply security for Alpha-1 Antitrypsin Deficiency therapies as manufacturers diversify beyond single-origin dependencies. Grifols leverages vertically integrated plasma fractionation networks across Spain and the United States to secure raw material access. CSL Behring anchors its position through high-volume plasma processing capacity and long-standing donor center relationships. Takeda Pharmaceutical Company competes via specialized immunology portfolios that extend into rare protein replacement markets.
Alpha-1 Antitrypsin Deficiency is a genetic disorder characterized by insufficient production of the AAT protein, a 52-kilodalton serine protease inhibitor synthesized primarily in hepatocytes, where deficiency leads to uncontrolled neutrophil elastase activity and progressive lung tissue destruction. Plasma-derived therapy remains the dominant revenue category due to established reimbursement and decades of clinical validation, while gene therapy represents the fastest-growing segment as vector delivery technologies mature and durability data accumulates. Intravenous infusion maintains structural importance in hospital settings, though subcutaneous delivery is gaining traction in homecare settings where patient convenience drives preference shifts.
The FDA's orphan drug designation framework and the EMA's parallel incentives for rare disease therapies shape development economics by extending market exclusivity and reducing regulatory fees for AATD innovators. The EU's MDR requirements for plasma-derived products impose stringent traceability and viral safety standards that filter smaller manufacturers from European market access. Stakeholders must monitor gene therapy durability readouts and payer willingness to fund curative modalities against chronic replacement paradigms.
Market Dynamics
Gene therapy vector durability is forcing plasma-derived manufacturers to defend chronic replacement revenue against one-time curative alternatives, while FDA orphan drug incentives accelerate pipeline diversification among biotech entrants.
Growth Catalysts
- EMA's parallel orphan drug incentives:European regulators extend market exclusivity and reduce fees for rare disease biologics, attracting development investment into AATD therapies.
- Specialty clinic expansion:Dedicated respiratory centers in the United States broaden patient access to augmentation therapy and drive diagnosis rates.
- Subcutaneous delivery technology:Homecare-compatible administration methods reduce hospital dependency and improve patient adherence to replacement protocols.
Market Restraints
- Plasma collection concentration:United States dominance in donor infrastructure creates supply vulnerability for manufacturers dependent on North American raw material sourcing.
- EU MDR traceability mandates:Stringent viral safety and origin-tracking requirements filter smaller fractionators from European market participation.
- Gene therapy substitution threat:CRISPR-based and AAV-vector approaches promise functional cures that would eliminate chronic protein replacement demand.
Strategic Opportunities
- Underpenetrated European diagnosis:Spain and Italy show latent prevalence pools with limited screening infrastructure, offering expansion potential for testing and treatment.
- Neonatal screening mandates:State-level implementation of genetic testing protocols in newborn populations creates presymptomatic patient identification channels.
- Biobetters and half-life extension:Fc-fusion and PEGylation technologies converge to reduce infusion frequency and differentiate next-generation products.
Industry Challenges
- Vector manufacturing scale-up:Gene therapy producers face capacity constraints in GMP-compliant AAV production that delay clinical trial enrollment and commercial readiness.
- Reimbursement negotiation complexity:Payers demand long-term durability data before funding curative modalities, creating financing gaps between approval and adoption.
- Plasma donor recruitment:Specialized collection centers compete for limited eligible donors with rare disease antibodies required for hyperimmune product manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha-1 Antitrypsin Deficiency Market |
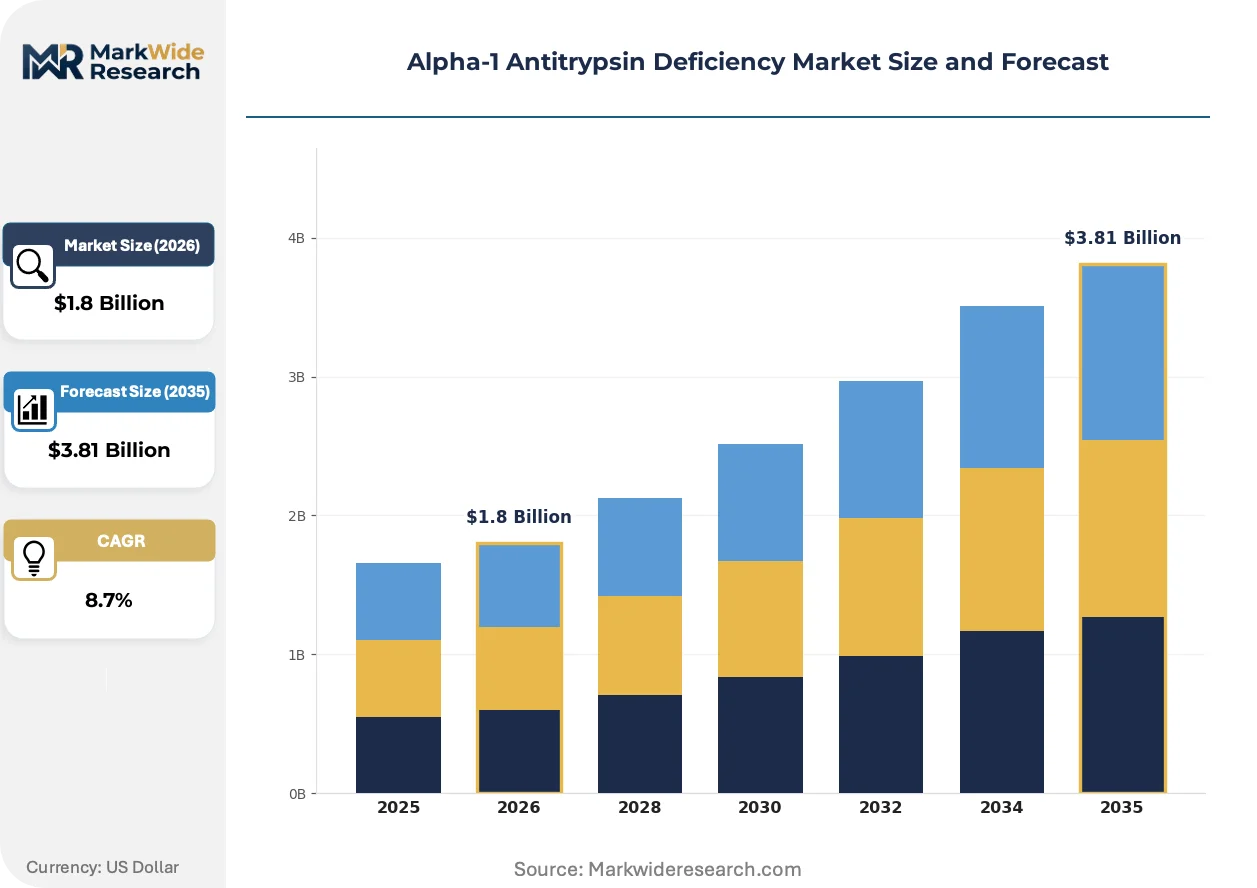
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Protein, Plasma-Derived Therapy, Gene Therapy, Monoclonal Antibodies Delivery Mode: Intravenous, Subcutaneous, Inhalation, Oral End User: Hospitals, Homecare Settings, Specialty Clinics, Laboratories Application: Chronic Obstructive Pulmonary Disease, Liver Disease, Clinical Trials, Supportive Care |
| Companies Covered | Grifols, CSL Behring, Takeda Pharmaceutical Company, Kamada, AstraZeneca, Pfizer, Boehringer Ingelheim, Baxter, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha-1 Antitrypsin Deficiency Market Strategic Shifts
Delivery modality innovation and regulatory pathway refinement are compressing development timelines while reshaping competitive boundaries between chronic replacement and curative approaches.
AAV-based liver-directed gene therapy is absorbing clinical development resources previously allocated to plasma-derived augmentation, with vector engineering advances improving hepatocyte transduction efficiency. Academic medical centers and specialized gene therapy units are accelerating patient enrollment for durability trials. This technology is absorbing market attention from protein replacement manufacturers who must now demonstrate non-inferior safety profiles against potentially curative alternatives.
EMA's MDR requirements for plasma-derived biologics impose batch-level viral safety documentation and donor traceability standards that exceed prior CE-marking obligations. Fractionators must retrofit quality systems to accommodate real-time supply chain monitoring. European manufacturers with legacy infrastructure face the steepest compliance costs, while newer entrants design native MDR-compliant processes.
Home infusion nursing networks are displacing hospital-based administration as the default delivery channel for established patients on maintenance therapy. Specialty pharmacy distributors are building direct-to-patient logistics capabilities that bypass traditional hospital purchasing committees. This channel shift is most visible in United States markets where reimbursement supports home healthcare services and patient convenience drives retention.
Alpha-1 Antitrypsin Deficiency Market Segmentation
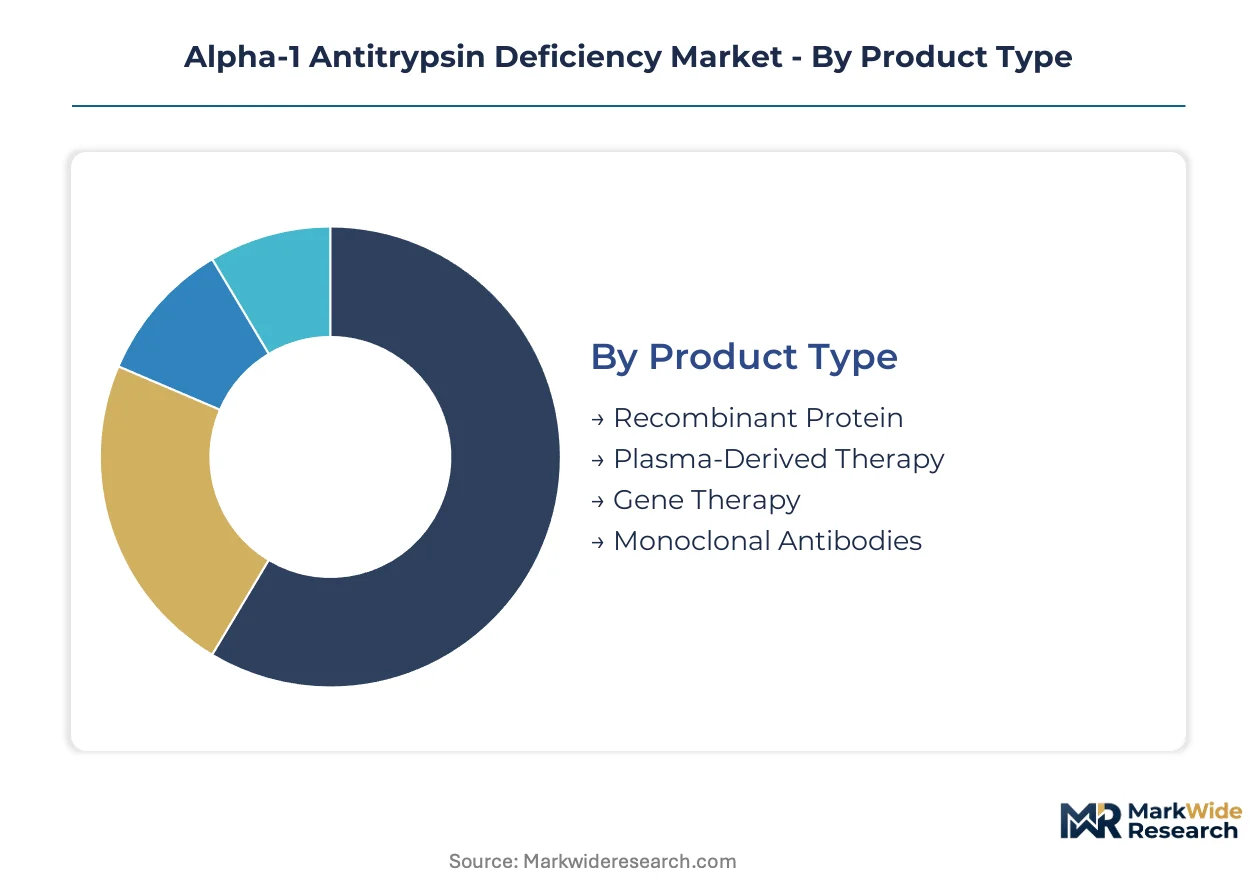
Alpha-1 Antitrypsin Deficiency treatment modalities span chronic replacement, curative intervention, and supportive management, with each segment demanding distinct manufacturing capabilities, distribution channels, and reimbursement frameworks. The market structure reflects tension between established plasma-derived standards and emerging biologic innovations.
Product Type:
Customization intensity varies sharply across this category, from standardized plasma fractionation outputs to patient-specific gene therapy vectors requiring individualized manufacturing protocols.
- Plasma-Derived Therapy:Purified human Alpha-1 Antitrypsin protein extracted through Cohn fractionation and viral inactivation processes, administered as weekly intravenous infusions. Demand concentrates in United States specialty clinics where established reimbursement pathways and decades of safety data sustain preference among pulmonologists managing progressive emphysema.
- Gene Therapy:Liver-directed AAV vectors delivering functional SERPINA1 gene copies to restore endogenous protein production. Clinical development accelerates in academic medical centers across Spain and Italy as durability data from early-phase trials reshape competitive positioning against chronic replacement paradigms.
- Recombinant Protein:Yeast or mammalian cell culture-derived AAT manufactured without plasma donor dependency.
- Monoclonal Antibodies:Investigational biologics targeting inflammatory pathways downstream of elastase-mediated tissue damage.
Leading the category by volume: Plasma-Derived Therapy. Expanding most quickly: Gene Therapy.
Delivery Mode:
Cost tier stratification separates hospital-based administration from homecare-compatible alternatives, with capital intensity and nursing requirements driving reimbursement differentials.
- Intravenous:Hospital or infusion center-based delivery of protein replacement therapy requiring 30-60 minute supervised administration sessions. United States Medicare reimbursement structures favor site-of-care flexibility, though hospital outpatient departments retain volume concentration due to specialist oversight requirements for newly diagnosed patients.
- Subcutaneous:Self-administered or home nursing-supported injection protocols enabled by concentrated protein formulations and patient training programs. Preference shifts accelerate in German and French markets where home healthcare infrastructure reduces total cost of care for maintenance-phase patients.
- Inhalation:Direct pulmonary delivery of aerosolized AAT to target lung tissue.
- Oral:Systemic absorption of small molecule elastase inhibitors or gene expression modulators.
Hospital channels dominate current volume. Homecare administration gains share fastest.
End User:
Customer type fragmentation reflects divergent purchasing authority, with integrated delivery networks, specialty pharmacies, and direct-to-patient channels competing for therapy distribution control.
- Specialty Clinics:Dedicated respiratory and hepatology centers providing coordinated diagnosis, genetic counseling, and long-term disease management. Expansion concentrates in United States metropolitan clusters where pulmonologist density and patient advocacy organization presence drive screening program implementation.
- Homecare Settings:Nurse-supported or self-directed therapy administration outside institutional facilities. Growth accelerates where reimbursement supports remote monitoring technologies and specialty pharmacy networks build direct logistics capabilities bypassing traditional hospital purchasing.
- Hospitals:Acute care facilities managing exacerbations and initial diagnosis workups.
- Laboratories:Reference and clinical testing sites performing genotyping and phenotyping.
Specialty clinics lead by patient volume. Homecare settings climb the fastest.
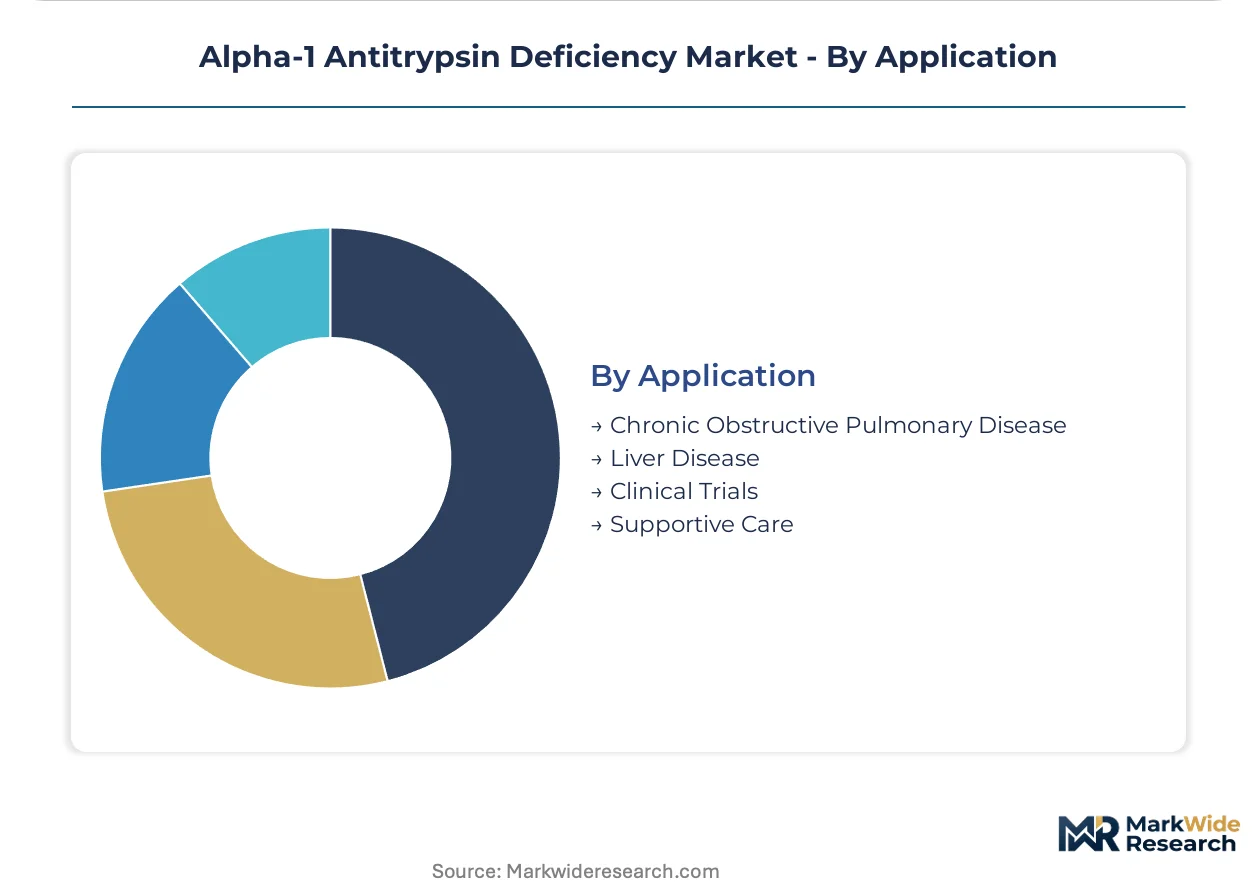
Application:
Maturity gradients separate well-established lung-directed therapy from emerging liver-focused interventions and preclinical pipeline categories.
- Chronic Obstructive Pulmonary Disease:Emphysema and bronchiectasis management through elastase inhibition represents the dominant clinical indication with established efficacy endpoints. United States pulmonology practices anchor demand where high-resolution CT screening and spirometry protocols identify eligible augmentation therapy candidates.
- Liver Disease:Pediatric cholestasis, cirrhosis, and hepatocellular carcinoma surveillance in PiZZ homozygous patients. Spanish referral centers advance transplant-free survival studies as liver-directed gene therapy trials enroll pediatric cohorts with severe synthetic dysfunction.
- Clinical Trials:Investigational therapy development and natural history study participation.
- Supportive Care:Symptom management and quality-of-life interventions without disease-modifying intent.
COPD applications dominate current volume. Liver disease represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma collection infrastructure in the United States anchors raw material supply for augmentation therapy manufacturers, while diagnostic concentration and regulatory frameworks create divergent market trajectories across national boundaries.
United States
Specialty respiratory clinics in metropolitan clusters drive patient identification through high-resolution CT screening protocols. FDA orphan drug incentives extend market exclusivity for rare disease biologics, attracting development investment into gene therapy pipelines. The Southeast and Midwest regions concentrate plasma collection centers where Grifols and CSL Behring maintain vertically integrated donor networks.
Germany
Homecare administration gains preference among maintenance-phase patients seeking reduced hospital dependency. EMA parallel orphan drug frameworks align with national reimbursement structures for rare disease therapies. The Rhine-Ruhr and Bavarian medical corridors host specialized pulmonary centers advancing subcutaneous delivery protocols.
Spain
Latent prevalence pools in Mediterranean populations remain underdiagnosed relative to Northern European benchmarks. EMA MDR traceability mandates impose batch-level viral safety documentation that filters smaller fractionators from market participation. Barcelona and Madrid academic medical centers accelerate liver-directed gene therapy enrollment for pediatric cholestasis cohorts.
Italy
Lombardy and Veneto regions concentrate referral capacity for transplant-free survival studies in PiZZ homozygous liver disease patients. National neonatal screening implementation remains fragmented across regional health systems. Milan-based research hospitals coordinate multicenter durability trials for AAV-vector approaches.
United Kingdom
London and Southeast England anchor specialist commissioning for alpha-1 antitrypsin deficiency through designated respiratory networks. MHRA alignment with EMA orphan drug pathways streamlines rare disease therapy authorization. The Midlands and North England regions show diagnostic penetration gaps that advocacy organizations target with screening program expansion.
Alpha-1 Antitrypsin Deficiency Market Competitive Environment
Global majors compete with regional champions across plasma fractionation capacity and gene therapy development resources, producing a consolidated structure where three manufacturers control augmentation therapy supply. European and North American players dominate established protein replacement, while biotechnology entrants absorb clinical development investment into curative modalities. Two strategic archetypes prevail: vertically integrated plasma collectors with donor network control, and vector engineering specialists with academic medical center partnerships. Capacity expansion and strategic licensing arrangements constitute the dominant competitive moves as manufacturers defend chronic replacement revenue against one-time curative alternatives.
Among plasma-derived therapy specialists, Grifols, CSL Behring, and Takeda Pharmaceutical Company occupy positions reflecting distinct geographic and integration strategies. Grifols exemplifies the vertically integrated archetype with Spanish and United States fractionation assets. CSL Behring represents high-volume processing capacity anchored in long-standing donor center relationships. Takeda sits within the diversified immunology portfolio archetype, extending rare protein replacement capabilities through specialized therapeutic area focus.
| Leading Market Players |
|---|
| Grifols |
| CSL Behring |
| Takeda Pharmaceutical Company |
| Kamada |
| AstraZeneca |
| Pfizer |
| Boehringer Ingelheim |
| Baxter |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
EMA's MDR viral safety documentation mandates gate qualified plasma fractionation supply and premium-tier pricing access for European market participants, filtering smaller manufacturers while concentrating pricing power among compliant incumbents with retrofitted quality systems.
Pricing Analysis
Warranty and service bundling separates hospital-contracted augmentation therapy from unbundled homecare administration, with nursing support and remote monitoring included in institutional pricing but charged separately in direct-to-patient channels. Three-tier pricing structure across premium, standard, and economy levels reflects plasma protein purity grades, FDA orphan drug exclusivity periods, and volume commitment scales. Cost compression in the standard tier is intensifying because gene therapy durability data is reshaping payer willingness to fund chronic replacement. Hospital purchasing committees exhibit lowest price sensitivity due to bundled reimbursement, while self-pay homecare patients in German markets demonstrate highest sensitivity to unbundled service fees.
Supply Chain Analysis
Dual-sourcing requirements from European hospital systems and United States specialty pharmacies mandate multi-supplier qualification for plasma-derived AAT, forcing manufacturers to maintain redundant fractionation capacity across Spain and the United States. Raw material sourcing draws from United States donor centers, Spanish plasma collection networks, and German hyperimmune specialty sites. Single-source vulnerability concentrates in North American donor infrastructure where Grifols and CSL Behring control vertically integrated networks. Distribution runs through specialty pharmacy distributors building direct-to-patient logistics capabilities that bypass traditional hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where plasma collection network control and gene therapy vector manufacturing capacity constitute the decisive upstream levers separating defendable positions from margin erosion.
For Market Incumbents: Extend plasma donor center relationships in the United States Southeast and Midwest to secure raw material access against recombinant protein substitution threats. Retrofit European fractionation assets for EMA MDR batch-level traceability compliance to defend hospital contract renewals. Gene therapy durability readouts represent the primary threat vector requiring chronic replacement manufacturers to demonstrate non-inferior safety profiles against potentially curative alternatives.
For New Entrants and Emerging Players: Direct-to-patient digital pharmacy platforms offer the lowest barrier route into United States homecare administration, bypassing entrenched hospital purchasing committee relationships. Target underpenetrated neonatal screening channels in Italian regional health systems and Spanish Mediterranean populations where latent prevalence pools exceed current diagnosis infrastructure. Partner with academic medical centers in Barcelona and Milan to accelerate liver-directed gene therapy enrollment against established plasma-derived standards.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation for AAV-vector durability trials is the leading indicator that curative modality reimbursement frameworks are crystallizing, shifting capital allocation from chronic replacement manufacturers toward gene therapy developers. Acquisition targets should profile as vector engineering specialists with hepatocyte transduction efficiency patents and academic medical center partnerships in Spain or Italy. Watch EMA MDR compliance cost disclosures from European fractionators as the signal for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | United States donor center density secures raw material access against recombinant substitution threats. |
| Gene Therapy Durability Trial Advancement | AAV-vector hepatocyte transduction data from Spanish academic centers reshapes competitive positioning. |
| EMA MDR Compliance Investment | Batch-level viral safety documentation filters smaller European fractionators from market participation. |
| Homecare Distribution Partnership | Specialty pharmacy direct-to-patient logistics bypass hospital purchasing committee control. |
| Neonatal Screening Program Licensing | State-level genetic testing mandates in United States markets create presymptomatic patient identification. |
Study Parameters
FDA orphan drug filings, EMA centralized procedure submissions, and ClinicalTrials.gov registry data formed the secondary backbone, cross-referenced with primary interviews involving plasma fractionation executives, specialty pharmacy distribution heads, hospital pulmonology procurement leads, and gene therapy clinical investigators. Bottom-up patient volume estimates across United States specialty clinics, German homecare networks, and Spanish academic medical centers were triangulated against top-down manufacturer revenue disclosures and plasma protein pricing benchmarks.
Historical trendline analysis of augmentation therapy volumes and gene therapy enrollment curves informed the projection framework across the analysis window, with segmentation modeling spanning treatment modality, delivery route, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves adjusted for EMA MDR implementation timelines and FDA orphan drug exclusivity periods. Forecast inputs incorporated plasma collection capacity expansion announcements, vector manufacturing scale-up disclosures, and payer reimbursement policy shifts.
The model holds under stable regulatory pathways for plasma-derived products and gene therapy accelerated approvals; deviation in FDA durability standard requirements or EMA viral safety enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Byler Disease Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Asia-Pacific Down Syndrome Market