
 Aviation Adhesives and Sealants Market | 2026-2036
Aviation Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Adhesives and Sealants Market Analysis
AS9100-grade qualification standards are unwinding legacy supply arrangements across the aviation adhesives sector. Huntsman International LLC leverages its aerospace-grade epoxy portfolio to anchor European OEM relationships. Henkel AG & Co. KGaA sustains broad technology coverage across heat-cured and pressure-sensitive platforms. PPG Industries, Inc. dominates the North American MRO channel through certified distributor networks.
Aviation adhesives and sealants are engineered bonding and sealing compounds formulated from epoxy, polyurethane, silicone, or acrylic chemistries, typically cured via thermal, ambient, ultraviolet, or pressure-activated mechanisms to achieve specified shear strength, outgassing limits, and temperature resistance for airframe assembly and protection. These materials serve to replace mechanical fasteners, reduce structural weight, seal pressure boundaries, and electrically isolate avionics compartments across commercial, military, and general aviation platforms. Epoxy formulations occupy the deepest qualification history and capture the largest share of structural airframe bonding, while polyurethane and silicone segments are expanding fastest in interior sealing and exterior weatherproofing applications where flexibility and UV durability outweigh modulus requirements. The technology dimension shows heat-cured systems retaining dominance in primary structure, though room-temperature-cured and UV-cured alternatives are gaining traction in MRO and line-replaceable unit applications where oven access is impractical.
FAA airworthiness standards under 14 CFR Part 25, EASA CS-25 certification requirements, and REACH restrictions on hazardous substance content collectively shape formulation roadmaps, testing protocols, and market access conditions for suppliers serving transatlantic OEM programs. The EU F-Gas Regulation and emerging MEE guidelines in China are adding compliance layers to sealant portfolios with blowing-agent or solvent components. Stakeholders must monitor divergence between FAA and EASA flammability test methods, as harmonization gaps threaten to fragment qualification investments and duplicate certification costs across dual-source supply strategies.
Market Dynamics
AS9100-grade qualification standards are unwinding legacy supply arrangements across the aviation adhesives sector, forcing tier-2 and tier-3 suppliers to rebuild certification portfolios or exit OEM supply chains entirely. This recertification wave is compressing vendor counts while elevating technical barriers for new entrants.
Growth Catalysts
- 14 CFR Part 25 flame-retardant mandates:FAA airworthiness directives on cabin interior materials are accelerating reformulation programs across epoxy and silicone product lines, creating sustained demand for certified alternatives.
- Bonded primary structure assembly:Commercial aviation OEMs are expanding adhesive-intensive joining methods to achieve airframe weight reduction targets, displacing riveted joints in wing and fuselage sections.
- MRO channel expansion:Line-replaceable unit maintenance programs at Dallas-Fort Worth and Singapore Changi hubs are driving consumption of room-temperature-cured sealants where oven access is impractical.
Market Restraints
- Specialty resin supply concentration:Aerospace-grade epoxy precursors depend on a concentrated German and Japanese chemical base, exposing formulators to input cost volatility and allocation risk.
- REACH substance restrictions:ECHA candidate list expansions on isocyanates and certain flame retardants are forcing costly reformulation cycles ahead of sunset dates.
- Dual-certification burden:Divergence between FAA and EASA flammability test methods threatens to fragment qualification investments, duplicating certification costs for transatlantic supply strategies.
Strategic Opportunities
- Urban air mobility platforms:Electric vertical take-off and landing manufacturers in California and Bavaria represent unserved demand for lightweight, rapid-cure bonding systems outside traditional qualification pathways.
- UV-cured MRO applications:Tarmac repair operations are adopting ultraviolet-activated sealants to eliminate thermal curing equipment, opening channel partnerships with mobile service providers.
- EU F-Gas Regulation compliance services:Sealant portfolios with blowing-agent components require reformulation support, creating advisory revenue streams for technical service teams.
Industry Challenges
- AS9100 auditor capacity constraints:Certification body backlogs are extending supplier qualification timelines, delaying new product introductions and contract awards.
- Legacy system integration:Adhesive bonding processes must interface with existing rivet-dominated tooling and workforce skill bases, complicating production line transitions.
- Outgassing test protocol harmonization:Discrepancies between ASTM E595 and ECSS-Q-ST-70-02 standards create uncertainty for suppliers serving both NASA and commercial satellite programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Adhesives and Sealants Market |
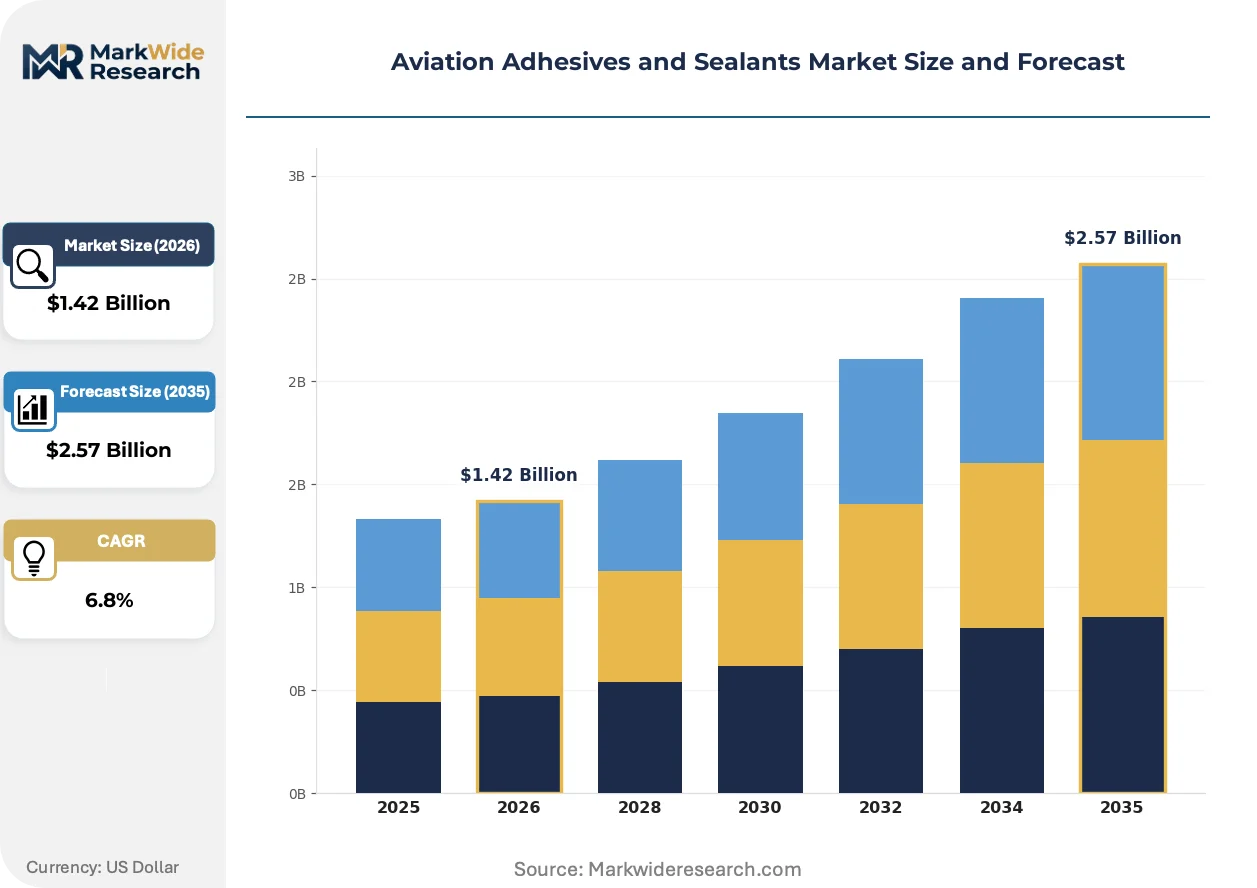
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Interior, Exterior, Structural, Electrical Technology: Heat-Cured, Room Temperature Cured, UV-Cured, Pressure-Sensitive End User: Commercial Aviation, Military Aviation, General Aviation, MRO |
| Companies Covered | Huntsman International LLC, H.B. Fuller Company, PPG Industries, Inc., Illinois Tool Works Inc. (ITW), Arkema S.A. (Bostik), 3M Company, The Dow Chemical Company, Lord Corporation (Parker Hannifin), Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Adhesives and Sealants Market Emerging Trajectories
Formulation chemistry and curing mechanisms are undergoing accelerated evolution as qualification standards tighten and application environments diversify. Three distinct vectors are reshaping competitive positioning and technical roadmaps.
Structural film adhesives with controlled flow characteristics are supplanting paste epoxies in wing-to-fuselage joints at major commercial OEMs. These materials reduce assembly labor hours while maintaining peel strength under cryogenic fuel tank exposure. The shift is compressing demand for traditional two-part mixing systems in primary structure applications.
REACH restrictions on hazardous substance content are forcing systematic elimination of certain brominated flame retardants from interior sealant formulations. ECHA's SVHC candidate list expansions are triggering pre-emptive reformulation investments across European supply chains. Interior panel bonding segments are responding fastest, with several product lines already transitioning to phosphorus-based alternatives.
Airline procurement departments are consolidating adhesive purchasing through airframe OEM specified-bid programs rather than direct MRO channel buying. This shift disintermediates traditional distributor relationships and transfers price negotiation leverage to Boeing and Airbus supply chain teams. The pattern is most visible in North American and Middle Eastern carrier fleets with centralized technical procurement functions.
Aviation Adhesives and Sealants Market Segmentation
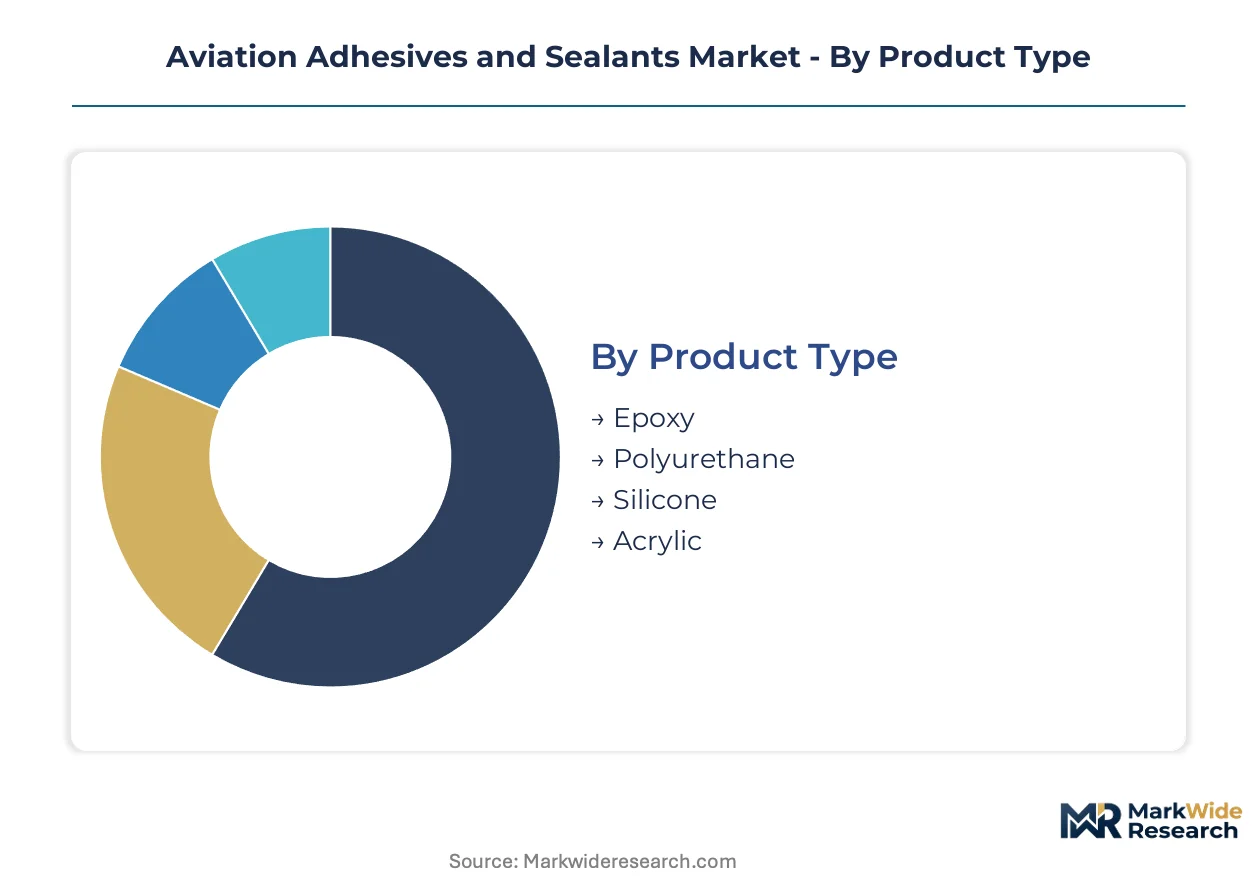
Segmentation in aviation adhesives reveals distinct qualification barriers and substitution dynamics across chemistry families, cure mechanisms, and end-use environments. Each dimension carries unique regulatory exposure and supply chain configuration requirements that shape vendor positioning.
Product Type:
Epoxy formulations face intensifying substitution pressure from polyurethane and silicone alternatives in applications where flexibility requirements override modulus specifications.
- Epoxy:Two-part thermoset systems deliver the highest shear strength and temperature resistance for primary structural bonds. Boeing's bonded wing programs in Washington State and Airbus A350 production in Toulouse concentrate demand for aerospace-grade film and paste variants. REACH restrictions on brominated flame retardants are forcing reformulation cycles across interior-rated product lines.
- Polyurethane:Flexible, moisture-cured sealants dominate exterior weatherproofing and fuel tank sealing where elongation properties exceed 400%. Gulfstream and Bombardier business jet programs in Georgia and Quebec represent concentrated consumption for cabin pressure boundary applications. FAA 14 CFR Part 25 fire resistance mandates are accelerating shifts toward low-smoke formulations.
- Silicone:Temperature-stable from -65°C to 260°C, these formulations seal engine nacelles and avionics compartments. Demand clusters around GE Aviation and Pratt & Whitney engine assembly sites.
- Acrylic:Pressure-sensitive and cyanoacrylate variants serve temporary fixture and rapid repair applications. General aviation MRO channels in Florida and Texas represent primary consumption.
Epoxy anchors the volume base while polyurethane gains share at the steepest rate.
Application:
Cost tier differentiation separates structural applications requiring million-dollar qualification investments from interior segments with faster certification cycles.
- Interior:Panel bonding, decorative laminate attachment, and galley/lavatory sealing demand low-outgassing, flame-retardant formulations. Seating manufacturers in North Carolina and Bavaria drive specification trends. EASA CS-25 flammability test method divergence from FAA protocols is fragmenting qualification requirements for transatlantic suppliers.
- Exterior:Aerodynamic smoothing, antenna sealing, and leading edge protection require UV-stable, rain erosion-resistant elastomers. Airbus Hamburg and Boeing Charleston final assembly lines specify regional supplier bases.
- Structural:Wing-to-fuselage joints, empennage attachments, and cryogenic fuel tank bonds use high-modulus adhesives with 30+ year service life predictions. Qualification to OEM-specific material specifications limits viable suppliers to AS9100-certified formulators with decade-long track records.
- Electrical:Potting compounds and conformal coatings isolate avionics from moisture and electromagnetic interference. Satellite and defense programs add outgassing requirements per ASTM E595.
Structural applications command the highest margins while interior segments expand most quickly amid cabin retrofit cycles.
Technology:
Volume concentration in heat-cured systems is eroding as room-temperature and UV alternatives capture MRO and line maintenance workflows.
- Heat-Cured:Autoclave and oven-cured epoxies achieve full mechanical properties for primary structure. Airbus A320 family production in Hamburg and Tianjin relies on automated dispensing and curing cells. Capital equipment requirements and energy costs constrain adoption outside OEM assembly environments.
- Room Temperature Cured:Two-part systems eliminate thermal infrastructure for field repairs and secondary bonding. Singapore Changi and Dubai International MRO hubs specify these formulations for tarmac operations where oven access is impractical. Working life limitations and humidity sensitivity restrict structural applications.
- UV-Cured:Acrylic and modified epoxy systems cure in seconds under 365nm LED arrays. Emerging adoption in windshield repair and composite patch applications at Southwest Airlines and Lufthansa Technik operations. Depth of cure constraints limit use to thin-section bonds.
- Pressure-Sensitive:Film and tape formats enable rapid fixture and temporary positioning during assembly. Boeing 787 program in Everett specified extensive PSA usage for stringer bonding before final cure.
Heat-cured technology retains the largest installed base while UV-cured alternatives climb the fastest on mobile maintenance adoption.
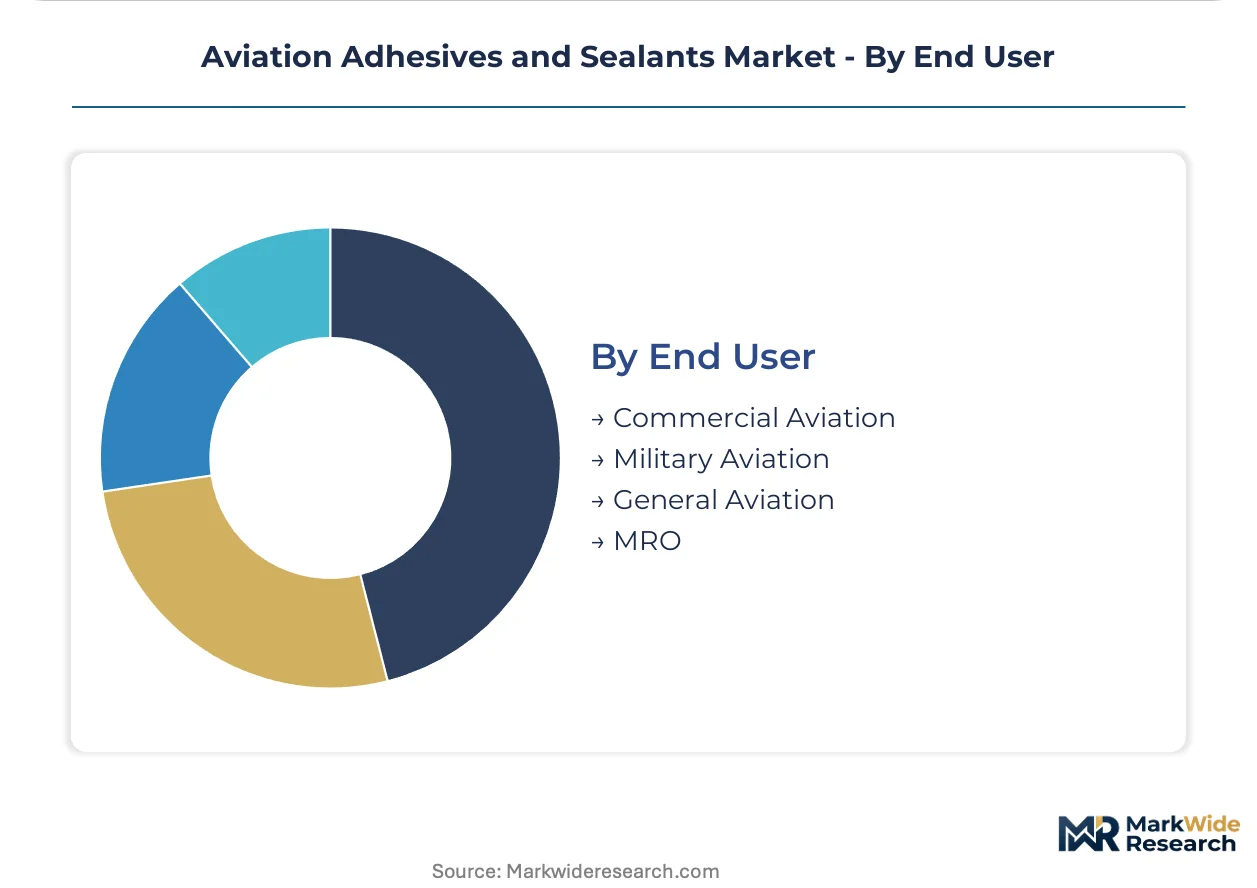
End User:
Customer type determines procurement channel structure, with OEM specified-bid programs displacing direct MRO purchasing across major carrier fleets.
- Commercial Aviation:Boeing and Airbus supply chain teams negotiate multi-year adhesive contracts covering their respective carrier customer bases. Airframe OEMs specify qualified products, transferring price leverage from airlines to tier-1 distributors. Single-aisle production rate recovery in Renton and Toulouse drives volume.
- Military Aviation:Lockheed Martin F-35 and B-21 programs impose ITAR-controlled supply chains with domestic sourcing mandates. Defense-qualified products carry 40-60% price premiums over commercial equivalents.
- General Aviation:Cirrus, Textron, and Piper airframe manufacturers specify lower-volume, broader-spectrum products. Direct procurement through distributor networks persists in this fragmented segment.
- MRO:Line-replaceable unit maintenance at Delta TechOps in Atlanta and ST Engineering in Singapore consumes room-temperature-cured sealants. Consolidation of airline procurement functions is compressing direct channel volumes.
Commercial aviation anchors revenue concentration while MRO channels face procurement restructuring pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty resin supply chains cluster around German chemical conglomerates and Japanese industrial groups, creating input dependencies that shape regional manufacturing footprints. Formulation facilities locate near final assembly sites to minimize logistics risks for AS9100-certified products. Regulatory divergence between FAA and EASA jurisdictions fragments qualification investments across transatlantic supply strategies.
United States
Boeing's final assembly lines in Everett and Charleston drive concentrated demand for structural film adhesives. FAA 14 CFR Part 25 flame-retardant mandates accelerate reformulation cycles across interior-rated product lines. The Dallas-Fort Worth and Atlanta MRO hubs anchor North American consumption of room-temperature-cured sealants for line maintenance operations.
Germany
Airbus A320 family production in Hamburg and A350 assembly in Toulouse (with German supply chain integration) sustain epoxy precursor demand. ECHA REACH restrictions on isocyanates and brominated flame retardants force systematic reformulation investments. The Rhine-Ruhr chemical corridor hosts aerospace-grade resin production serving tier-1 formulators across Europe.
China
COMAC C919 production ramp-up in Shanghai and Tianjin Airbus final assembly lines expand bonded assembly adoption. MEE guidelines on volatile organic compound emissions add compliance layers to sealant portfolios with solvent components. The Yangtze River Delta concentration of aviation manufacturing clusters drives localization requirements for adhesive suppliers.
France
Airbus headquarters in Toulouse and Safran engine assembly sites concentrate demand for high-temperature silicone formulations. EASA CS-25 certification requirements shape formulation roadmaps distinct from FAA protocols. The Occitanie aerospace cluster sustains specialized distributor networks for OEM-specified adhesive procurement.
Japan
Mitsubishi Heavy Industries and Subaru Corporation defense programs impose domestic sourcing mandates for ITAR-controlled supply chains. METI industrial standards align with ASTM outgassing protocols for satellite and commercial aviation dual-use applications. The Nagoya aerospace manufacturing corridor anchors polyurethane sealant demand for regional jet programs.
Aviation Adhesives and Sealants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the aviation adhesives sector. AS9100-certified formulators with decade-long OEM track records command structural applications, while regional distributors compete on logistics proximity for MRO channels. The market structure tiers into qualification-heavy primary structure suppliers, flexible formulation specialists for interior segments, and scale-driven commodity producers. Consolidation pressure operates through AS9100 recertification waves and OEM-specified bid programs that compress vendor counts.
Among diversified chemical conglomerates, Huntsman International LLC and Henkel AG & Co. KGaA exemplify technology-coverage archetypes spanning heat-cured and pressure-sensitive platforms. PPG Industries, Inc. occupies a position within North American channel-dominant players. These three represent distinct strategic postures: European OEM relationship anchoring, broad chemistry portfolio maintenance, and certified distributor network control.
| Leading Market Players |
|---|
| Huntsman International LLC |
| H.B. Fuller Company |
| PPG Industries, Inc. |
| Illinois Tool Works Inc. (ITW) |
| Arkema S.A. (Bostik) |
| 3M Company |
| The Dow Chemical Company |
| Lord Corporation (Parker Hannifin) |
| Henkel AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Ninety-day qualification timelines for AS9100-certified formulations compress pricing power toward German and Japanese resin suppliers while elevating spot premiums for aerospace-grade epoxy precursors. Boeing and Airbus procurement teams exploit this concentration through multi-year specified-bid programs that transfer cost volatility risk to tier-1 formulators.
Pricing Analysis
14 CFR Part 25 flame-retardant mandates dictate the pricing tier structure across interior-rated product lines, forcing reformulation investments that stratify pricing across premium, standard, and economy certification levels. Price differentiation hinges on EASA dual-certification status and volume scale commitments to OEM supply chain teams. Cost compression in standard-grade polyurethane sealants is intensifying because REACH restrictions on isocyanates are accelerating raw material substitution cycles. General aviation MRO channels exhibit highest price sensitivity due to fragmented procurement and direct distributor relationships, while structural film adhesive buyers at Boeing and Airbus demonstrate lowest sensitivity given million-dollar qualification barriers.
Supply Chain Analysis
Germany and Japan anchor aerospace-grade epoxy precursor production, with the Rhine-Ruhr chemical corridor and Nagoya industrial belt feeding tier-1 formulators across three continents. Specialty resin supply draws from concentrated German chemical conglomerates and Japanese industrial groups, creating input dependencies that expose formulators to allocation risk during supply shocks. Single-source vulnerability pervades heat-cured system catalysts sourced from Japanese suppliers. Distribution runs through AS9100-certified facilities located adjacent to Boeing Everett, Airbus Toulouse, and COMAC Shanghai final assembly lines to minimize logistics risks for qualified products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation adhesives procurement is consolidating through platform-economics logic as Boeing and Airbus specified-bid programs disintermediate traditional distributor relationships and transfer price-setting power to airframe OEM supply chain teams.
For Market Incumbents: Fortify AS9100 certification portfolios against auditor capacity constraints that extend qualification timelines and delay contract awards. Deepen backward integration into aerospace-grade epoxy precursor production to offset German and Japanese supply concentration. Prioritize EASA-FAA harmonization advocacy to reduce dual-certification cost duplication threatening transatlantic supply strategies.
For New Entrants and Emerging Players: Lead with UV-cured formulations for mobile MRO applications at Singapore Changi and Dallas-Fort Worth hubs where tarmac repair operations seek rapid-cure alternatives without thermal infrastructure. Target urban air mobility manufacturers in California and Bavaria outside traditional qualification pathways. Pursue channel partnerships with mobile service providers rather than OEM direct qualification.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with aviation adhesives divisions lacking AS9100 certification depth or European OEM relationships. Long-term viability centers on qualification moats and OEM-specified bid program participation. Monitor divergence between FAA and EASA flammability test methods as signal for fragmentation risk or harmonization opportunity. Recalibration cycles align with AS9100 recertification waves and REACH substance restriction sunset dates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Precursors | Reduces exposure to German and Japanese supply concentration and allocation risk. |
| Dual-Certification Investment | Captures transatlantic OEM programs amid FAA-EASA harmonization gaps. |
| UV-Cured Formulation Development | Addresses MRO channel demand at Singapore Changi and Dallas-Fort Worth hubs. |
| Urban Air Mobility Partnership | Opens unserved demand outside traditional Boeing and Airbus qualification pathways. |
| REACH Compliance Service Expansion | Creates advisory revenue streams as ECHA restrictions force pre-emptive reformulation. |
Methodological Framework
Cross-validation between primary interviews with supply chain directors at Boeing and Airbus, technical procurement leads at tier-1 distributors, and plant managers at German and Japanese resin producers anchors the qualitative findings. Secondary validation draws from FAA 14 CFR Part 25 filings, EASA CS-25 certification databases, ECHA REACH substance restriction updates, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up triangulation across chemistry families, cure mechanisms, and end-use applications converges with top-down demand modeling from commercial aviation production rates and MRO fleet data.
Sensitivity analysis around single-aisle production rate recovery, REACH sunset date acceleration, and UV-cured technology adoption curves informs the analytical framework across the projection horizon. Segmentation dimensions include chemistry family, cure mechanism technology, application environment, and end-user procurement channel structure. CAGRs derive from installed base erosion rates for riveted joints versus adhesive bonding adoption curves, calibrated against Boeing and Airbus delivery forecasts. Industry-specific inputs encompass outgassing test protocol harmonization progress and MEE guideline implementation timelines in China.
Forecasts assume regulatory continuity in FAA, EASA, and REACH regimes; material policy shifts would require re-modeling. Specific risk factors include AS9100 auditor capacity constraints extending qualification timelines, specialty resin supply allocation shocks, and divergence between ASTM E595 and ECSS-Q-ST-70-02 outgassing standards fragmenting satellite program access. Recalibration cycles align with material shifts in OEM production rates, regulatory sunset dates, and alternative cure technology adoption inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Europe Reactive Adhesives Market