
 Industrial Fryers Market | 2026-2036
Industrial Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Fryers Market Foresight
The gap between premium and commodity tiers is widening. Heat and Control, Inc. leverages its vertical integration into oil filtration and conveyor systems to command premium positioning in continuous fryer installations. Middleby Corporation anchors its portfolio through broad manufacturing scale across multiple protein and snack categories. Henny Penny competes on brand strength in pressure frying, a sub-area where it has sustained technology leadership for decades.
Industrial fryers are closed-vessel thermal processing systems that heat cooking oil or alternative thermal media to temperatures between 160°C and 200°C for submerged or sprayed food treatment, with primary purpose being uniform moisture reduction and Maillard browning in high-volume production environments. Continuous fryers dominate volume shipments due to throughput advantages in potato chip and extruded snack lines, while batch fryers retain margin pools in craft-scale operations and product development kitchens. Electric technology segments are gaining fastest in regions with aggressive decarbonization mandates, though gas-fired systems still occupy the majority of installed base in North American protein processing.
The U.S. FDA and OSHA shape equipment specifications through food safety and worker protection standards, while the EU F-Gas Regulation and REACH directly constrain refrigerant and coating chemistries used in frying system auxiliaries. Germany's KBA and France's ANSM enforce national variations on CE-marked equipment that extend compliance burdens for cross-border suppliers. Stakeholders must monitor how evolving carbon border adjustments and energy efficiency labeling schemes will reshape total cost of ownership calculations for frying line investments.
Market Dynamics
Energy transition mandates and refrigerant phase-downs are compressing equipment replacement cycles as manufacturers face simultaneous pressure to decarbonize thermal systems while maintaining throughput on legacy frying lines.
Growth Catalysts
- Clean-label snack specifications:Snack food producers are retrofitting continuous fryers with oil filtration and reduced-oil spray systems to meet retailer clean-label requirements without sacrificing production velocity.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in frying system auxiliaries is accelerating replacement demand for compliant heat pump and thermal management configurations.
- Automated oil management:Real-time oil quality monitoring and automated top-up systems are reducing labor inputs and extending fryer campaign lengths in high-volume potato processing.
Market Restraints
- Stainless steel input volatility:Fryer vessel fabrication depends on austenitic stainless grades whose price swings compress margin visibility for equipment fabricators.
- Specialized burner assembly concentration:Precision gas burner systems for high-BTU frying applications concentrate among a limited supplier base in Germany and Italy.
- Electric infrastructure gaps:Grid capacity limitations in older food processing districts constrain the feasibility of electric fryer conversions despite carbon reduction targets.
Strategic Opportunities
- Plant-based protein expansion:Meat analog production requires modified frying parameters for texture development, opening specification windows for fryer vendors with protein expertise.
- India FSSAI modernization:Updated food safety codes for packaged snacks are driving first-time automated fryer adoption among domestic savory snack manufacturers.
- Predictive maintenance convergence:Integration of thermal imaging with fryer control systems enables condition-based maintenance contracts that shift revenue toward recurring service streams.
Industry Challenges
- Controls engineering scarcity:Programming talent for legacy PLC-to-IoT fryer retrofits remains concentrated among a narrow contractor base in industrial automation hubs.
- CE-MDR dual certification:Fryers with integrated robotics for loading and extraction now require parallel conformity assessments under machinery and medical device regulations where food-contact applications overlap.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Fryers Market |
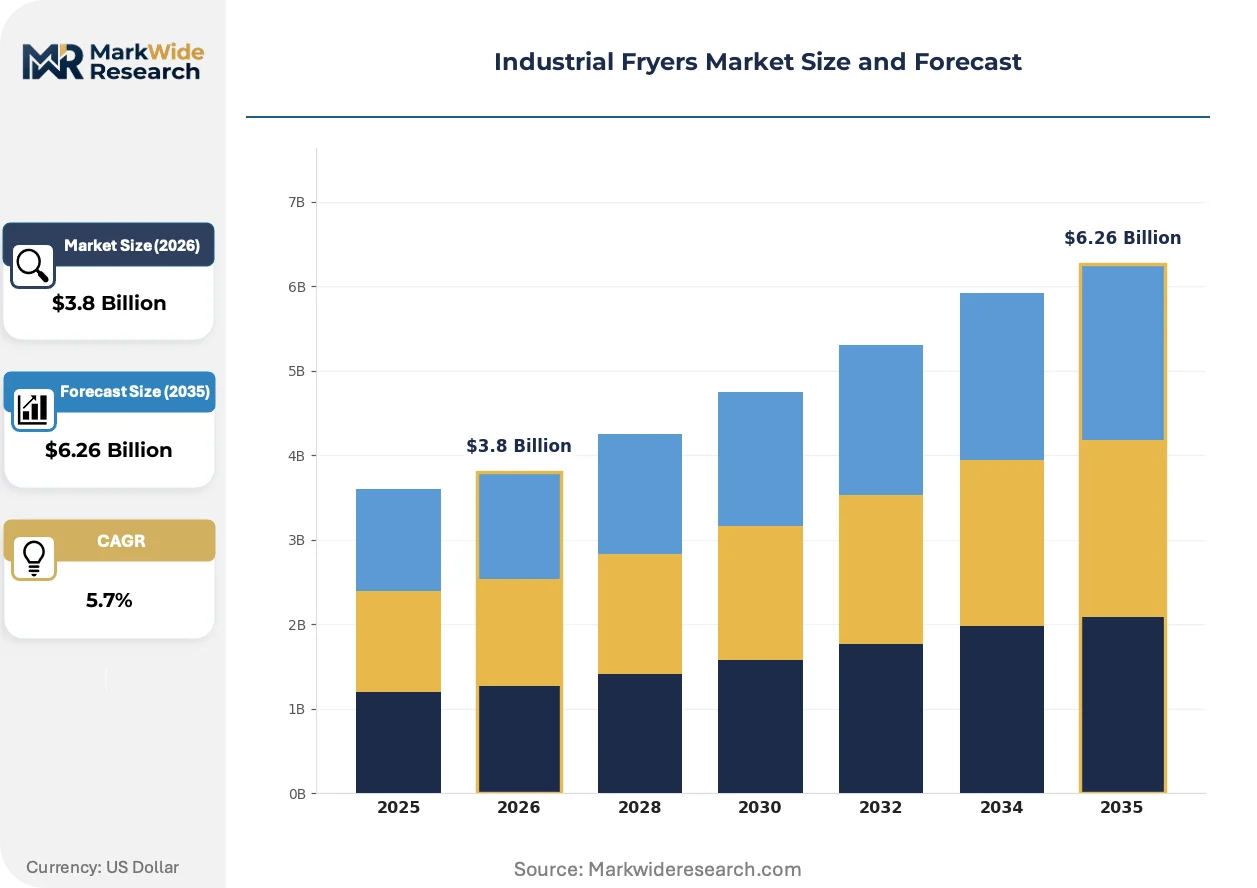
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Fryers, Continuous Fryers, Multi-Purpose Fryers, Degreasing Systems End User: Food Processing Plants, Snack Food Manufacturers, Restaurants, Catering Services Technology: Convection, Infrared, Electric, Gas Application: Frying, Blanching, Cooking, Roasting |
| Companies Covered | Heat and Control, Inc., Middleby Corporation, Henny Penny, JBT Corporation, TNA Australia Solutions Pty Ltd, Frymaster LLC, Electrolux Professional, Ali Group, Welbilt Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Fryers Market Shifts & Advancements
Thermal processing automation and refrigerant chemistry constraints are forcing simultaneous upgrades to fryer hardware and auxiliary systems. Equipment vendors must now bundle thermal efficiency, emissions compliance, and data connectivity into single capital proposals.
Closed-loop oil filtration with membrane separation is automating the removal of particulate and polar compounds during frying campaigns. Potato chip manufacturers in the Netherlands and Belgium are deploying these systems to extend oil life by forty percent or more. The technology is automating what had been manual sampling and batch replacement decisions, compressing the labor component of fryer operations.
The EU F-Gas Regulation's stepped reductions in global warming potential limits are banning common refrigerants used in fryer heat recovery and dehumidification units. Equipment suppliers are engineering auxiliary thermal loops using ammonia or CO2 transcritical cycles to maintain compliance. Protein processors in Germany face the steepest retrofit timelines given their installed base of aging heat pump configurations.
Outcome-based service agreements are displacing traditional parts-and-labor maintenance contracts for continuous fryer installations. Large snack manufacturers in the United States are negotiating uptime guarantees that bundle preventive maintenance, oil management, and remote diagnostics into per-ton processing fees. This restructuring concentrates vendor risk while locking in multi-year relationships and reducing buyer capex volatility.
Industrial Fryers Market Segmentation
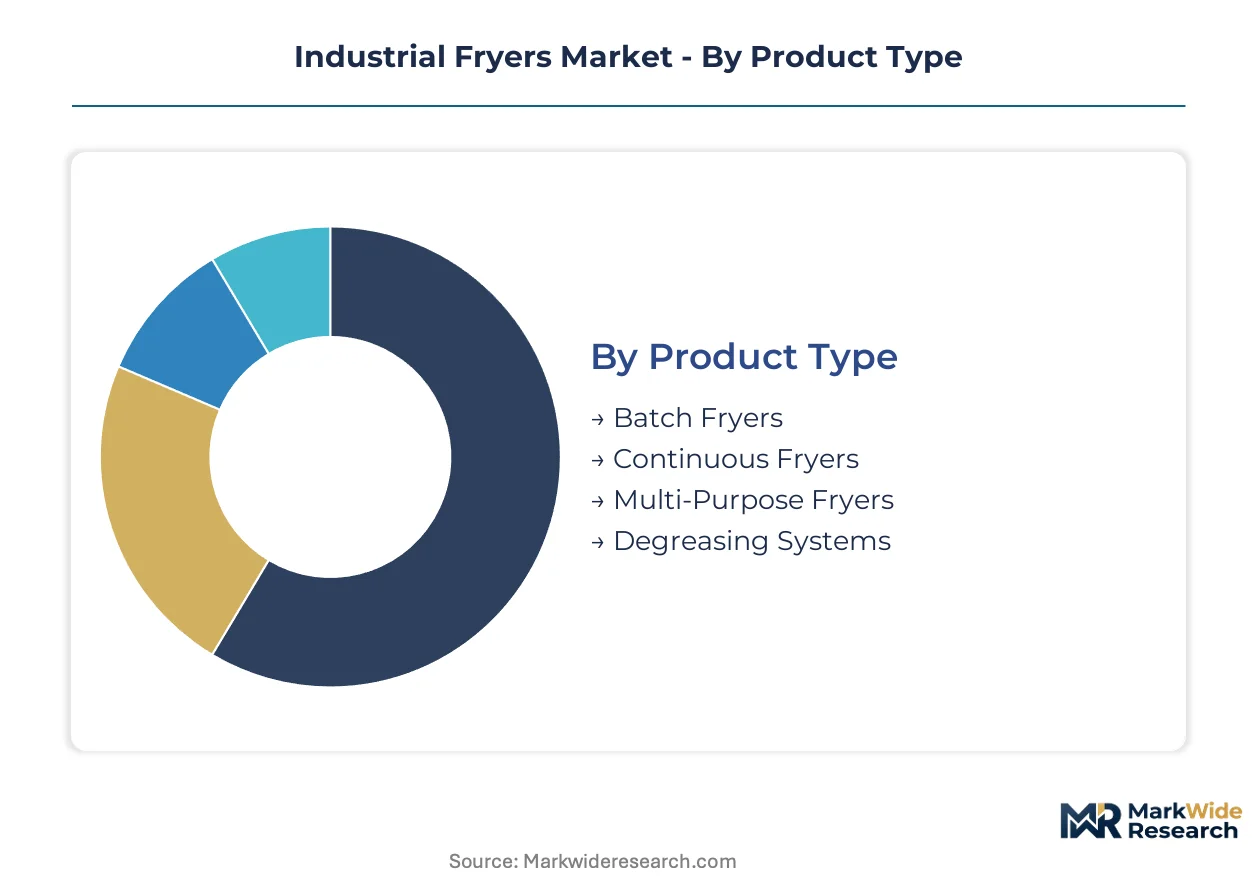
Industrial fryer segmentation reveals how equipment specifications align with thermal processing intensity, throughput requirements, and regulatory compliance burdens across protein, snack, and prepared food operations.
Product Type:
Equipment architecture determines capital deployment patterns and operating economics across high-volume continuous lines versus flexible batch configurations.
- Continuous Fryers:Submerged conveyor systems process 2,000–10,000 kg per hour of potato chips, extruded snacks, and battered proteins. Demand concentrates in the Netherlands and Belgium where potato processors deploy membrane filtration-integrated lines to extend oil life. The EU F-Gas Regulation accelerates replacement of aging heat pump auxiliaries in these installations.
- Batch Fryers:Vessel-based systems with basket or rack loading accommodate product changeovers every 15–30 minutes. Craft-scale snack producers in Germany retrofit these for clean-label trial runs and limited-edition product launches. Labor intensity limits expansion beyond mid-scale operations.
- Multi-Purpose Fryers:Modular designs switch between frying, blanching, and roasting modes through programmable thermal profiles.
- Degreasing Systems:Post-fry centrifugal or air-knife modules reduce surface oil content 15–40 percent for reduced-fat product specifications.
Continuous Fryers leads on scale; Multi-Purpose Fryers leads on momentum.
End User:
Customer scale and product mix dictate automation depth, with snack manufacturers driving standardization while foodservice operators prioritize flexibility.
- Snack Food Manufacturers:Dedicated lines for potato chips, tortilla chips, and extruded pellets require 99.5 percent uptime guarantees. Real-time oil quality monitoring and automated top-up systems reduce labor inputs. U.S. FDA PHF temperature controls shape control system specifications.
- Food Processing Plants:Multi-product facilities processing breaded poultry, seafood, and vegetable tempura demand rapid changeover capability. Protein processors in Germany face compressed replacement cycles from simultaneous energy transition mandates and refrigerant phase-downs.
- Restaurants:High-turnover pressure frying and open-pot configurations dominate quick-service and casual dining installations.
- Catering Services:Mobile and event-scale batch units emphasize portability and rapid heat recovery.
Snack Food Manufacturers leads on scale; Food Processing Plants leads on momentum.
Technology:
Thermal delivery mechanisms balance energy cost, emissions compliance, and browning control precision across regional grid conditions.
- Electric:Resistance and induction heating systems achieve temperature stability within ±2°C for delicate protein coatings. Aggressive decarbonization mandates in Germany and France accelerate adoption despite grid capacity constraints in older industrial districts.
- Gas:Direct-fired burner assemblies deliver 200,000–500,000 BTU for high-moisture product loading. North American protein processing retains majority installed base due to lower thermal energy costs and existing infrastructure.
- Convection:Forced-air circulation reduces oil volume requirements 20–30 percent versus submerged frying.
- Infrared:Radiant heat sources target surface moisture reduction without oil submersion for pre-cooked applications.
Gas leads on scale; Electric leads on momentum.
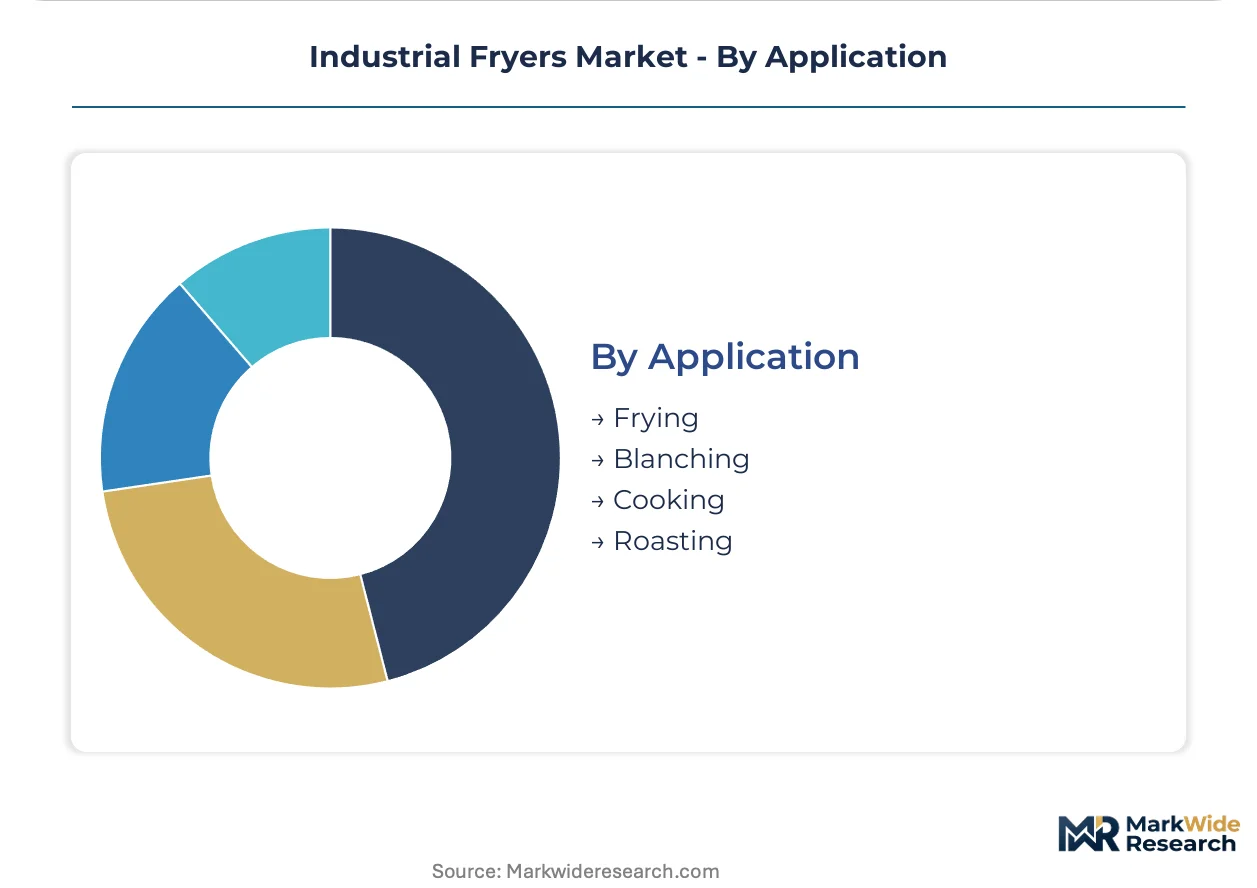
Application:
Process objectives determine oil chemistry management, residence time control, and downstream handling requirements.
- Frying:Submerged oil contact at 160°C–200°C achieves Maillard browning and moisture reduction for shelf-stable snacks. Closed-loop oil filtration with membrane separation extends campaign lengths 40 percent in Dutch potato chip operations.
- Blanching:Short-duration oil or steam exposure deactivates enzymes and reduces surface moisture before final frying. Pre-processing lines in Belgian frozen potato facilities integrate these stages with continuous fryers.
- Cooking:Oil-based thermal treatment for fully prepared proteins and starches requiring internal temperature verification.
- Roasting:Lower-temperature oil or air circulation for nut and seed processing with minimal color development.
Frying leads on scale; Blanching leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retrofit wave for energy-efficient continuous frying systems contrasts with India's first-time automation surge driven by modernized food safety codes.
United States
Snack food manufacturers in the Midwest and Southeast are expanding automated frying capacity to meet clean-label specifications. The FDA's updated PHF temperature controls reshape equipment specifications for potato chip and extruded snack lines. Chicago-area processing clusters deploy real-time oil quality monitoring to extend fryer campaign lengths.
Germany
Industrial bakeries and savory snack producers face compressed replacement cycles from simultaneous energy transition mandates and refrigerant phase-downs. The KBA enforces national variations on CE-marked equipment that extend compliance burdens for cross-border suppliers. Bavarian protein processors retrofit facilities with ammonia-based heat pump configurations to meet EU F-Gas Regulation timelines.
Netherlands
Potato chip manufacturers deploy membrane filtration-integrated lines to extend oil life by forty percent or more. REACH constraints directly affect coating chemistries used in frying system auxiliaries. Processing clusters around Rotterdam and the northern agricultural regions automate oil sampling decisions that previously required manual intervention.
India
Domestic savory snack manufacturers drive first-time automated fryer adoption as FSSAI modernizes packaged food safety codes. The country's central food regulator tightens enforcement on temperature control documentation for high-volume frying operations. Maharashtra and Gujarat-based producers upgrade from batch configurations to continuous systems for potato chip and namkeen lines.
Belgium
Frozen potato facilities integrate blanching stages with continuous fryers for pre-processing efficiency. ECHA chemical registrations constrain auxiliary system materials selection. Flemish processing plants near the Dutch border pioneer closed-loop oil filtration with automated polar compound removal during extended frying campaigns.
Industrial Fryers Market Competitive Landscape
Top-tier vendors anchor premium continuous fryer installations with integrated filtration and conveyor systems, while mid-scale fabricators compete on batch equipment flexibility for craft-scale operations. The vendor base stratifies across three archetypes: full-line automation specialists, pressure frying technology leaders, and regional batch equipment fabricators. M&A activity concentrates among thermal processing automation assets, with strategic partnerships emerging around predictive maintenance and IoT control retrofits.
Within the full-line automation tier, Heat and Control, Inc. and Middleby Corporation exemplify divergent scale strategies. The California-based Heat and Control occupies a position tied to upstream control over oil filtration and conveyor integration. Middleby Corporation, a publicly traded U.S. entity, represents portfolio breadth across multiple protein and snack categories through manufacturing scale. Henny Penny, an Ohio-based private company, anchors the pressure frying specialization vector where technology leadership has concentrated for decades. These three entities collectively illustrate how geographic origin and corporate structure map to competitive positioning in thermal processing equipment.
| Leading Market Players |
|---|
| Heat and Control, Inc. |
| Middleby Corporation |
| Henny Penny |
| JBT Corporation |
| TNA Australia Solutions Pty Ltd |
| Frymaster LLC |
| Electrolux Professional |
| Ali Group |
| Welbilt Inc |
| Others |
Supply & Pricing Matrix
Controls engineering talent concentration in Stuttgart and Milan amplifies labor-cost differentials between premium continuous fryer installations and standard batch configurations. Stainless steel fabrication clusters in northern Italy and the German Ruhr region feed tiered equipment pricing that separates membrane-filtration-integrated lines from basic vessel systems.
Pricing Analysis
Bundled service agreements covering predictive maintenance and oil management command per-ton processing fees, while unbundled equipment-only transactions dominate mid-scale craft operations. Three-tier pricing structure across premium, standard, and economy levels separates Heat and Control's integrated filtration-conveyor systems from regional batch fabricators. Cost compression in standard-tier gas-fired equipment intensifies because of burner assembly supplier concentration in Germany and Italy. Snack food manufacturers with 99.5 percent uptime requirements show least price sensitivity; emerging Indian savory producers retrofitting from manual batch operations exhibit highest.
Supply Chain Analysis
Workforce availability constraints in Bavaria and Lombardy extend lead times for precision burner system integration. Supply concentrates in Germany, Italy, and the United States for specialized thermal components. Vessel fabrication draws from austenitic stainless grades sourced from European mills; refrigerant chemistry for heat pump auxiliaries hinges on ammonia and CO2 transcritical cycle suppliers. Single-source vulnerability runs through German precision burner assemblers for high-BTU protein applications. Distribution runs through OEM-direct channels for large continuous installations and regional distributor networks for batch equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial fryers market reads as a late-cycle quality story justified by snack manufacturers' specification shift toward clean-label compliance and extended oil-life automation.
For Market Incumbents: Anchor premium positioning through captive supply of membrane filtration modules and conveyor integration systems. Deepen backward integration into oil quality sensor manufacturing to defend against emerging IoT-native control vendors. Expand ammonia-based heat pump service capacity in Germany ahead of EU F-Gas Regulation enforcement timelines.
For New Entrants and Emerging Players: Capture specification windows in Indian savory snack automation where FSSAI modernization drives first-time continuous fryer adoption. Target Maharashtra and Gujarat processing clusters with modular electric configurations that bypass gas infrastructure constraints. Lead with predictive maintenance software subscriptions rather than equipment margin extraction.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional batch fabricators with transferable craft-scale expertise. The five-to-ten year viability framing favors vendors with protein analog texture-development capabilities. Target acquisition profile centers on thermal imaging integration specialists and ammonia refrigeration engineering teams. Watch for inflection in carbon border adjustment implementation across European food processing imports.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oil Filtration | Captive membrane module production locks in premium continuous fryer margins against commodity competitors. |
| Ammonia Heat Pump Retrofit Service Buildout | EU F-Gas Regulation compliance deadlines in Germany compress replacement cycle capture windows. |
| Predictive Maintenance Platform Launch | Outcome-based uptime guarantees shift revenue toward recurring per-ton processing fees in snack manufacturing. |
| India Market Entry via Modular Electric Systems | FSSAI enforcement on temperature documentation accelerates first-time automation in Maharashtra processing clusters. |
| Protein Analog Frying Parameter Development | Meat analog texture specifications open new specification windows for vendors with thermal profile expertise. |
Research Methodology
Multiple input streams — equipment shipment databases, regulatory filing analysis, and plant engineering interviews — were reconciled to construct market estimates. Primary conversations with maintenance directors at potato processing facilities, OEM procurement teams in protein operations, aftermarket service heads, and plant engineers in snack manufacturing were validated against secondary sources including FDA PHF guidance documents, EU F-Gas Regulation implementation notices, and REACH chemical registration databases. Bottom-up triangulation across equipment vendor sales channels and top-down validation from food processing capital expenditure surveys anchored volume and value estimates.
Historical shipment patterns were cross-referenced against panel input from thermal processing automation specialists to project segment trajectories across the analysis window. The analytical framework modeled product type, end user scale, thermal delivery technology, and application intensity dimensions. CAGRs were derived from equipment replacement cycle compression analysis and energy transition mandate timelines. Forecast inputs incorporated stainless steel price volatility indices and grid capacity expansion schedules in older industrial districts.
Underlying measurement precision varies by segment; continuous fryer installations in the Netherlands and Belgium carry tighter precision than emerging market batch retrofit estimates. Forecasts reflect assumptions on refrigerant phase-down enforcement consistency and carbon border adjustment implementation scope. Material deviation in EU F-Gas Regulation timelines or stainless input cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Industrial Food Milling Machine Market