
 Food Away from Home Market | 2026-2036
Food Away from Home Market Size, Share, and Industry Trends Forecast 2026-2036
Food Away from Home Market Analysis
China's commercial kitchen infrastructure build-out is fragmenting as local and international operators compete for prime real estate in dense urban corridors. McDonald's leverages its supply chain scale to secure cost advantages across tier-two and tier-three cities. Starbucks Corporation anchors its premium positioning through localized menu innovation and experiential store formats. Compass Group PLC specializes in institutional contract catering, sustaining margins through long-term corporate and education partnerships.
Food away from home encompasses all prepared meals and beverages consumed outside residential settings, spanning commercial establishments from quick-service counters to full-service restaurants with standardized food safety protocols, temperature-controlled supply chains, and portion-controlled production workflows designed for immediate consumption. Fast food and casual dining segments dominate transaction volume, though fine dining captures disproportionate margin pools through experiential pricing and wine program attach rates. Delivery mode stratification reveals catering as the most underpenetrated channel, while takeout and third-party delivery platforms reshape labor allocation and real estate footprints across operator portfolios.
FDA Food Code enforcement and state-level health department inspections shape operational compliance costs and kitchen design standards across the United States. The EU Green Deal's packaging waste directives and F-Gas refrigeration regulations in Europe mandate equipment retrofits and sustainable material transitions. China's SAMR food safety traceability requirements and NMPA-related nutritional labeling standards tighten market access for non-compliant operators. Stakeholders must monitor regulatory divergence across jurisdictions while calibrating capital deployment between dine-in experience upgrades and off-premise fulfillment infrastructure.
Market Dynamics
Third-party delivery platform economics are compressing operator margins while simultaneously expanding addressable demand, forcing a fundamental recalibration of kitchen design toward off-premise fulfillment capacity.
Growth Catalysts
- Urban density premiums:China's tier-one cities generate outsized transaction volumes as commuters trade meal preparation time for convenience-oriented formats. SAMR food safety traceability mandates accelerate consolidation among compliant operators.
- Digital ordering infrastructure:Quick-service chains deploy proprietary mobile platforms to capture first-party customer data and reduce aggregator commission exposure. Southeast Asian markets show particular receptivity to app-based pre-ordering.
- FDA Food Code harmonization:Standardized kitchen sanitation protocols reduce compliance friction for multi-state US operators, lowering barriers to geographic expansion within the domestic market.
Market Restraints
- Labor cost escalation:Minimum wage compression and benefits mandates in California and New York constrain unit-level profitability for full-service formats dependent on tipped compensation structures.
- Real estate concentration:Prime urban corridor availability tightens as institutional investors acquire food-service-capable properties, elevating rent burdens for independent operators in London, Shanghai, and Manhattan.
- Refrigeration retrofit mandates:EU F-Gas regulations phase down hydrofluorocarbon-dependent equipment, imposing capital-intensive transitions for European operators with legacy cold-chain infrastructure.
Strategic Opportunities
- Catering channel underpenetration:Corporate and institutional contract segments retain fragmented supply structures, creating white space for scaled operators with compliance documentation capabilities.
- Experiential format innovation:Premium operators invest in theatrical kitchen visibility and localized menu engineering to justify price positioning resistant to delivery commoditization.
- Packaging waste directives:EU Green Deal single-use plastic restrictions accelerate demand for compostable and reusable container systems, favoring suppliers with certified circular material streams.
Industry Challenges
- Culinary workforce pipeline:Line-cook and kitchen-manager talent scarcity intensifies as vocational training program enrollment lags sector expansion in the United States and United Kingdom.
- Aggregator dependency:Third-party platform commission structures extract 15-30 percent of order value, eroding operator economics without commensurate customer acquisition cost reduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Away from Home Market |
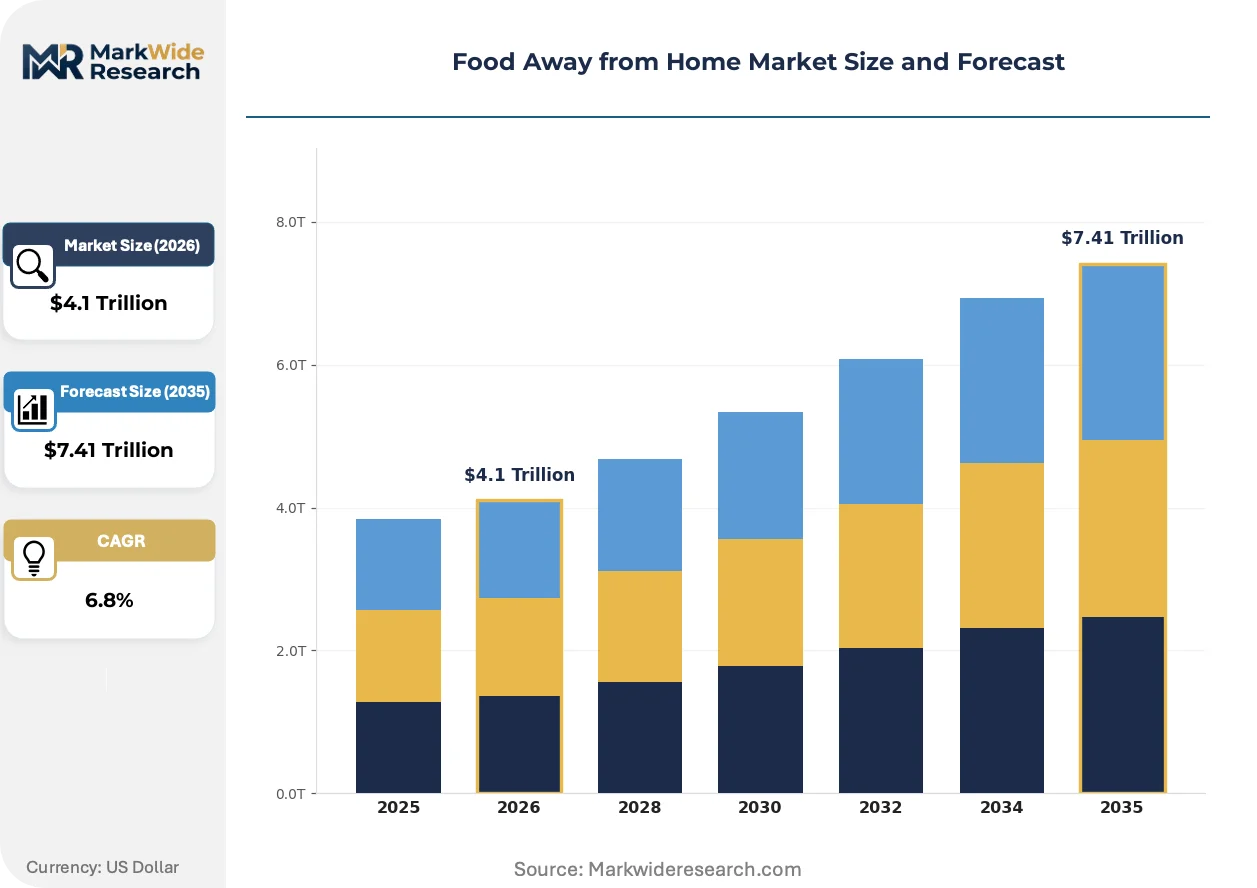
| Market Size in 2026 | $4.1 Trillion |
| Market Size in 2035 | $7.41 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Casual Dining, Fine Dining, Food Trucks Customer Type: Families, Millennials, Business Travelers, Tourists Menu Type: Vegetarian, Vegan, Gluten-Free, Organic Delivery Mode: Takeout, Dine-in, Delivery, Catering |
| Companies Covered | McDonald's, Starbucks Corporation, Compass Group PLC, Sodexo, Aramark, Subway IP LLC, Darden Concepts Inc., Chipotle Mexican Grill, Yum! Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Away from Home Market Emerging Trajectories
Automation and regulatory stringency are converging to reshape kitchen operations, customer interface design, and supply chain transparency requirements across food-away-from-home formats.
Robotic food preparation systems are rendering obsolete manual assembly stations in high-volume quick-service environments. Chains with standardized menu architectures deploy flippy-grill automation and beverage-dispensing robotics to reduce hourly labor requirements. These installations compress kitchen footprints while enabling 24-hour operational windows previously uneconomical under human staffing models.
EU Green Deal packaging waste directives mandate extended producer responsibility frameworks for food-service containers and utensils. Operators face material transition costs as compostable alternatives command price premiums over conventional petroleum-based disposables. Full-service formats in Germany and France accelerate reusable container deposit schemes to preempt regulatory penalties.
Urban consumers in Shanghai, Beijing, and Shenzhen demonstrate pronounced preference for convenience-maximizing meal solutions over traditional dine-in occasions. This behavioral pivot elevates ghost kitchen and delivery-only format viability while compressing demand for conventional restaurant square footage. Premium operators respond with smaller-format pickup counters and enhanced mobile order-ahead functionality.
Food Away from Home Market Segmentation
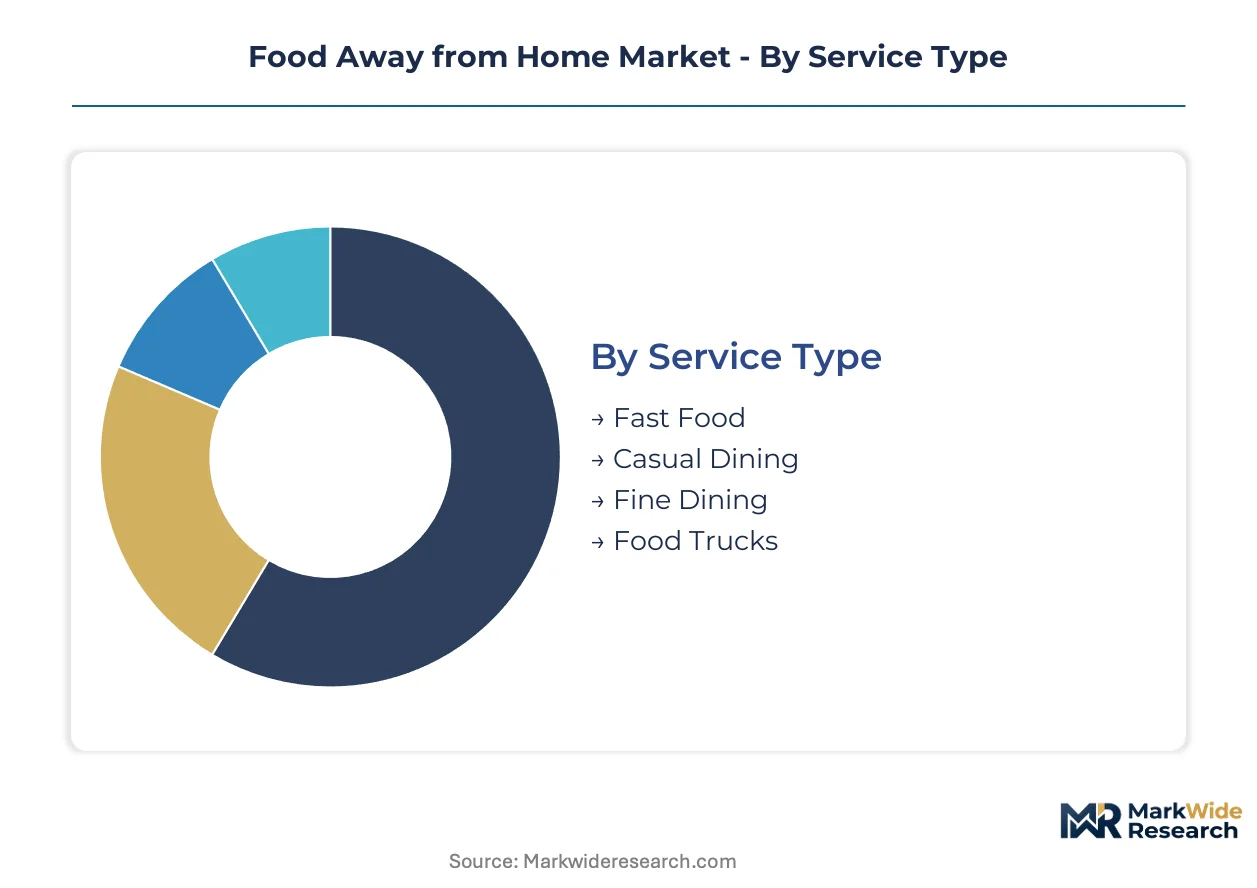
Food away from home operators configure capital deployment and labor models around distinct consumption occasions and customer profiles. Segmentation reveals how service format, diner demographics, dietary preferences, and fulfillment channel combine to determine unit economics and expansion viability.
Service Type:
Cost tier stratification separates volume-driven formats from experience-premium positioning.
- Fast Food:Standardized menu architectures and assembly-line production workflows enable throughput maximization at price points accessible to daily consumption. Demand concentrates in China's tier-one cities where commuters trade meal preparation time for convenience-oriented formats, though labor cost escalation in California and New York constrains unit-level profitability.
- Casual Dining:Full-service counter or table-service models with moderate price positioning and broader menu variety than quick-service alternatives. The steepest expansion runs through Southeast Asian markets where rising disposable incomes support format upgrading from street food and fast food.
- Fine Dining:Chef-driven tasting menus and wine program attach rates capture disproportionate margin pools through experiential pricing.
- Food Trucks:Mobile kitchen units with lower capital barriers and flexible location targeting of high-foot-traffic events and business districts.
Fast Food commands the established base. The steepest expansion runs through Casual Dining.
Customer Type:
Application context shapes daypart mix, party size, and average check dynamics.
- Families:Multi-generational dining occasions demanding menu breadth, child-friendly amenities, and value-oriented pricing bundles. Weekend lunch and early dinner dayparts dominate transaction timing.
- Millennials:Digital-native cohorts exhibiting pronounced preference for mobile order-ahead functionality and delivery platform integration. Urban density in Shanghai, Beijing, and Shenzhen elevates ghost kitchen and delivery-only format viability for this segment.
- Business Travelers:Expense-account dining with location convenience and speed-of-service priorities.
- Tourists:Destination-driven consumption seeking localized menu signatures and experiential store formats.
Millennials are gaining share fastest among customer types. Families retain the largest transaction volume base.
Menu Type:
Volume concentration varies sharply by dietary positioning and ingredient certification requirements.
- Vegetarian:Plant-forward preparations excluding meat proteins while retaining dairy and egg ingredients. India's FSSAI labeling standards and China's SAMR nutritional disclosure requirements shape formulation transparency obligations.
- Vegan:Exclusion of all animal-derived ingredients demanding supply chain segregation and cross-contamination protocols. EU Green Deal packaging waste directives accelerate demand for compostable container systems in this segment.
- Gluten-Free:Celiac-safe preparation workflows with dedicated equipment and ingredient sourcing.
- Organic:Certified ingredient procurement with audit documentation and premium pricing justification.
Vegetarian options command the established base. Vegan offerings are climbing the fastest as regulatory pressure and consumer preference converge.
Delivery Mode:
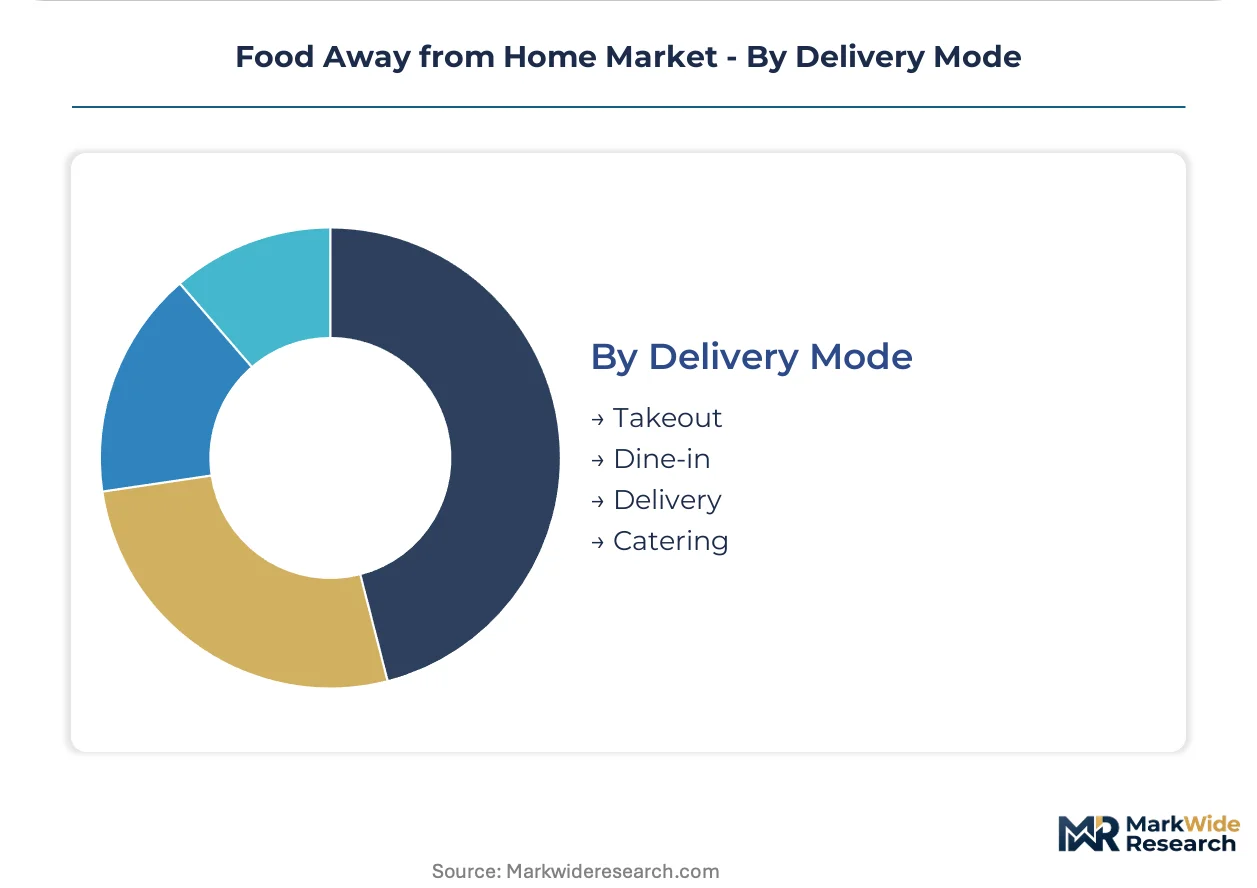
Fulfillment channel determines kitchen design, labor allocation, and real estate footprint requirements.
- Takeout:Customer-collected orders requiring dedicated pickup counters and packaging systems optimized for transport integrity. China's tier-one cities demonstrate pronounced preference for convenience-maximizing meal solutions in this mode.
- Dine-in:On-premise consumption demanding experiential environment investment and front-of-house staffing. Third-party platform commission structures extract 15-30 percent of order value, eroding operator economics and reinforcing dine-in margin defense.
- Delivery:Third-party platform or proprietary fleet fulfillment with 15-30 minute speed-of-service requirements and temperature-controlled packaging.
- Catering:Corporate and institutional contract segments with fragmented supply structures and compliance documentation requirements. FDA Food Code harmonization reduces compliance friction for multi-state US operators in this channel.
Dine-in commands the established base. Catering represents the most underpenetrated channel with steepest expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Food Code harmonization anchors the United States as the dominant geography for regulatory precedent, while tier-one urban corridors in China and contract catering networks across Europe concentrate operator investment and transaction volume.
United States
California and New York labor mandates compress unit-level profitability for full-service formats dependent on tipped compensation structures. FDA Food Code enforcement and state-level health department inspections reshape kitchen design standards and operational compliance costs. Manhattan and Los Angeles prime urban corridors tighten real estate availability as institutional investors acquire food-service-capable properties.
China
Shanghai, Beijing, and Shenzhen commuters demonstrate pronounced preference for convenience-maximizing meal solutions over traditional dine-in occasions. SAMR food safety traceability requirements and NMPA-related nutritional labeling standards tighten market access for non-compliant operators. Tier-two and tier-three cities attract supply chain scale deployment as operators compete for prime real estate in dense urban corridors.
Germany
EU Green Deal packaging waste directives mandate extended producer responsibility frameworks for food-service containers and utensils. F-Gas refrigeration regulations phase down hydrofluorocarbon-dependent equipment, imposing capital-intensive transitions for operators with legacy cold-chain infrastructure. Berlin and Munich accelerate reusable container deposit schemes to preempt regulatory penalties.
United Kingdom
London contract catering segments retain fragmented supply structures, creating white space for scaled operators with compliance documentation capabilities. Culinary workforce pipeline scarcity intensifies as vocational training program enrollment lags sector expansion. The Greater London Authority's planning frameworks influence ghost kitchen and delivery-only format viability through commercial zoning decisions.
Japan
Tokyo's urban density generates outsized transaction volumes as commuters trade meal preparation time for convenience-oriented formats. METI industrial standards and local prefectural health ordinances shape kitchen sanitation protocols and equipment certification requirements. Osaka and Nagoya clusters concentrate automated food preparation system deployment in high-volume quick-service environments.
Food Away from Home Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base separates between multinational chains with proprietary supply chain infrastructure and regional specialists with localized menu engineering competence. Strategic archetypes include quick-service volume leaders, experiential premium operators, and institutional contract caterers. Dominant competitive moves encompass geographic tier-down expansion and digital ordering platform deployment.
Within the quick-service archetype, McDonald's and Yum! Brands exemplify scale-driven supply chain leverage, while Starbucks Corporation anchors premium positioning through experiential format investment. Compass Group PLC occupies the institutional contract catering tier with long-term corporate and education partnership structures. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| McDonald's |
| Starbucks Corporation |
| Compass Group PLC |
| Sodexo |
| Aramark |
| Subway IP LLC |
| Darden Concepts Inc. |
| Chipotle Mexican Grill |
| Yum! Brands |
| Others |
Supply Flow & Price Mechanics
Shanghai's ghost kitchen cluster capacity dynamics directly shape downstream pricing power for delivery-native operators across China's tier-one cities, compressing dine-in premiums while elevating convenience-format margins through density-driven fulfillment economics.
Pricing Analysis
Geographic price spreads between Manhattan and Shanghai delivery corridors exceed threefold for comparable quick-service formats, reflecting rent burden differentials and labor cost structures. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by SAMR traceability certification tier and proprietary app penetration depth. Pricing pressure stems from third-party aggregator commission extraction, eroding operator economics without commensurate customer acquisition relief. Corporate catering buyers exhibit lowest price sensitivity due to expense-account structures, while independent millennials in Southeast Asian markets demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for protein and packaging input sourcing. Raw material flows concentrate in China, Brazil, and the United States for poultry and beef inputs, while compostable packaging draws from European Union certified suppliers and Southeast Asian molded-fiber producers. Cold-chain equipment sourcing rests on EU F-Gas regulatory compliance timelines, creating retrofit bottlenecks. Distribution runs through hub-and-spoke temperature-controlled networks anchored by regional distribution centers in tier-one urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional procurement consolidators as corporate catering contracts centralize under Compass Group PLC and Sodexo, fragmenting independent operator access to stable revenue streams.
For Market Incumbents: Pre-empt aggregator dependency erosion by deploying proprietary mobile ordering infrastructure with first-party data capture capabilities. Accelerate backward integration into compostable packaging supply chains to preempt EU Green Deal extended producer responsibility penalties. Ghost kitchen format expansion in tier-two Chinese cities represents the priority capacity deployment lever against local competitor encroachment. For New Entrants and Emerging Players: Mid-market casual dining in Vietnam and Indonesia represents the most penetrable entry point given disposable income trajectory and format upgrading appetite from street food. Corporate catering compliance documentation capabilities in the United Kingdom offer white-space acquisition potential against fragmented independent suppliers. Direct-to-enterprise sales with SAMR-aligned traceability systems provides the clearest go-to-market angle for China market entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated food preparation system suppliers with proven quick-service deployment records. Long-term viability across the analysis window hinges on regulatory compliance infrastructure ownership rather than brand equity alone. Acquisition targets should demonstrate EU F-Gas retrofit completion and FDA Food Code multi-state operational documentation. Ghost kitchen real estate portfolios in Shanghai and Beijing serve as the critical inflection indicator for delivery-native format viability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Digital Platform Deployment | First-party data capture reduces DoorDash and Meituan commission exposure by fifteen to thirty percentage points. |
| Automated Kitchen Equipment Installation | Flippy-grill robotics in McDonald's and Yum! Brands locations compress labor hours per transaction. |
| Compostable Packaging Transition | EU Green Deal compliance mandates accelerate demand for certified circular material streams from European suppliers. |
| Ghost Kitchen Format Expansion | Delivery-only footprints in Shanghai and Shenzhen reduce rent burden versus conventional dine-in square footage. |
| Corporate Catering Contract Acquisition | Long-term Compass Group PLC and Aramark partnership structures stabilize revenue against consumer discretionary volatility. |
Methodological Framework
The analysis maps quick-service chains, casual dining operators, institutional caterers, and ghost kitchen platforms, each validated through supply chain directors, restaurant operations executives, real estate acquisition leads, and third-party delivery platform strategists. Primary interview data triangulates against FDA Food Code enforcement records, SAMR traceability filings, EU F-Gas regulatory databases, and commercial real estate transaction databases. Secondary validation draws from SEC 10-K filings, customs trade data, and municipal health department inspection records. Bottom-up unit economics modeling and top-down market sizing converge through iterative stakeholder feedback loops.
Assumption sets held regulatory enforcement timelines and labor cost trajectories fixed while varying urban density projections and digital adoption curves across the projection horizon. Segmentation dimensions include service format, customer demographic, dietary positioning, and fulfillment channel, with regional regulatory cluster and city-tier infrastructure maturity as cross-cutting variables. CAGRs derive from historical transaction volume analysis projected through demographic and income elasticity coefficients. Forecast inputs incorporate FDA Food Code harmonization pace and SAMR enforcement intensity as scenario-weighted modifiers.
Macroeconomic conditions sit as an overlay; deviation in Chinese urban disposable income growth or California minimum wage compression trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timelines and technology adoption S-curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
North America Food Service Disposable Market
Food Service
United States Foodservice Market
Food Service
Food Service Pasta Market
Food Service
Restaurant Takeout Market
Food Service
France Foodservice Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
UAE Food Service Market
Food Service
Global Digital Food Delivery Market
Food Service
Global Meal Kit Market
Food Service
Charbroiler Market
Food Service
Online Grocery Market
Food Service
Food Contract Manufacturing Market
Food Service
Online Catering Market
Food Service
Full-Service Restaurants Market
Food Service
GCC Food Service Market
Food Service
North America Food Platform-To-Consumer Delivery Market