
 Food Truck Services Market | 2026-2036
Food Truck Services Market Size, Share, and Industry Trends Forecast 2026-2036
Food Truck Services Market Insights
Cloud-based point-of-sale and route optimization software is reconfiguring how food truck fleets coordinate daily operations and customer engagement. Kogi BBQ leverages its pioneering social media strategy to sustain brand visibility across Los Angeles. Cousins Maine Lobster anchors its growth through franchise licensing that extends geographic reach without direct capital deployment. The Halal Guys competes on standardized halal preparation protocols that differentiate its offering in dense urban corridors.
Food truck services comprise mobile commercial kitchen operations mounted on vehicle chassis, typically ranging from 14 to 30 feet in length with onboard generators, refrigeration, and ventilation systems compliant with municipal fire and health codes, designed to prepare and serve food at transient locations. Mobile catering and event services dominate revenue generation due to contracted minimums from festival organizers and corporate clients, while menu customization represents the fastest-expanding segment as operators respond to dietary restrictions and Instagram-driven visual differentiation. Gourmet burgers and tacos occupy mature volume positions, whereas vegan options capture expanding margin pools through premium pricing power.
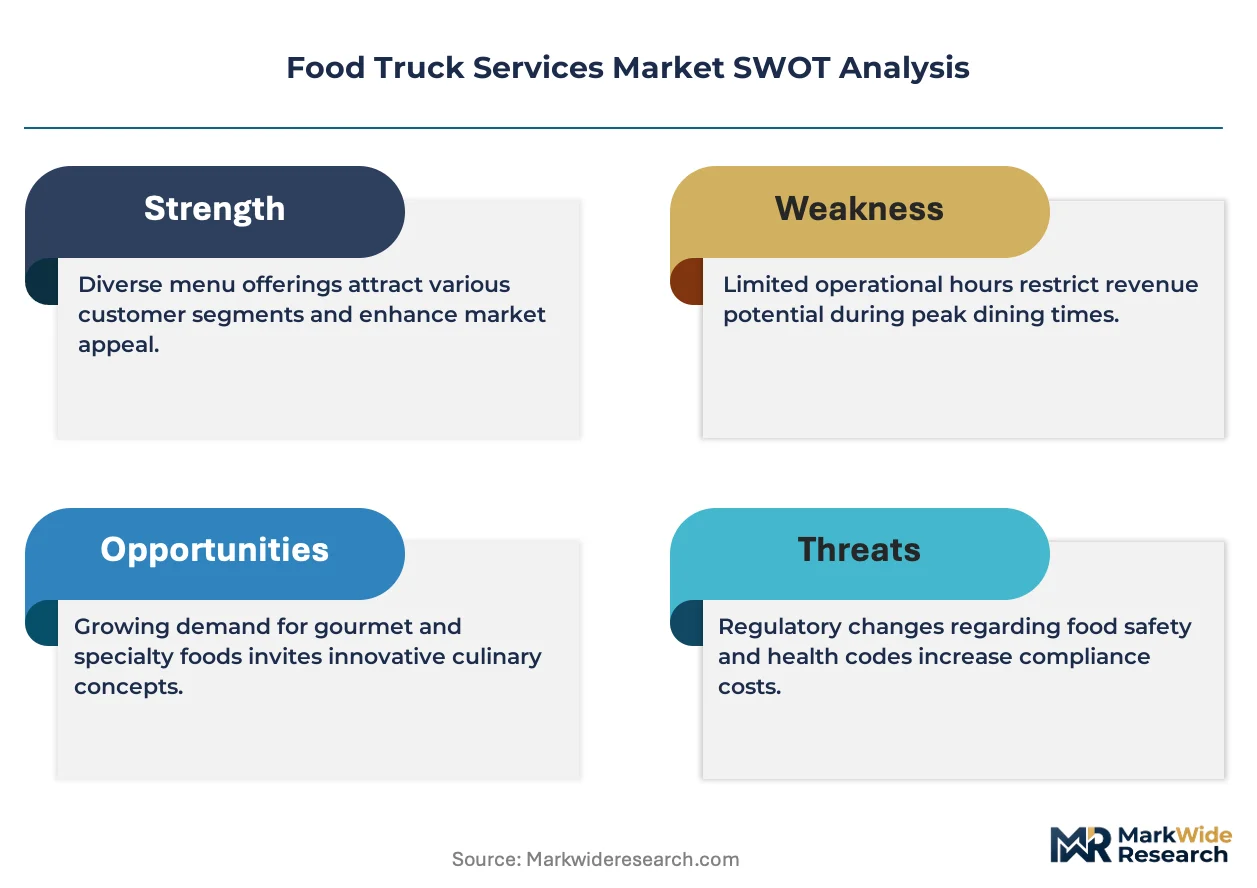
The FDA Food Code establishes baseline sanitation requirements that state and local health departments enforce through permitting and inspection regimes, while the National Fire Protection Association codes govern propane and electrical installations that determine vehicle compliance. Municipal zoning ordinances in cities such as Austin and New York City restrict operating locations and hours, directly constraining revenue potential and site selection strategy. Stakeholders must monitor evolving ghost kitchen regulations and third-party delivery platform commission structures that could compress already thin operating margins.
Market Dynamics
Cloud-based fleet management platforms are compressing route planning cycles and enabling real-time demand-response coordination across dispersed mobile kitchen operations.
Growth Catalysts
- Corporate Catering Contracts:Festival organizers and enterprise clients now specify minimum volume guarantees that stabilize revenue streams for mobile food operators.
- Social Media-Driven Discovery:Location-based digital marketing tools from Instagram and TikTok reduce customer acquisition costs for transient food service locations.
- Municipal Food Hall Partnerships:Cities including Austin and Los Angeles are designating permanent food truck plazas that reduce site uncertainty.
Market Restraints
- Propane Supply Volatility:Onboard fuel systems face input cost swings that compress operating margins during energy price spikes.
- Local Permitting Fragmentation:Health department inspection regimes vary by county, creating compliance friction for interstate fleet operators.
- Ghost Kitchen Substitution:Fixed-location delivery-only kitchens capture urban demand without vehicle capital requirements.
Strategic Opportunities
- Suburban Office Park Expansion:Underpenetrated daytime demand zones in secondary metropolitan rings offer contracted lunch service potential.
- Electric Chassis Integration:Battery-powered vehicle platforms from manufacturers like Rivian converge with solar refrigeration to reduce fuel dependency.
- FDA Food Code Harmonization:Proposed federal standardization of mobile kitchen sanitation protocols would reduce multi-jurisdiction compliance overhead.
Industry Challenges
- Certified Food Safety Manager Scarcity:ServSafe-level credential requirements limit qualified hiring pools in competitive labor markets.
- Mobile Equipment Depreciation Schedules:Custom vehicle builds require specialized maintenance capabilities that strain capex planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Truck Services Market |
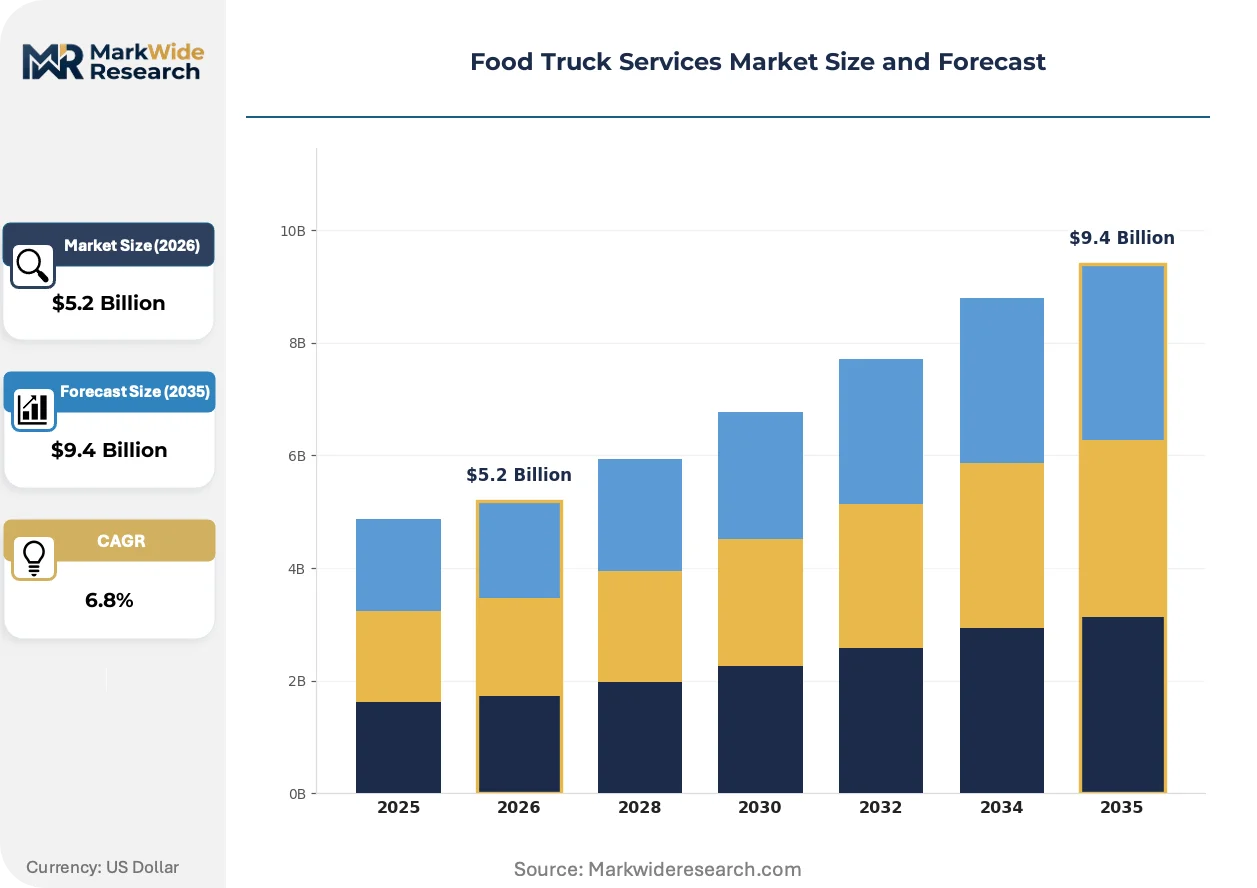
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $9.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Catering, Event Services, Menu Customization, Franchise Opportunities Food Type: Gourmet Burgers, Tacos, Vegan Options, Desserts End User: Tourists, Local Residents, Corporations, Festivals Sales Channel: Direct Sales, Online Orders, Partnerships, Offsite Events |
| Companies Covered | Kogi BBQ, Cousins Maine Lobster, The Halal Guys, The Grilled Cheese Truck, Gourmet Food Trucks, Lobsta Truck, Curry Up Now, Kona Ice, Cruising Kitchens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Truck Services Market Trends and Innovations
Digital infrastructure is reconfiguring how mobile food operators coordinate production, distribution, and customer relationships in real-time urban environments.
Artificial intelligence-powered demand forecasting is hybridizing historical sales patterns with weather and event data to optimize inventory pre-positioning. Multi-unit fleet operators in Los Angeles and New York City deploy these systems to reduce spoilage rates. The technology is compressing decision cycles between commissary kitchens and street-level service points.
The FDA Food Code revision process is tightening handwashing station and temperature logging requirements for mobile units. State health departments in Texas and California are piloting digital inspection documentation that accelerates permitting timelines. Smaller operators without compliance technology investments face exclusion from high-revenue festival circuits.
Festival organizers are consolidating vendor selection around contracted minimum guarantees rather than per-transaction revenue shares. This procurement model shift displaces speculative event participation with pre-committed volume relationships. Corporate campus catering in Austin and Chicago exhibits the fastest adoption of guaranteed-service structures.
Food Truck Services Market Segmentation
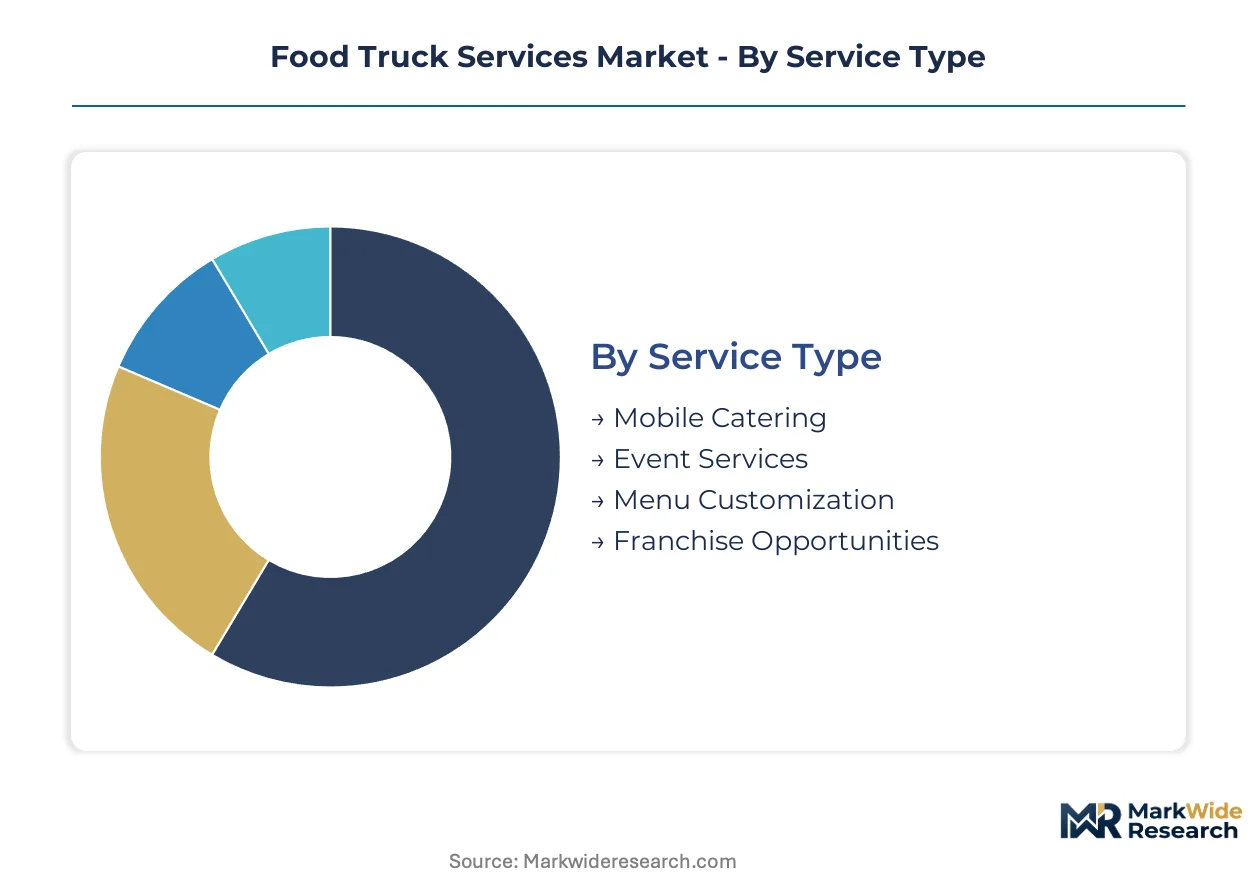
Food truck services fragment across operational models, cuisine specialization, and customer engagement channels. Each dimension shapes capital requirements, margin profiles, and regulatory exposure differently. Understanding these splits reveals where volume concentrates and where expansion capital flows.
Service Type:
Operators deploy distinct business architectures ranging from event-dependent models to recurring revenue structures with divergent risk-return profiles.
- Mobile Catering:Contracted service delivery to corporate campuses, construction sites, and private events with pre-negotiated minimums. Demand clusters around Austin and Chicago office parks where guaranteed-service structures displace speculative street vending.
- Event Services:Festival circuit participation with revenue tied to attendance volatility and organizer commission structures. Los Angeles and New York City operators face consolidated vendor selection around volume guarantees rather than per-transaction splits.
- Menu Customization:Dietary-restriction accommodation and Instagram-driven visual differentiation command premium pricing. Rapid expansion follows vegan, halal, and allergen-free specialization.
- Franchise Opportunities:Licensing models enabling geographic extension without direct capital deployment. Cousins Maine Lobster anchors growth through this structure.
The dominant share belongs to Mobile Catering, while Menu Customization is expanding most quickly through premium positioning.
Food Type:
Cuisine categories stratify by margin potential, ingredient input volatility, and preparation complexity requirements.
- Gourmet Burgers:Mature volume position with established supply chains and broad consumer acceptance. Los Angeles and Austin operators compete on patty sourcing and brioche customization rather than novelty.
- Tacos:Kogi BBQ pioneered Korean-Mexican fusion in Los Angeles, demonstrating social media amplification potential. Price compression limits margin expansion in saturated urban corridors.
- Vegan Options:Premium pricing power captures expanding margin pools as dietary restriction accommodation becomes standard expectation. Ingredient costs run higher but waste rates compress through precise demand forecasting.
- Desserts:Specialized equipment requirements for frozen and baked goods create operational complexity. Festival circuits provide concentrated demand windows.
Gourmet Burgers retain volume leadership, though Vegan Options are gaining share fastest through pricing power and demographic tailwinds.
End User:
Customer archetypes determine location strategy, service cadence, and relationship investment intensity.
- Tourists:Transient demand concentrated at landmarks, transit hubs, and entertainment districts. Location visibility and digital discovery tools reduce repeat visit dependency.
- Local Residents:Neighborhood loyalty cultivation through recurring presence and menu rotation. Austin food truck plazas reduce site uncertainty for this segment.
- Corporations:Contracted campus catering with multi-year service agreements and volume minimums. Fastest-growing demand channel as enterprise clients seek differentiated meal programs.
- Festivals:Concentrated revenue windows with high per-day throughput requirements. Organizer consolidation around guaranteed minimums reshapes vendor economics.
Corporations command the steepest expansion trajectory, while Local Residents provide the revenue base with highest predictability.
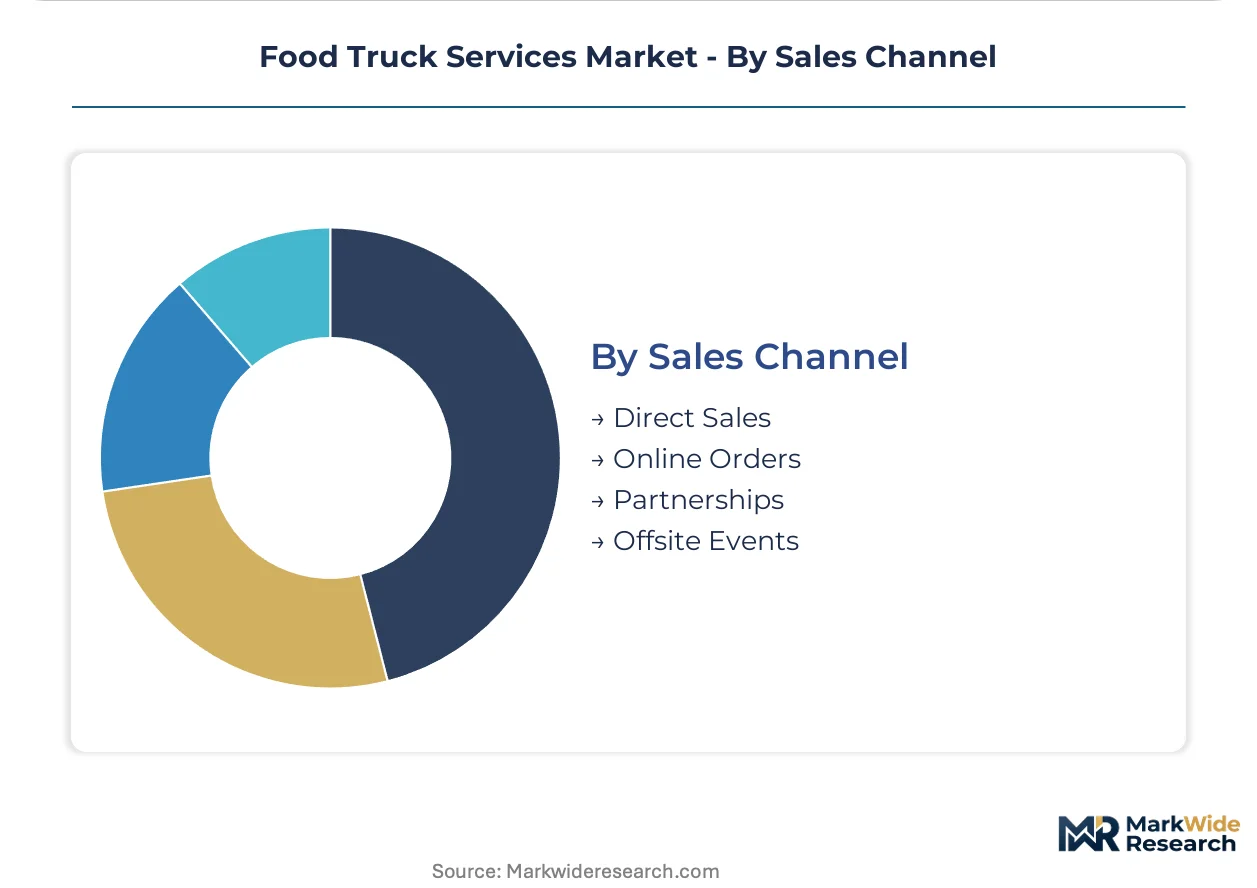
Sales Channel:
Customer acquisition pathways diverge by technology investment, commission structures, and brand control retention.
- Direct Sales:Window transactions preserving full margin but requiring physical presence and weather resilience. Core revenue mechanism for established operators with fixed location relationships.
- Online Orders:Pre-order and pickup coordination through proprietary apps or third-party platforms. Commission compression threatens viability without volume scale.
- Partnerships:Brewery, retail, and entertainment venue co-location arrangements with revenue sharing or fixed rent structures. Reduces site procurement friction.
- Offsite Events:Private and corporate function deployment with transportation and setup cost recovery built into pricing. Higher per-transaction revenue offsets logistical complexity.
Direct Sales still dominates transaction volume, yet Online Orders are climbing the fastest as digital infrastructure penetrates the segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate campus catering contracts and festival vendor consolidation concentrate demand in metropolitan clusters with established food truck infrastructure and permissive mobile vending ordinances.
United States
Enterprise clients in Austin and Los Angeles drive contracted minimum-guarantee structures that stabilize operator revenue streams. The FDA Food Code establishes baseline sanitation requirements that state health departments enforce through permitting regimes. Kogi BBQ anchors the Los Angeles cluster with social media-driven customer acquisition that other operators emulate.
Canada
Toronto and Vancouver office parks generate underpenetrated daytime demand for mobile lunch services with recurring service potential. Health Canada coordinates with provincial regulators to standardize mobile kitchen inspection protocols across Ontario and British Columbia. Montreal's festival circuit provides concentrated seasonal revenue windows for equipped operators.
Germany
Berlin's street food markets and corporate catering contracts create dual-channel revenue opportunities for fleet operators. The LFGB (Lebensmittel- und Futtermittelgesetzbuch) governs mobile food safety standards enforced by local Ordnungsamt offices. Munich's Oktoberfest and trade fair calendar generates predictable high-volume event demand.
United Kingdom
London's financial district and tech corridor employers increasingly contract mobile catering for differentiated meal programs. The Food Standards Agency mandates hazard analysis critical control point documentation for mobile vendors. Bristol and Manchester food truck collectives reduce site uncertainty through permanent municipal partnerships.
Australia
Sydney and Melbourne festival circuits and brewery partnerships sustain operator revenue through Australia's extended outdoor event season. Food Standards Australia New Zealand coordinates state-level mobile vendor licensing that varies by territory. Brisbane's subtropical climate extends operating windows beyond temperate-zone constraints.
Food Truck Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented metropolitan markets where location access and social media visibility determine customer acquisition economics. The vendor base stratifies into three tiers: single-unit owner-operators, regional multi-truck fleets, and franchise-licensed national brands. Dominant competitive moves include municipal permit aggregation and proprietary commissary kitchen networks that reduce per-unit operating costs.
Within the franchise-licensed tier, Cousins Maine Lobster exemplifies geographic extension without direct capital deployment, while The Halal Guys represents standardized preparation protocols that differentiate offerings in dense urban corridors. Kogi BBQ anchors the social media amplification archetype, demonstrating how location-based digital marketing reduces customer acquisition costs for transient service points. These three operators occupy positions that illustrate distinct pathways to scale in metropolitan food truck markets.
| Leading Market Players |
|---|
| Kogi BBQ |
| Cousins Maine Lobster |
| The Halal Guys |
| The Grilled Cheese Truck |
| Gourmet Food Trucks |
| Lobsta Truck |
| Curry Up Now |
| Kona Ice |
| Cruising Kitchens |
| Others |
Pricing and Supply Chain Analysis
Commissary kitchen concentration in Texas and California anchors input cost structures for mobile food operators, with propane and refrigeration equipment sourcing determining where margin pools accumulate across festival circuits and corporate catering contracts.
Pricing Analysis
Cost-plus contracts with propane indexation dominate multi-year corporate catering agreements in Austin and Chicago office parks. Three-tier pricing structure across premium, standard, and economy levels separates gourmet vegan specialists from taco and burger commoditized segments. Price differentiation rests on ServSafe certification tier and Instagram-driven brand premium. Cost compression in the economy tier is intensifying because ghost kitchen substitution eliminates vehicle capital requirements. Corporate clients exhibit lowest price sensitivity due to contracted minimum guarantees, while festival circuit operators face acute margin pressure from organizer commission structures.
Supply Chain Analysis
Supplier-financing through extended payment terms from refrigeration equipment manufacturers supports smaller operators managing custom vehicle build cycles. Mobile kitchen chassis fabrication concentrates in Indiana, Texas, and California. Propane tank systems, onboard generators, and NSF-certified refrigeration units constitute critical component dependencies. Single-source vulnerability runs through specialized food-grade stainless steel fabricators serving the commercial vehicle conversion tier. Distribution runs through regional commissary kitchen networks that aggregate ingredient procurement and waste disposal for dispersed fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food truck services fragmentation creates acquisition opportunities as corporate catering demand shifts toward guaranteed-service structures that favor multi-unit fleet operators over speculative street vendors.
For Market Incumbents: Harden proprietary commissary kitchen networks in Los Angeles and Austin to defend against ghost kitchen substitution threatening mobile catering margins. Acquire ServSafe-certified management talent pools before labor scarcity constrains festival circuit participation. Secure municipal permit aggregation in secondary metropolitan rings before new entrants replicate the strategy.
For New Entrants and Emerging Players: Toronto and Vancouver office parks offer underpenetrated daytime demand for contracted lunch services with recurring revenue potential. Target suburban corporate campuses in secondary US metropolitan rings where incumbent coverage remains thin. Deploy electric chassis pilot programs with solar refrigeration to differentiate on fuel cost volatility hedging.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fleet operators in Texas and California seeking exit liquidity before electric vehicle conversion capex requirements intensify. Five-to-ten year viability hinges on municipal permit portfolio quality and corporate contract renewal rates. Monitor FDA Food Code harmonization progress as inflection indicator for compliance cost consolidation benefits accruing to scaled operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Kitchen Network Expansion | Aggregates procurement volume and waste disposal for dispersed fleet operators in Austin and Los Angeles. |
| Electric Chassis Pilot Deployment | Reduces propane dependency and aligns with municipal zero-emission vehicle mandates in California corridors. |
| Corporate Catering Contract Consolidation | Captures multi-year guaranteed minimum structures displacing speculative festival circuit participation. |
| Municipal Permit Portfolio Acquisition | Secures site access rights in designated food truck plazas across Austin and New York City. |
| Digital Inspection Documentation Investment | Accelerates permitting timelines with Texas and California health department pilot programs. |
Research Methodology
The analysis maps mobile catering, event services, menu customization, and franchise licensing segments, each validated through fleet operators, commissary kitchen managers, municipal health department inspectors, and corporate catering procurement officers. Primary fieldwork combined structured interviews with secondary validation against FDA Food Code documentation, state health department permitting databases, and municipal zoning ordinance records. Bottom-up unit economics modeling triangulated against top-down market sizing from commercial vehicle registration data and festival organizer vendor expenditure disclosures.
Assumptions held fixed include current FDA Food Code sanitation requirements and existing municipal zoning restrictions in analyzed metropolitan clusters, while propane price volatility and electric vehicle adoption curves were varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, cuisine specialization, end-user archetype, and sales channel. CAGRs were derived from historical fleet expansion rates correlated with corporate catering contract penetration and festival circuit vendor consolidation trends. Commissary kitchen network density and ServSafe certification availability served as industry-specific forecast inputs.
Practitioners should monitor propane price volatility spikes, FDA Food Code revision timelines, and ghost kitchen regulatory classification changes for early signals of forecast deviation. Macroeconomic contraction affecting corporate catering budgets, regulatory or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
New Zealand Foodservice Market
Food Service
Pasteurized Eggs Market
Food Service
Electric Tiffin Market
Food Service
International Food Subscription Box Service Market
Food Service
Commercial Grills Market
Food Service
Kuwait Food Service Market
Food Service
Limited-Service Restaurants Market
Food Service
Takeout Dinner Market
Food Service
Bar Refrigeration Market
Food Service
India Online Grocery Market
Food Service
Online Grocery Market
Food Service
Gourmet Street Food Market
Food Service
Pizza Oven Market
Food Service
Steam Stew Pot Market
Food Service
Quick-Service Restaurants Market
Food Service
South Korea Foodservice Market