
 White Coal Market | 2026-2036
White Coal Market Size, Share, and Industry Trends Forecast 2026-2036
White Coal Market Outlook
EU Green Deal carbon border adjustments is realigning export competitiveness for white coal producers serving European industrial buyers. ETIA SAS leverages its pyrolysis technology leadership to sustain premium positioning in torrefied pellet supply. Vega Biofuels Inc. anchors North American capacity through controlled feedstock partnerships with southeastern sawmill networks. Airex Energy competes on densification efficiency, differentiating its output for utility-scale co-firing contracts.
White coal denotes densified biomass fuel produced through mechanical compression or thermochemical upgrading of agricultural residues, wood waste, and energy crops to achieve calorific values typically ranging from 4,000 to 5,000 kcal per kilogram, serving primarily as a direct combustion substitute for fossil coal in thermal applications. Biomass Pellets dominate volume flows due to standardized sizing that integrates with existing coal handling infrastructure at power plants, while Agro Residue Briquettes capture margin pools in rural industrial heating where feedstock proximity outweighs logistics costs. Sawdust Pellets occupy a specialized niche among residential heating distributors in European markets with stringent particulate emissions standards.
EPA renewable fuel standards in the United States, India's CEA biomass utilization mandates for thermal power stations, and the EU F-Gas Regulation's indirect pressure on heating fuel choices collectively shape product certification requirements and market access conditions for white coal suppliers. India's BIS quality specifications for biomass briquettes and Indonesia's Ministry of Energy mineral content rules further fragment compliance burdens across export destinations. Stakeholders must monitor feedstock cost volatility and regulatory enforcement intensity as the primary variables determining regional profitability thresholds.
Market Dynamics
EU Green Deal carbon border adjustments are compressing margins for exporters while redirecting procurement toward torrefied pellet grades that qualify for industrial emissions accounting. This regulatory pressure is accelerating technology substitution timelines across European-bound supply chains.
Growth Catalysts
- India's CEA biomass utilization mandates:Thermal power stations must co-fire agro residue briquettes, creating guaranteed offtake for domestic processors.
- Cement kiln retrofitting in Surabaya:Indonesia's industrial corridor is absorbing bio-coal for clinker production, displacing imported thermal coal volumes.
- PLI scheme capital redirection:India's production-linked incentive for biomass gasification is funding domestic agro residue processing infrastructure.
Market Restraints
- Feedstock cost volatility:Agricultural residue prices fluctuate with monsoon patterns and competing fodder demand in India's northern grain belt.
- Supply concentration risk:Premium torrefied pellet capacity clusters in France and Germany, exposing buyers to single-source dependencies.
- Technical limitation:High-alkali agro residues accelerate slagging in pulverized coal boilers, restricting co-firing ratios without equipment modification.
Strategic Opportunities
- Underpenetrated rural industrial heating:India's small and medium enterprises in Uttar Pradesh and Punjab remain dependent on loose biomass or diesel.
- Emerging application in steel sector:Direct reduced iron producers in Indonesia are piloting bio-coal as a metallurgical reductant substitute.
- Technology convergence:Pyrolysis systems integrated with carbon capture are enabling negative-emission fuel certification for European industrial buyers.
Industry Challenges
- Certification timeline compression:EU F-Gas Regulation and REACH compliance documentation now requires 12-18 month pre-shipment preparation.
- Capex intensity for densification:Ring-die pellet mills and torrefaction reactors demand capital deployment that exceeds rural processor balance sheet capacity.
- Integration complexity with legacy coal handling:Existing power plant conveyors and silos require retrofitting for standardized pellet dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Coal Market |
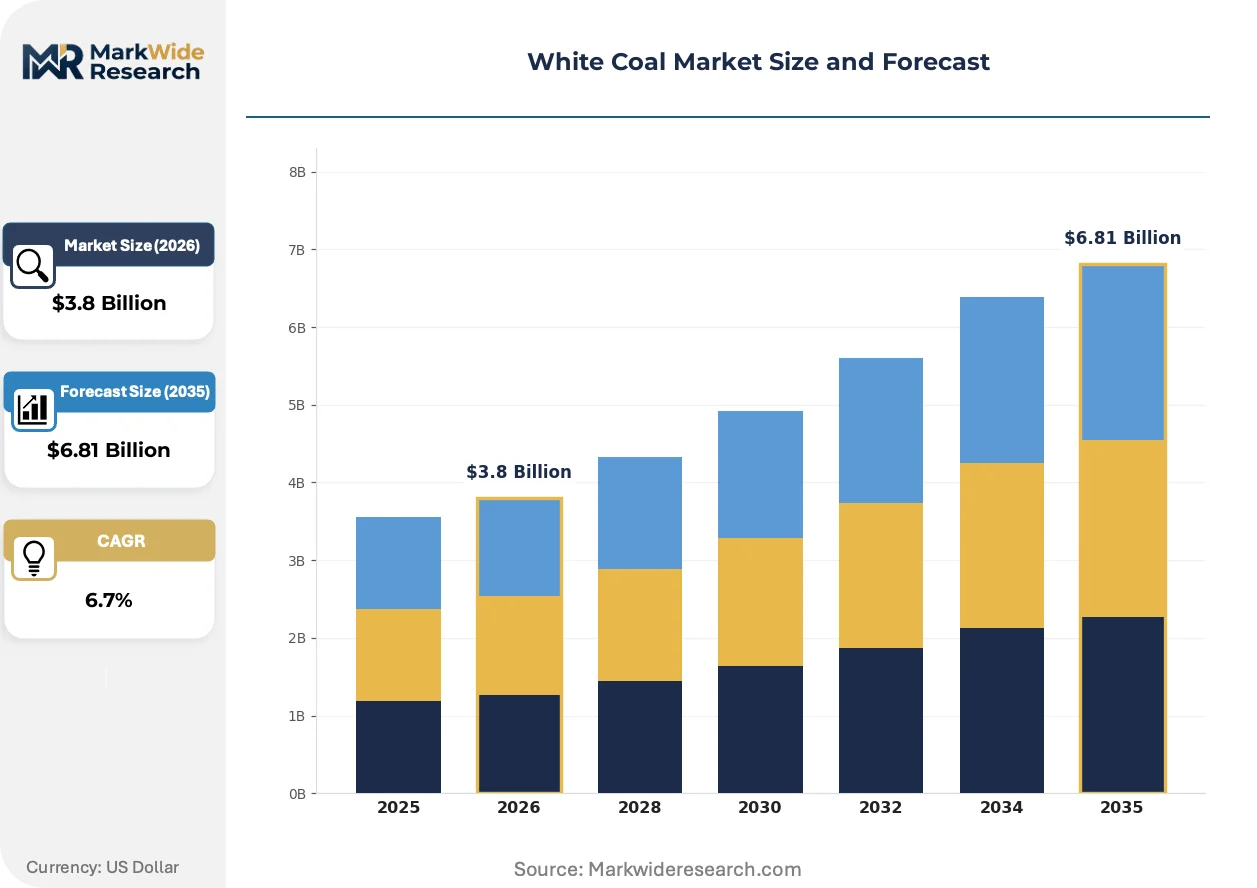
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomass Pellets, Agro Residue Briquettes, Sawdust Pellets, Wood Chips End User: Power Plants, Industrial Heating, Residential Heating, Biofuel Production Application: Electricity Generation, Heating Systems, Cooking, Industrial Processes Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesalers |
| Companies Covered | ETIA SAS, Vega Biofuels Inc., Airex Energy, CSC Bio-Coal Sdn. Bhd., NextCoal International Inc., TorrCoal, Global Bio-Coal Energy Inc., Balaji Agro Coal Industries, SSGE Bio-Energy Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Coal Market Strategic Shifts
Thermochemical upgrading and densification technologies are compressing the quality gap between biomass fuels and fossil coal. Equipment manufacturers and fuel suppliers are racing to capture margin pools from industrial buyers facing carbon accounting pressures.
Torrefaction is absorbing capital deployment from European utilities seeking drop-in coal replacements. RWE and Uniper are testing torrefied pellet co-firing at 20% ratios in existing pulverized coal units. This thermochemical process is absorbing moisture and volatile compounds to achieve grindability and calorific parity with sub-bituminous coal, enabling seamless fuel substitution without boiler derating.
EPA renewable fuel standards in the United States are tightening lifecycle carbon intensity thresholds for biomass fuel eligibility. Industrial thermal users must now document feedstock origin and land-use change impacts to qualify for compliance credits. Power generators in the Midwest are responding by sourcing exclusively from forestry residue streams with chain-of-custody certification.
Buyer procurement is consolidating around long-term offtake contracts with fixed-price escalators. Cement and steel producers are displacing spot market purchases with five-year supply agreements that transfer feedstock risk to pellet suppliers. This pattern is most visible in Indonesia's industrial corridor, where procurement teams at Semen Indonesia and Krakatau Steel have standardized on indexed pricing for bio-coal volumes.
White Coal Market Segmentation
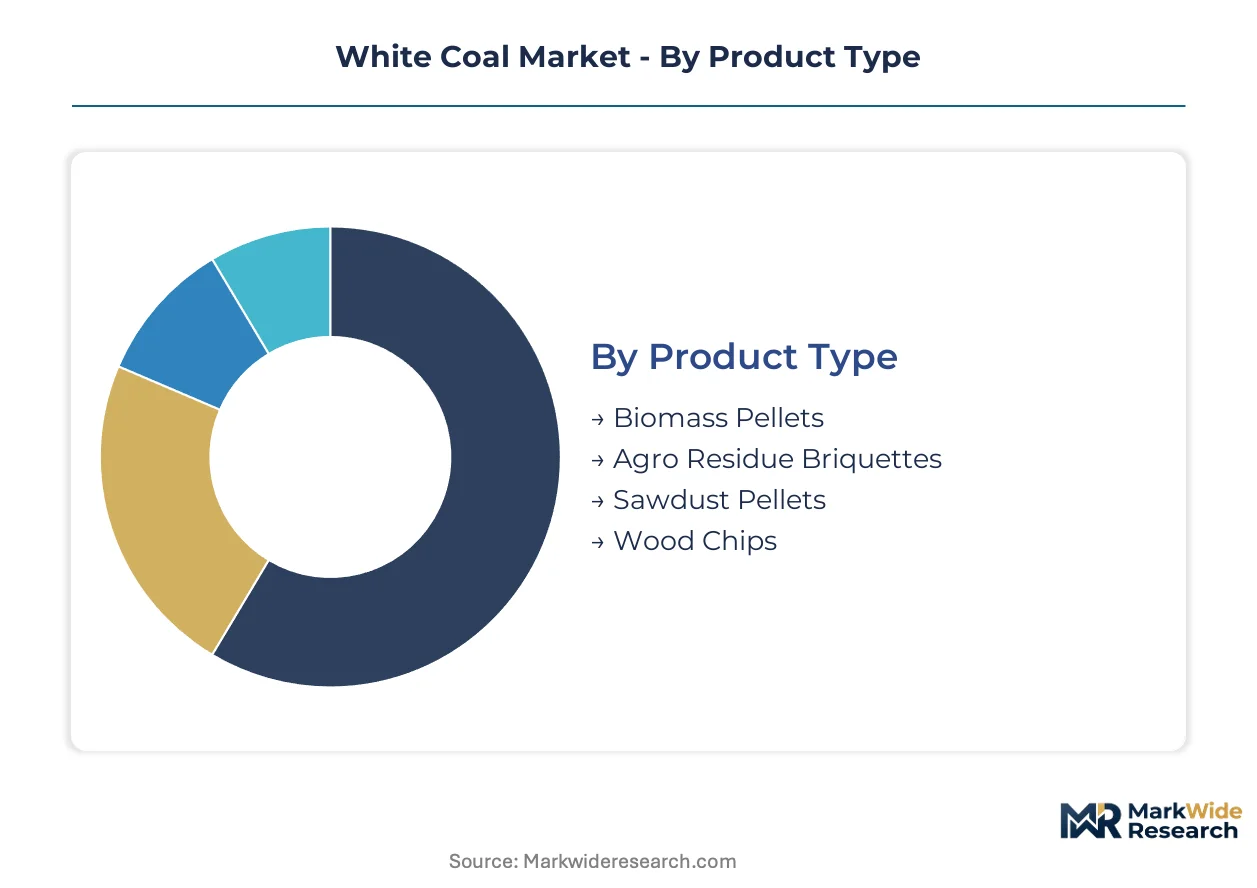
White coal markets fragment across fuel forms, end-use thermal requirements, and logistics configurations that determine procurement economics. Each segmentation dimension reveals distinct margin pools and capital deployment patterns for processors and distributors.
Product Type:
Upgrade cycles from loose biomass to densified fuels follow calorific value requirements and handling infrastructure compatibility at the point of combustion.
- Biomass Pellets:Standardized cylindrical fuel with moisture content below 10% and bulk density exceeding 600 kg per cubic meter. Cement kilns in Indonesia's Surabaya corridor are retrofitting coal feeders for pellet dimensions, displacing imported thermal coal under Ministry of Energy mineral content rules. Volume placements concentrate in Biomass Pellets; the faster expansion belongs to Agro Residue Briquettes.
- Agro Residue Briquettes:Compressed blocks from rice husk, wheat straw, or cotton stalk with calorific values of 3,500 to 4,200 kcal per kilogram. India's CEA mandates for thermal power station co-firing are redirecting capital toward domestic agro residue processing infrastructure in Punjab and Uttar Pradesh.
- Sawdust Pellets:Fine-wood particle densification for residential heating markets with stringent particulate emissions standards.
- Wood Chips:Unprocessed or minimally sized forestry residue serving industrial boilers with on-site fuel handling capabilities.
Margin structures vary with densification intensity and feedstock proximity to processing facilities.
End User:
Customer scale determines contract duration, price indexing mechanisms, and technical service requirements across the value chain.
- Power Plants:Utility-scale thermal generators requiring standardized fuel specifications for pulverized coal boiler co-firing. RWE and Uniper in Germany are testing torrefied pellet blends at 20% substitution ratios, driving procurement consolidation around long-term offtake agreements with fixed-price escalators.
- Industrial Heating:Cement, steel, and chemical processors with continuous thermal demand and captive fuel handling infrastructure. Procurement teams at Semen Indonesia and Krakatau Steel have standardized on indexed bio-coal pricing for clinker and direct reduced iron production.
- Residential Heating:Distributed household and commercial building heat demand concentrated in European markets with EU F-Gas Regulation compliance requirements.
- Biofuel Production:Secondary processors converting white coal feedstock into liquid or gaseous energy carriers.
Contract concentration favors Power Plants; Residential Heating climbs the fastest on emissions compliance retrofit cycles.
Application:
Combustion technology specifications and emissions accounting frameworks shape product certification requirements for each thermal use case.
- Electricity Generation:Grid-connected power production with carbon intensity tracking under EPA renewable fuel standards or EU Green Deal carbon border adjustments.
- Heating Systems:Building and district heat networks requiring particulate emissions control and automated fuel feeding mechanisms.
- Cooking:Household and commercial food preparation with direct combustion exposure and indoor air quality constraints.
- Industrial Processes:High-temperature thermal applications including cement clinker formation and steel reductant substitution.
Equipment retrofit intensity peaks in Electricity Generation; Industrial Processes show steepest expansion trajectory on metallurgical fuel substitution pilots.
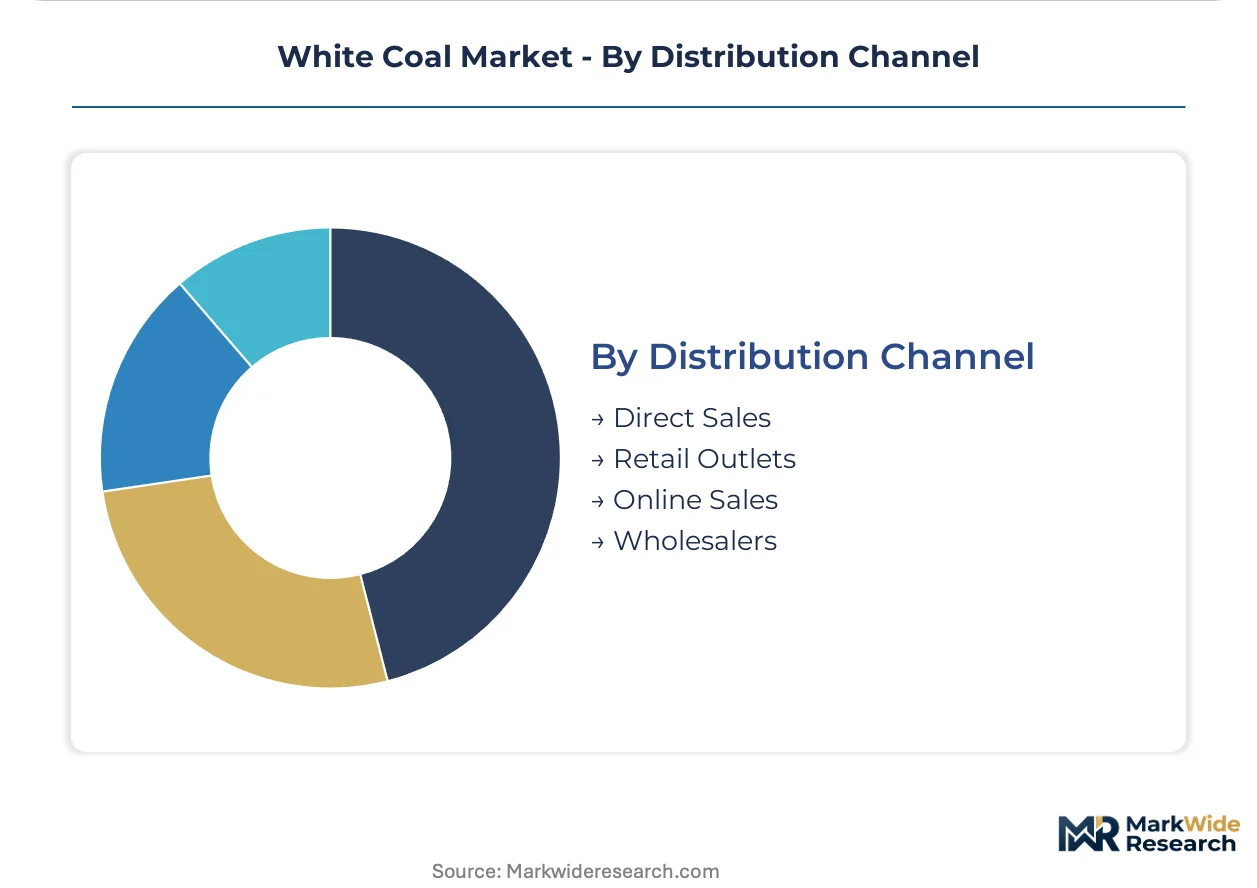
Distribution Channel:
Logistics configuration and buyer scale determine channel economics and working capital requirements for fuel suppliers.
- Direct Sales:Producer-to-end-user contracts for utility and industrial volumes with dedicated handling infrastructure. Five-year supply agreements with fixed-price escalators are displacing spot market purchases among cement and steel producers in Indonesia.
- Retail Outlets:Bagged fuel sales through agricultural supply cooperatives and building material distributors serving residential and small commercial heating demand.
- Online Sales:E-commerce platforms for residential pellet procurement with delivery logistics coordination.
- Wholesalers:Intermediate inventory holders aggregating volumes from multiple producers for redistribution to retail and industrial accounts.
Contract value pools concentrate in Direct Sales; Online Sales expands most quickly on residential heating retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Indonesia's East Java corridor concentrate bio-coal demand from cement and steel producers seeking carbon-adjusted fuel alternatives. India's PLI scheme for biomass gasification is redirecting capital toward domestic agro residue processing clusters. Germany's industrial heartland anchors European torrefied pellet capacity expansion.
Indonesia
Cement kilns around Surabaya are retrofitting coal feeders for bio-coal co-firing, displacing imported thermal coal under Ministry of Energy mineral content rules. The PLN biomass cofiring mandate requires state power generators to blend agricultural residue pellets. Industrial procurement teams at Semen Indonesia have standardized on five-year indexed supply agreements.
India
CEA biomass utilization mandates require thermal power stations to co-fire agro residue briquettes, creating guaranteed offtake for Punjab and Uttar Pradesh processors. The PLI scheme for biomass gasification funds domestic agro residue processing infrastructure. Cement plants in Rajasthan's industrial belt are piloting bio-coal for clinker production.
Germany
RWE and Uniper are testing torrefied pellet blends at 20% substitution ratios in existing pulverized coal units under EU Green Deal carbon border adjustment pressure. The country's national energy regulator oversees grid-connected bioenergy facility certification. Industrial clusters in North Rhine-Westphalia concentrate utility-scale co-firing demand.
United States
EPA renewable fuel standards tighten lifecycle carbon intensity thresholds for biomass fuel eligibility, requiring chain-of-custody documentation. Southeastern sawmill networks supply forestry residue streams to controlled feedstock partnerships. Midwest power generators source exclusively from certified residue streams to qualify for compliance credits.
France
ETIA SAS leverages pyrolysis technology leadership from its French base to sustain premium positioning in torrefied pellet supply for industrial emissions accounting. The country's national environmental agency enforces REACH compliance documentation for export-bound fuel shipments. Industrial buyers in the Hauts-de-France region prioritize drop-in coal replacements for steel and cement applications.
White Coal Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology licensing, feedstock control, and densification efficiency vectors. The vendor base clusters around three strategic archetypes: thermochemical upgrading technology licensors, feedstock-integrated processors with sawmill or agricultural residue partnerships, and utility-facing fuel suppliers with long-term offtake contracting capabilities. Dominant competitive moves include backward integration into captive feedstock supply and strategic partnerships with power generators for co-firing pilot programs.
Among European technology specialists, ETIA SAS and TorrCoal exemplify the thermochemical upgrading archetype, positioning around pyrolysis system deployment and torrefied pellet densification efficiency. North American feedstock-integrated processors include Vega Biofuels Inc., representing the controlled partnership model with southeastern sawmill networks. These named entities anchor competitive positioning without exhaustively mapping market share concentration.
| Leading Market Players |
|---|
| ETIA SAS |
| Vega Biofuels Inc. |
| Airex Energy |
| CSC Bio-Coal Sdn. Bhd. |
| NextCoal International Inc. |
| TorrCoal |
| Global Bio-Coal Energy Inc. |
| Balaji Agro Coal Industries |
| SSGE Bio-Energy Company Ltd. |
| Others |
Value Chain & Pricing Dynamics
Torrefaction-grade premium over standard agro residue briquettes creates a bifurcated pricing landscape where EU-bound industrial buyers absorb cost premiums for emissions accounting compliance while domestic Indian processors compete on feedstock proximity economics. This tier divergence channels capital toward densification technology in France and Germany while fragmenting procurement across spot agricultural residue markets in Punjab and Uttar Pradesh.
Pricing Analysis
Short lead-time premiums dominate contract structures as European cement and steel producers pay escalated rates for torrefied pellet volumes with certified chain-of-custody documentation under EU Green Deal carbon border adjustments. Pricing stratifies across premium torrefied grades, standard biomass pellets, and economy agro residue briquettes based on calorific parity with sub-bituminous coal and REACH compliance status. Cost compression in standard pellet tiers is intensifying because Indonesian Ministry of Energy mineral content rules are forcing equipment retrofits that transfer expense to fuel suppliers. Small and medium enterprises in India's rural industrial heating segment exhibit highest price sensitivity, while German utility procurement teams at RWE and Uniper demonstrate lowest sensitivity given emissions accounting imperatives.
Supply Chain Analysis
Single-source vulnerability sits with premium torrefied pellet capacity clustering in France and Germany, exposing industrial buyers to concentrated supply risk from ETIA SAS and TorrCoal technology deployments. Geographic supply concentration spans Indonesia for cement kiln bio-coal, India for agro residue briquette processing, and Germany for torrefied pellet densification. Raw material dependencies include rice husk and wheat straw from India's northern grain belt, forestry residue from southeastern US sawmill networks, and woody biomass from European managed forests. Supply chain risk centers on tariff exposure from EU carbon border adjustments redirecting procurement toward domestic European torrefaction capacity. Distribution runs through direct producer-to-end-user contracts for utility and industrial volumes, with five-year indexed supply agreements displacing spot market purchases among Indonesian cement producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torrefaction reactor capacity bottlenecks in France and Germany prop pricing premiums for drop-in coal replacements, constraining supply expansion despite accelerating utility co-firing mandates. This supply-constrained structure favors processors with captive feedstock control and technology licensing positions.
For Market Incumbents: Extend backward integration into captive forestry residue supply in southeastern US sawmill networks to defend margin position against emerging torrefaction specialists. Prioritize certification investment for EU REACH and F-Gas Regulation compliance documentation, as twelve-to-eighteen-month pre-shipment preparation timelines are creating competitive moats. Add densification capacity in Indonesia's Surabaya corridor to capture cement kiln retrofit demand under Ministry of Energy mineral content rules. For New Entrants and Emerging Players: India's CEA biomass utilization mandates open a window for agro residue briquette processing ventures targeting thermal power station co-firing offtake in Punjab and Uttar Pradesh. The most penetrable segment sits with rural small and medium enterprises in India's northern grain belt currently dependent on loose biomass or diesel for industrial heating. A go-to-market angle anchored to PLI scheme capital access for biomass gasification infrastructure offers differentiated positioning against established loose biomass traders. For Investors and Strategic Acquirers: Re-rating potential sits with feedstock-integrated processors given EU Green Deal carbon border adjustment pressure accelerating procurement consolidation around long-term offtake contracting capabilities. Long-term viability across a five-to-ten-year window hinges on technology convergence with carbon capture enabling negative-emission fuel certification. Acquisition target archetypes include controlled feedstock partnerships with southeastern US sawmill networks. The signal to watch is torrefied pellet co-firing ratio expansion beyond twenty percent in German pulverized coal units, indicating technology substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive forestry residue control from southeastern US sawmill networks secures margin against spot market volatility. |
| Torrefaction Capacity Expansion | EU Green Deal carbon border adjustments are redirecting procurement toward premium torrefied pellet grades for emissions accounting. |
| Long-term Supply Agreement Structuring | Five-year indexed contracts with Semen Indonesia transfer feedstock risk while locking in cement kiln retrofit volumes. |
| REACH Compliance Documentation Investment | Twelve-to-eighteen-month pre-shipment certification timelines create competitive moats against unqualified suppliers. |
| Pyrolysis-Carbon Capture Technology Convergence | Negative-emission fuel certification unlocks premium positioning for European industrial buyers under EU Green Deal frameworks. |
Study Parameters
Independent corroboration across utility planning officers at German power generators, procurement leads at Indonesian cement producers, and fuel supply specialists at Indian thermal stations underwrites the qualitative findings. Primary interviews with plant managers at torrefaction facilities, EPC contractors for densification equipment, and distribution channel partners in European residential heating markets combined with secondary validation from EIA biomass consumption data, IEA renewable energy reports, FERC filings for co-firing pilots, and Indian CEA utilization mandate disclosures. Bottom-up capacity assessments across France, Germany, Indonesia, and India triangulate against top-down demand projections from industrial thermal users.
Comparable-period anchoring to historical co-firing pilot data from RWE and Uniper installations established baseline substitution ratios for projection modeling across the analysis window. Segmentation dimensions modeled include fuel form tier, end-use thermal requirement, application combustion technology, and distribution channel logistics configuration. CAGRs derive from feedstock cost trajectory analysis and regulatory enforcement intensity assumptions. Industry-specific forecast inputs incorporate monsoon pattern impacts on Indian agricultural residue availability and EU carbon border adjustment implementation pacing.
The model assumes a particular technology adoption path; alternative pathways for torrefaction reactor deployment would alter the outlook if capital constraints delay capacity expansion beyond utility procurement timelines. Forecasts reflect assumptions regarding PLI scheme disbursement continuity and CEA mandate enforcement consistency. Specific risk factors that could revise projections include feedstock price spikes from competing fodder demand and slagging-related co-firing ratio limitations in high-alkali agro residue applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Fuel Oxygenate Market
Fuels
CNG Dispenser Market
Fuels
Anthracite Coal Mining Market
Fuels
Aviation Fuel Market
Fuels
Mobile Gas Pumping System Market
Fuels
LPG Tanker Market
Fuels
Coal Gasification Market
Fuels
LNG Filling Station Market
Fuels
Brazil Bunker Fuel Market
Fuels
Solid Recovered Fuel Market
Fuels
No.2 Diesel Fuel Market
Fuels
Europe Coal Market
Fuels
South America Bunker Fuel Market
Fuels
Hydrogen Cylinder Market
Fuels
Fuel Oil Market