
 GLP-1 Diet Food Market | 2026-2036
GLP-1 Diet Food Market Size, Share, and Industry Trends Forecast 2026-2036
GLP-1 Diet Food Market Insights
Meal planning and grocery spend is reconfiguring around pharmaceutical-adjacent nutrition as GLP-1 users seek structured eating protocols. Nestlé leverages its clinical nutrition heritage to develop portion-controlled formats that align with reduced gastric capacity. PepsiCo competes through shelf-stable convenience positioning in retail channels where prescription pickup and food shopping coincide. Danone anchors its strategy in fermented protein and gut-health crossover claims that resonate with metabolic-focused consumers.
GLP-1 diet food comprises formulated nutrition products designed to complement glucagon-like peptide-1 receptor agonist therapy, typically delivering 15-30 grams of protein per serving with controlled carbohydrate loads below 20 grams to mitigate postprandial glucose fluctuation. These products serve the commercial purpose of reducing muscle catabolism and micronutrient deficiency risks associated with suppressed appetite. Meal replacement formats occupy the deepest margin pools due to recurring subscription models and clinical positioning, while protein shakes represent the fastest-growing category as on-the-go consumption rises among busy professionals. Ready-to-eat meals remain comparatively mature, though diabetic patient applications show structural upside as physicians integrate nutrition counseling into prescription protocols.
The FDA exercises primary oversight through its Center for Food Safety and Applied Nutrition, with escalating scrutiny of structure-function claims linking diet foods to drug adjunct therapy. The USDA's Bioengineered Food Disclosure Standard and evolving FSMA traceability rules further constrain ingredient sourcing and label architecture for national distribution. Stakeholders must monitor whether regulatory bodies classify GLP-1 companion foods as a distinct category requiring pre-market notification, as this determination would reshape competitive barriers and capital requirements for new entrants.
Market Dynamics
Prescription volume trajectories for GLP-1 receptor agonists are restructuring food industry R&D priorities as pharmaceutical-adjacent nutrition becomes a definable commercial category with dedicated shelf space and formulation protocols.
Growth Catalysts
- US FDA Structure-Function Guidance:Evolving clarity on health claims linking diet foods to drug therapy adjunct use is enabling clearer marketing pathways for companion nutrition products.
- Reduced Gastric Capacity Physiology:The mechanical constraint of delayed gastric emptying from semaglutide and tirzepatide compounds is creating mandatory demand for nutrient-dense, portion-controlled formats.
- Protein Fortification Technology:Microencapsulation advances in dairy and plant protein isolates are resolving palatability barriers that previously limited compliance with high-protein, low-carbohydrate protocols.
Market Restraints
- Whey Protein Concentrate Volatility:Global dairy commodity price swings and New Zealand supply concentration are compressing gross margins for formulated meal replacements.
- Pre-Market Notification Uncertainty:Ambiguity around whether FDA will classify GLP-1 companion foods as a distinct regulatory category is freezing capital deployment for new facility construction.
- Whole-Food Substitution:Consumer preference for unprocessed protein sources and fresh meal preparation is constraining addressable market for shelf-stable formulated products.
Strategic Opportunities
- Subscription-First Distribution:Direct-to-patient models integrated with telehealth prescription platforms are capturing recurring revenue pools outside traditional retail margin structures.
- USDA Bioengineered Disclosure Alignment:Early compliance with evolving traceability rules is creating competitive separation for brands with verified non-GMO protein supply chains.
- Fermented Protein Convergence:Integration of precision fermentation-derived proteins with established gut-health positioning is opening white space in premium tier positioning.
Industry Challenges
- Clinical Nutrition Formulation Talent Scarcity:Shortage of food scientists with pharmaceutical manufacturing experience is extending product development timelines for therapeutic-grade nutrition.
- Co-Manufacturer Capacity Bottlenecks:Limited aseptic processing lines capable of low-acid, high-protein retort operations are constraining scale-up for ready-to-drink formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GLP-1 Diet Food Market |
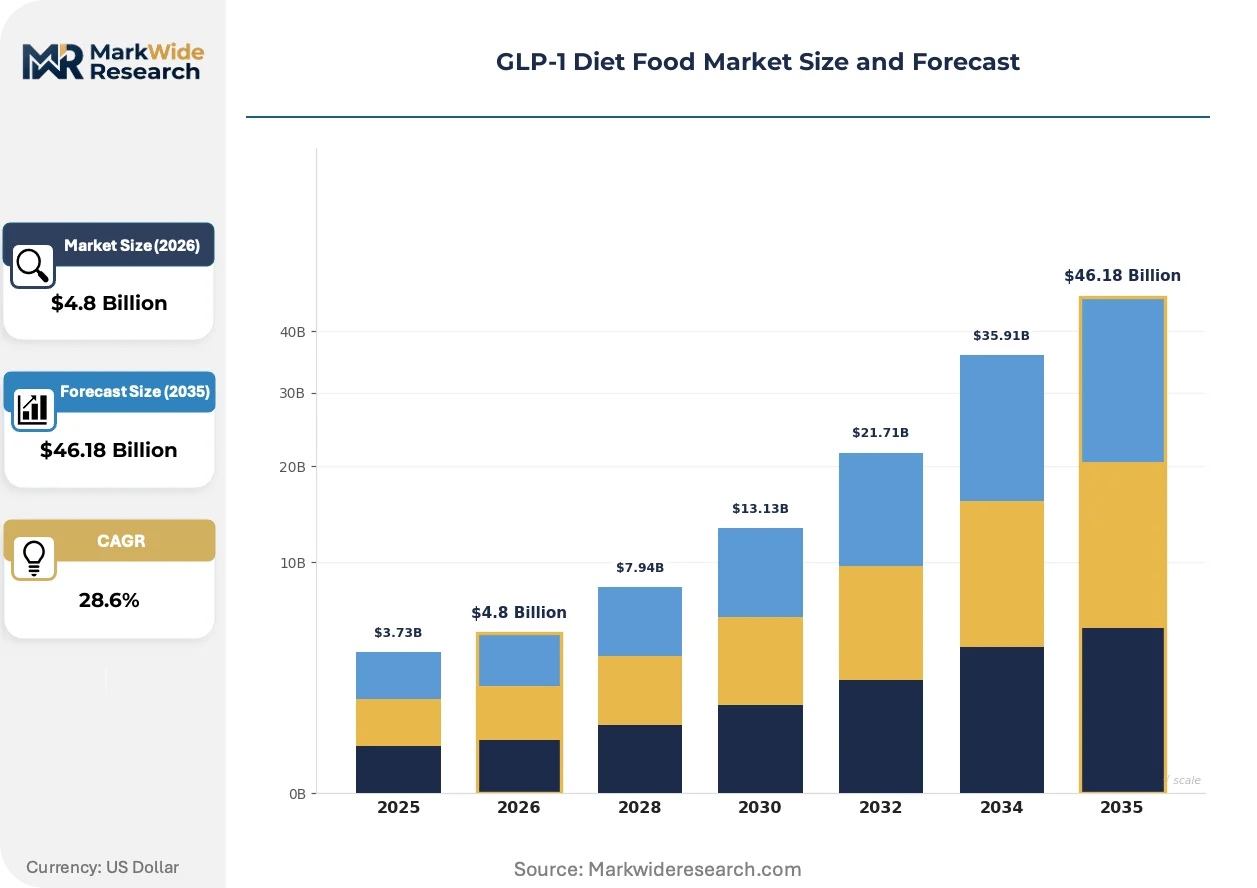
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacement, Nutritional Bars, Protein Shakes, Dietary Supplements, Ready-to-Eat Meals Formulation: Powder, Liquid, Capsule, Gummies, Tablets Application: Weight Management, Blood Glucose Control, Appetite Suppression, Metabolic Support, Energy Boost Customer Type: Fitness Enthusiasts, Diabetic Patients, Senior Citizens, Busy Professionals, Wellness Seekers |
| Companies Covered | Nestlé, Conagra Brands, PepsiCo, General Mills, Coca-Cola, Danone, Kellanova, Supergut, Vital Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GLP-1 Diet Food Market Trends and Innovations
Digital infrastructure is restructuring how GLP-1 diet food brands engage patients, with algorithm-driven personalization replacing one-size-fits-all nutrition protocols.
Precision fermentation of dairy proteins is virtualizing traditional livestock-dependent supply chains. Early-stage adopters in North American contract manufacturing are commissioning dedicated bioreactor capacity. This protein sourcing architecture is virtualizing conventional whey and casein procurement models that dominated sports nutrition for decades.
EU EFSA health claim substantiation requirements are tightening evidentiary standards for metabolic benefit positioning. Manufacturers must now generate human intervention studies rather than relying on compositional claims alone. The meal replacement segment is responding by funding clinical trials through European university research partnerships.
Hospital discharge protocols are embedding nutrition counseling into GLP-1 prescription workflows. Retail pharmacy chains are capturing this referral traffic through co-located dietitian services. The United States exhibits the most advanced integration, with CVS and Walgreens deploying registered dietitians at flagship locations in diabetes-prevalent states.
GLP-1 Diet Food Market Segmentation
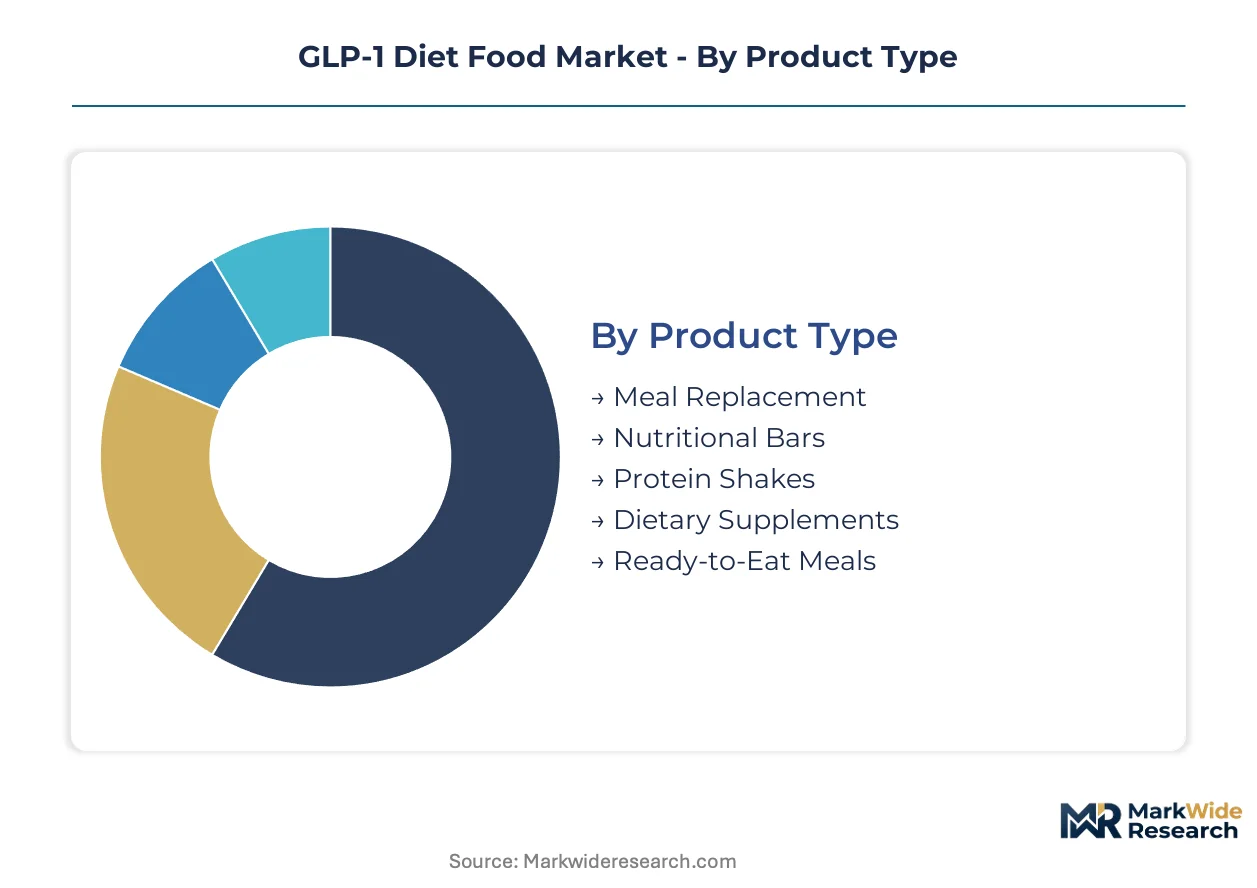
GLP-1 diet food segmentation reflects divergent consumption velocities across formats, with liquid and bar formats turning inventory faster than shelf-stable meals. Manufacturers calibrate production cadences to these cycle-time differentials while building formulation flexibility across protein sources and delivery systems.
Product Type:
Cycle times vary dramatically across formats, with ready-to-drink shakes replenishing weekly versus meal kits with monthly purchase intervals.
- Meal Replacement:Complete macronutrient profiles delivering 400-600 calories with 25-30 grams protein per serving, engineered for gastric volume constraints. Subscription models in the United States concentrate demand among insured GLP-1 users seeking structured protocols. Recurring revenue pools and clinical positioning sustain premium pricing.
- Protein Shakes:Shelf-stable liquid formats with 15-30 grams protein and sub-10 gram carbohydrate loads for postprandial glucose stability. On-the-go consumption among busy professionals in urban corridors drives velocity. Microencapsulation advances resolve prior palatability barriers.
- Nutritional Bars:Compressed nutrient delivery with extended ambient stability for travel and workplace consumption.
- Dietary Supplements:Micronutrient-dense formats addressing deficiency risks from suppressed appetite.
- Ready-to-Eat Meals:Retort-pouched or frozen complete meals with controlled portion architecture.
Meal replacement dominates installed base. Protein shakes are where expansion concentrates.
Formulation:
Cost tiers separate commodity powders from precision-dosed delivery systems with bioavailability enhancement.
- Powder:Bulk protein isolates requiring reconstitution, occupying economy positioning with lowest per-serving cost. Warehouse club channels in the United States move volume through multi-pound canisters. Price compression from whey commodity volatility constrains margin.
- Liquid:Pre-mixed ready-to-drink formats with aseptic processing requirements and higher per-unit production cost. Convenience premiums support standard-to-premium tier placement. Co-manufacturer capacity bottlenecks limit scale-up.
- Capsule:Encapsulated micronutrient and amino acid complexes for targeted supplementation.
- Gummies:Palatability-optimized delivery with gelatin or pectin matrices for compliance-sensitive users.
- Tablets:Compressed solid-dose formats for mineral and vitamin delivery with extended shelf stability.
Powder commands volume leadership. Liquid formats are climbing the fastest.
Application:
Customer journey stages determine margin architecture, with acute metabolic intervention commanding premium over maintenance protocols.
- Weight Management:Caloric deficit support with high satiety index formulations and fiber fortification. Physician-integrated counseling in United States diabetes-prevalent states drives prescription-adjacent demand. Hospital discharge protocols increasingly embed nutrition referral.
- Blood Glucose Control:Low-glycemic formulations with resistant starch and controlled carbohydrate release kinetics. Diabetic patient applications show structural upside as endocrinologists integrate food protocols with GLP-1 therapy. EFSA tightening evidentiary standards in Europe shapes claim substantiation investment.
- Appetite Suppression:Gastric volume-mimicking fiber matrices and protein preloading strategies.
- Metabolic Support:Broad-spectrum micronutrient repletion for altered absorption states.
- Energy Boost:Caffeine and adaptogen co-formulation for counteracting GLP-1-associated fatigue.
Weight management anchors revenue concentration. Blood glucose control is where clinical validation investment concentrates.
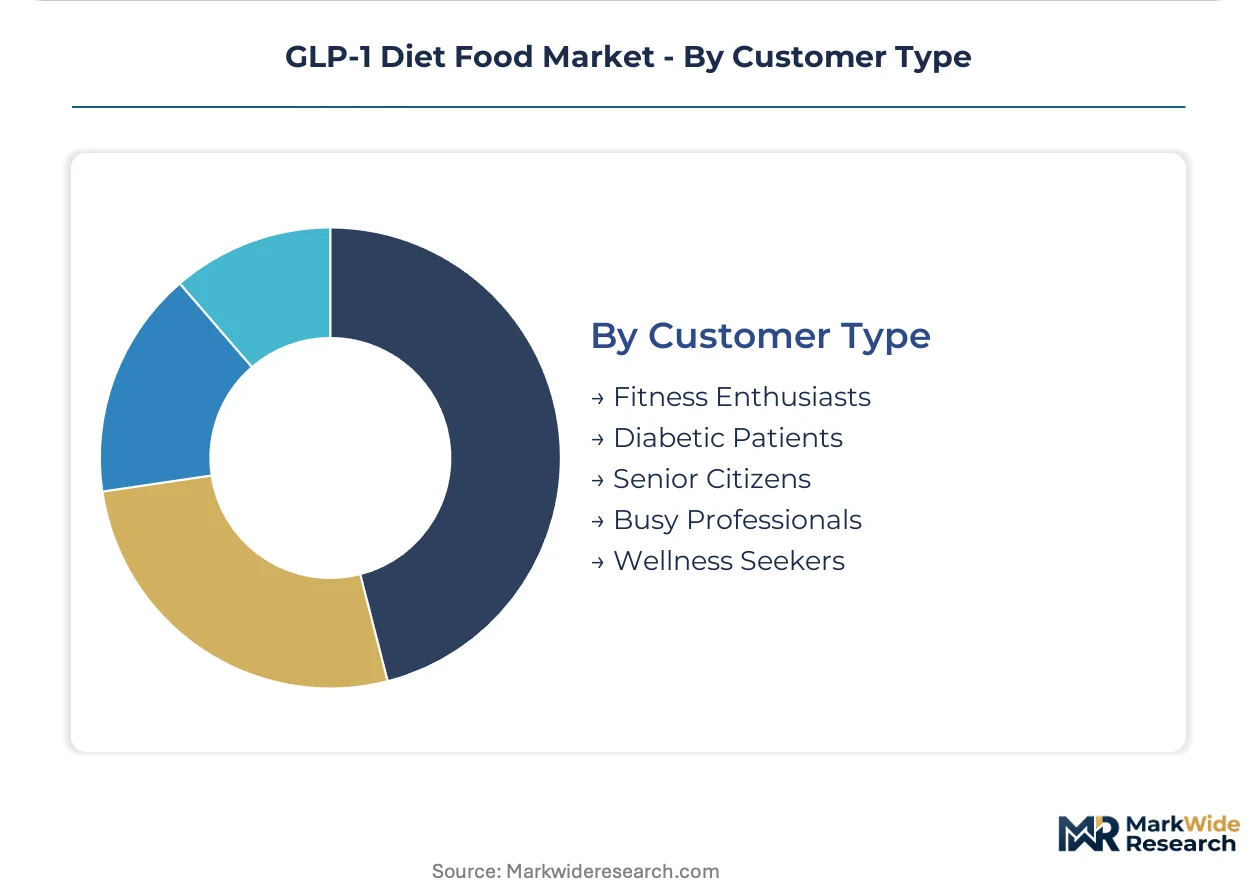
Customer Type:
Professional time scarcity versus clinical necessity creates divergent willingness-to-pay curves across user profiles.
- Busy Professionals:Time-constrained users prioritizing grab-and-go formats with minimal preparation friction. Urban pharmacy retail capture in the United States co-locates prescription pickup with nutrition purchase. Subscription-first models capture recurring revenue outside traditional retail.
- Diabetic Patients:Medically supervised users with insurance-adjacent purchasing and physician counseling integration. Retail pharmacy chains deploy registered dietitians at flagship locations. Clinical outcome accountability shapes brand selection.
- Fitness Enthusiasts:Performance-oriented users with existing protein supplementation habits.
- Senior Citizens:Sarcopenia-prevention focused with texture-modified format requirements.
- Wellness Seekers:Prevention-oriented consumers with clean-label and traceability priorities.
Diabetic patients dominate prescription-linked volume. Busy professionals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with United States users prioritizing pharmacy-retail convenience while European markets emphasize clinical substantiation and clean-label traceability.
United States
Insured populations on GLP-1 therapy drive the largest addressable consumer base for companion nutrition, with CVS and Walgreens deploying registered dietitians at flagship locations in diabetes-prevalent states. FDA structure-function guidance evolution is enabling clearer marketing pathways for drug-adjunct positioning. Greater Boston hosts precision fermentation startups commissioning dedicated bioreactor capacity for dairy protein virtualization.
Germany
Hospital discharge protocols increasingly embed nutrition counseling into GLP-1 prescription workflows, creating referral-driven demand for therapeutic-grade formulations. EFSA health claim substantiation requirements are tightening evidentiary standards for metabolic benefit positioning. Bavaria's contract manufacturing clusters are funding clinical trials through European university research partnerships to meet these standards.
United Kingdom
Retail pharmacy chains capture prescription-linked nutrition traffic through co-located dietitian services in urban corridors. The Medicines and Healthcare products Regulatory Agency maintains oversight coordination with food standards bodies on structure-function claims. London's health-tech infrastructure supports algorithm-driven personalization platforms replacing one-size-fits-all nutrition protocols.
France
Fermented protein convergence with gut-health positioning resonates strongly with metabolic-focused consumers in this market. ANSM maintains pharmaceutical-adjacent oversight coordination for products making therapeutic-adjunct claims. The Île-de-France region anchors Danone's precision fermentation R&D investments for next-generation dairy protein sourcing.
Japan
Senior citizens with sarcopenia-prevention needs create texture-modified format requirements distinct from Western markets. PMDA coordination with food safety regulators shapes the boundary between supplement and functional food categories. The Kanto region around Tokyo concentrates metabolic health product development for aging-population applications.
GLP-1 Diet Food Market Competitive Landscape
Capability concentration sits with clinical nutrition specialists; scale advantage sits with diversified food conglomerates with existing pharmacy-retail distribution infrastructure. The market structures around three tiers: pharmaceutical-grade formulators with therapeutic positioning, mass-market CPG players with convenience-oriented formats, and emerging precision fermentation specialists with novel protein architectures. Dominant competitive moves include strategic partnerships with telehealth prescription platforms and portfolio diversification into subscription-first direct-to-patient models.
Among diversified nutrition conglomerates, Nestlé and Danone exemplify contrasting strategic archetypes—one leveraging clinical nutrition heritage for portion-controlled therapeutic formats, the other anchoring in fermented protein and gut-health crossover claims. PepsiCo occupies a position on the convenience-vector, competing through shelf-stable positioning in retail channels where prescription pickup and food shopping coincide. These three represent the dominant competitive poles: clinical credibility, microbiome positioning, and retail-capture efficiency.
| Leading Market Players |
|---|
| Nestlé |
| Conagra Brands |
| PepsiCo |
| General Mills |
| Coca-Cola |
| Danone |
| Kellanova |
| Supergut |
| Vital Proteins |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in aseptic processing lines for high-protein retort operations is driving contract manufacturers toward selective customer prioritization and tiered pricing postures that favor volume-commitment buyers over spot purchasers.
Pricing Analysis
Long-term offtake agreements with retail pharmacy chains anchor pricing stability for meal replacement formats, while spot purchasing in powder segments faces compression from whey commodity volatility. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade formulations with FDA-aligned substantiation from mass-market convenience positioning. Pricing pressure stems from New Zealand dairy supply concentration and co-manufacturer capacity bottlenecks. Diabetic patients with insurance-adjacent purchasing show lowest price sensitivity; wellness seekers in warehouse club channels exhibit highest.
Supply Chain Analysis
Toll manufacturing concentration in United States, Germany, and France holds capacity for precision fermentation-derived proteins and aseptic liquid processing. Raw material dependencies center on whey protein isolates, plant protein concentrates, and microencapsulation lipids. Single-source vulnerability in New Zealand dairy procurement creates margin exposure. Distribution runs through pharmacy retail chains with co-located dietitian services capturing prescription-linked traffic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against whole-food substitution as fresh meal preparation and unprocessed protein sources capture compliance-minded GLP-1 users.
For Market Incumbents: Build regulatory moat through early FDA structure-function claim alignment and EFSA clinical trial investment. Secure captive supply of precision fermentation capacity in Greater Boston and Île-de-France clusters. Defend against precision fermentation specialists by accelerating therapeutic-grade formulation certification. For New Entrants and Emerging Players: Establish a beachhead in subscription-first direct-to-patient models integrated with telehealth prescription platforms. Target busy professionals in urban United States corridors with algorithm-driven personalization. Penetrate through fermented protein convergence with gut-health positioning in France and Germany. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clinical nutrition formulators with pharmacy-retail distribution integration. Long-term viability rests on regulatory navigation capability and protein sourcing architecture flexibility. Monitor FDA pre-market notification determinations as category-definition inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Virtualizes livestock-dependent whey supply chains through bioreactor commissioning in North America. |
| Telehealth Platform Integration | Captures recurring revenue pools outside traditional retail margin structures through prescription-adjacent distribution. |
| Clinical Trial Investment | Meets tightening EFSA evidentiary standards through European university research partnerships. |
| Registered Dietitian Deployment | CVS and Walgreens embed nutrition counseling into GLP-1 prescription workflows at flagship locations. |
| Clean-Label Supply Chain Verification | Early USDA Bioengineered Disclosure compliance creates competitive separation in traceability-sensitive segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA structure-function guidance documents, EFSA health claim substantiation records, and retail pharmacy chain procurement databases. Interviews with clinical nutrition formulators, registered dietitians at CVS and Walgreens, co-manufacturer operations directors, and telehealth platform executives informed demand-side and supply-side calibration. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporate prescription volume trajectories for GLP-1 receptor agonists, protein fortification technology adoption curves, and regulatory clarity evolution. Segmentation dimensions span product type, formulation, application, and customer journey stage. CAGRs derived from trend extrapolation with scenario-weighted probability adjustments. Precision fermentation capacity buildout and hospital discharge protocol integration served as industry-specific demand drivers.
Stress conditions across dairy commodity price volatility, FDA category classification ambiguity, and co-manufacturer capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on prescription penetration and insurance reimbursement stability. Quarterly review of FDA pre-market notification guidance and EFSA clinical trial acceptance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Nutritional Yeast Market