
 North America Insoluble Dietary Fibers Market | 2026-2036
North America Insoluble Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insoluble Dietary Fibers Market Analytics
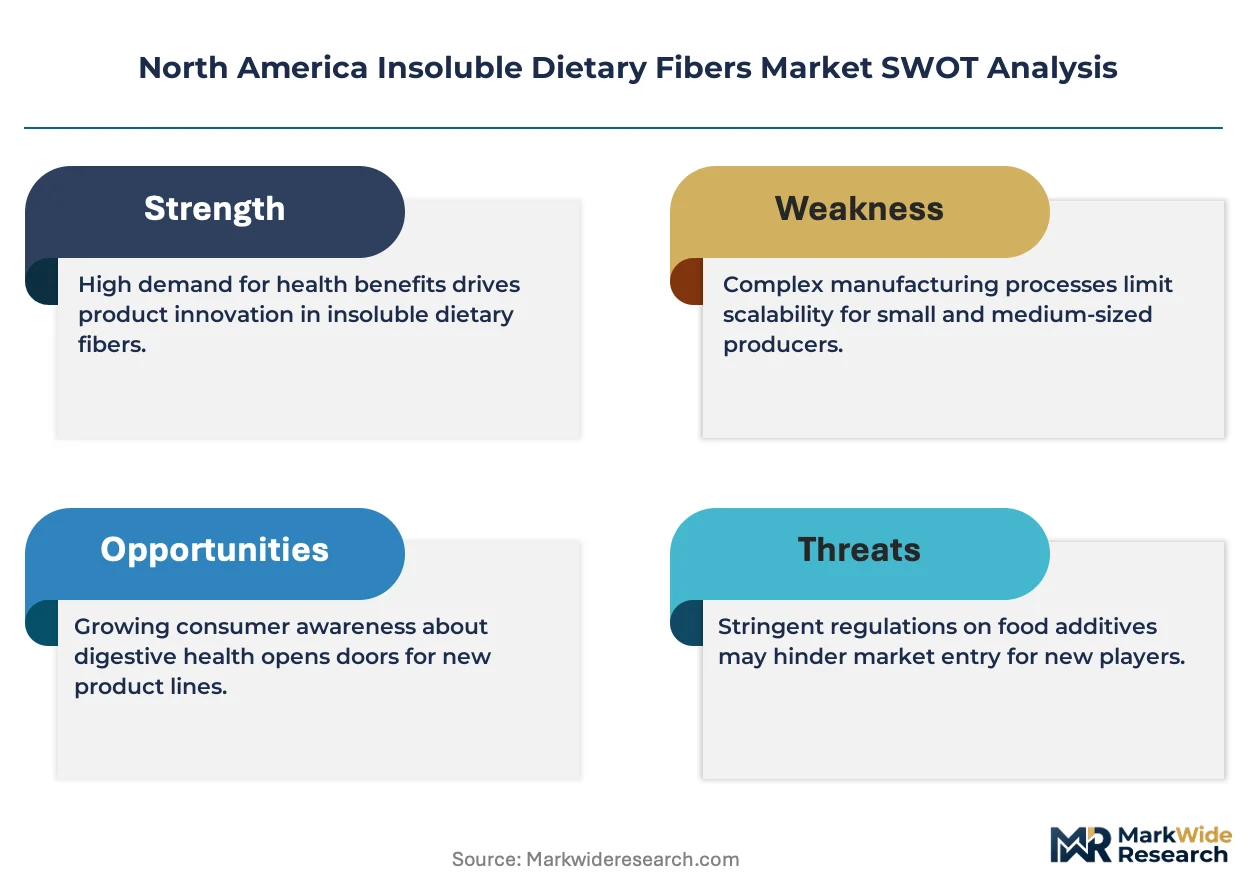
Food science talent scarcity is bifurcating the North America insoluble dietary fibers competitive landscape into scale-driven commodity suppliers and specialized technical innovators. Cargill, Incorporated leverages its integrated grain origination network to secure cost-advantaged corn fiber supply across the Upper Midwest. J. Rettenmaier & Söhne GmbH + Co KG specializes in cellulose-based texturizing systems for reduced-calorie bakery applications. Tate & Lyle competes through deep formulation partnerships with North American beverage developers seeking clean-label fiber enrichment.
Insoluble dietary fibers comprise non-digestible carbohydrate polymers—predominantly cellulose, hemicellulose, and lignin—that resist hydrolysis by human digestive enzymes and typically deliver water-holding capacities exceeding five grams per gram of fiber. These ingredients function primarily as bulking agents, moisture managers, and shelf-life extenders in processed foods while contributing to regulatory-compliant fiber content claims. Wheat fiber dominates volume flows into commercial baking operations where cost positioning and neutral flavor profiles matter most, while psyllium commands premium positioning in dietary supplement channels due to its cholesterol-management health claims. Cellulose grades are capturing accelerated placement in plant-based meat analogs where texture replication demands precise hydration control.
FDA nutrition labeling mandates and Health Canada fiber definition updates shape product formulation standards and permissible health claim language across the continent. USDA organic certification requirements and EPA biofuel coproduct regulations further influence fiber sourcing economics and availability of corn-based feedstocks. Stakeholders must monitor evolving FDA guidance on isolated versus intrinsic fiber physiological benefits, as this distinction threatens to recategorize certain cellulose grades and redirect R&D spending toward clinically validated alternatives.
Market Dynamics
Reformulation mandates from the FDA's updated nutrition labeling requirements are forcing food manufacturers to recalibrate fiber sourcing strategies and ingredient portfolios across North American production lines.
Growth Catalysts
- Clean-label bakery demand:Consumer preference for recognizable ingredients is accelerating wheat fiber adoption in commercial bread and snack applications across the United States.
- USDA organic certification pathways:Streamlined approval processes for organic fiber ingredients are expanding certified supply availability for premium product lines.
- Plant-based meat texture engineering:Cellulose fiber hydration control systems are enabling improved mouthfeel replication in alternative protein formulations.
Market Restraints
- Corn fiber feedstock volatility:EPA biofuel coproduct regulations create competing demand for corn stover and bran, squeezing fiber ingredient supply pools.
- Upper Midwest origination concentration:Cargill's integrated grain network and regional processor dominance limit price competition for bulk wheat fiber.
- Intrinsic versus isolated fiber classification uncertainty:Pending FDA guidance on physiological benefit distinctions threatens recategorization of certain cellulose grades.
Strategic Opportunities
- California functional food corridor expansion:Precision fermentation and cellular agriculture startups in the San Francisco Bay Area create novel fiber-texturizing partnerships.
- Health Canada fiber definition harmonization:Aligned regulatory standards across the US-Canada border simplify cross-border formulation and labeling compliance.
- Psyllium-cholesterol claim convergence:FDA-approved health claims for soluble fiber are spilling over into blended insoluble-soluble product development for supplement channels.
Industry Challenges
- Food science formulation expertise scarcity:Technical talent gaps in fiber-hydration system design are forcing manufacturers to outsource R&D to specialized consultancies.
- Dual certification timeline compression:Simultaneous USDA organic and non-GMO verification requirements extend product launch cycles by eight to fourteen months.
- Legacy extrusion equipment incompatibility:High-fiber dough rheology demands capital-intensive line modifications for mid-scale bakeries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insoluble Dietary Fibers Market |
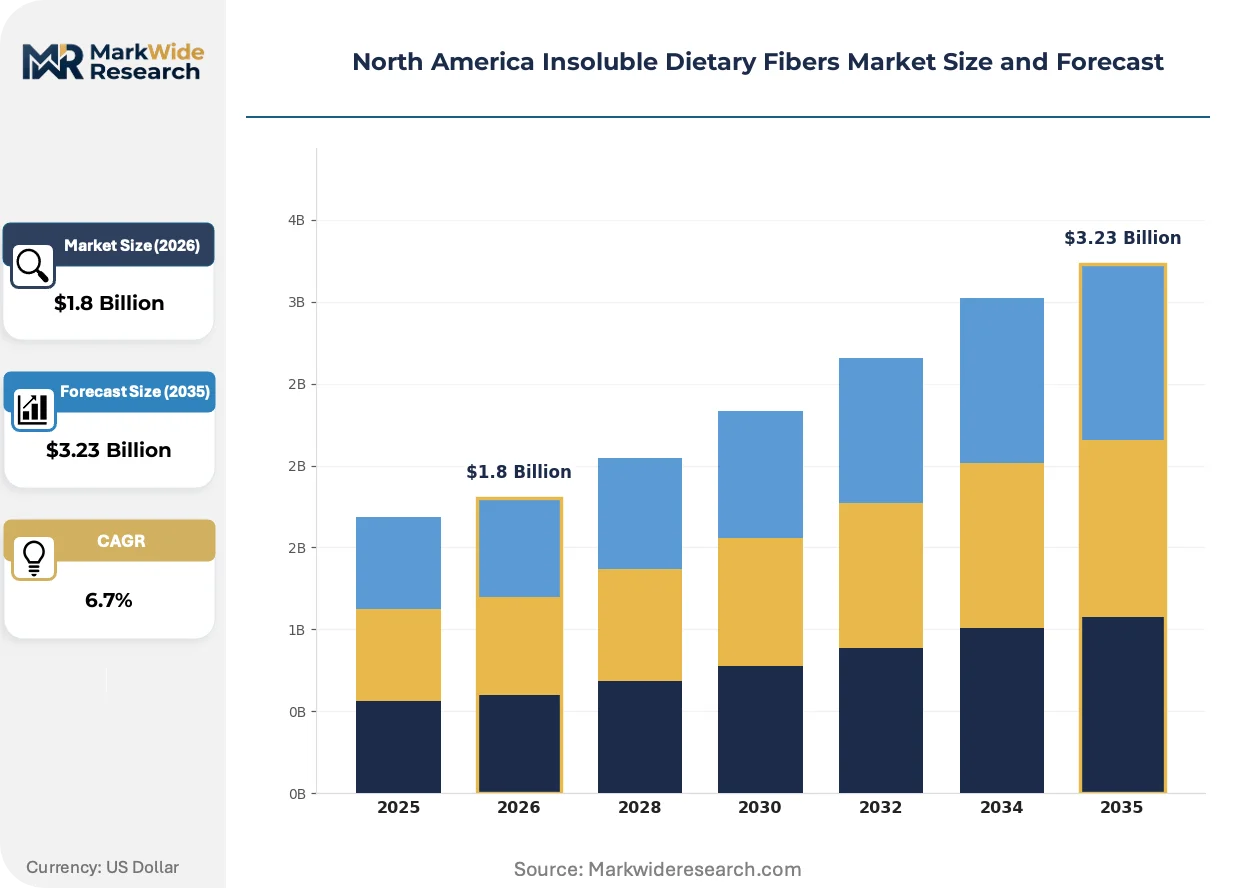
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Fiber, Cellulose, Psyllium, Corn Fiber Application: Baking, Snacks, Dairy Products, Beverages End User: Food Manufacturers, Dietary Supplements, Pharmaceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | Grain Processing Corporation, Cargill, Incorporated, Ingredion Inc., InterFiber, Archer Daniels Midland Company, DuPont, Roquette Frères, Tate & Lyle, J. Rettenmaier & Söhne GmbH + Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insoluble Dietary Fibers Market Evolving Landscape
Precision fermentation-derived fiber alternatives and advanced texturizing systems are reshaping how North American manufacturers achieve regulatory-compliant fiber content without compromising sensory performance.
Cellulose nanofibril production methods are displacing conventional mechanical grinding in premium bakery applications. Artisan and commercial bakers in the Northeast United States are adopting these grades for improved crumb structure and extended shelf life. This technology is displacing traditional wheat fiber in clean-label positioning where fiber source transparency commands price premiums.
Health Canada's updated fiber definition, implemented through guidance documents aligned with CODEX standards, is creating formulation clarity for cross-border product lines. The regulation eliminates previous ambiguity around resistant starch classification, forcing manufacturers to revalidate analytical methods. Dietary supplement producers in Ontario and British Columbia are most affected, accelerating third-party testing investments.
Beverage developers are unbundling fiber fortification from traditional dairy and juice applications into functional water and ready-to-drink formats. Direct-to-consumer subscription channels and specialty retailers are capturing volume that conventional grocery distribution previously monopolized. This pattern concentrates in Colorado and Pacific Northwest metropolitan markets where wellness-positioned consumption habits are most entrenched.
North America Insoluble Dietary Fibers Market Segmentation
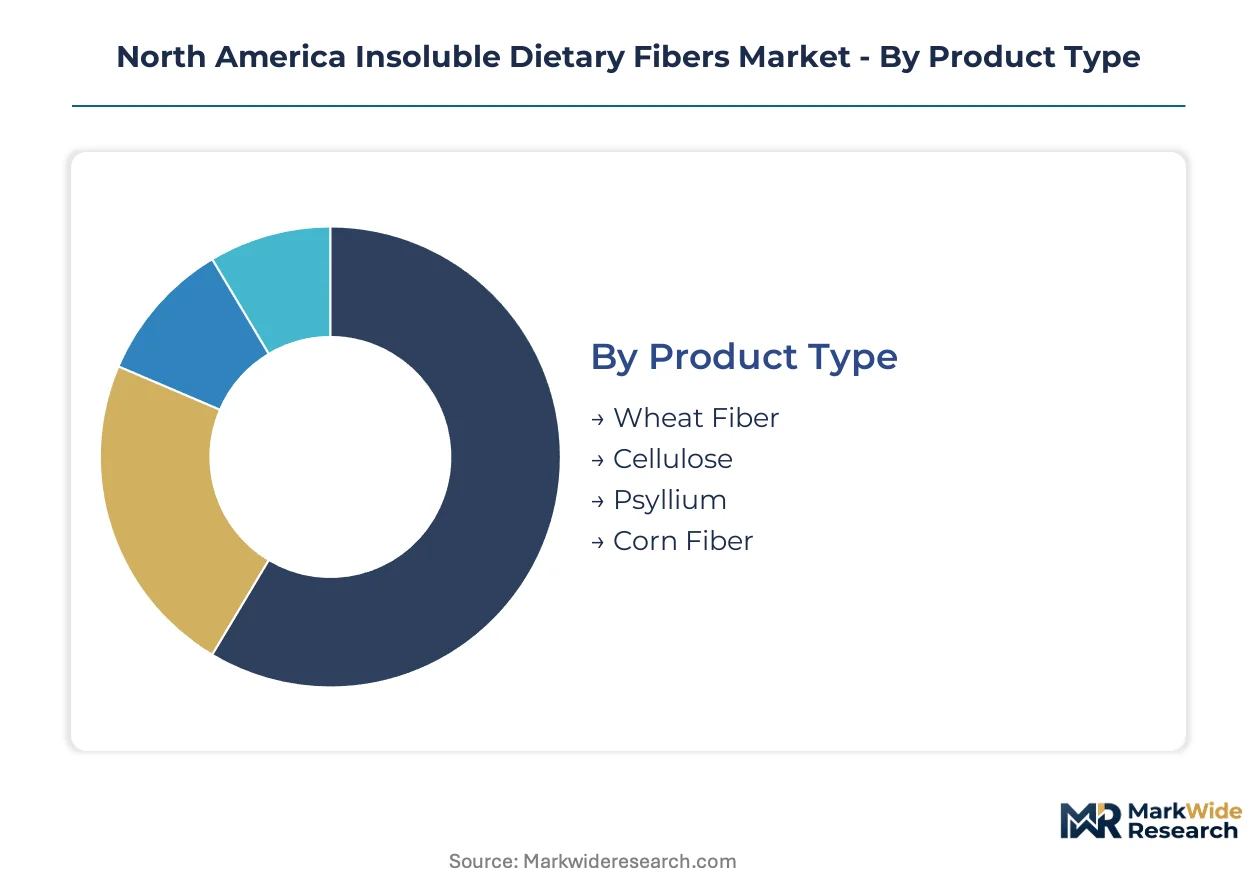
Segmentation reveals how fiber ingredient flows split across divergent technical requirements and commercial channels. Product specifications, application demands, and end-user compliance standards create distinct procurement patterns that suppliers must navigate simultaneously.
Product Type:
Channel-mix patterns vary sharply by fiber source, with commodity grades flowing through wholesale procurement while specialty grades concentrate in direct manufacturer relationships.
- Wheat Fiber:Milled from wheat bran with neutral flavor profiles and moisture-binding capacities of 4-6 grams water per gram fiber. Commercial bakeries in the Midwest grain-processing belt source this grade through long-term supply agreements with regional millers seeking cost-stable bulking solutions.
- Cellulose:Purified wood pulp or cotton linters processed to specific particle size distributions for hydration control. Plant-based meat formulators in California's functional food corridor specify microcrystalline grades for precise texture engineering in alternative protein matrices.
- Psyllium:Seed husk fiber with exceptional water retention exceeding 10:1 ratio, concentrated in supplement channels requiring FDA-compliant cholesterol health claims.
- Corn Fiber:Pericarp and endosperm fractions from wet milling operations, subject to EPA biofuel coproduct regulation volatility affecting feedstock availability.
By volume, wheat fiber leads. By growth pace, cellulose is climbing the fastest.
Application:
Cost tier stratification separates commodity baking applications from premium functional positioning in emerging beverage formats.
- Baking:Commercial bread and pastry operations incorporate insoluble fiber for dough conditioning, crumb structure improvement, and shelf-life extension without sensory compromise. Reformulation investments by FDA labeling deadline are accelerating wheat fiber placement across high-volume production lines.
- Snacks:Extruded and baked snack matrices utilize fiber for oil absorption control and structural integrity in reduced-fat formulations. Clean-label positioning in Northeast US artisan channels is displacing conventional texturizers with transparent fiber sources.
- Dairy Products:Yogurt and cheese applications leverage fiber for syneresis control and mouthfeel modification in reduced-fat formulations.
- Beverages:Functional water and ready-to-drink formats in Colorado and Pacific Northwest markets require ultra-fine particle grades for suspension stability.
By revenue concentration, baking dominates. By margin expansion, beverages show the steepest trajectory.
End User:
Customer type determines certification burden and technical service intensity, with pharmaceutical and supplement channels demanding validated physiological evidence.
- Food Manufacturers:Integrated procurement teams manage multi-fiber portfolios across reformulation mandates. FDA nutrition labeling compliance timelines are compressing supplier qualification cycles for these buyers.
- Dietary Supplements:Capsule and powder formulators require lot-to-lot consistency for health claim substantiation, particularly for psyllium cholesterol-management positioning.
- Pharmaceuticals:Excipient-grade cellulose for tablet disintegration and controlled-release matrices demands USP-NF certification and documented traceability.
- Animal Feed:Pet food and livestock nutrition applications utilize lower-specification fiber grades with reduced purity requirements.
By procurement volume, food manufacturers lead. By specification stringency, pharmaceuticals set the benchmark.
Distribution Channel:
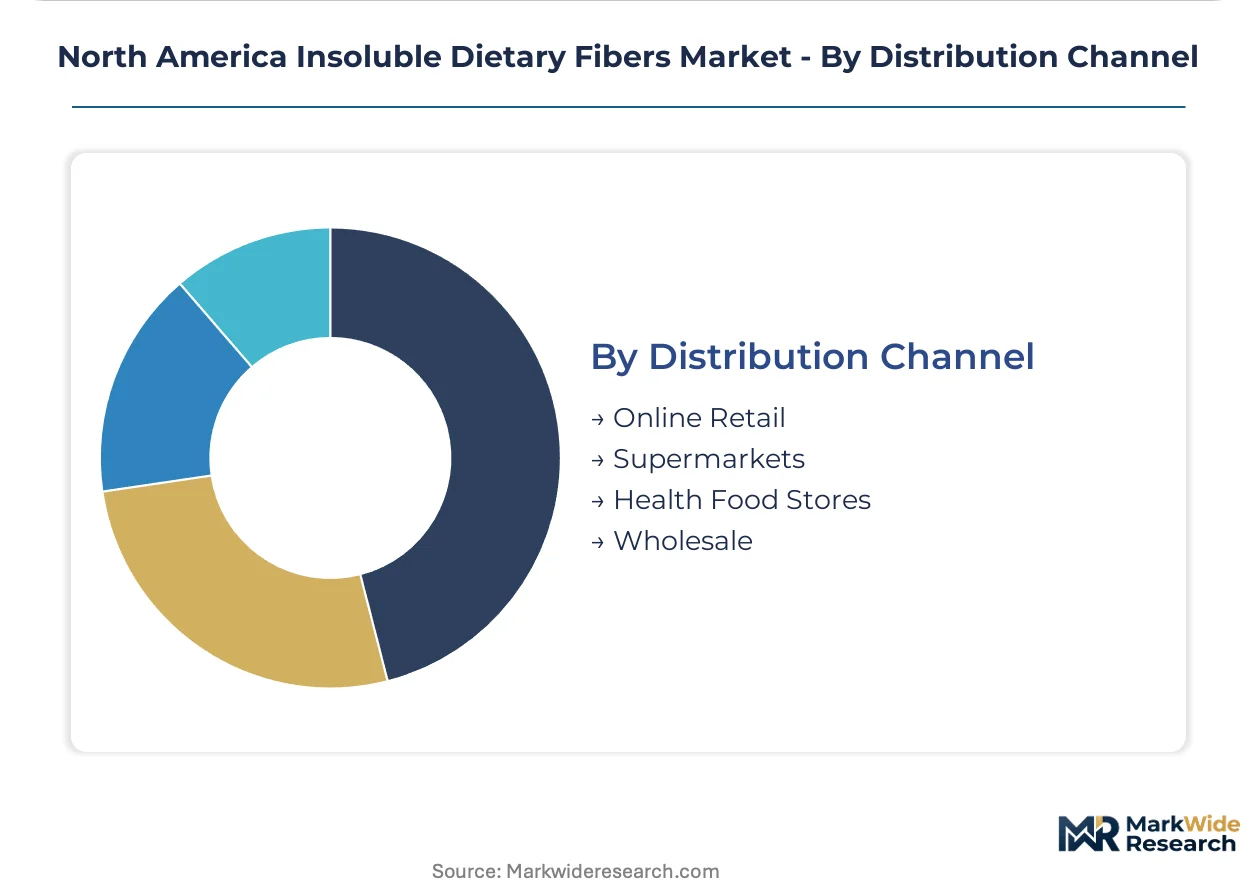
Volume scale and customer technical sophistication dictate channel selection, with wholesale dominating commodity flows and direct relationships capturing specialty grades.
- Online Retail:Direct-to-consumer fiber ingredient sales concentrate in small-batch supplement producers and artisan food startups bypassing traditional distribution. Subscription channel growth in wellness-positioned metropolitan markets is capturing volume from conventional grocery.
- Supermarkets:Private-label fiber-fortified finished goods placement drives indirect ingredient demand through contract manufacturer procurement.
- Health Food Stores:Premium organic and non-GMO certified fiber SKUs serve specialty formulators with extended certification timelines.
- Wholesale:Bulk wheat and corn fiber distribution through regional grain elevators and ingredient distributors serves high-volume baking operations.
By transaction volume, wholesale channels lead. By growth acceleration, online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling mandates anchor demand dynamics across the continent, with Health Canada fiber definition updates creating cross-border formulation complexity. Regional fiber ingredient flows concentrate in Midwest grain-processing infrastructure and California's functional food innovation corridor.
United States
Commercial bakeries in the Midwest grain-processing belt drive wheat fiber procurement through long-term supply agreements with regional millers. FDA updated nutrition labeling requirements for dietary fiber content are compelling reformulation investments across high-volume production lines. California's functional food corridor hosts precision fermentation startups seeking novel fiber-texturizing partnerships for plant-based applications.
Canada
Health Canada's updated fiber definition aligned with CODEX standards eliminates ambiguity around resistant starch classification. Dietary supplement producers in Ontario and British Columbia are accelerating third-party testing investments to revalidate analytical methods. The Prairie Provinces supply organic wheat fiber feedstocks through streamlined USDA organic certification pathways.
Mexico
Bakery and snack manufacturing expansion in the Bajío Region and Mexico City Metro is creating import demand for U.S.-origin wheat fiber grades. The country's national food safety regulator enforces labeling standards that increasingly reference North American harmonized fiber definitions. Corn fiber availability fluctuates with biofuel coproduct regulations affecting cross-border agricultural commodity flows.
North America Insoluble Dietary Fibers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure across the North America insoluble dietary fibers market. Scale-driven commodity suppliers leverage integrated grain origination networks to secure cost-advantaged feedstock positions. Specialized technical innovators command premium positioning through formulation expertise and clean-label certification capabilities. Dominant competitive moves include backward integration into captive grain supply and strategic partnerships with precision fermentation startups.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven supply chain control. Tate & Lyle occupies a position among formulation-focused specialists serving beverage developers. J. Rettenmaier & Söhne GmbH + Co KG represents the European technical innovator archetype with cellulose-based specialization.
| Leading Market Players |
|---|
| Grain Processing Corporation |
| Cargill, Incorporated |
| Ingredion Inc. |
| InterFiber |
| Archer Daniels Midland Company |
| DuPont |
| Roquette Frères |
| Tate & Lyle |
| J. Rettenmaier & Söhne GmbH + Co KG |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for wheat fiber in the Upper Midwest grain-processing belt concentrate pricing power with integrated origination networks while forcing smaller buyers into premium spot markets. This lead-time compression amplifies cost differentials between contract-based procurement and emergency sourcing when EPA biofuel regulations divert corn stover feedstocks.
Pricing Analysis
Midwest-to-California freight spreads of eight to twelve cents per pound separate commodity wheat fiber from cellulose grades commanding clean-label premiums. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with USDA organic verification adding fifteen to twenty percent at the top tier. Price erosion runs through standard-grade wheat fiber as Cargill's captive supply contracts lock in regional millers. Beverage developers show least price sensitivity due to formulation service bundling, while mid-scale bakeries face margin tightening from legacy equipment retrofit costs.
Supply Chain Analysis
Sixty-day lead times for microcrystalline cellulose from European suppliers expose California plant-based meat formulators to tariff volatility and currency fluctuation. Supply concentrates in the United States, Canada, and Germany, with raw material flows drawing from Upper Midwest corn wet milling, Prairie Provinces organic wheat, and Black Forest wood pulp operations. Single-source vulnerability sits with pharmaceutical-grade cellulose dependent on USP-NF certified facilities in Germany and the eastern United States. Distribution runs through regional grain elevators for bulk wheat fiber and direct manufacturer relationships for specialty texturizing grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's pending guidance on intrinsic versus isolated fiber classification creates a regulatory inflection that will recategorize ingredient portfolios and redirect R&D spending toward clinically validated alternatives. This disruption window favors players who pre-position validation data ahead of enforcement timelines.
For Market Incumbents: Secure backward integration into captive organic wheat supply in the Prairie Provinces before streamlined USDA certification pathways expire. Lock in multi-year formulation partnerships with California precision fermentation startups to preempt displacement by novel fiber alternatives. Cargill and ADM must defend against technical innovators by embedding fiber-hydration expertise directly into customer R&D labs. For New Entrants and Emerging Players: USDA organic certification fast-tracks for psyllium husk suppliers open immediate white-space in supplement channels where FDA cholesterol health claims command forty percent price premiums. Target Colorado and Pacific Northwest functional water developers with ultra-fine particle cellulose grades for suspension stability. Go-to-market through direct-to-consumer subscription channels bypasses entrenched wholesale distribution controlled by integrated agribusinesses. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming food ingredient divisions holding USP-NF certified cellulose assets. Five-to-ten year viability hinges on physiological benefit validation capabilities rather than commodity scale. Watch FDA guidance publication timelines as the inflection signal that will re-rate cellulose-heavy portfolios overnight.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feedstock | Captive Prairie Provinces wheat supply locks in cost advantage against spot-market volatility. |
| Precision Fermentation Partnership | California cellular agriculture startups create novel fiber-texturizing capabilities for plant-based applications. |
| USP-NF Certification Investment | Pharmaceutical-grade cellulose qualification opens excipient markets with documented traceability requirements. |
| Direct-to-Consumer Channel Launch | Subscription models in Colorado and Pacific Northwest bypass wholesale concentration controlled by ADM and Cargill. |
| Clinical Validation Program | FDA physiological benefit studies preempt recategorization risk for isolated fiber grades. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial bakery procurement directors, plant-based meat formulation scientists, dietary supplement quality assurance managers, and pharmaceutical excipient sourcing leads. Secondary validation drew from FDA guidance documents, Health Canada fiber definition updates, USDA organic certification databases, and EPA biofuel coproduct regulation filings. Bottom-up volume estimates from individual facility throughput were triangulated against top-down trade flow analysis across the North American border.
Across the analysis window, projections integrate product type segmentation by fiber source, application tier by processing complexity, and end-user channel by certification burden. CAGRs were derived from modeled adoption curves in reformulation-mandated baking operations and precision fermentation partnership formations. Forecast inputs include EPA renewable fuel standard rulemaking timelines and Health Canada CODEX alignment implementation progress.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of updated fiber definitions or abrupt biofuel policy shifts would require recalibration. Forecasts reflect documented assumptions about reformulation investment pacing and organic certification uptake rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Chromium Picolinate Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Global Beta-Alanine Market