
 Whey Hydrolysates Market | 2026-2036
Whey Hydrolysates Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Hydrolysates Market Analytics
The whey hydrolysates category is pivoting around a widening gap between premium bioactive peptide grades and commodity hydrolyzed whey streams used for cost-driven fortification. Arla Foods Ingredients leverages its European dairy cooperative structure to secure raw whey supply and sustain vertical control from milk collection to enzymatic hydrolysis. Glanbia PLC anchors its position through specialized sports nutrition channels, while Fonterra Co-operative Group dominates Oceania-origin whey hydrolysate exports with scale advantages in spray-drying infrastructure.
Whey hydrolysates are whey proteins subjected to controlled enzymatic hydrolysis that cleaves peptide bonds, reducing molecular weight to 1-10 kDa and yielding soluble fractions with faster gastric emptying and reduced allergenicity compared to intact whey. Manufacturers employ trypsin, chymotrypsin, or proprietary protease blends under monitored temperature and pH conditions to achieve specific degrees of hydrolysis measured by pH-stat or OPA methods. Sports nutrition applications lead volume absorption due to post-workout timing protocols, while clinical nutrition segments for malabsorption and dysphagia patients command premium positioning. Powder formats retain manufacturing economies of scale, though liquid ready-to-drink hydrolysates are gaining fastest in convenience-oriented channels.
FDA GRAS determinations and FSMA preventive controls govern U.S. import and domestic production standards for whey hydrolysate safety, while EFSA novel food and health claim assessments shape European market access for bioactive peptide positioning. China's SAMR and national food safety standards for whey-based products add compliance layers for imported hydrolysate ingredients. Stakeholders must monitor evolving peptide-specific health claim pathways and regional purity thresholds to align R&D investment with commercially viable positioning.
Market Dynamics
Enzymatic hydrolysis process optimization is compressing production costs for bioactive peptide fractions while FDA and EFSA tighten purity benchmarks, forcing manufacturers to choose between commodity fortification grades and premium clinical positioning.
Growth Catalysts
- EFSA Health Claim Frameworks:Evolving approval pathways for bioactive peptide positioning are enabling premium pricing in European clinical nutrition segments. Manufacturers invest in peptide-specific dossiers to secure functional food status.
- Sports Nutrition Channel Expansion:Post-workout timing protocols are driving absorption-focused formulations across United States and German athletic supplement markets. Specialty distributors prioritize hydrolysate portfolios with documented gastric emptying data.
- Enzymatic Process Intensification:Continuous hydrolysis systems with real-time degree-of-hydrolysis monitoring are reducing batch-to-batch variation. Food-grade protease suppliers advance immobilized enzyme technologies for cleaner label positioning.
Market Restraints
- Whey Protein Concentrate Price Volatility:Global dairy commodity swings transmit directly to hydrolysate input costs. Manufacturers lack hedging instruments for enzymatic processing margins.
- Oceania Supply Concentration:Fonterra's dominance in spray-dried whey exports creates bottleneck risk for Asia-Pacific hydrolysate processors. Alternative European and North American whey streams carry freight and tariff penalties.
- Bitterness Masking Limitations:Low-molecular-weight peptides below 3 kDa generate unpalatable hydrophobic residues. Flavor system costs erode margins in mass-market applications.
Strategic Opportunities
- Chinese Clinical Nutrition Reimbursement:SAMR's expanding coverage for medical foods in dysphagia and malabsorption protocols opens premium positioning. Domestic partners accelerate import registration timelines.
- Ready-to-Drink Liquid Formats:Aseptic processing investments enable shelf-stable hydrolysate beverages for convenience channels. Sports nutrition brands pilot on-the-go recovery formats in German and United States urban markets.
- Peptide Bioactivity Certification:Third-party verification of angiotensin-converting enzyme inhibitory or antioxidant activity supports functional claims. EFSA novel food consultations provide regulatory templates for dossier preparation.
Industry Challenges
- Enzymologist Talent Scarcity:Specialized protein chemists with hydrolysis kinetics expertise command premium compensation. Universities produce fewer graduates with combined food science and biochemistry training.
- GRAS Notification Timelines:FDA's peptide-specific safety evaluations extend 18-24 months for novel hydrolysate compositions. Smaller manufacturers lack resources for toxicology package preparation.
- Legacy Spray-Drying Integration:Retrofitting existing whey protein isolate plants for controlled hydrolysis requires capital-intensive temperature and pH control systems. Asset specificity limits operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Hydrolysates Market |
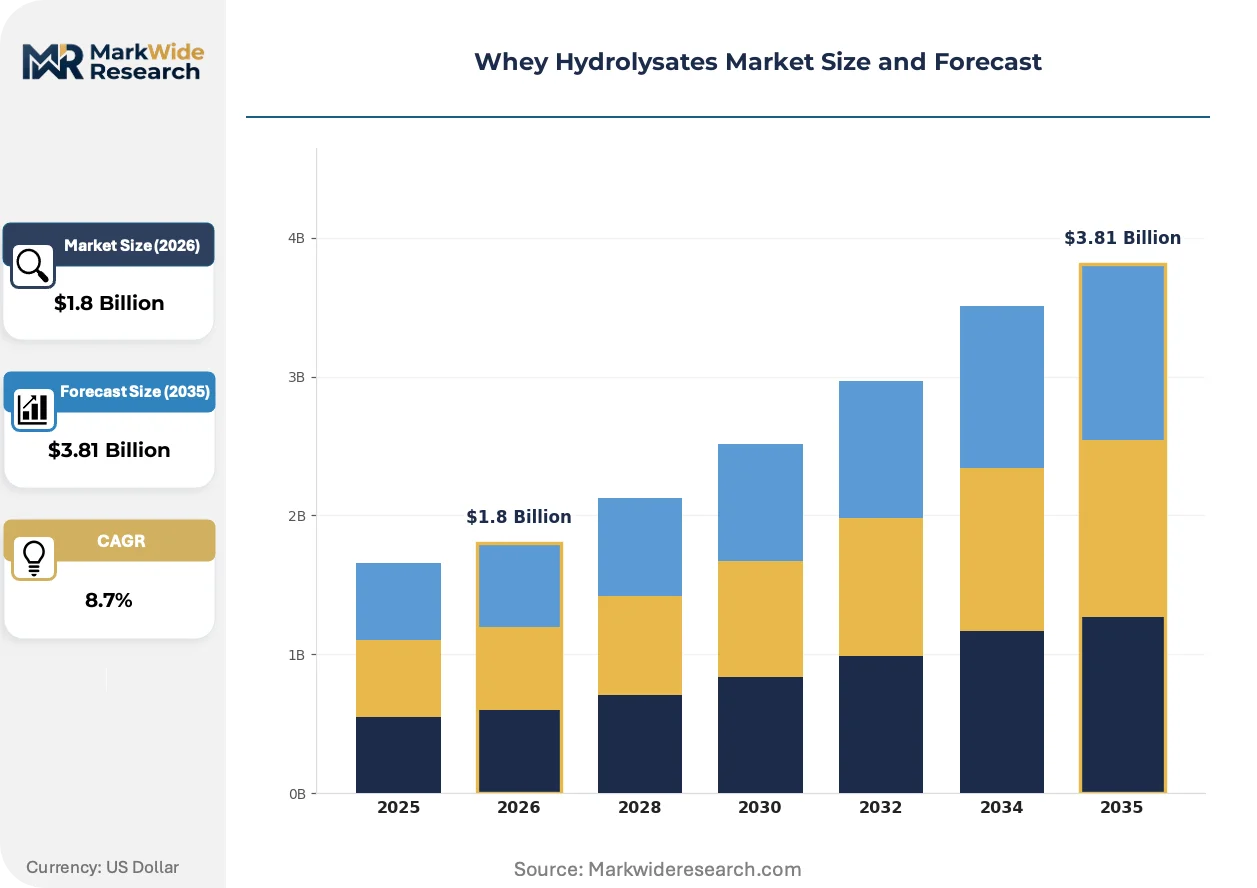
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Isolates, Hydrolysates, Blends End User: Sports Nutrition, Infant Nutrition, Clinical Nutrition, Functional Foods Form: Powder, Liquid, Tablets, Bars Distribution Channel: Online Retail, Supermarkets, Health Stores, Distributors |
| Companies Covered | Arla Foods Ingredients, Glanbia PLC, Hilmar Ingredients, Fonterra Co-operative Group, Kerry Group, FrieslandCampina Ingredients, Abbott, Nestlé Health Science, Agropur Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Hydrolysates Market Evolving Landscape
Membrane filtration technologies are advancing alongside precision fermentation, reshaping how manufacturers separate and standardize bioactive peptide fractions for targeted end-use applications.
Electrodialysis with bipolar membranes is converging with enzymatic hydrolysis to enable simultaneous desalting and peptide fractionation without thermal damage. Clinical nutrition formulators in Germany and the United States adopt these hybrid systems to achieve narrow molecular weight distributions for dysphagia patients. The technology is converging with continuous processing architectures, compressing capital requirements for mid-scale peptide purification.
EFSA's updated guidance on protein hydrolysate novel food assessments is extending safety data requirements for infant formula applications. Manufacturers must now submit comprehensive peptide mapping and allergenicity reduction documentation. European clinical nutrition brands are responding by segregating infant-grade hydrolysate production lines from sports nutrition streams to isolate compliance costs.
Direct-to-consumer subscription models are displacing traditional sports nutrition retail distribution in United States metropolitan markets. Specialty e-commerce platforms curate hydrolysate portfolios with batch-specific degree-of-hydrolysis certificates. This channel rotation is most visible in California and New York fitness ecosystems, where athletes prioritize transparency over shelf presence.
Whey Hydrolysates Market Segmentation
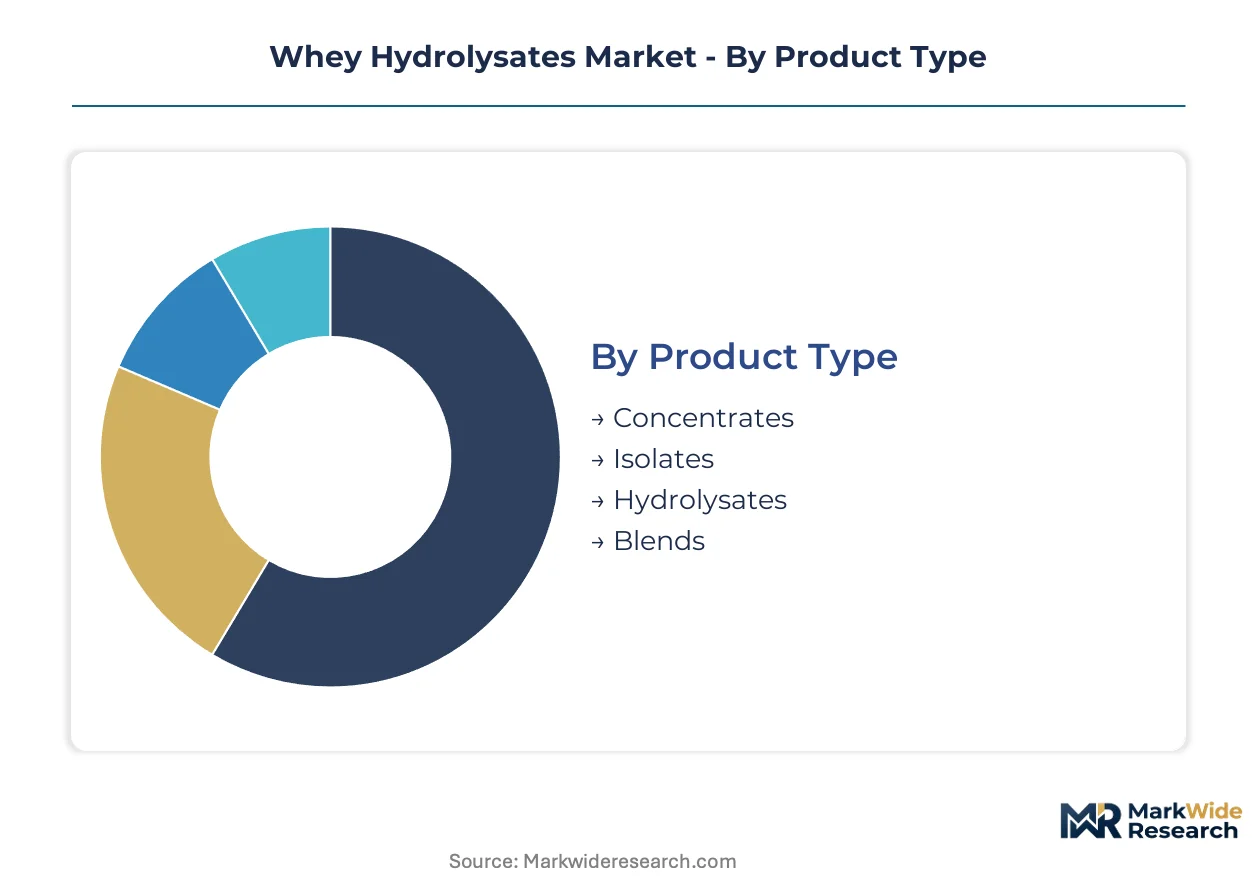
Whey hydrolysate segmentation reveals a market bifurcated between commodity-grade fortification streams and premium bioactive peptide fractions. Manufacturers calibrate enzymatic processing depth and molecular weight distribution to match distinct end-use specifications across nutrition categories.
Product Type:
Volume production concentrates in cost-optimized grades, while premium positioning clusters around specialized peptide profiles with documented bioactivity.
- Hydrolysates:Controlled enzymatic cleavage reduces molecular weight to 1-10 kDa, yielding rapid gastric emptying and reduced allergenicity. Sports nutrition brands in the United States and Germany prioritize documented degree-of-hydrolysis certificates for post-workout timing protocols. EFSA's tightening purity benchmarks for bioactive peptide content are forcing manufacturers toward clinical-grade positioning.
- Isolates:Higher protein concentration (90%+) with minimal lactose and fat serves cost-sensitive fortification applications. Functional food manufacturers in China blend isolates with hydrolysates to balance absorption speed against flavor system costs.
- Concentrates:Lower processing intensity preserves more native protein structure for economy-tier sports nutrition. Powdered concentrate streams dominate mass-market protein fortification in emerging markets where price elasticity remains acute.
- Blends:Strategic combinations of hydrolysate, isolate, and concentrate fractions optimize cost-performance ratios. German clinical nutrition formulators deploy staged-release blends for dysphagia patients requiring sustained amino acid availability.
Mature deployment sits with Isolates. Newer deployment is concentrated in Hydrolysates.
End User:
Application-driven segmentation separates timing-critical athletic consumption from therapeutic nutrition protocols with reimbursement dependencies.
- Sports Nutrition:Post-workout recovery windows drive demand for rapid-absorption formats. United States specialty distributors stock hydrolysate portfolios with gastric emptying validation data from third-party laboratories.
- Clinical Nutrition:Malabsorption and dysphagia protocols command premium pricing with peptide-specific dossier requirements. China's SAMR reimbursement expansion for medical foods accelerates import registration for European and Oceania-origin hydrolysates.
- Infant Nutrition:Hypoallergenic formula applications require extensive peptide mapping and allergenicity reduction documentation per EFSA novel food assessments. Manufacturers segregate production lines to isolate compliance costs from sports nutrition streams.
- Functional Foods:Beverage and bar fortification leverages hydrolysate solubility for clean-label positioning. German urban markets pilot ready-to-drink recovery formats with aseptic processing investments.
Established volume anchors Sports Nutrition. Steepest expansion trajectory appears in Clinical Nutrition.
Form:
Manufacturing economics favor powder formats, while convenience channels drive liquid innovation despite higher per-unit processing costs.
- Powder:Spray-dried hydrolysates retain scale economies and extended shelf stability. Bulk powder dominates B2B ingredient supply to sports nutrition contract manufacturers in the United States and Germany.
- Liquid:Ready-to-drink formats gain traction in convenience-oriented channels despite aseptic processing capital requirements. California and New York fitness ecosystems show strongest subscription model penetration for batch-certified liquid hydrolysates.
- Bars:Extruded protein bars incorporate hydrolysate fractions for texture modification and rapid amino acid delivery. Bitterness masking limitations constrain low-molecular-weight peptide inclusion below 3 kDa.
- Tablets:Compression formats serve clinical nutrition compliance protocols with precise dosing. Dysphagia patients in German reimbursement systems access tabletized hydrolysates through pharmacy distribution.
Scale concentration favors Powder. Format innovation clusters in Liquid.
Distribution Channel:
Channel segmentation reflects a structural shift from retail shelf presence toward transparency-focused direct relationships.
- Online Retail:Subscription models displace traditional sports nutrition retail in United States metropolitan markets. Specialty e-commerce platforms curate portfolios with batch-specific degree-of-hydrolysis certificates and third-party bioactivity verification.
- Distributors:B2B ingredient supply chains connect hydrolysate manufacturers to contract formulators. German clinical nutrition brands rely on specialized distributors with cold-chain capabilities for peptide stability.
- Health Stores:Staff-trained retail environments educate consumers on absorption speed differentials. United States specialty retailers prioritize hydrolysate SKUs with documented gastric emptying data over commodity protein positioning.
- Supermarkets:Mass-market placement requires flavor system investments to mask hydrophobic peptide bitterness. Economy-tier concentrates and blends dominate supermarket protein aisles in price-sensitive geographies.
Traditional strength resides with Distributors. Channel momentum is accelerating in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American whey hydrolysate demand through its sports nutrition contract manufacturing corridor, while enzymatic processing clusters concentrate near major dairy processing infrastructure across three continents.
United States
Post-workout recovery protocols drive hydrolysate absorption in California and New York fitness ecosystems. FDA GRAS notifications govern novel peptide compositions, extending safety evaluation timelines for smaller manufacturers. Chicago's contract manufacturing belt processes bulk hydrolysate powder for national sports nutrition brands.
Germany
Clinical nutrition reimbursement frameworks accelerate dysphagia and malabsorption protocol adoption. EFSA novel food assessments shape bioactive peptide positioning, requiring comprehensive peptide mapping documentation. Bavaria's dairy processing corridor hosts enzymatic hydrolysis facilities serving European medical food formulators.
China
SAMR's expanding medical food coverage opens premium clinical nutrition positioning for imported hydrolysates. National food safety standards for whey-based products add compliance layers for foreign ingredient suppliers. Yangtze River Delta pharmaceutical clusters pilot import registration partnerships with European hydrolysate manufacturers.
Australia
Oceania-origin whey exports supply Asia-Pacific hydrolysate processors with scale advantages in spray-drying infrastructure. TGA therapeutic goods frameworks influence regional quality benchmarks for clinical-grade peptide fractions. Victoria's dairy belt concentrates whey fractionation capacity serving export markets.
Netherlands
European dairy cooperative structures secure raw whey supply for vertical integration into enzymatic processing. REACH compliance requirements govern food-grade protease import and handling protocols. Randstad logistics hubs distribute hydrolysate ingredients to German and French formulators.
Whey Hydrolysates Market Competitive Landscape
Capital-heavy dairy cooperatives compete with asset-light ingredient specialists across the whey hydrolysate value chain. Market structure concentrates around three strategic tiers: backward-integrated dairy processors controlling milk-to-hydrolysate pipelines, specialized protein ingredient houses with enzymatic processing expertise, and finished goods brands outsourcing hydrolysate procurement. Dominant competitive moves include enzymatic process intensification investments and peptide-specific dossier preparation for EFSA health claim pathways.
Within the dairy cooperative tier, Arla Foods Ingredients and Fonterra Co-operative Group represent backward-integrated models securing captive whey supply from member farms. Glanbia PLC occupies a position among specialized protein houses with sports nutrition channel concentration. These three entities exemplify divergent strategic postures: European cooperative governance versus Oceania export scale versus Irish-listed ingredient specialization.
| Leading Market Players |
|---|
| Arla Foods Ingredients |
| Glanbia PLC |
| Hilmar Ingredients |
| Fonterra Co-operative Group |
| Kerry Group |
| FrieslandCampina Ingredients |
| Abbott |
| Nestlé Health Science |
| Agropur Ingredients |
| Others |
Value Network & Pricing Analysis
Clinical nutrition procurement officers in German reimbursement systems anchor pricing power for bioactive peptide grades, forcing manufacturers toward value-based contracts tied to documented patient outcomes rather than commodity whey protein benchmarks. This buyer concentration interacts with enzymatic processing cost structures to stratify the market between premium clinical positioning and cost-driven fortification streams.
Pricing Analysis
Outcome-based pricing for bioactive peptide fractions ties contract value to demonstrated gastric emptying acceleration and allergenicity reduction metrics. Three-tier pricing structure across premium clinical-grade, standard sports nutrition, and economy fortification levels differentiates by degree-of-hydrolysis certification and peptide mapping documentation. Cost compression in economy tiers intensifies because flavor system investments to mask hydrophobic bitterness erode already thin margins. Sports nutrition contract manufacturers exhibit highest price sensitivity due to private-label competition, while dysphagia protocol formulators accept premium positioning for reimbursement eligibility.
Supply Chain Analysis
EFSA novel food certification and FDA GRAS notification pathways gate market access for bioactive peptide positioning, creating qualification backlogs that constrain supplier expansion. Raw whey supply concentrates in New Zealand, Germany, and the Netherlands, with enzymatic processing capacity clustering near Bavarian dairy corridors and Victoria's spray-drying infrastructure. Food-grade protease inputs and specialized membrane filtration equipment draw from limited qualified vendor pools, creating single-source vulnerability for continuous hydrolysis system deployments. Distribution runs through specialized B2B ingredient distributors with cold-chain capabilities for peptide stability maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The whey hydrolysates market functions as a cost-of-compliance story where EFSA's expanding peptide-specific dossier requirements erect barrier-to-entry moats favoring incumbent manufacturers with dedicated regulatory affairs infrastructure and segregated production line investments.
For Market Incumbents: Extend peptide-specific certification portfolios to capture expanding Chinese clinical nutrition reimbursement coverage under SAMR frameworks. Deepen backward integration into captive whey supply through European dairy cooperative structures to offset commodity price volatility transmission. Prioritize enzymatic process intensification investments that compress batch-to-batch variation while maintaining clinical-grade purity benchmarks against emerging commodity hydrolysate suppliers. For New Entrants and Emerging Players: Ready-to-drink liquid format distributors in California and New York fitness ecosystems represent the most penetrable buyer archetype for subscription-based hydrolysate offerings with batch-specific transparency. Direct-to-consumer channels bypass entrenched B2B distributor relationships that incumbent dairy cooperatives dominate. Target peptide bioactivity verification partnerships with third-party laboratories as a credibility-building go-to-market angle for athlete-focused positioning. For Investors and Strategic Acquirers: The window for entry favors asset-light ingredient specialists with enzymatic processing expertise and existing EFSA dossier portfolios over greenfield dairy processing investments. Long-term viability hinges on clinical nutrition reimbursement expansion rather than sports nutrition commodity competition. Monitor SAMR medical food coverage decisions as the primary inflection indicator for premium positioning demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide-Specific Dossier Preparation | EFSA novel food consultations provide regulatory templates for functional claim positioning in European clinical nutrition. |
| Continuous Hydrolysis System Deployment | Real-time degree-of-hydrolysis monitoring reduces batch-to-batch variation for sports nutrition contract manufacturers. |
| Aseptic Processing Investment | Shelf-stable liquid hydrolysate formats unlock convenience channel penetration in German and United States urban markets. |
| Backward Integration into Whey Supply | European dairy cooperative structures secure raw material access against Oceania supply concentration risks. |
| Third-Party Bioactivity Certification |
Research Methodology
Independent corroboration across enzymatic processing technologists, clinical nutrition formulators, and sports nutrition brand procurement leads underwrites the qualitative findings in this study. Primary interviews with regulatory affairs specialists at dairy cooperatives and specialized protein ingredient houses combined with secondary validation from EFSA novel food assessment databases, FDA GRAS notification filings, and SAMR medical food registration records. Bottom-up volume modeling triangulates against top-down whey protein isolate trade flow analysis.
Rate-of-change decomposition across the analysis window separates volume drivers by product type tier, end-use application, and geographic regulatory cluster. Segmentation dimensions modeled include hydrolysate grade specification, clinical versus sports nutrition positioning, powder versus liquid format, and distribution channel structure. CAGRs derive from installed enzymatic processing capacity expansion schedules and reimbursement policy trajectory assumptions rather than extrapolated historical growth patterns.
Revisions become necessary when EFSA peptide-specific health claim pathways materialize with accelerated timelines, when SAMR medical food coverage expands beyond current dysphagia and malabsorption protocols, or when food-grade protease supply disruptions constrain continuous hydrolysis system deployment. A model refresh is warranted upon material change in clinical nutrition reimbursement eligibility criteria across German, Chinese, or United States healthcare systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Global Nutraceuticals Product Market