
 France Whey Protein Market | 2026-2036
France Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
France Whey Protein Market Foresight
Ingredient sourcing revenue is fragmenting between commodity whey traders and specialized fractionation houses. Fonterra Co-operative Group Limited leverages its New Zealand dairy network to secure raw material streams. Arla Foods amba sustains competitive pressure through integrated farm-to-ingredient control. Lactalis Ingredients anchors domestic supply with its extensive French dairy cooperative base.
France whey protein denotes the complete range of milk-derived protein fractions separated during cheese manufacturing, typically containing beta-lactoglobulin and alpha-lactalbumin in ratios varying by processing method, with protein concentrations spanning thirty-five to ninety percent depending on filtration intensity. Industrial applications center on muscle protein synthesis support, satiety modulation, and functional food texture enhancement. Whey protein isolate commands premium positioning due to higher purity and lower lactose content, while hydrolyzed whey protein attracts specialized medical nutrition formulations requiring rapid absorption kinetics. Sports nutrition applications dominate volume throughput, though functional foods represent the fastest-expanding margin pool as CPG brands integrate protein fortification into mainstream grocery channels.
ANSES sets maximum contaminant thresholds and nutritional claim verification protocols that manufacturers must satisfy before market release. EFSA health claim authorizations determine which physiological benefit statements appear on French whey protein packaging, directly constraining marketing strategy. DGCCRF enforcement actions against mislabeled sports supplements have intensified laboratory testing requirements across the supply chain. Stakeholders must monitor evolving EU novel food designations for emerging whey fraction derivatives and position compliance investments ahead of regulatory ratification timelines.
Market Dynamics
ANSES contaminant thresholds and EFSA health claim protocols are compressing formulation freedom while forcing manufacturers toward higher-purity processing investments. This regulatory tightening intersects with raw material sourcing fragmentation between commodity traders and specialized fractionation houses.
Growth Catalysts
- EFSA Protein Claim Authorization:Approved satiety and muscle maintenance statements enable sports nutrition brands to differentiate functional positioning on retail packaging.
- Medical Nutrition Absorption Requirements:Hydrolyzed whey protein fractions meet rapid-digestion specifications for clinical enteral feeding formulations.
- Île-de-France Fitness Density:Paris metropolitan gym penetration concentrates demand volume for ready-to-mix protein supplements.
Market Restraints
- Dairy Input Volatility:Farm-gate milk price fluctuations transmit directly to whey protein concentrate production economics.
- New Zealand Supply Concentration:Fonterra's dominance in global whey powder trade creates single-source dependency for French importers.
- Lactose Tolerance Ceiling:Whey protein concentrate formulations face substitution pressure from plant isolates among digestive-sensitive consumers.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Aging Demographics:Senior nutrition programs in southeastern France represent underdeveloped channels for medical-grade protein fortification.
- EU Green Deal Dairy Sustainability:Methane-reduction incentives favor cooperative processors with verified low-carbon whey streams.
- Direct-to-Consumer Subscription Models:Specialized sports nutrition brands bypass pharmacy and mass retail markup structures through automated replenishment platforms.
Industry Challenges
- Fractionation Technician Scarcity:Membrane filtration and chromatography operation requires specialized dairy engineering credentials that outpace vocational training output.
- DGCCRF Testing Backlogs:Laboratory verification queues for contaminant screening extend product release timelines by six to twelve weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Whey Protein Market |
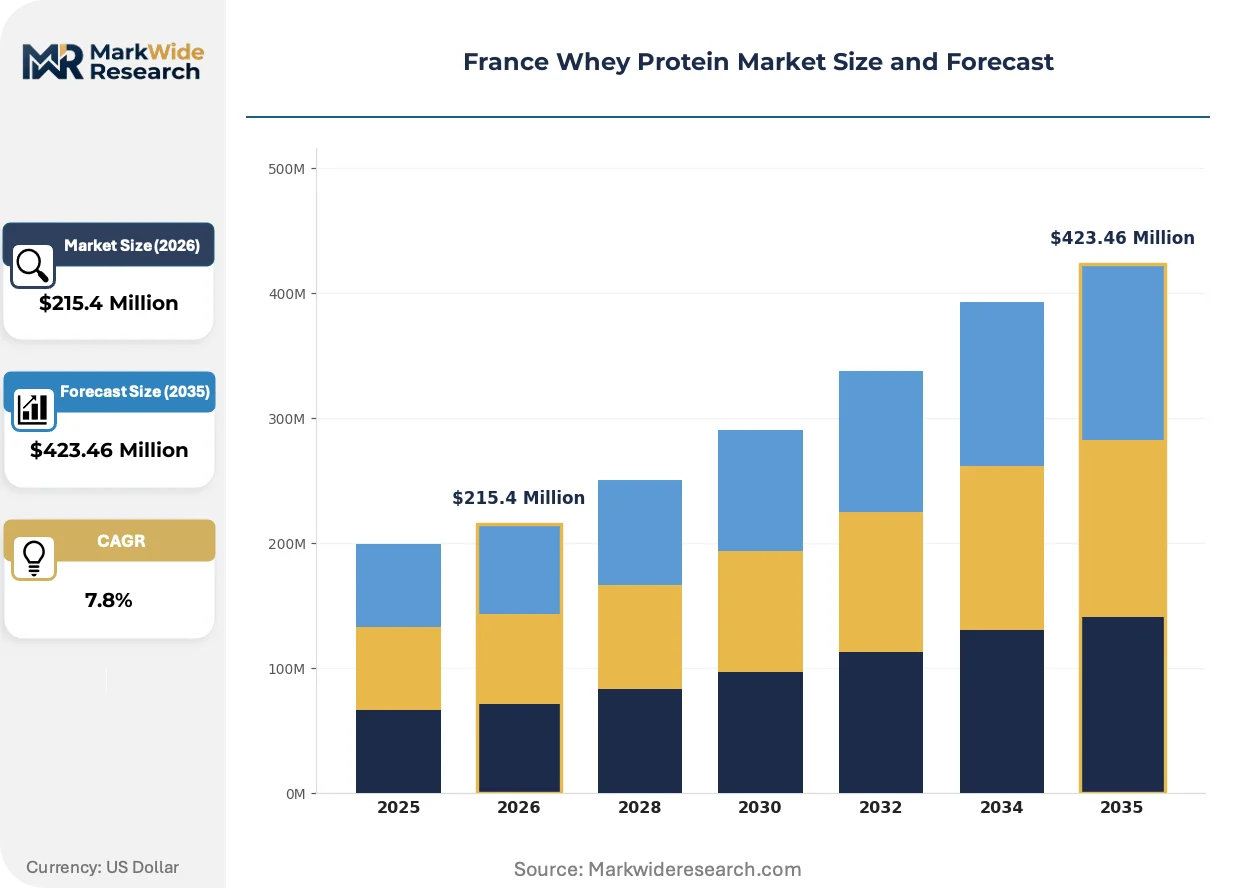
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $423.46 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Native Whey Protein, Whey Protein Blends Application: Sports Nutrition, Dietary Supplements, Functional Foods, Infant Nutrition, Weight Management End User: Athletes, Fitness Enthusiasts, Medical Nutrition, Elderly Population, Bodybuilders Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Pharmacies, Specialty Stores, Direct Sales |
| Companies Covered | Champignon-Hofmeister Group, Fonterra Co-operative Group Limited, Arla Foods amba, FrieslandCampina Ingredients, The Agropur Dairy Cooperative, Glanbia plc, Lactalis Ingredients, Eric Favre, Carbery Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Whey Protein Market Shifts & Advancements
Processing technology convergence and regulatory claim standardization are reconfiguring how whey protein manufacturers compete on purity, speed-to-market, and channel access. Three developments dominate current strategic positioning.
Cross-flow microfiltration and ceramic membrane systems are achieving ninety percent protein concentration without denaturation heat damage. Medical nutrition formulators in Lyon and Marseille are adopting these cold-processed isolates for immunocompromised patient applications. Thermal precipitation methods are rendering obsolete for premium-grade production lines.
ANSES tightened maximum residue limits for veterinary antibiotics and mycotoxins in dairy-derived supplements during 2024. Manufacturers must now submit batch-specific chromatography reports before market release. Sports nutrition brands with integrated farm auditing programs are capturing shelf space from importers lacking traceability documentation.
French consumers are prioritizing third-party Informed Sport and Informed Choice certifications over price comparison when selecting protein powders. Pharmacy chains and specialized nutrition retailers are displacing supermarket sports aisles as the primary purchase channel for repeat buyers. This certification-driven channel rotation is most pronounced in urban centers with CrossFit and boutique fitness studio density.
France Whey Protein Market Segmentation
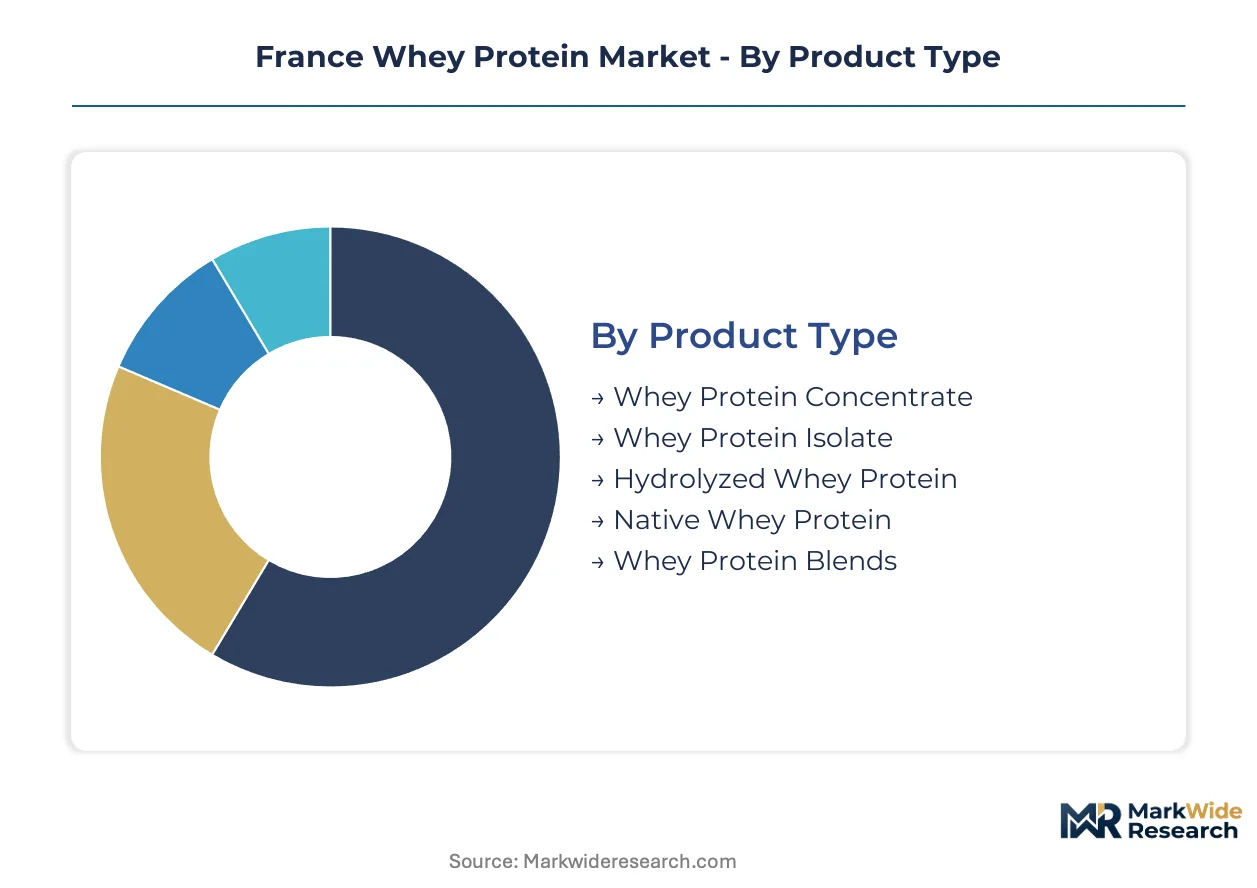
Segmentation in the France whey protein market reveals divergent margin structures across purity grades and channel strategies. Manufacturers align production investments with the distinct technical requirements and certification burdens of each product tier.
Product Type:
Inventory velocity varies sharply across purity grades, with commodity concentrates turning fastest and specialized isolates sitting longest on warehouse shelves.
- Whey Protein Concentrate:Contains thirty-five to eighty percent protein with retained lactose and fat fractions. Mass-market sports nutrition brands in Île-de-France source this grade for price-sensitive gym-goers, though ANSES contaminant testing adds two-week release delays.
- Whey Protein Isolate:Achieves ninety percent-plus protein through ion exchange or microfiltration. Premium positioning in Paris pharmacy chains commands higher shelf space fees, with Informed Sport certification becoming mandatory for repeat purchase retention.
- Hydrolyzed Whey Protein:Pre-digested peptides for rapid absorption kinetics. Medical nutrition formulators in Lyon specify this grade for enteral feeding protocols.
- Native Whey Protein:Cold-processed from fresh milk rather than cheese byproduct. Niche positioning among clean-label functional food startups.
- Whey Protein Blends:Custom ratios of concentrate, isolate, and casein. Private-label sports nutrition brands favor this flexibility for SKU proliferation.
Whey Protein Concentrate anchors the volume base while Whey Protein Isolate gains share at the steepest rate.
Application:
Formulation complexity and regulatory scrutiny scale inversely with consumer familiarity, creating distinct competitive moats around each use case.
- Sports Nutrition:Ready-to-mix powders and ready-to-drink formulations dominate tonnage. CrossFit box partnerships in Marseille and Bordeaux drive subscription retention for specialized brands.
- Dietary Supplements:Capsule and tablet formats with EFSA-approved health claims. ANSES verification protocols constrain marketing language to muscle maintenance and satiety statements only.
- Functional Foods:Protein-fortified yogurts, bars, and bakery applications. Major dairy cooperatives integrate whey fractions into mainstream grocery SKUs.
- Infant Nutrition:Demands alpha-lactalbumin-enriched fractions with batch-level contaminant documentation. Hospital procurement in Provence-Alpes-Côte d'Azur specifies domestic sourcing.
- Weight Management:Meal replacement formulations with specific viscosity and mouthfeel requirements. Pharmacy channel placement requires clinical study substantiation.
Sports Nutrition holds the installed demand base while Functional Foods climbs the fastest as CPG brands accelerate protein fortification timelines.
End User:
Purchase frequency and price elasticity separate recreational consumers from clinical prescribers and competitive athletes.
- Athletes:Competitive and semi-professional competitors with structured supplementation protocols. Anti-doping certification requirements filter supplier options severely.
- Fitness Enthusiasts:Recreational gym members with discretionary spending on premium flavors and mixability. Online subscription models capture this cohort most effectively.
- Medical Nutrition:Hospital and long-term care prescribers with reimbursement-dependent purchasing. Hydrolyzed isolates dominate this specification-driven segment.
- Elderly Population:Sarcopenia prevention programs in southeastern France represent underdeveloped channel potential for high-leucine formulations.
- Bodybuilders:High-volume consumers with brand loyalty to established sports nutrition labels. Contest preparation cycles create predictable seasonal demand spikes.
Fitness Enthusiasts provide the recurring revenue foundation while Medical Nutrition expands most quickly as clinical protein prescribing protocols standardize.
Distribution Channel:
Channel economics and customer acquisition costs fragment go-to-market strategies between mass retail and specialized access points.
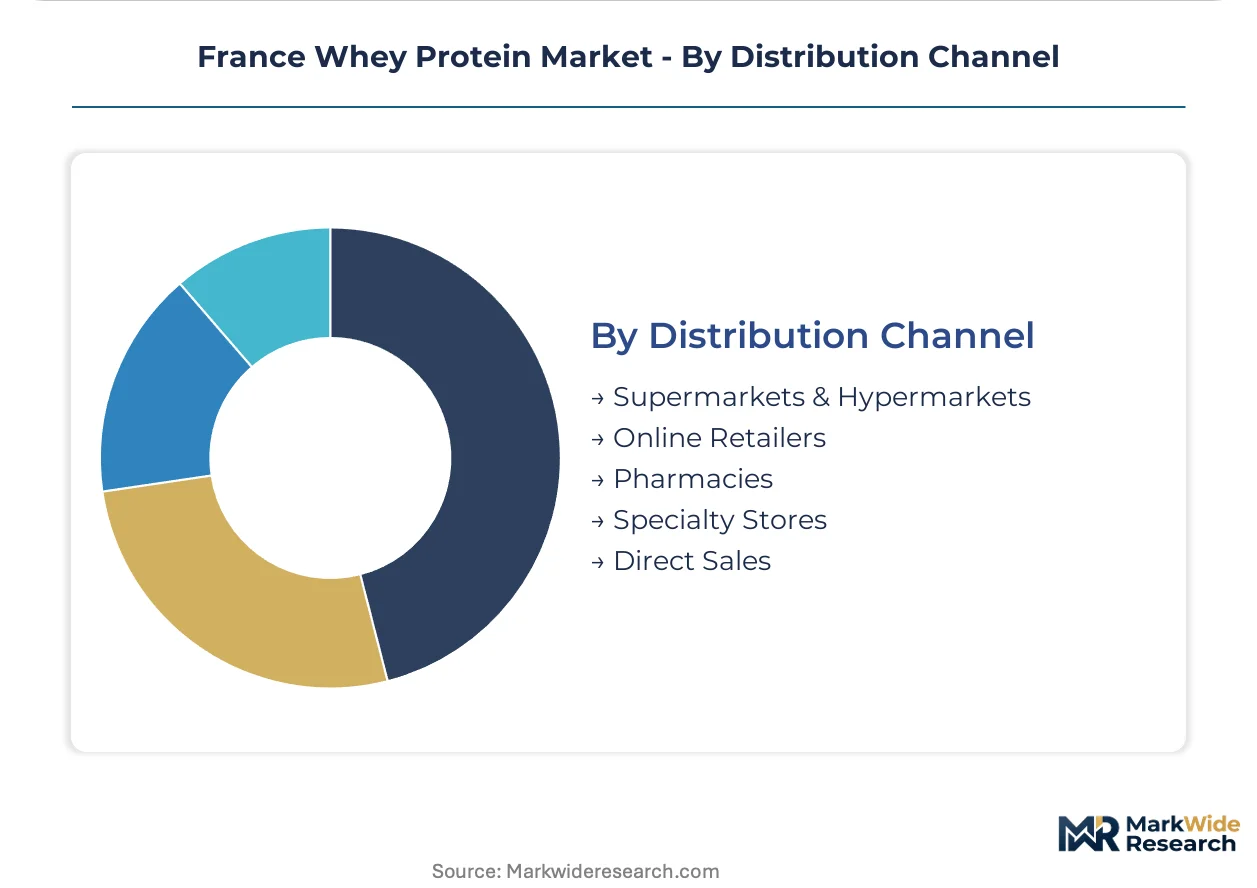
- Supermarkets & Hypermarkets:Mass-market concentrates and blended formats with high promotional intensity. Carrefour and E.Leclerc shelf placement requires trade marketing investment.
- Online Retailers:Direct-to-consumer brands bypass pharmacy markups through automated replenishment. Amazon.fr and specialized sports nutrition platforms compete on delivery speed.
- Pharmacies:Medical-grade isolates and infant nutrition with pharmacist consultation. Informed Choice certification drives repeat purchase in urban centers.
- Specialty Stores:CrossFit boxes, yoga studios, and running shops with curated brand selection. Staff recommendation carries higher conversion weight than price comparison.
- Direct Sales:Multi-level marketing and gym-based sampling programs. High customer acquisition cost limits scalability to niche demographics.
Supermarkets & Hypermarkets maintain the broadest reach while Online Retailers capture share most aggressively through subscription retention mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan France exhibits pronounced regional variation in whey protein consumption patterns, with fitness-oriented Île-de-France diverging sharply from medical-nutrition-focused southeastern regions. This geographic segmentation shapes distinct supply chain configurations and channel strategies across sub-national markets.
Île-de-France
Paris metropolitan gym density and CrossFit studio proliferation concentrate demand for ready-to-mix sports nutrition powders. ANSES headquarters in Maisons-Alfort drives national regulatory standard-setting that filters down to regional enforcement. Specialized nutrition retailers in central Paris command premium shelf space fees for Informed Sport-certified isolates.
Auvergne-Rhône-Alpes
Lyon's hospital procurement networks specify hydrolyzed whey protein for enteral feeding protocols in clinical nutrition programs. The EU Green Deal dairy sustainability incentives favor cooperative processors in the Alpine dairy belt with verified low-carbon whey streams. Medical-grade fractionation facilities in Grenoble supply precision isolates for immunocompromised patient applications.
Provence-Alpes-Côte d'Azur
Aging demographics in Nice and Marseille create underdeveloped channel potential for sarcopenia-prevention protein fortification programs. Regional health authorities pilot senior nutrition reimbursement schemes that could expand medical-grade whey prescribing. Specialized pharmacy chains along the Côte d'Azur curate premium isolate selections for affluent retiree populations.
Hauts-de-France
Dairy cooperative concentration in the northern milk belt anchors domestic whey protein concentrate production for mass-market sports nutrition brands. Lactalis Ingredients leverages its extensive French dairy cooperative base for farm-to-ingredient supply security. DGCCRF regional laboratories in Lille process contaminant screening queues that extend product release timelines.
Nouvelle-Aquitaine
Bordeaux functional food startups integrate native whey protein into clean-label bakery and yogurt applications for export-oriented gourmet positioning. The region's wine economy spillover creates demand for premium protein-fortified wellness products in tourist-facing retail. Local dairy processors experiment with cold-processed microfiltration for specialty foodservice channels.
France Whey Protein Market Competitive Landscape
Capability concentration sits with specialized fractionation houses mastering membrane filtration and chromatography; scale advantage sits with integrated dairy cooperatives controlling raw material throughput. The market structures around three archetypes: New Zealand-origin commodity traders, European cooperative processors with farm-to-ingredient control, and domestic French specialists serving medical nutrition formulators. Dominant competitive moves include backward integration into dairy cooperative ownership and certification-driven channel positioning through third-party quality verification.
Among the cooperative processor tier, Fonterra Co-operative Group Limited and Arla Foods amba exemplify scale-driven raw material security, while Lactalis Ingredients anchors domestic supply with its French dairy cooperative base. These three occupy positions spanning commodity concentrate volume and premium isolate certification, representing the spectrum from mass-market sports nutrition to pharmacy-grade medical applications.
| Leading Market Players |
|---|
| Champignon-Hofmeister Group |
| Fonterra Co-operative Group Limited |
| Arla Foods amba |
| FrieslandCampina Ingredients |
| The Agropur Dairy Cooperative |
| Glanbia plc |
| Lactalis Ingredients |
| Eric Favre |
| Carbery Group |
| Others |
Supply & Pricing Matrix
Hauts-de-France dairy cooperative concentration anchors domestic whey protein concentrate capacity, translating upstream milk supply security into pricing leverage against importers dependent on New Zealand spot markets. Lactalis Ingredients leverages this geographic clustering to stabilize farm-gate input costs while commodity traders absorb Fonterra's global price volatility.
Pricing Analysis
Long-term offtake contracts between French dairy cooperatives and mass-market sports nutrition brands dominate volume transactions, insulating domestic processors from spot-market swings. Three-tier pricing structure across premium isolate, standard concentrate, and economy blended grades differentiates by Informed Sport certification status and ANSES batch-verification documentation. Cost compression in commodity concentrate tiers intensifies as plant-protein substitutes erode price floors. Fitness enthusiasts in Île-de-France exhibit lowest price sensitivity, prioritizing third-party certification over per-kilogram cost comparison.
Supply Chain Analysis
Tariff exposure between New Zealand and the European Union concentrates risk for French importers sourcing Fonterra whey powder, forcing procurement diversification toward domestic cooperative supply. Raw material flows draw from New Zealand bulk trade, French Alpine dairy belt fractionation, and Dutch cooperative processing. Single-source vulnerability to Fonterra's global trade dominance threatens supply continuity for commodity-grade formulations. Distribution runs through pharmacy chains for medical-grade isolates, specialized sports nutrition retailers for certified premium tiers, and mass retail for economy concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France whey protein sits in early-cycle expansion as clinical protein prescribing protocols standardize and CPG brands accelerate mainstream grocery fortification timelines.
For Market Incumbents: Insulate market position through backward integration into dairy cooperative ownership and captive membrane filtration capacity in Grenoble or Lyon medical-grade facilities. Fonterra's New Zealand supply dominance and accelerating plant-protein substitution threaten commodity concentrate margins. Prioritize Informed Sport certification investment to defend pharmacy channel shelf space against emerging private-label entrants. For New Entrants and Emerging Players: Establish a beachhead in Provence-Alpes-Côte d'Azur senior nutrition programs, where sarcopenia-prevention reimbursement pilots create underpenetrated white space. Medical-grade hydrolyzed isolate specifications in Lyon hospital procurement networks offer second entry vector. Direct-to-consumer subscription platforms bypass incumbent retail markup structures most effectively for fitness enthusiast acquisition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized fractionation houses with ceramic membrane and cross-flow microfiltration capabilities over commodity concentrate traders. Long-term viability hinges on clinical nutrition application expansion and EU Green Deal methane-reduction credentialing. Watch DGCCRF testing backlog resolution as signal for regulatory compliance cost normalization and speed-to-market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Cooperatives | Lactalis Ingredients secures farm-gate supply security against Fonterra import volatility. |
| Ceramic Membrane Capacity Expansion | Grenoble fractionation facilities capture medical nutrition premium for immunocompromised applications. |
| Informed Sport Certification Program | Pharmacy chain placement in Paris requires third-party verification for repeat purchase retention. |
| Direct-to-Consumer Subscription Launch | Specialized brands bypass Carrefour and E.Leclerc trade marketing investment requirements. |
| EU Green Deal Sustainability Credentialing | Alpine cooperative processors leverage methane-reduction incentives for low-carbon whey streams. |
Research Methodology
A standing panel of membrane filtration engineers, dairy cooperative procurement directors, sports nutrition brand formulators, and ANSES regulatory affairs specialists provided ongoing calibration against operating reality. Primary interviews with Lyon hospital nutritionists and Marseille CrossFit box owners combined with secondary validation from ANSES contaminant threshold publications, EFSA health claim authorization databases, and French dairy trade association production statistics. Bottom-up SKU-level volume builds triangulated against top-down cooperative processor capacity assessments.
Scenario-bracketing around regulatory ratification timelines and plant-protein substitution rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled include purity grade tier, application use case, end-user archetype, and regional distribution channel. CAGRs derived from historical cooperative production trends and hospital procurement volume trajectories. Industry-specific inputs incorporated DGCCRF testing queue durations and Informed Sport certification adoption curves.
Sensitivities concentrate around ANSES residue limit revisions, Fonterra supply disruption events, and senior nutrition reimbursement scheme expansion pace. Forecasts reflect documented assumptions on membrane filtration capacity additions and clinical prescribing protocol standardization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Global Soluble Dietary Fibers Market